
 Bovine Gelatin Market | 2026-2036
Bovine Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
Bovine Gelatin Market Analysis
Asset-light toll manufacturing and third-party collagen tolling arrangements are narrowing the capital barrier for mid-scale entrants in bovine gelatin production. Darling Ingredients leverages its integrated rendering-to-gelatin pipeline across North American cattle processing regions to sustain cost advantages in raw material sourcing. Gelita AG anchors European pharmaceutical-grade supply through controlled alkali extraction protocols that meet EP and USP monograph standards. Rousselot competes in Asian nutraceutical markets through specialized hydrolyzed bovine collagen peptides positioned for joint health formulations.
Bovine gelatin is a proteinaceous hydrocolloid derived from partial hydrolysis of collagen extracted from bovine skin, bones, and connective tissues, with typical bloom strengths ranging from 50 to 300 g and isoelectric points between 4.7 and 5.4 depending on extraction method. The material functions primarily as a gelling agent, stabilizer, and film-former across food, pharmaceutical, and photographic industries, with type B gelatin processed through alkaline pretreatment dominating commercial output for its broader pH tolerance. Powder formulations occupy the largest volume share in food and beverage applications where dispersibility and hydration kinetics determine processing economics, while pharmaceutical capsules and film coatings drive premium positioning for sheet and film grades with defined viscosity profiles. Nutraceutical applications represent the fastest-expanding demand pool as hydrolyzed bovine collagen peptides gain traction in joint health and skin elasticity supplements, with liquid concentrates emerging in functional beverage formulations despite shorter shelf-life constraints.
FDA food additive regulations under 21 CFR 172.5 and EFSA safety evaluations for bovine-derived materials govern market access for gelatin in pharmaceutical and food applications, with BSE/TSE compliance documentation now mandatory for cross-border shipments into both jurisdictions. India's FSSAI has tightened bovine gelatin labeling requirements for vegetarian-sensitive consumer segments, while China's SAMR enforces GB standards for imported collagen raw materials that include species verification and geographic origin traceability. Stakeholders must monitor evolving regulatory divergence between pharmaceutical-grade monograph standards and food-grade specification flexibility, as this gap determines where margin pools consolidate and which extraction technologies warrant capital commitment.
Market Dynamics
Clean-label formulation mandates from major food retailers are compressing synthetic additive demand while pulling bovine gelatin into expanded confectionery and functional dairy applications, restructuring procurement patterns across European and North American supply chains.
Growth Catalysts
- EU REACH Chemical Safety Framework:Updated traceability requirements for collagen suppliers are filtering out non-compliant processors and consolidating volume with certified extraction facilities.
- Hydrolyzed Collagen Peptides:Nutraceutical manufacturers are expanding bovine-derived peptide use in joint health and skin elasticity supplements, opening premium positioning beyond traditional food applications.
- India PLI Scheme Incentives:Domestic food processing infrastructure investments are accelerating localized bovine gelatin consumption and reducing import dependency.
Market Restraints
- Cattle Byproduct Supply Volatility:Rendering output fluctuations in Brazil and Argentina create raw material cost instability for non-integrated gelatin producers.
- Plant-Based Hydrocolloid Substitution:Pectin and carrageenan formulations are capturing clean-label confectionery share where vegetarian positioning outweighs functional performance.
- BSE/TSE Documentation Burden:Cross-border shipment compliance costs for FDA and EFSA jurisdictions disproportionately impact small-scale regional suppliers.
Strategic Opportunities
- Pharmaceutical-Grade Capsule Films:EP and USP monograph-compliant alkali extraction capacity remains underdeveloped in Southeast Asia, creating white space for certified entrants.
- Functional Beverage Liquid Concentrates:Shelf-life stabilized hydrolyzed collagen formats are penetrating sports nutrition channels where powder dispersion limits processing efficiency.
- India BIS Certification Standards:Tightened domestic labeling requirements for vegetarian-sensitive segments favor transparent supply chain operators with species verification systems.
Industry Challenges
- Alkali Extraction Technician Scarcity:Pharmaceutical-grade gelatin production requires specialized process control expertise that outpaces vocational training pipeline output in emerging production regions.
- Multi-Jurisdiction Certification Timelines:Simultaneous EP, USP, and FSSAI compliance audits extend product launch cycles by twelve to eighteen months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bovine Gelatin Market |
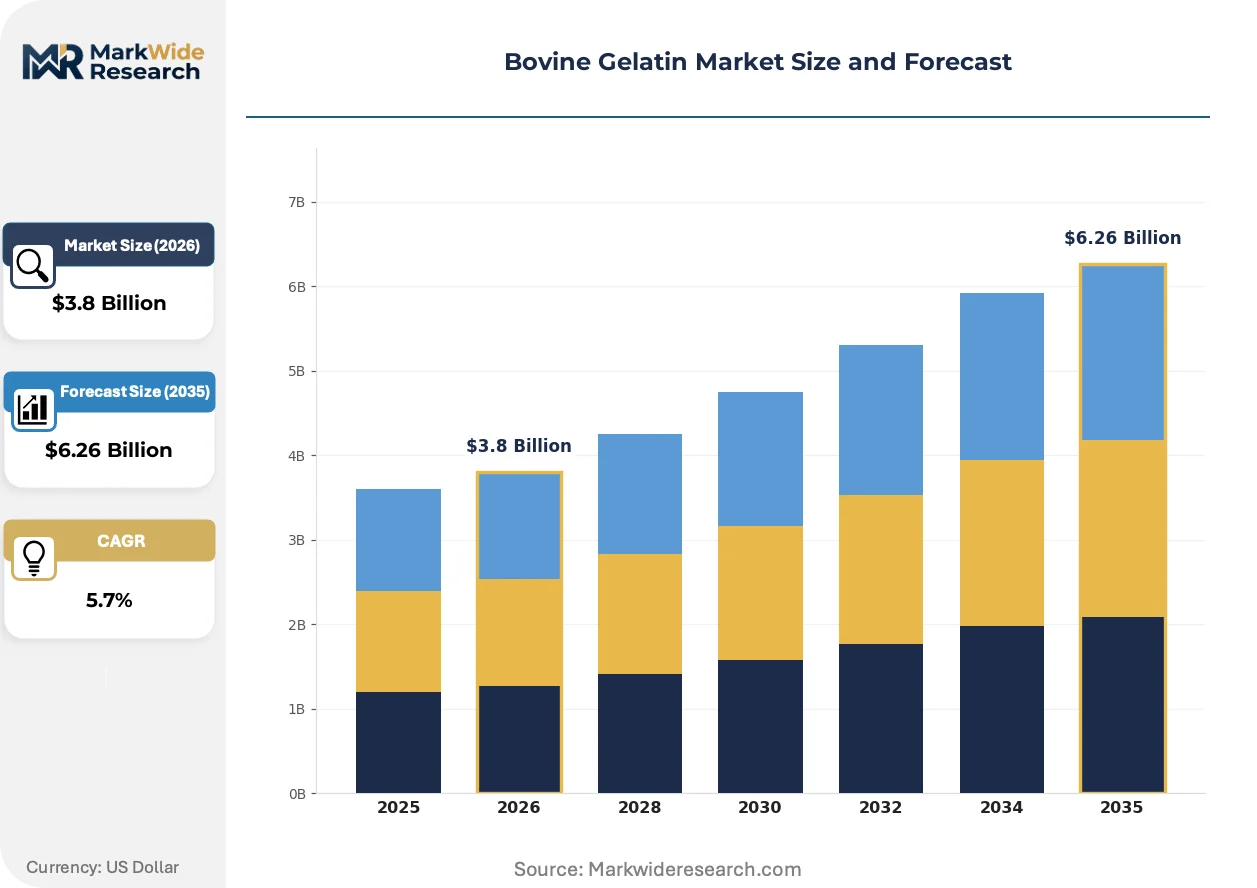
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granule, Sheet, Film Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Food Industry, Healthcare, Personal Care, Research Institutions Form: Liquid, Solid, Gel, Capsule |
| Companies Covered | Gelita AG, Darling Ingredients, Nitta Gelatin Inc., Lapi Gelatine S.p.A., Tessenderlo Group, Weishardt, PB Leiner, Rousselot, Trobas Gelatine BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bovine Gelatin Market Emerging Trajectories
Extraction technology evolution and regulatory documentation digitization are compressing batch-to-batch variability while enabling real-time supply chain verification for pharmaceutical and food-grade buyers.
Enzymatic hydrolysis protocols are migrating from acid-based collagen breakdown methods in premium nutraceutical manufacturing, where peptide molecular weight precision determines bioavailability claims. European and North American supplement brands are accelerating adoption to meet label substantiation requirements. This shift is compressing demand for conventional gelatin with undefined peptide profiles in high-margin applications.
China's SAMR enforcement of GB standards for imported collagen raw materials now mandates geographic origin traceability and species verification documentation for all cross-border shipments. The industrial consequence is a filtering of uncertified suppliers from pharmaceutical and food ingredient channels. Pharmaceutical capsule manufacturers in East Asia are responding by consolidating procurement with integrated rendering-to-gelatin operators possessing captive cattle sourcing.
Direct formulation partnerships between gelatin suppliers and clean-label confectionery brands are displacing traditional distributor-mediated procurement in Western European markets. Mid-scale chocolate and gummy manufacturers are negotiating exclusive bloom-strength specifications and co-development agreements. This pattern is most visible in Germany and the Netherlands where retailer sustainability scorecards reward documented supply chain transparency.
Bovine Gelatin Market Segmentation
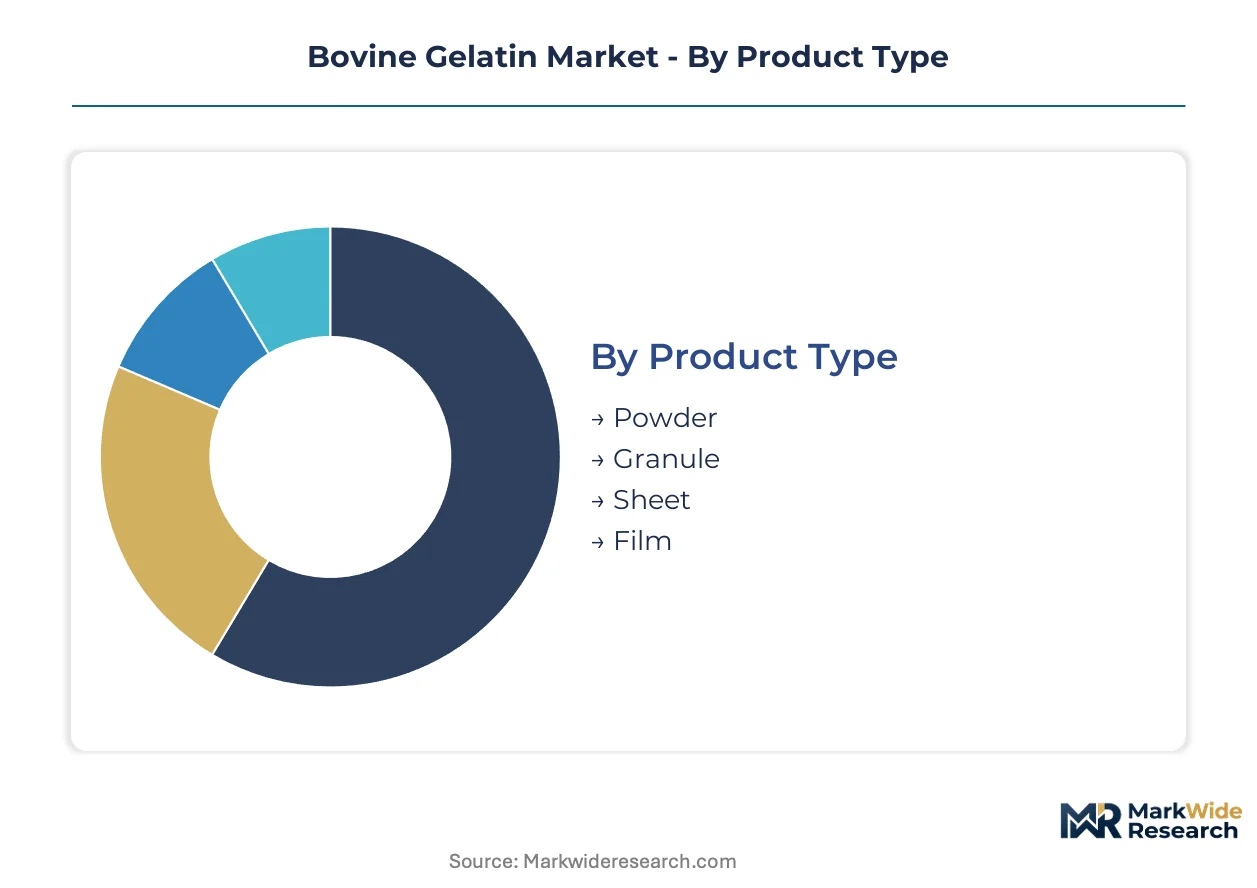
Bovine gelatin's functional versatility across gelling, stabilizing, and film-forming roles creates distinct procurement patterns by physical format and end-use specification. Segmentation reveals where margin pools concentrate and which extraction technologies warrant dedicated capacity investments.
Product Type:
After-sales technical support intensity varies sharply across physical formats, with pharmaceutical-grade sheet and film grades requiring sustained customer engineering collaboration on dissolution profiles and capsule-film compatibility.
- Powder:Dispersible particulate format dominates food and beverage manufacturing where hydration kinetics determine processing line efficiency. Demand concentrates in confectionery and dairy applications across Germany and the Netherlands, with clean-label retailer mandates pulling volume toward certified alkali-extracted supply. By volume, Powder leads. By growth pace, Film is ahead.
- Granule:Intermediate particle size offers controlled dissolution for industrial-scale batching operations. Pharmaceutical tablet binding and nutraceutical powder blending in India represent primary demand nodes, with BIS certification requirements filtering procurement toward traceable supply chains.
- Sheet:Defined thickness gelatin sheets serve premium confectionery and culinary applications requiring precise bloom-strength layering. French and Italian dessert manufacturers maintain specialized procurement relationships for calibrated sheet grades.
- Film:Thin-gauge transparent films command premium positioning in pharmaceutical capsule shells and enteric coatings. EP and USP monograph compliance requirements concentrate demand with integrated extraction facilities possessing captive rendering operations.
Pharmaceutical-grade formats capture margin premiums through certification barriers, while food-grade powder competes on hydration efficiency and dispersibility specifications.
Application:
Cost tier stratification separates commodity food-grade supply from pharmaceutical and nutraceutical segments where documentation burden and extraction precision justify price multiples.
- Food & Beverage:Gelling and stabilizing functions across confectionery, dairy, and meat products represent the foundational demand base. Clean-label formulation mandates from major European retailers are restructuring procurement toward transparent supply chains with species verification systems.
- Pharmaceuticals:Hard and soft capsule shells, tablet binders, and film coatings require EP and USP monograph compliance with defined viscosity and bloom profiles. FDA 21 CFR 172.5 and EMA documentation requirements concentrate volume with certified extraction facilities.
- Cosmetics:Film-forming and moisture-binding properties drive use in masks, creams, and hair care formulations. South Korean and Japanese beauty manufacturers represent concentrated demand for hydrolyzed collagen peptides with defined molecular weight ranges.
- Nutraceuticals:Hydrolyzed bovine collagen peptides for joint health and skin elasticity supplements are expanding most quickly, with enzymatic hydrolysis protocols displacing conventional gelatin in premium positioning. Sports nutrition channels in North America and Western Europe are accelerating adoption of liquid concentrate formats.
Food and Beverage maintains volume leadership while Nutraceuticals climbs fastest on peptide bioavailability claims and functional positioning.
End User:
Customer type determines specification stringency, with healthcare and research institutions imposing documentation requirements that food industry buyers rarely match.
- Food Industry:Confectionery, dairy, and processed meat manufacturers prioritize dispersibility, hydration speed, and cost efficiency in bulk procurement. India's PLI scheme incentives for food processing infrastructure are accelerating localized consumption and import substitution.
- Healthcare:Pharmaceutical manufacturers and hospital formulators require batch-to-batch consistency with full BSE/TSE traceability documentation. Multi-jurisdiction certification timelines extend supplier qualification cycles significantly.
- Personal Care:Cosmetic and personal hygiene product manufacturers seek film-forming and emulsion-stabilizing properties with sensory profile customization. Asian beauty markets drive specialized hydrolyzed peptide demand.
- Research Institutions:Cell culture media, laboratory reagents, and analytical applications require ultra-pure grades with minimal endotoxin levels. Specified protein content and low bioburden specifications limit qualified supplier pools.
Food Industry commands volume scale while Healthcare extracts premium pricing through compliance burden.
Form:
Supply concentration in solid and gel formats reflects historical processing infrastructure, while liquid and capsule forms are gaining traction in convenience-oriented applications.
- Liquid:Hydrolyzed collagen concentrates for functional beverages and ready-to-drink supplements require shelf-life stabilization technologies. Sports nutrition channels are penetrating despite shorter stability windows compared to dry formats.
- Solid:Powder and granule aggregates remain the default for industrial-scale food and pharmaceutical manufacturing. Dispersibility engineering and packaging moisture protection determine competitive positioning.
- Gel:Pre-hydrated gelatin preparations serve specialized confectionery and culinary applications requiring immediate use without dissolution steps. Premium dessert manufacturers in France and Belgium maintain niche demand.
- Capsule:Pre-formed hard and soft gelatin capsules represent downstream value-added processing rather than raw material supply, with integrated capsule manufacturers controlling this form channel.
Solid forms dominate manufacturing inputs while Liquid formats are gaining fastest in consumer-facing convenience applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme incentives for food processing infrastructure are accelerating localized bovine gelatin consumption and reducing import dependency. Germany and the Netherlands anchor European demand through clean-label confectionery procurement. China's SAMR enforcement of GB standards is filtering uncertified suppliers from pharmaceutical channels.
United States
Pharmaceutical capsule manufacturers drive premium-grade demand through FDA 21 CFR 172.5 compliance requirements. The country's national pharmaceutical regulator maintains stringent BSE/TSE documentation protocols for cross-border collagen shipments. Chicago and Kansas City processing clusters concentrate integrated rendering-to-gelatin operations serving domestic healthcare formulators.
Germany
Clean-label confectionery brands in North Rhine-Westphalia and Bavaria are negotiating exclusive bloom-strength specifications with gelatin suppliers. ECHA's updated REACH chemical safety framework tightens raw material traceability requirements for collagen processors. The Eindhoven-adjacent Rhine-Ruhr industrial corridor hosts specialized alkali extraction facilities meeting EP monograph standards.
China
SAMR enforcement of GB standards for imported collagen raw materials mandates species verification and geographic origin traceability. Yangtze River Delta pharmaceutical manufacturers are consolidating procurement with integrated operators possessing captive cattle sourcing. Shanghai and Suzhou clusters concentrate capsule film production requiring documented supply chain transparency.
India
FSSAI labeling requirements for vegetarian-sensitive consumer segments favor transparent supply chain operators with species verification systems. The PLI scheme accelerates domestic food processing infrastructure investments across Maharashtra and Gujarat. Mumbai and Ahmedabad industrial zones concentrate mid-scale toll manufacturing arrangements narrowing capital barriers for regional entrants.
Brazil
Rendering output fluctuations in São Paulo and Minas Gerais create raw material cost instability for non-integrated gelatin producers. ANVISA pharmaceutical regulations align with international BSE/TSE documentation standards for collagen-derived materials. The Campinas processing corridor anchors South American bovine byproduct concentration for export-oriented gelatin production.
Bovine Gelatin Market Vendor Landscape
On the supply side, the industry is consolidating around integrated rendering-to-gelatin operators and specialized extraction facilities with multi-jurisdiction certification capabilities. Three archetypes dominate: integrated agribusiness conglomerates controlling upstream cattle processing, pharmaceutical-grade specialists with EP and USP monograph compliance, and regional toll manufacturers leveraging asset-light third-party collagen tolling. Competitive dynamics center on backward integration into rendering operations and geographic expansion into undercertified pharmaceutical markets.
Among European specialists, Gelita AG and Lapi Gelatine S.p.A. exemplify the pharmaceutical-grade tier with controlled alkali extraction protocols. Darling Ingredients represents the integrated agribusiness archetype with rendering-to-gelatin pipeline control across North American cattle processing regions. Rousselot occupies a position within the hydrolyzed peptide specialization vector targeting Asian nutraceutical markets.
| Leading Market Players |
|---|
| Gelita AG |
| Darling Ingredients |
| Nitta Gelatin Inc. |
| Lapi Gelatine S.p.A. |
| Tessenderlo Group |
| Weishardt |
| PB Leiner |
| Rousselot |
| Trobas Gelatine BV |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Southeast Asian pharmaceutical-grade alkali extraction facilities is compressing spot pricing for EP and USP monograph-compliant gelatin while forcing buyers toward long-term offtake contracts with integrated European and North American suppliers.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and food-grade tiers, with FDA 21 CFR 172.5 and EMA documentation requirements supporting premium positioning for capsule film applications. Three-tier pricing structure across premium, standard, and economy levels reflects bloom strength precision, BSE/TSE traceability depth, and after-sales technical support intensity. Cost compression in standard food-grade powder is intensifying because Brazilian and Argentine rendering output fluctuations feed raw material volatility into non-integrated processors. Food industry buyers exhibit highest price sensitivity due to commoditized hydration kinetics, while healthcare formulators prioritize batch consistency over unit cost.
Supply Chain Analysis
Cattle byproduct availability in Brazil, Argentina, and India anchors upstream feedstock concentration for collagen extraction, with rendering-to-gelatin pipeline control determining cost stability. Bovine skin, bones, and connective tissues drawn from slaughterhouse operations feed alkali and acid pretreatment protocols, while specialized enzyme formulations for hydrolyzed peptides rest on biotech supplier relationships. Single-source vulnerability runs through concentrated South American rendering corridors exposed to cattle cycle volatility. Distribution runs through integrated agribusiness conglomerates with captive sourcing, regional toll manufacturers leveraging third-party collagen tolling, and specialized pharmaceutical-grade specialists with multi-jurisdiction certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from plant-based hydrocolloids in clean-label confectionery, requiring defensive positioning around functional performance advantages that pectin and carrageenan cannot replicate.
For Market Incumbents: Insulate pharmaceutical-grade margin pools by deepening backward integration into rendering operations across North American cattle processing regions, while accelerating enzymatic hydrolysis capacity to defend against peptide bioavailability claims from collagen competitors. Multi-jurisdiction certification investments in EP, USP, and FSSAI compliance create switching costs that plant-based substitutes cannot easily overcome. For New Entrants and Emerging Players: Southeast Asia's underdeveloped pharmaceutical-grade alkali extraction infrastructure offers white-space entry for certified facilities serving Yangtze River Delta capsule manufacturers. India's PLI scheme incentives for food processing infrastructure present a second penetration vector through toll manufacturing arrangements with domestic confectionery brands. A go-to-market angle anchored in species verification systems and transparent supply chain documentation addresses FSSAI labeling requirements for vegetarian-sensitive segments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated rendering-to-gelatin operators with captive cattle sourcing and long-term offtake contracts with healthcare formulators. Over the medium-term horizon, acquisition targets should prioritize facilities with simultaneous EP and USP monograph compliance and established BSE/TSE documentation protocols. The signal to watch is regulatory divergence between pharmaceutical-grade monograph standards and food-grade specification flexibility, as this gap determines where margin pools consolidate.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering Operations | Captive cattle sourcing in São Paulo and Minas Gerais insulates raw material cost volatility from Brazilian rendering fluctuations. |
| Enzymatic Hydrolysis Capacity Expansion | Peptide molecular weight precision meets EFSA label substantiation requirements for joint health supplement positioning. |
| Multi-Jurisdiction Certification Investment | Simultaneous EP, USP, and FSSAI compliance extends supplier qualification cycles and builds switching costs. |
| Direct Formulation Partnerships with Clean-Label Brands | Exclusive bloom-strength specifications with German and Dutch confectionery manufacturers displace distributor-mediated procurement. |
| Species Verification System Deployment | Geographic origin traceability documentation satisfies China's SAMR GB standards for imported collagen raw materials. |
Methodological Framework
Initial hypotheses were tested against primary input from gelatin plant managers, pharmaceutical procurement leads at capsule manufacturers, FSSAI regulatory affairs specialists, and clean-label confectionery brand managers, then refined against secondary validation from FDA 21 CFR filings, EFSA safety evaluations, BIS certification databases, and customs trade records. Bottom-up capacity assessments across alkali extraction facilities were triangulated with top-down demand modeling by application segment.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeled by product format, application tier, and end-user specification stringency. CAGRs were derived from elasticity-adjusted consumption trajectories incorporating PLI scheme incentive impacts and REACH framework compliance cost pass-through. Forecast inputs included rendering output volatility indices and enzymatic hydrolysis adoption curves in nutraceutical channels.
Practitioners should monitor regulatory divergence between pharmaceutical-grade monograph standards and food-grade flexibility, BSE/TSE documentation burden changes, and plant-based hydrocolloid functional performance advances for early signals of forecast revision. Cross-checking against EMA certification timelines and FSSAI enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Dried Beet Pulp Market
Ingredients
Blue Light Protection Ingredients Market
Ingredients
Soy Lecithin Market
Ingredients
Africa Food Ingredients Market
Ingredients
Low Fat Cooking Oil Market
Ingredients
North America Dairy Protein Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
Tomato Concentrate Market
Ingredients
United States Wheat Protein Market
Ingredients
Caramel Ingredient Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
APAC Savoury Ingredients Market
Ingredients
White Wheat Malt Market
Ingredients
Starch-Derived Fiber Market