
 Ice Cream Ingredients Market | 2026-2036
Ice Cream Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream Ingredients Market Foresight
The capital-intensity divergence between multinational suppliers and regional ingredient blenders is unwinding competitive stability in ice cream inputs. Cargill leverages its integrated sweetener and texturant supply chains to sustain cost advantages across bulk industrial accounts. Kerry differentiates through flavor systems and dairy protein expertise, positioning its portfolio toward premium artisanal channels where margin pools deepen.
Ice cream ingredients comprise functional additives—emulsifiers such as mono- and diglycerides, stabilizers including locust bean gum and carrageenan, sweeteners from sucrose to maltodextrin, and flavor compounds—that control crystallization, overrun, and mouthfeel during dynamic freezing. These inputs determine shelf-life stability, scoopability, and sensory delivery in finished frozen desserts. Sweeteners and stabilizers together anchor the largest value share within the component dimension, though emulsifiers command higher per-kilogram pricing due to specialized lipid chemistry requirements. The application split between industrial scale production and artisanal craft manufacturing reveals diverging procurement patterns, with bulk manufacturers prioritizing cost-optimized powders while small-batch producers seek liquid concentrates and clean-label stabilizer systems.
EFSA novel food assessments, FDA GRAS self-affirmation pathways, and EU F-Gas Regulation compliance for freezing equipment collectively shape ingredient approval timelines and manufacturing infrastructure requirements. REACH chemical registration obligations further constrain emulsifier sourcing flexibility for suppliers operating across European markets. Stakeholders must monitor evolving clean-label definitions and carbon-footprint disclosure mandates as these frameworks increasingly determine contract eligibility with retail and food-service buyers.
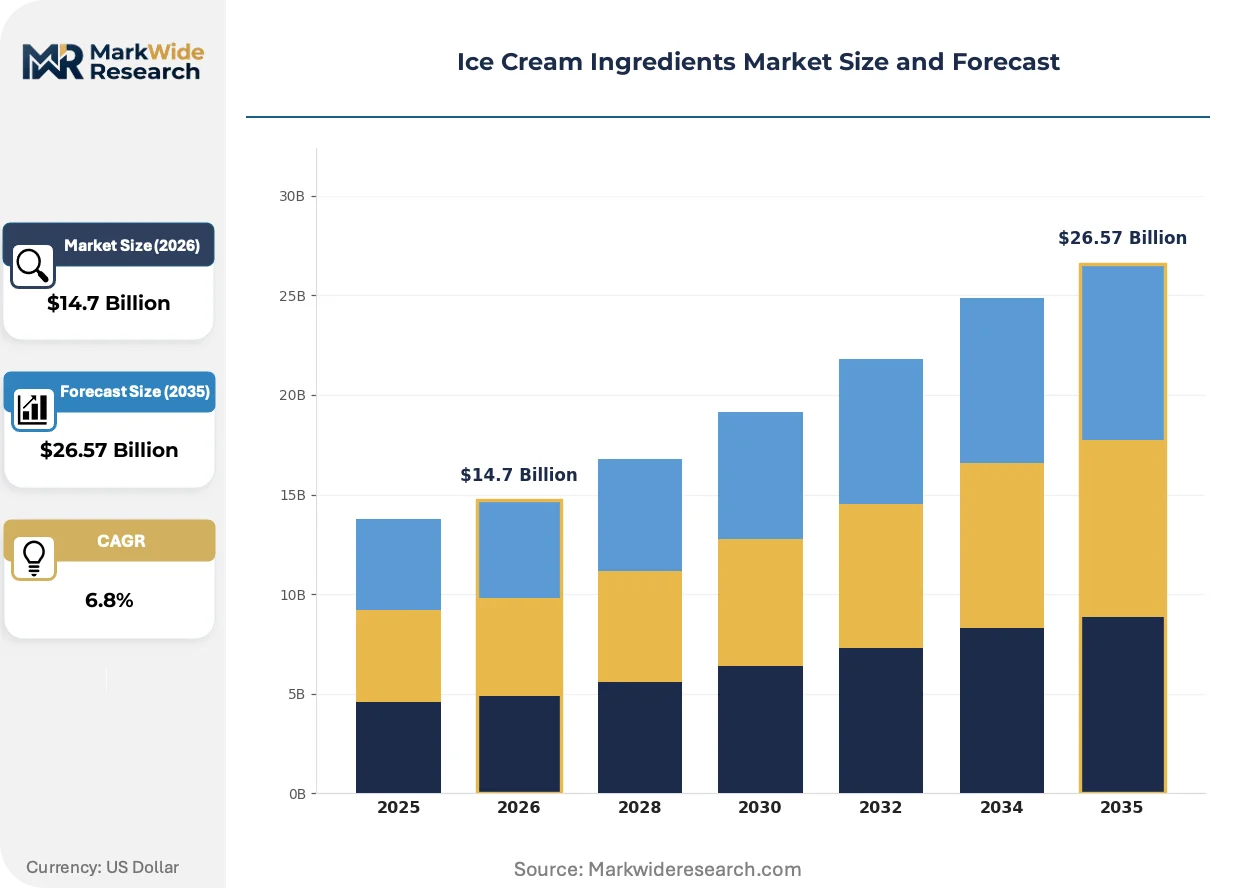
Market Dynamics
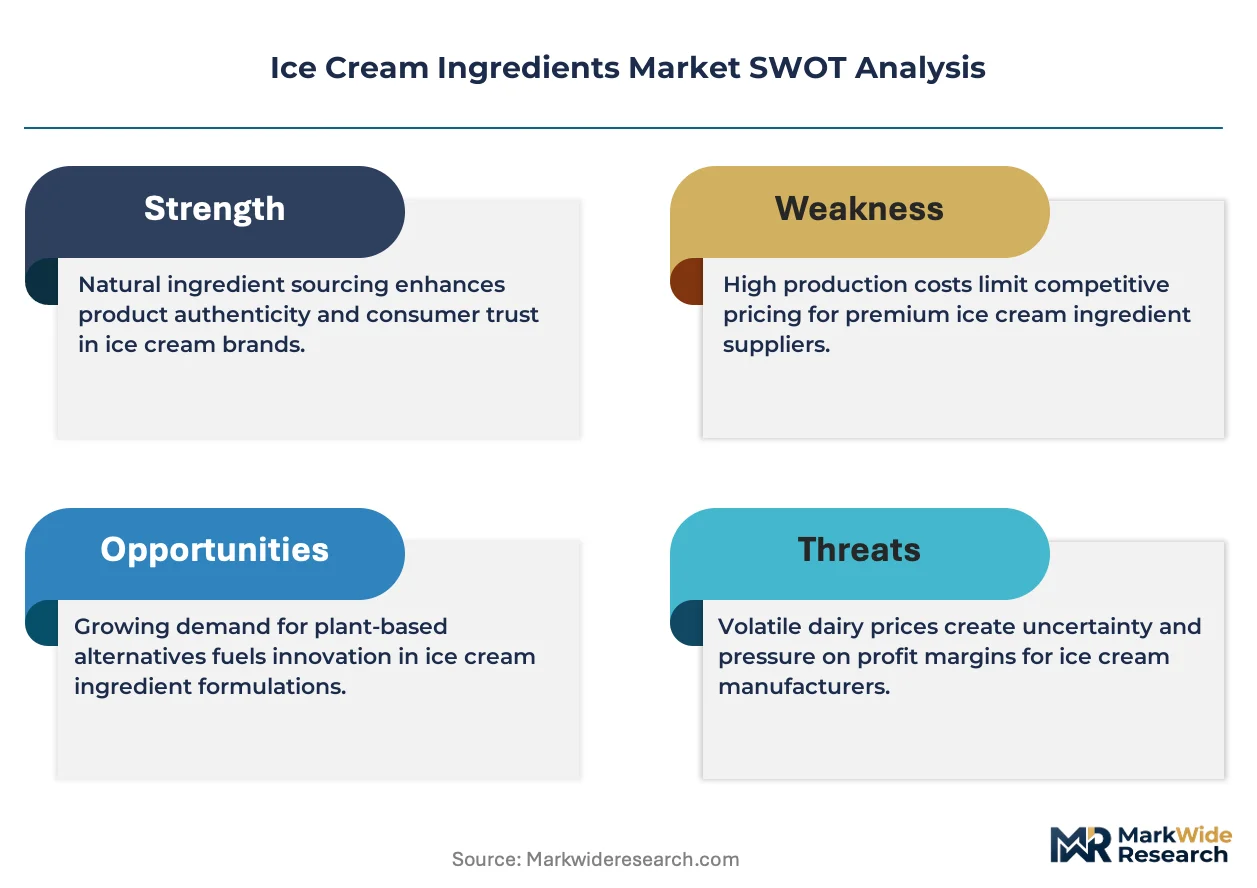
Clean-label mandates from EFSA and FDA are compressing formulation cycles while artisanal gelato producers in Germany accelerate specialty ingredient procurement, forcing suppliers to reconcile regulatory compliance with small-batch customization demands.
Growth Catalysts
- EFSA Novel Food Pathways:Accelerated approval timelines for plant-based stabilizers and alternative proteins are enabling faster product launches across European artisanal channels.
- Craft Ice Cream Parlor Expansion:Germany's specialty parlor segment is driving concentrated demand for premium emulsifier systems and liquid flavor concentrates.
- Precision Fermentation:Emerging microbial production methods for dairy proteins are creating new formulation possibilities for vegan frozen dessert applications.
Market Restraints
- Locust Bean Gum Supply Concentration:Mediterranean harvest volatility and limited geographic sourcing for this critical stabilizer create input cost instability.
- REACH Registration Burden:ECHA chemical compliance obligations constrain emulsifier sourcing flexibility for suppliers operating across European markets.
- EU F-Gas Equipment Mandates:Freezing infrastructure retrofit requirements add capital friction for ingredient manufacturers with captive processing operations.
Strategic Opportunities
- Carbon Disclosure Contracts:Retail and food-service buyers in Germany are mandating lifecycle footprint data, creating competitive differentiation for transparent suppliers.
- Clean-Label Stabilizer Blends:Unmet demand exists for single-ingredient alternatives to carrageenan in premium organic gelato formulations.
- Direct-to-Parlor Distribution:Bypassing traditional ingredient distributors to serve small-batch producers with customized liquid concentrate systems.
Industry Challenges
- Formulation Scientist Scarcity:Shortage of specialists capable of balancing crystallization control with clean-label requirements in frozen dessert applications.
- Dual Certification Timelines:Parallel FDA GRAS self-affirmation and EFSA novel food assessments extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream Ingredients Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Sweeteners, Emulsifiers, Stabilizers, Flavors Form: Liquid, Powder, Granular, Paste Application: Artisanal, Industrial, Retail, Food Service Customer Type: Manufacturers, Distributors, Retailers, Consumers |
| Companies Covered | Cargill, Archer Daniels Midland (ADM), Kerry, IFF (formerly DuPont Nutrition & Biosciences), dsm-firmenich, Ingredion, Tate & Lyle, CP Kelco, Fonterra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream Ingredients Market Shifts & Advancements
Ingredient functionality is decoupling from synthetic chemistry as biological and mechanical alternatives reshape texturant and emulsifier portfolios across industrial and craft production tiers.
Precision fermentation-derived dairy proteins are fragmenting traditional whey and casein supply relationships. Artisanal gelato makers in Northern Italy and Southern Germany are piloting these ingredients for mouthfeel replication. The technology is fragmenting established dairy protein procurement channels and forcing conventional suppliers into co-development partnerships.
EFSA's evolving clean-label definitions and expanded novel food assessments are tightening formulation disclosure requirements. Manufacturers must now document processing aids and incidental additives previously exempt from labeling. Small-batch producers in France and Belgium face the steepest compliance adaptation costs relative to their scale.
Ingredient purchasing is consolidating through cooperative buying groups among independent craft parlors. These collectives are displacing traditional distributor relationships with direct supplier contracts for stabilizers and flavor systems. The shift is most pronounced in urban clusters across Germany and the Netherlands where parlor density enables viable aggregation.
Ice Cream Ingredients Market Segmentation
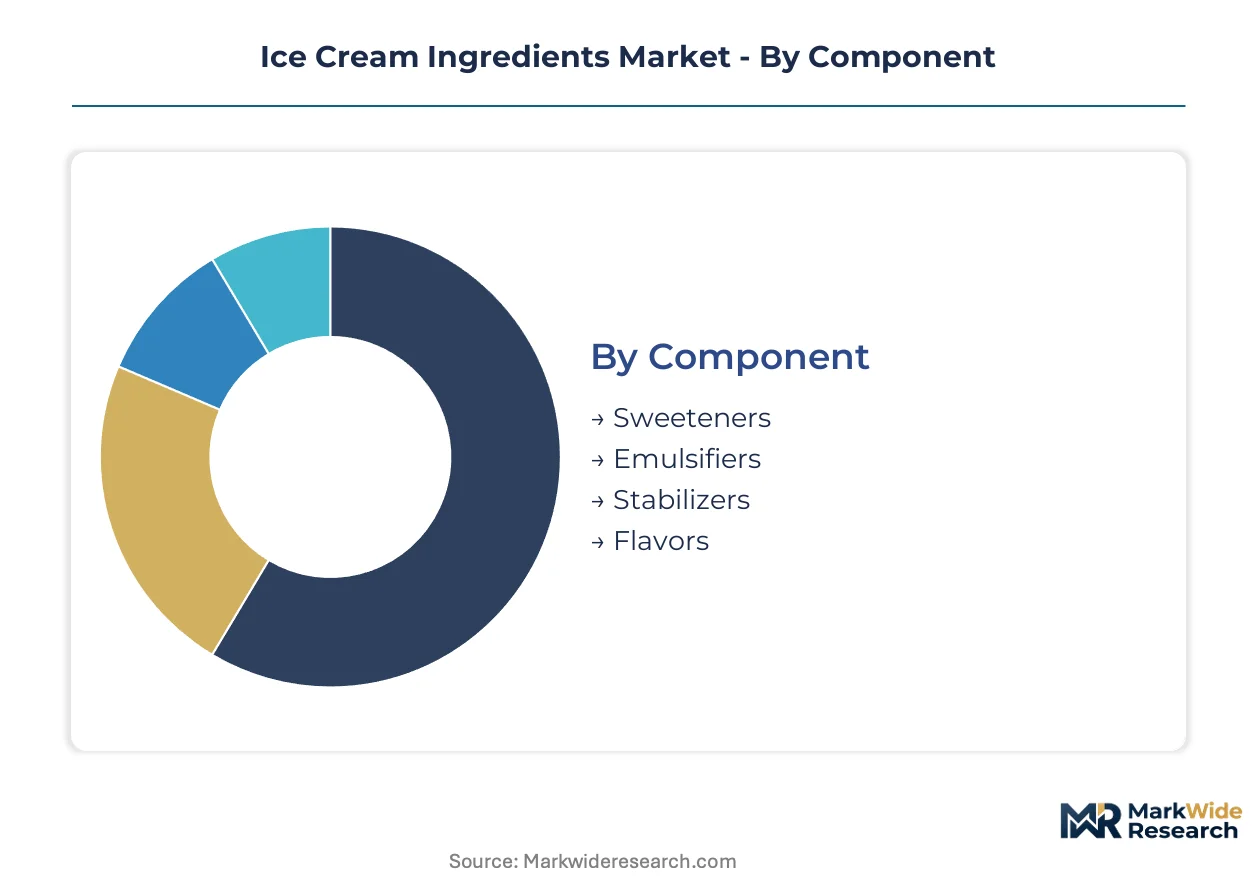
Ingredient procurement patterns diverge sharply across component chemistry, physical form, and end-use application. Suppliers must align formulation services with distinct technical requirements and regulatory exposure profiles.
Component:
Plant-derived alternatives are displacing conventional synthetic inputs fastest in stabilizer and emulsifier categories, pressuring suppliers to reformulate around clean-label mandates without sacrificing functional performance.
- Sweeteners:Sucrose, maltodextrin, and polyols control freezing point depression and sweetness delivery. Bulk industrial manufacturers in Germany prioritize cost-optimized sucrose syrups, while artisanal producers in Belgium source organic agave and coconut sugar to meet EFSA clean-label disclosure requirements.
- Emulsifiers:Mono- and diglycerides, lecithin, and polysorbates manage fat globule dispersion and overrun stability. Demand concentrates among precision fermentation startups seeking lipid chemistry expertise for vegan frozen dessert applications, with Kerry and Cargill competing on technical service depth.
- Stabilizers:Locust bean gum, guar gum, and carrageenan control ice crystal growth and melt resistance. Mediterranean harvest volatility for locust bean gum creates supply concentration risk that favors multi-source guar formulations in industrial accounts.
- Flavors:Natural extracts, synthetic compounds, and reaction flavors deliver sensory profiles. Liquid concentrate systems gain traction in craft parlor channels where small-batch flexibility outweighs per-unit cost premiums.
Sweeteners anchor the volume base while precision fermentation-enabled emulsifiers gain share at the steepest rate.
Form:
Physical state determines logistics economics and formulation labor intensity, with powder dominating bulk procurement and liquid concentrates penetrating premium channels.
- Liquid:Concentrated syrups and emulsion systems reduce handling steps for small-batch producers. German craft parlors in Berlin and Munich drive concentrated demand for liquid stabilizer blends that eliminate hydration time.
- Powder:Spray-dried emulsifiers and blended stabilizers offer shelf stability and freight efficiency. Industrial-scale manufacturers prioritize powder formats for automated dosing systems and extended storage.
- Granular:Crystalline sweeteners and coarse stabilizer grades suit specific texture requirements. Limited penetration outside specialty organic formulations where particle size affects dissolution kinetics.
- Paste:High-solids flavor bases and concentrated emulsifier dispersions. Niche adoption in gelato applications requiring intense flavor impact with minimal water addition.
Powder formats retain the largest volume position while liquid systems expand most quickly in artisanal channels.
Application:
Production scale separates procurement priorities, with industrial buyers optimizing unit economics and craft operators prioritizing formulation flexibility.
- Artisanal:Small-batch gelato and ice cream production with emphasis on clean-label credentials and local sourcing. Northern Italy and Southern Germany clusters drive specialty ingredient demand with direct supplier relationships displacing distributors.
- Industrial:High-volume frozen dessert manufacturing with standardized formulations and cost-optimized inputs. REACH registration burdens and EFSA compliance timelines shape supplier qualification processes.
- Retail:Private-label and branded packaged ice cream requiring extended shelf-life stability. Carbon footprint disclosure mandates from German retail buyers constrain ingredient sourcing flexibility.
- Food Service:Soft-serve and scoop-shop operations with variable throughput and equipment constraints. EU F-Gas Regulation compliance for freezing infrastructure adds capital friction for captive ingredient processing.
Industrial application anchors volume while artisanal channels climb fastest on premium positioning.
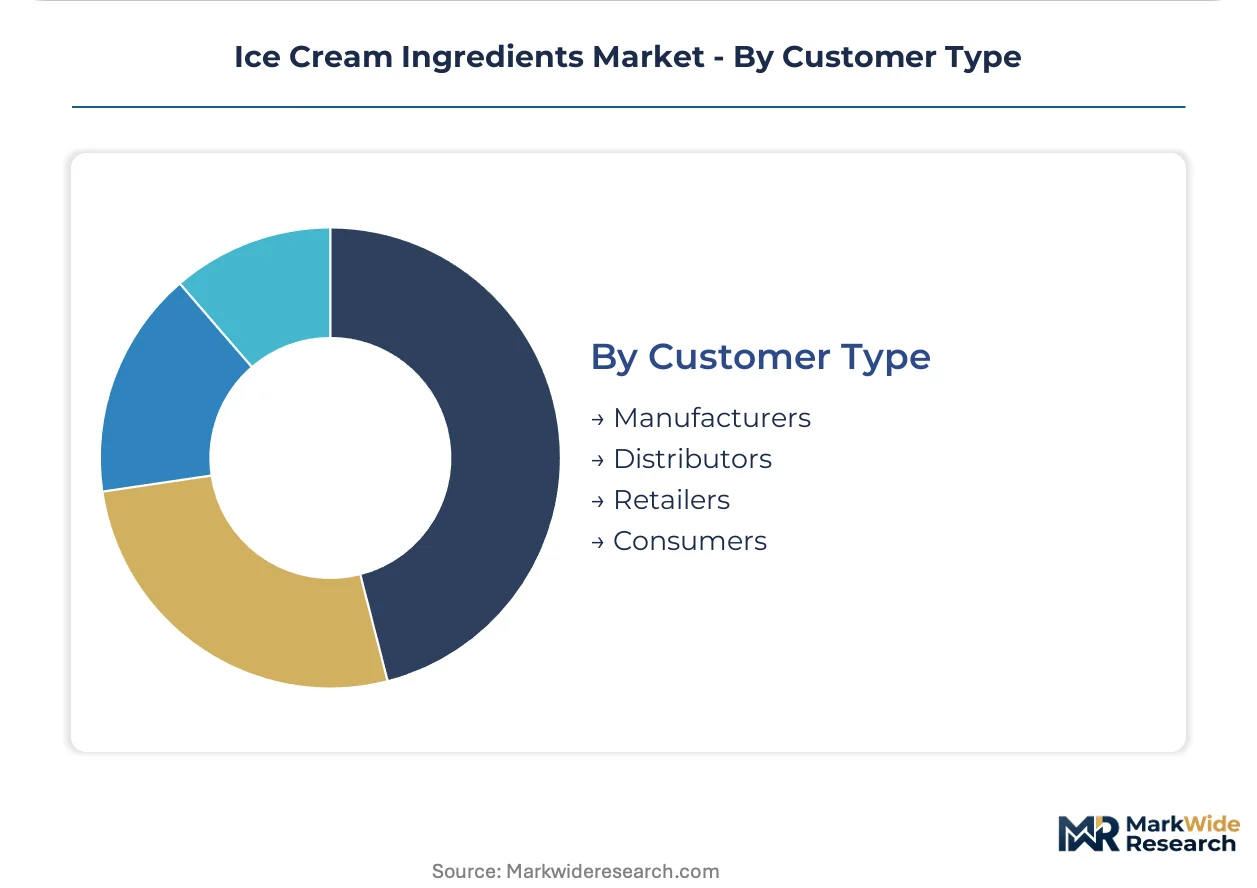
Customer Type:
Purchasing sophistication varies dramatically, with manufacturers demanding technical co-development and retailers imposing sustainability verification.
- Manufacturers:Frozen dessert producers requiring formulation support and regulatory documentation. EFSA novel food assessments and FDA GRAS pathways extend supplier engagement timelines.
- Distributors:Traditional ingredient intermediaries facing displacement from cooperative buying groups. German parlor collectives aggregate demand to bypass distributor markups on stabilizers and flavors.
- Retailers:Supermarket and convenience chains with private-label ice cream programs. Lifecycle footprint data requirements from German retail buyers favor transparent suppliers.
- Consumers:Direct-to-home ingredient kits for homemade frozen desserts. Minimal penetration limited by cold-chain logistics complexity.
Manufacturers dominate procurement volume while retailer direct contracting expands most rapidly on sustainability verification demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Germany accept premium pricing for clean-label credentials while Southeast Asian processors remain highly price-sensitive on bulk stabilizer procurement. Demand elasticity varies sharply by channel sophistication and regulatory exposure.
Germany
Craft gelato parlors in Berlin and Munich drive concentrated demand for liquid emulsifier concentrates and precision fermentation-derived proteins. EFSA novel food assessments compress formulation approval timelines for plant-based stabilizers. The Baden-Württemberg cluster anchors artisanal ingredient distribution networks serving cross-border Swiss and Austrian producers.
United States
Precision fermentation startups in California and Massachusetts reshape dairy protein sourcing for vegan frozen desserts. FDA GRAS self-affirmation pathways enable faster product launches than European regulatory routes. The Midwest dairy belt maintains bulk sweetener and stabilizer demand from industrial-scale manufacturers.
Italy
Artisanal gelato traditions in Lombardy and Piedmont sustain premium demand for single-origin flavor extracts and clean-label stabilizer blends. EU F-Gas Regulation compliance mandates retrofit capital for freezing equipment across Emilia-Romagna production facilities. Northern Italian parlor collectives pioneer direct supplier contracting models.
France
EFSA expanded disclosure requirements for processing aids strain small-batch producers in Île-de-France and Provence-Alpes-Côte d'Azur. REACH registration obligations constrain emulsifier sourcing flexibility for suppliers serving Parisian craft channels. The Auvergne-Rhône-Alpes region hosts specialty dairy ingredient processing for export gelato markets.
Netherlands
Cooperative buying groups among Amsterdam and Rotterdam craft parlors aggregate demand to bypass traditional distributor markups. ECHA chemical compliance timelines extend supplier qualification processes for stabilizer blenders. The Randstad logistics hub enables just-in-time liquid concentrate distribution to Belgian and German buyers.
Ice Cream Ingredients Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the ice cream ingredients landscape. Integrated agricultural processors dominate bulk sweetener and texturant supply chains through captive raw material access. Specialized flavor houses and dairy protein experts occupy premium formulation service tiers. The market structure rewards M&A-driven portfolio breadth and direct-to-artisan distribution bypass strategies.
Among integrated agricultural processors, Cargill and Archer Daniels Midland exemplify scale-driven archetypes with upstream control over commodity sweetener and texturant supply chains. Kerry occupies a position within the specialized formulation services tier, anchoring technical expertise in dairy protein systems and flavor delivery. These three entities represent the dominant competitive anchors structuring procurement relationships across industrial and craft production segments.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland (ADM) |
| Kerry |
| IFF (formerly DuPont Nutrition & Biosciences) |
| dsm-firmenich |
| Ingredion |
| Tate & Lyle |
| CP Kelco |
| Fonterra |
| Others |
Supply & Pricing Matrix
EFSA novel food assessments gate both supplier qualification and price differentiation simultaneously, as clean-label certification becomes the threshold for contract eligibility with German retail and food-service buyers while commanding measurable premiums over uncertified alternatives.
Pricing Analysis
After-sales technical service and formulation support contracts drive lifetime value in artisanal channels where small-batch producers pay recurring fees for customization assistance. Three-tier pricing structure across premium, standard, and economy levels separates precision fermentation-derived proteins from conventional dairy isolates from commodity sweetener blends. Cost compression in economy-tier stabilizers is intensifying because Mediterranean locust bean gum harvest volatility feeds through to guar gum substitution demand. Bulk industrial manufacturers exhibit highest price sensitivity, while German craft parlors accept premiums for liquid concentrate systems that eliminate hydration labor.
Supply Chain Analysis
Spain, Morocco, and Portugal anchor locust bean gum harvests that feed European stabilizer production, while India and Pakistan supply guar gum alternatives that industrial blenders pivot toward during Mediterranean shortfalls. The supply chain draws from Mediterranean orchards, South Asian guar processing clusters, and Midwestern corn belt sweetener refineries. Single-source vulnerability concentrates in locust bean gum where limited geographic cultivation creates harvest-driven price spikes. Distribution runs through cooperative buying groups that aggregate German parlor demand for direct supplier contracting, bypassing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where cooperative buying groups among craft parlors are displacing distributor intermediaries, creating interoperability demands between supplier ERP systems and parlor collective procurement platforms.
For Market Incumbents: Secure backward integration into precision fermentation capacity before microbial dairy protein production scales beyond pilot volumes. Defend formulation scientist talent pools through technical apprenticeship programs that address scarcity in crystallization control expertise. Channel control through direct-to-parlor liquid concentrate distribution protects margin pools that distributor markups currently erode. For New Entrants and Emerging Players: Lead with clean-label stabilizer blends that replace carrageenan in premium organic gelato formulations where unmet demand outpaces incumbent reformulation cycles. Target German Baden-Württemberg and Netherlands Randstad parlor clusters where cooperative density enables viable aggregation. Go-to-market through technical co-development partnerships with artisanal producers seeking single-ingredient alternatives. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation-enabled ingredient categories as microbial production platforms achieve commercial scale. Long-term viability favors suppliers with dual certification capabilities spanning FDA GRAS and EFSA novel food pathways. Acquisition target archetype: specialized flavor houses with established artisanal channel relationships and clean-label stabilizer formulation depth. Signal to watch: carbon disclosure contract penetration rates among German retail buyers as proxy for regulatory acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial dairy protein production fragments traditional whey and casein procurement relationships across vegan frozen dessert applications. |
| Direct-to-Parlor Distribution Buildout | Bypassing traditional distributors captures margin pools deepening in Berlin and Munich craft gelato channels. |
| Clean-Label Stabilizer R&D Investment | Single-ingredient carrageenan alternatives address EFSA disclosure requirements straining French and Belgian small-batch producers. |
| Cooperative Buying Group Partnership | Aggregation platforms among Netherlands and German parlors reshape procurement economics for liquid concentrate systems. |
| Carbon Footprint Certification Program | Lifecycle transparency meets German retailer mandates that constrain contract eligibility for non-compliant suppliers. |
Research Methodology
A standing panel of formulation scientists at artisanal gelato producers, procurement leads at industrial frozen dessert manufacturers, EFSA regulatory affairs specialists, and flavor house technical directors provided ongoing calibration. Primary interviews combined with secondary validation against customs records, EFSA novel food submission databases, and SEC filings from publicly traded ingredient suppliers. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
Consistency checks validated projections against external benchmarks spanning trade flow data and equipment installation records across European freezing infrastructure. The analytical framework modeled component chemistry, physical form, application scale, and customer purchasing sophistication across the projection horizon. CAGRs derived from regression analysis of historical input cost trajectories and demand elasticity parameters specific to clean-label premium tiers.
Forecasts assume regulatory continuity in EFSA novel food pathways and FDA GRAS self-affirmation regimes; material policy shifts would require re-modeling approval timeline assumptions. Specific risks include REACH registration burden expansion, locust bean gum harvest disruption, and F-Gas equipment mandate acceleration. Recalibration cycles align with material shifts in clean-label definition evolution and carbon disclosure mandate adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Soy Peptones Market
Ingredients
Fiber Rich Flours Market
Ingredients
Fermented Ingredients Market
Ingredients
Europe Dairy Protein Market
Ingredients
Cacao Extracts Market
Ingredients
Elecampane Root Market
Ingredients
Amylase Market
Ingredients
Europe Fruit and Vegetable Ingredients Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Textured Soy Flour Market
Ingredients
Global Edible Oil Market
Ingredients
Europe Malt Extract Market
Ingredients
United States Avocado Oil Market
Ingredients
Egg Free Premix Market
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
Corn Gluten Meal Market