
 Safflower Oil Market | 2026-2036
Safflower Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Safflower Oil Market Outlook
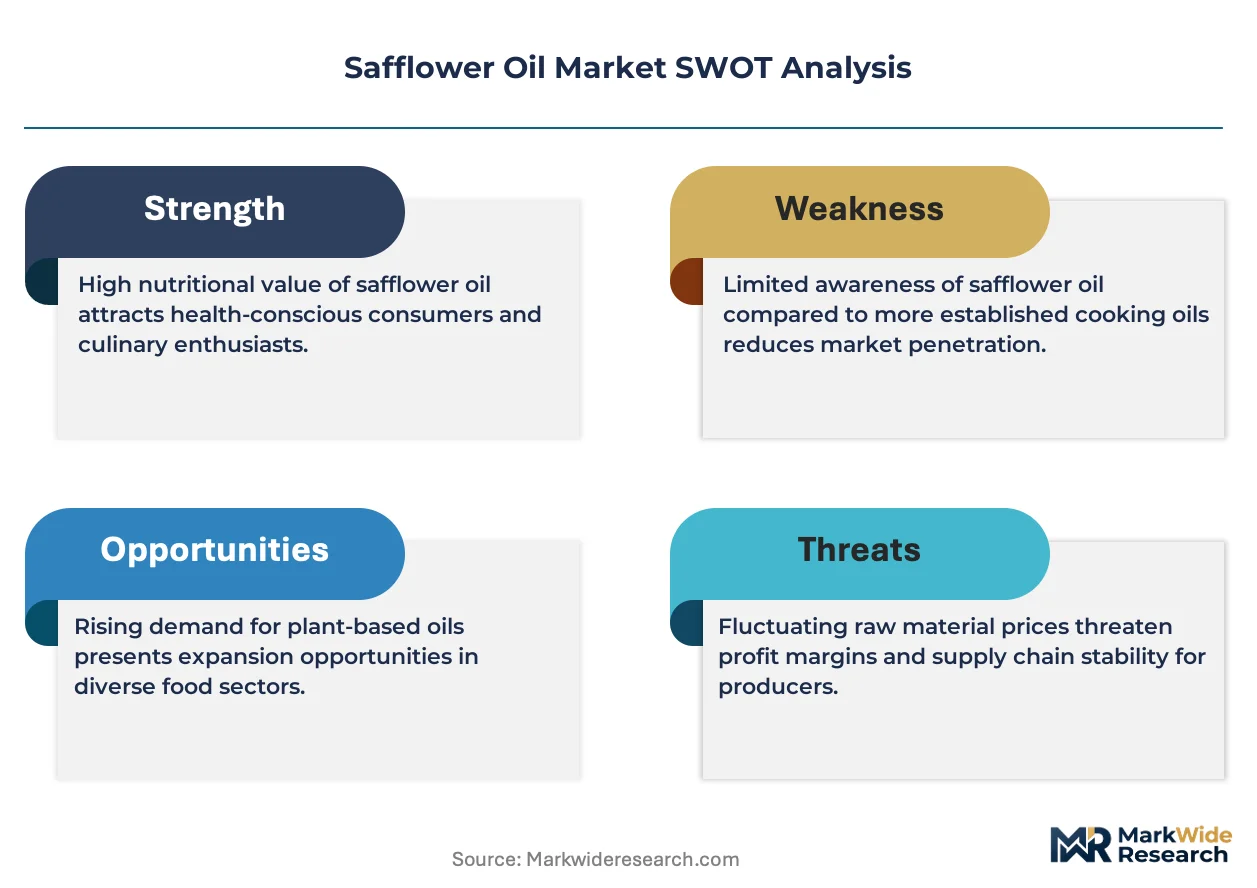
Project finance for small-scale crushing and refining cooperatives is fragmenting competitive access across India's safflower belt. Marico Ltd. leverages its branded edible oil distribution to secure offtake agreements with Maharashtra farmer-producer organizations. Henry Lamotte OILS GmbH anchors European pharmaceutical-grade supply through backward integration into certified organic seed sourcing. Connoils LLC specializes in toll-refining contracts that let mid-sized brands enter the safflower segment without capital-intensive extraction assets.
Safflower oil is a triglyceride vegetable oil extracted from Carthamus tinctorius seeds, with high-oleic varieties containing 70-80% monounsaturated fatty acids and linoleic variants reaching 75% polyunsaturated content; cold-press or solvent extraction yields a light-colored, flavor-neutral oil valued for high smoke-point frying, cosmetic emollient formulations, and linoleic acid dietary supplements. Refined oil dominates food-service volume due to extended fry-life and neutral sensory profiles, while organic oil commands premium shelf positioning in North American and European retail channels where clean-label certification drives margin pools. The nutraceuticals end user segment is expanding fastest as softgel manufacturers source high-linoleic safflower oil for conjugated linoleic acid precursor applications.
India's FSSAI mandates solvent residue limits and labeling disclosures that shape refining investment priorities for domestic crushers. The EU REACH framework and EFSA novel food assessments govern import access for Indian and Chinese safflower oil entering European cosmetic and supplement channels. USDA organic certification and FDA food facility registration create dual compliance thresholds for exporters targeting American natural products retailers. Stakeholders must monitor convergence between India's PLI scheme capacity buildout and evolving EU deforestation-free supply chain due diligence rules that could redirect Indian export flows toward Middle Eastern and Southeast Asian markets.
Market Dynamics
India's PLI scheme for edible oil processing is concentrating crushing capacity in Maharashtra and Gujarat, redirecting export flows toward Middle Eastern and Southeast Asian markets as EU deforestation-free due diligence rules tighten compliance thresholds.
Growth Catalysts
- Clean-label frying demand:Food manufacturers in India are expanding procurement of high-oleic safflower oil for neutral sensory profiles and extended fry-life in food-service applications.
- FSSAI solvent residue mandates:India's food safety regulator enforces strict labeling disclosures and residue limits that shape refining investment priorities for domestic crushers upgrading extraction infrastructure.
- Softgel nutraceutical expansion:Manufacturers source high-linoleic safflower oil for conjugated linoleic acid precursor applications, accelerating volume in dietary supplement channels.
Market Restraints
- Seed supply volatility:Safflower cultivation competes with wheat and chickpea rotations in India's semi-arid zones, creating input cost uncertainty for solvent extraction clusters.
- EU REACH compliance friction:EFSA novel food assessments and deforestation-free supply chain due diligence rules create import barriers for Indian and Chinese safflower oil entering European cosmetic channels.
- Palm and sunflower oil substitution:Lower-cost vegetable oils with comparable smoke-point characteristics displace safflower in bulk frying applications across price-sensitive institutional buyers.
Strategic Opportunities
- Organic certification premium capture:USDA organic certification creates dual compliance thresholds that unlock margin pools in North American natural products retail channels.
- Toll-refining service expansion:Mid-sized brands enter the safflower segment without capital-intensive extraction assets through contract refining partnerships.
- Middle Eastern export pivot:India's PLI scheme capacity buildout redirects refined oil flows toward Gulf Cooperation Council markets as European access constricts.
Industry Challenges
- Dual certification timeline compression:Exporters targeting American natural products retailers must synchronize USDA organic audits with FDA food facility registration windows.
- Backward integration execution:Pharmaceutical-grade suppliers face capital intensity in certified organic seed sourcing and captive crushing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safflower Oil Market |
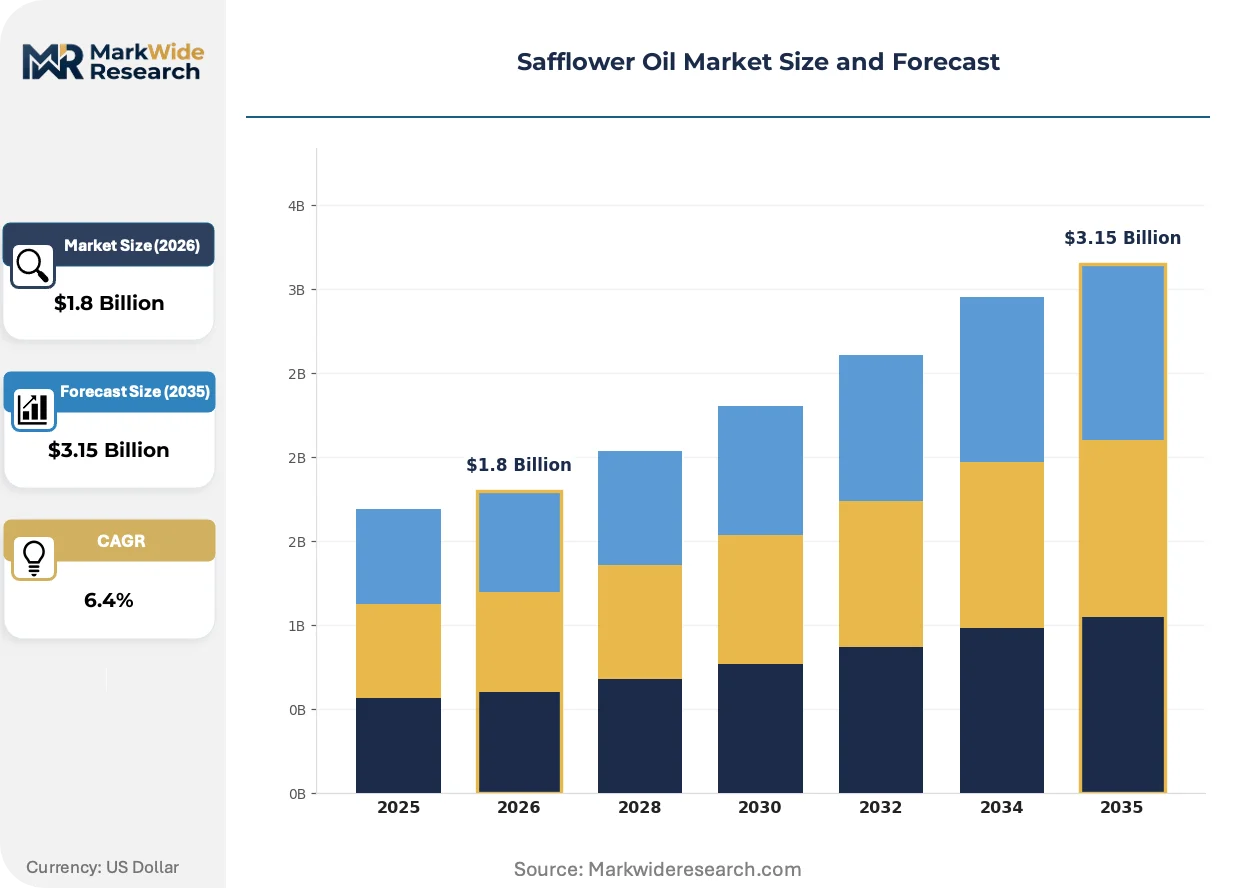
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Crude Oil, Organic Oil, Conventional Oil End User: Food Industry, Cosmetic Industry, Nutraceuticals, Pharmaceuticals Packaging Type: Bottles, Drums, Totes, Bulk Application: Culinary Uses, Skincare Products, Dietary Supplements, Industrial Uses |
| Companies Covered | Connoils LLC, Adams Group Inc., Marico Ltd., Henry Lamotte OILS GmbH, Centra Foods Inc., SunOpta Inc., Oilseeds International Ltd., Spectrum Organic Products LLC, Gustav Heess Oleochemische Erzeugnisse GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safflower Oil Market Strategic Shifts
Extraction technology, regulatory compliance frameworks, and procurement models are simultaneously evolving across the safflower oil value chain, compressing competitive timelines for quality differentiation.
Cold-press extraction equipment is migrating from artisanal-scale operations to mid-cap commercial facilities serving organic retail channels. European cosmetic formulators are adopting these systems to secure pharmaceutical-grade supply with certified organic provenance. The technology is migrating from niche premium positioning toward volume-scale deployment, compressing the cost gap with solvent extraction in high-margin segments.
EU deforestation-free supply chain due diligence rules are reshaping export market access for Indian crushers. EFSA novel food assessments now govern entry into European supplement channels alongside REACH framework compliance for cosmetic applications. Indian solvent extraction clusters are responding by redirecting refined oil flows toward Middle Eastern and Southeast Asian markets with less stringent traceability mandates.
Buyer concentration among pan-Asian food processors is consolidating procurement power across Maharashtra and Gujarat supply basins. Large-scale food manufacturers now secure offtake agreements directly with farmer-producer organizations, disintermediating traditional trader networks. This pattern is most visible in India's safflower belt where Marico Ltd. leverages branded distribution infrastructure to lock in seed supply ahead of crushing season.
Safflower Oil Market Segmentation
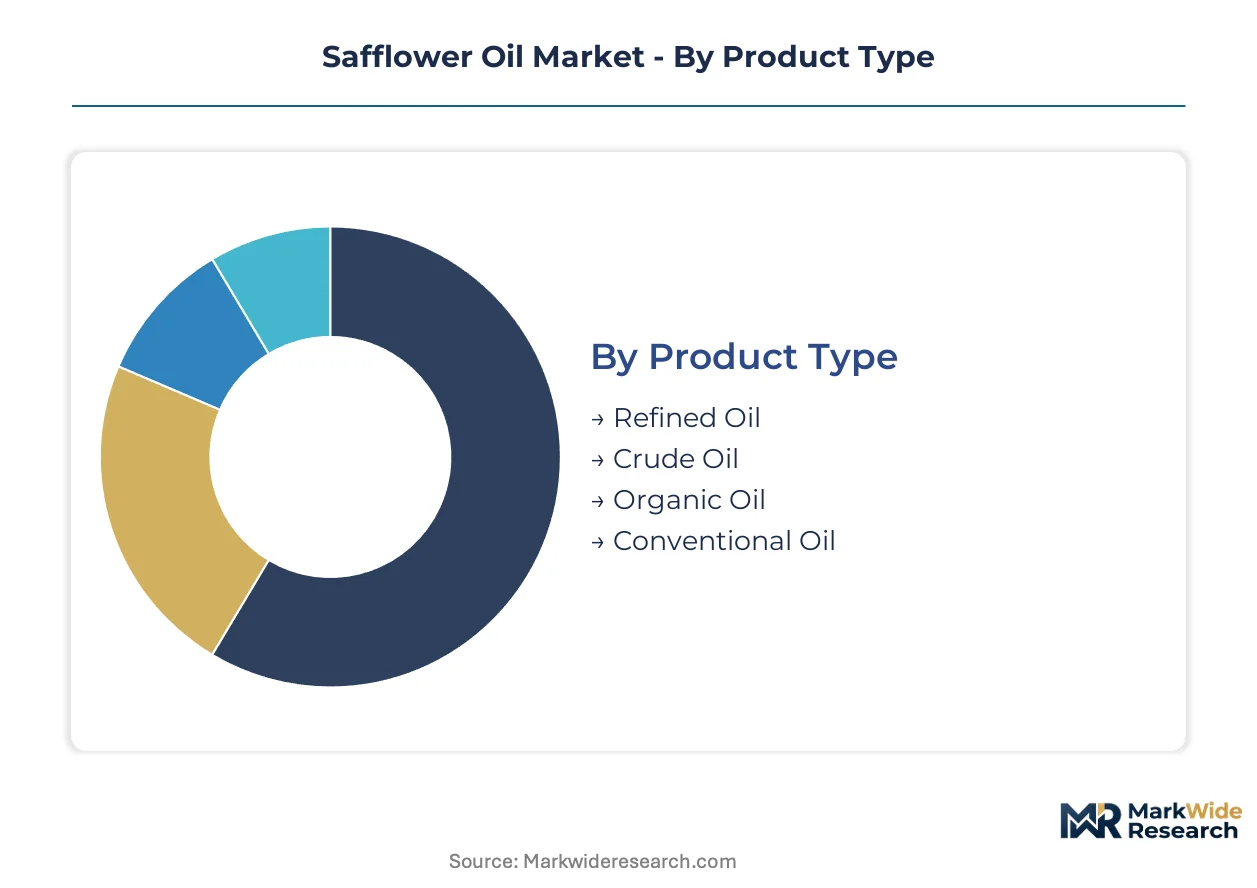
Safflower oil segmentation reveals how extraction method, certification grade, and end-use purity requirements create distinct margin pools across the value chain. Each dimension shapes procurement patterns differently for food-service volume buyers versus pharmaceutical-grade specialists.
Product Type:
Mature refining infrastructure dominates commercial throughput, while organic certification creates emerging premium positioning in North American retail channels.
- Refined Oil:Solvent-extracted and deodorized to neutral sensory profiles with extended fry-life specifications. Maharashtra and Gujarat solvent extraction clusters supply bulk refined oil to pan-Asian food processors seeking clean-label frying mediums with high smoke-point performance.
- Organic Oil:Cold-pressed from certified organic seed with full traceability documentation. USDA organic certification unlocks margin pools in North American natural products retail where clean-label positioning commands shelf price premiums over conventional grades.
- Crude Oil:Unrefined extraction retaining native tocopherol content for cosmetic emollient formulations and subsequent toll-refining operations.
- Conventional Oil:Standard cultivation without organic certification, serving price-sensitive institutional frying applications across Middle Eastern and Southeast Asian markets.
Refined oil handles the majority of throughput; organic oil is expanding most quickly on share as certification premiums penetrate mainstream retail channels.
End User:
Volume concentration tilts toward food manufacturing, while margin capture concentrates in pharmaceutical and nutraceutical channels demanding certified organic provenance.
- Food Industry:High-oleic varieties with 70-80% monounsaturated fatty acid content serve extended fry-life applications in food-service and packaged snack production. India's FSSAI solvent residue mandates shape refining investment priorities for domestic crushers supplying this channel.
- Nutraceuticals:High-linoleic safflower oil reaching 75% polyunsaturated content functions as conjugated linoleic acid precursors in softgel manufacturing. EFSA novel food assessments govern European supplement channel access, compressing compliance timelines for Indian exporters.
- Cosmetic Industry:Pharmaceutical-grade supply with light color and flavor-neutral characteristics supports emollient formulations in European personal care products.
- Pharmaceuticals:Certified organic seed sourcing with backward integration into captive crushing infrastructure anchors supply for active pharmaceutical ingredient applications.
Food industry offtake commands the largest volume base; nutraceuticals demonstrates the steepest expansion trajectory as dietary supplement manufacturers diversify lipid sourcing.
Packaging Type:
Scale economics separate institutional bulk flows from retail-ready unit formats with differentiated handling requirements.
- Bulk:Tanker and flexitank delivery for food manufacturers with integrated refining and formulation capabilities, minimizing per-unit packaging cost in high-volume procurement.
- Drums:Standard 200-liter steel containers for mid-scale cosmetic and nutraceutical processors requiring controlled dispensing without full bulk infrastructure.
- Totes:Intermediate bulk containers bridging drum scale and full bulk delivery for regional food processors and toll-refining operations.
- Bottles:Consumer retail formats with label real estate for organic certification and nutritional claims in North American and European natural products channels.
Bulk packaging moves the greatest tonnage; bottles gain share fastest as branded organic positioning penetrates mainstream grocery retail.
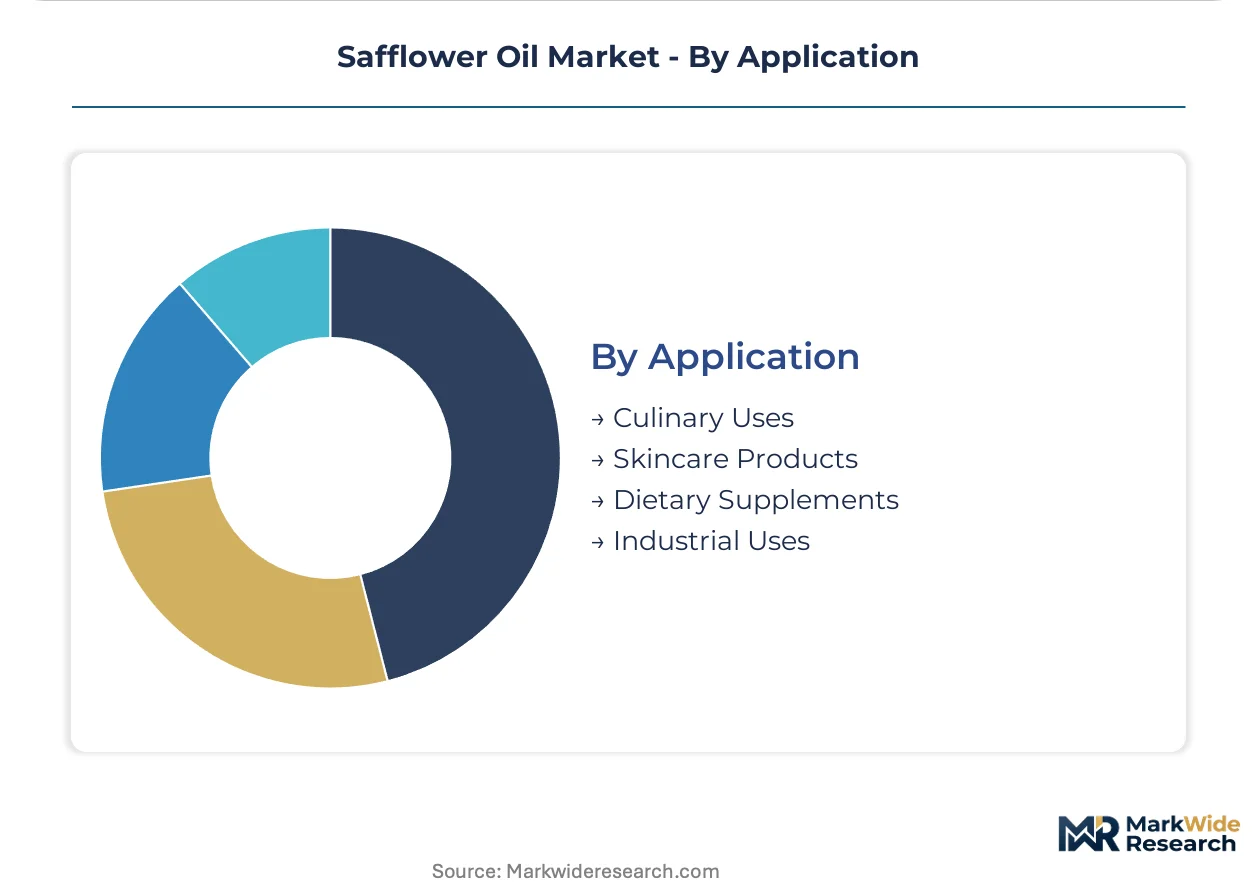
Application:
Functional performance requirements separate culinary smoke-point specifications from cosmetic emollient and pharmaceutical purity demands.
- Culinary Uses:High-oleic refined oil with neutral flavor profiles and smoke points exceeding 230°C supports clean-label frying in food-service and packaged food manufacturing. India's PLI scheme capacity buildout concentrates supply for this application in Maharashtra and Gujarat extraction clusters.
- Dietary Supplements:High-linoleic oil processed into softgel capsules delivering conjugated linoleic acid precursors for metabolic health positioning. FDA food facility registration creates dual compliance thresholds with USDA organic audits for American market access.
- Skincare Products:Pharmaceutical-grade cold-pressed oil with certified organic provenance serves European cosmetic formulators adopting extraction technology migration from artisanal to mid-cap commercial facilities.
- Industrial Uses:Technical-grade safflower oil in paint, varnish, and biodiesel applications competing with lower-cost vegetable oil substitutes.
Culinary applications absorb the dominant volume share; dietary supplements climb fastest as softgel manufacturers expand lipid sourcing portfolios beyond fish and flaxseed oils.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for edible oil processing is accelerating domestic crushing capacity expansion, redirecting refined oil flows toward Middle Eastern and Southeast Asian markets as EU compliance thresholds tighten.
India
Maharashtra and Gujarat solvent extraction clusters now supply bulk refined oil to pan-Asian food processors. FSSAI mandates on solvent residue limits and labeling disclosures shape refining investment priorities for domestic crushers. Farmer-producer organizations in these states secure offtake agreements with branded edible oil distributors ahead of crushing season.
United States
Softgel manufacturers source high-linoleic safflower oil for conjugated linoleic acid precursor applications in dietary supplement channels. FDA food facility registration creates dual compliance thresholds with USDA organic audits for natural products retailers. California and Pacific Northwest organic certification clusters anchor pharmaceutical-grade supply for cosmetic emollient formulations.
Germany
European cosmetic formulators adopt cold-press extraction systems to secure pharmaceutical-grade supply with certified organic provenance. ECHA REACH framework and EFSA novel food assessments govern import access for safflower oil entering cosmetic and supplement channels. Hamburg-based oleochemical specialists anchor backward integration into certified organic seed sourcing.
China
Technical-grade safflower oil competes in paint, varnish, and biodiesel applications against lower-cost vegetable oil substitutes. SAMR food safety standards and GB quality specifications regulate domestic refining infrastructure. Shandong Peninsula processing clusters concentrate solvent extraction capacity for industrial end uses.
United Arab Emirates
Gulf Cooperation Council markets absorb redirected Indian refined oil flows as European access constricts under deforestation-free due diligence rules. MOHAP food safety regulations govern import standards for edible oil distribution across Emirates. Dubai logistics hubs consolidate pan-regional procurement for Middle Eastern food-service applications.
Safflower Oil Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered margin pools. Consolidated branded distribution anchors volume throughput in food-service channels, while fragmented toll-refining specialists capture premium positioning in organic and pharmaceutical grades. Three archetypes dominate: integrated consumer brands with farmer-producer organization offtake networks, European oleochemical houses with backward integration into certified organic seed sourcing, and North American toll-refiners enabling mid-market brand entry without capital-intensive extraction assets. Capacity expansion and strategic partnerships represent the dominant competitive moves as players respond to PLI scheme incentives and shifting export market access.
Among India-based integrated consumer brands, Marico Ltd. exemplifies the channel-control archetype through branded edible oil distribution infrastructure. Henry Lamotte OILS GmbH occupies a position within the European pharmaceutical-grade specialist tier, representing backward integration into certified organic seed sourcing. Connoils LLC sits within the North American toll-refining service layer, enabling mid-sized brands to enter the safflower segment without extraction asset ownership.
| Leading Market Players |
|---|
| Connoils LLC |
| Adams Group Inc. |
| Marico Ltd. |
| Henry Lamotte OILS GmbH |
| Centra Foods Inc. |
| SunOpta Inc. |
| Oilseeds International Ltd. |
| Spectrum Organic Products LLC |
| Gustav Heess Oleochemische Erzeugnisse GmbH |
| Others |
Value Chain & Pricing Dynamics
Maharashtra and Gujarat solvent extraction clusters anchor upstream supply, concentrating margin capture in pan-Asian food processors with direct farmer-producer organization offtake agreements. Certification premiums for USDA organic and pharmaceutical-grade cold-pressed variants create divergent downstream value pools.
Pricing Analysis
Certification grade creates the primary spread between conventional refined oil and organic cold-pressed variants. Three-tier pricing structure across premium organic, standard refined, and economy conventional levels reflects FSSAI compliance investment and smoke-point performance specifications. Cost compression in standard refined tiers intensifies as palm and sunflower oil substitutes displace safflower in bulk institutional frying contracts. Price-sensitive Middle Eastern and Southeast Asian food-service buyers drive volume at economy tiers, while North American natural products retailers absorb premium organic positioning with minimal elasticity.
Supply Chain Analysis
EU deforestation-free supply chain due diligence rules restrict Indian and Chinese refined oil flows into European cosmetic and supplement channels. Geographic supply concentration centers on India, China, and select European oleochemical houses with backward integration into certified organic seed sourcing. Raw material dependencies rest on safflower seed availability competing with wheat and chickpea rotations in semi-arid cultivation zones, solvent extraction chemicals, and flexitank logistics infrastructure. Single-source vulnerability runs through Maharashtra-Gujarat crushing cluster dominance. Distribution runs through Dubai logistics hubs consolidating pan-regional procurement for Gulf Cooperation Council markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Palm and sunflower oil substitution threats demand active defense from incumbent safflower oil processors as clean-label positioning alone cannot sustain premium capture against lower-cost functional equivalents.
For Market Incumbents: Pre-empt displacement by locking multi-year offtake agreements with Maharashtra and Gujarat farmer-producer organizations ahead of crushing season, securing seed supply against rotation competition from food grains. Deepen backward integration into certified organic seed sourcing to defend pharmaceutical-grade margin pools against European oleochemical houses with captive crushing infrastructure. Channel control through branded edible oil distribution remains essential for food-service volume retention.
For New Entrants and Emerging Players: Mid-market toll-refining services for organic certification aspirants represent the most penetrable entry point, enabling brand owners to enter safflower segments without capital-intensive extraction assets. Target nutraceutical softgel manufacturers seeking high-linoleic oil diversification beyond fish and flaxseed alternatives. Go-to-market execution should emphasize FDA food facility registration support bundled with USDA organic audit navigation for American natural products retail channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian edible oil processors holding PLI scheme capacity expansion permits but lacking export market diversification beyond constricting European channels. Long-term viability hinges on successful pivot toward Middle Eastern and Gulf Cooperation Council market development. Watch for EU deforestation-free rule enforcement tightening as the signal indicating accelerated redirection of Indian export flows and corresponding infrastructure investment needs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Seed Sourcing | Captive supply chains anchor pharmaceutical-grade positioning for EFSA-governed European cosmetic channels. |
| Toll-Refining Service Expansion | Asset-light entry pathways enable mid-market brands to access safflower segments without crushing infrastructure. |
| Farmer-Producer Organization Offtake Agreements | Direct procurement locks seed supply ahead of crushing season against wheat and chickpea rotation competition. |
| Middle Eastern Export Market Development | Dubai logistics hubs consolidate pan-regional flows as EU due diligence rules constrict European access. |
| FDA Registration and Organic Certification Bundling | Dual compliance thresholds unlock North American natural products retail margin pools for dietary supplement channels. |
Study Parameters
Operator-level perspectives from crushing plant managers, procurement leads at pan-Asian food processors, cosmetic formulators, and softgel manufacturers anchored the qualitative base. Primary interviews with FSSAI compliance officers and EFSA regulatory affairs specialists cross-referenced with secondary validation from USDA organic certification databases, EU REACH registration filings, and India PLI scheme disclosure documents. Customs trade data on solvent extraction equipment imports and edible oil export flows provided volume calibration. Bottom-up seed production estimates and top-down end-use consumption models triangulated market sizing.
Scenario-bracketing around EU deforestation-free enforcement timing and PLI scheme capacity buildout pace shaped the analytical framework across the analysis window. Segmentation dimensions modeled included extraction method, certification grade, end-use purity requirements, packaging scale, and geographic regulatory cluster. CAGRs derived from weighted average of historical crush capacity expansion rates and projected clean-label frying adoption curves in food-service channels. Forecast inputs incorporated rotation competition elasticity for semi-arid cultivation zones and softgel manufacturer lipid sourcing diversification trends.
Practitioners should monitor EU supply chain due diligence rule implementation schedules and FSSAI solvent residue mandate enforcement intensity for early signals requiring forecast reassessment. Material shifts in safflower seed availability relative to wheat and chickpea planting economics, or abrupt European market access restrictions, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cocoa Bean Extract Market
Ingredients
Salad Oil Market
Ingredients
France Soy Protein Market
Ingredients
GCC Egg Powder Market
Ingredients
Commercial Flour Market
Ingredients
Yeast Derivatives Market
Ingredients
Europe BBQ Charcoal Market
Ingredients
Germany Protein Market
Ingredients
Europe Fats and Oil Market
Ingredients
North America Milk Protein Market
Ingredients
Proteose Peptone Market
Ingredients
Cottonseed Oil Market
Ingredients
Middle East Feed Palatability Enhancers Market
Ingredients
Potato Granules Market
Ingredients
North America Vegetable Oils Market
Ingredients
Shortening Powder Market