
 South America Spirulina Extract Market | 2026-2036
South America Spirulina Extract Market Size, Share, and Industry Trends Forecast 2026-2036
South America Spirulina Extract Market Analytics
Functional food manufacturers are redrawing ingredient sourcing priorities across South America. Cyanotech Corporation leverages its integrated cultivation and extraction infrastructure to secure long-term contracts with Brazilian nutraceutical brands. DIC Corporation anchors supply reliability through controlled-environment algae farms that reduce batch-to-batch phycocyanin variability. Sensient Technologies Corporation differentiates via color-stable spirulina formulations that withstand pasteurization in beverage applications.
Spirulina extract comprises concentrated phycocyanin pigments, proteins, and antioxidants derived from Arthrospira platensis biomass through aqueous extraction and spray-drying, yielding standardized color values between E6 and E18 for food-grade applications. The powder segment dominates manufacturing throughput due to its blending flexibility across bakery, dairy, and supplement matrices, while liquid extracts capture premium positioning in ready-to-drink functional beverages where solubility and visual stability command higher formulation fees. Nutraceutical applications lead volume offtake as protein-conscious consumers in urban Brazil and Colombia shift toward plant-derived micronutrient stacks, though cosmetics-grade extracts with enhanced radical-scavenging assays represent the fastest-expanding margin pool.
ANVISA governs novel food ingredient approvals and maximum contaminant thresholds for cyanobacterial products entering Brazilian commerce, while Argentina's national food regulator enforces Mercosur-aligned labeling standards that mandate phycocyanin concentration disclosures on supplement packaging. Brazil's Ministry of Agriculture (MAPA) oversees organic certification for algae cultivation facilities, creating compliance barriers for uncertified imports from non-Mercosur origins. Stakeholders must monitor pending harmonization of maximum heavy-metal limits across Mercosur member states, as divergent arsenic and lead thresholds currently fragment cross-border formulation strategies.
Market Dynamics
ANVISA's tightened novel food ingredient guidelines are forcing extractors to abandon variable phycocyanin batches in favor of standardized certification, compressing margins for uncertified suppliers while rewarding integrated producers with captive testing infrastructure.
Growth Catalysts
- Protein-fortified supplement demand:Urban Brazilian and Colombian consumers are pivoting toward plant-derived micronutrient stacks, expanding offtake volumes for spirulina powder in nutraceutical formulations.
- ANVISA standardization mandates:The regulator's push for certified phycocyanin content is accelerating consolidation among extractors with in-house analytical capabilities.
- São Paulo manufacturing cluster:Southeastern Brazil's health product hub anchors regional supply agreements, creating procurement density that reduces logistics costs for qualified suppliers.
Market Restraints
- Organic certification barriers:MAPA's oversight of algae cultivation facilities blocks uncertified imports from non-Mercosur origins, limiting supply source diversification.
- Heavy-metal threshold fragmentation:Divergent arsenic and lead limits across Mercosur member states force formulators to maintain multiple compliance protocols for cross-border distribution.
- Chlorella substitution pressure:Alternative microalgae proteins with comparable amino acid profiles threaten spirulina's positioning in cost-sensitive protein powder segments.
Strategic Opportunities
- Colombia's underpenetrated urban markets:Bogotá and Medellín health-conscious demographics show protein-conscious consumption patterns comparable to São Paulo's 2021 baseline.
- Mercosur regulatory harmonization:Pending alignment of maximum contaminant thresholds would eliminate cross-border formulation fragmentation for integrated producers.
- Cosmetics-grade radical-scavenging extracts:Enhanced antioxidant assay formulations command premium positioning in Brazilian dermocosmetic pipelines.
Industry Challenges
- Phycocyanin assay standardization:Batch-to-batch color value consistency between E6 and E18 grades demands capital-intensive spectrophotometric testing infrastructure that mid-scale extractors struggle to deploy.
- Aqueous extraction technician scarcity:Specialized biomass processing expertise concentrates among legacy operators in southern Brazil, constraining workforce expansion for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Spirulina Extract Market |
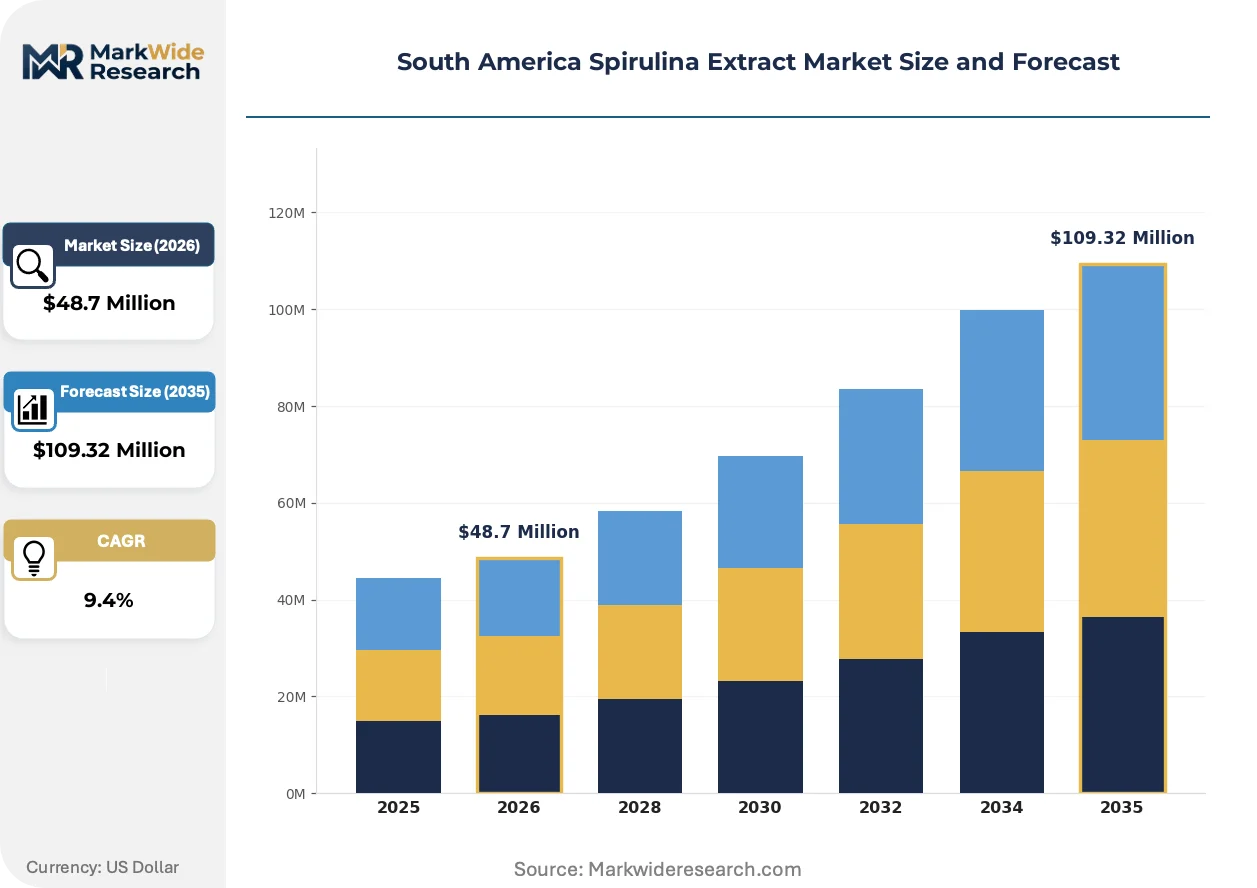
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $109.32 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Tablet, Capsule, Liquid Application: Food & Beverage, Nutraceuticals, Cosmetics, Animal Feed End User: Retail Consumers, Food Manufacturers, Fitness Centers, Laboratories Distribution Channel: Online, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Cyanotech Corporation, DIC Corporation, Parry Nutraceuticals, Earthrise Nutritionals, Sensient Technologies Corporation, NOW Foods, Algene Biotech, Döhler Group, Chr Hansen AS, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Spirulina Extract Market Evolving Landscape
Controlled-environment algae cultivation is compressing batch variability while regulatory disclosure mandates and beverage-grade solubility demands are reshaping extractor R&D priorities across the continent.
Spray-drying optimization with inline moisture sensors is decomposing the traditional post-harvest quality variance that previously required extensive reprocessing. Brazilian dairy and beverage formulators are adopting these systems at accelerated procurement cycles. The technology is decomposing cost structures for mid-tier extractors lacking captive drying infrastructure.
ANVISA's phycocyanin concentration disclosure requirements on supplement packaging are forcing label redesigns and third-party assay investments. The mandate compresses time-to-market for new product introductions. Powder segment manufacturers in São Paulo state are responding by integrating in-house HPLC testing to bypass external laboratory bottlenecks.
Direct procurement from certified cultivation facilities is displacing layered distributor networks in Brazilian nutraceutical supply chains. São Paulo-based formulators are contracting directly with MAPA-certified algae farms to secure traceability documentation. This pattern is most visible in southeastern Brazil's protein supplement manufacturing corridor.
South America Spirulina Extract Market Segmentation
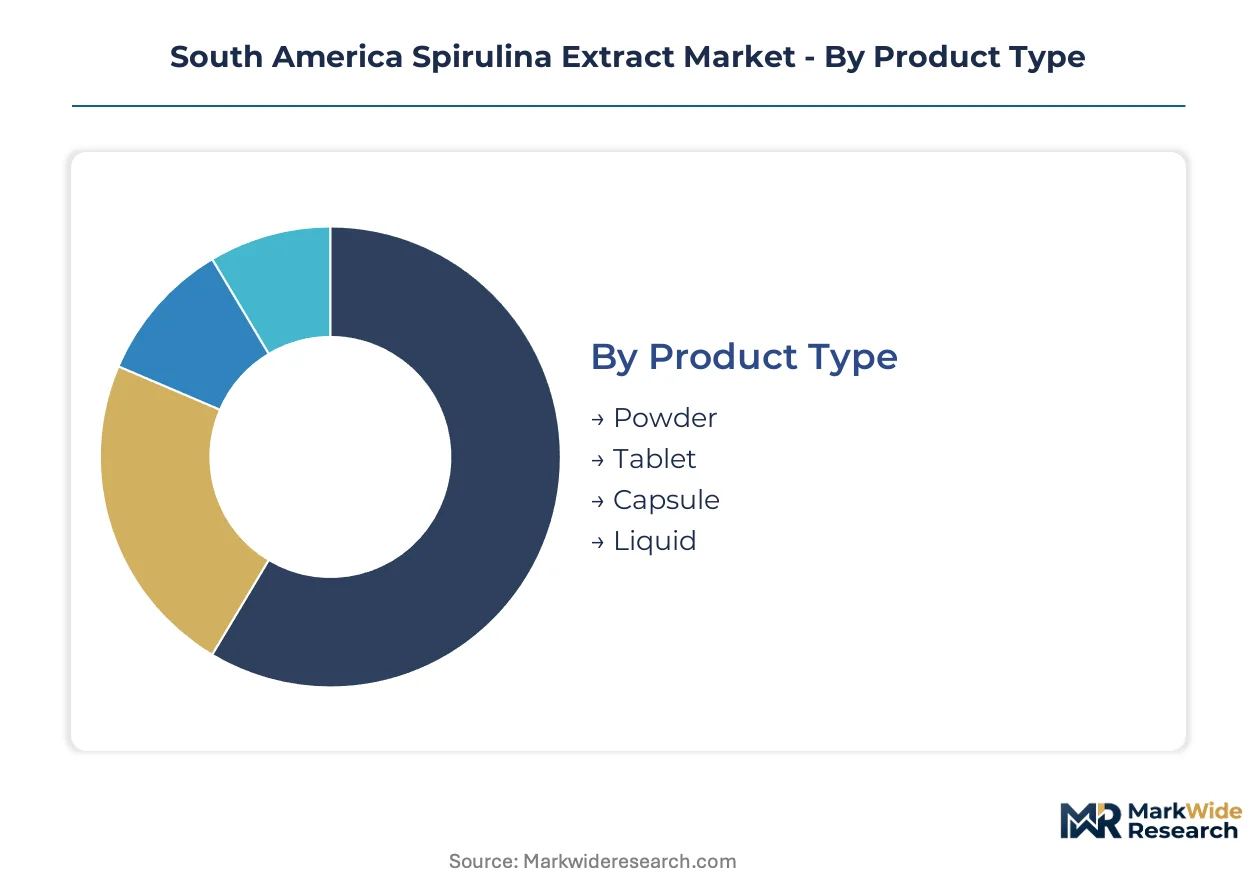
Spirulina extract segmentation in South America reflects divergent margin capture across formulation complexity and regulatory compliance tiers. Procurement patterns concentrate where ANVISA certification requirements intersect with manufacturing infrastructure density.
Product Type:
Premium margin pools concentrate in standardized phycocyanin concentrates and pasteurization-stable liquid formats, while commodity powder segments compete on blending flexibility and volume throughput.
- Powder:Spray-dried aqueous extracts yielding standardized color values between E6 and E18 dominate manufacturing throughput due to blending flexibility across bakery, dairy, and supplement matrices. São Paulo's health product manufacturing cluster anchors regional supply agreements for this segment, with ANVISA's tightened novel food ingredient guidelines pushing extractors toward standardized phycocyanin content certification.
- Liquid:Solubility-optimized extracts command premium positioning in ready-to-drink functional beverages where visual stability and pasteurization resistance justify higher formulation fees. Colombian urban markets in Bogotá and Medellín show accelerating procurement cycles for beverage-grade liquid spirulina as protein-conscious consumers shift toward plant-derived micronutrient stacks.
- Tablet:Compressed formulations target retail consumer convenience in fitness and travel segments, with dosing standardization simplifying ANVISA compliance documentation.
- Capsule:Gelatin and vegetable-shell encapsulations serve supplement manufacturers seeking precise unit-dose phycocyanin delivery for nutraceutical pipelines.
Powder holds installed capacity. Liquid is rotating up the share rankings.
Application:
Volume concentration diverges sharply between mass-market food fortification and high-assay cosmetic formulations, with nutraceutical applications occupying the intermediate revenue tier.
- Nutraceuticals:Protein-fortified supplements lead volume offtake as urban Brazilian and Colombian consumers pivot toward plant-derived micronutrient stacks. Direct procurement from MAPA-certified algae farms is displacing layered distributor networks in Brazilian nutraceutical supply chains, with São Paulo-based formulators contracting for traceability documentation.
- Cosmetics:Enhanced radical-scavenging assay formulations represent the steepest expansion trajectory in Brazilian dermocosmetic pipelines, commanding premium positioning through antioxidant concentration certification.
- Food & Beverage:Bakery and dairy matrices absorb standardized E-grade powders, with pasteurization-stable formulations gaining formulation share in beverage applications.
- Animal Feed:Aquaculture and poultry fortification applications source lower-assay spirulina meals, with Mercosur organic certification requirements limiting import source diversification.
Nutraceuticals anchor current revenue. Cosmetics is climbing the fastest.
End User:
Procurement scale and technical specification intensity separate institutional buyers from retail channels, with manufacturing clusters dictating geographic demand concentration.
- Food Manufacturers:São Paulo's southeastern Brazil manufacturing corridor drives bulk powder procurement for protein-fortified product lines, with in-house HPLC testing investments accelerating to bypass external laboratory bottlenecks under ANVISA disclosure mandates.
- Retail Consumers:Health-conscious demographics in urban Brazil and Colombia source finished supplements through pharmacies and health stores, with phycocyanin concentration labeling influencing purchase decisions.
- Fitness Centers:Protein supplement dispensing points in Brazilian metropolitan areas stock tablet and powder formats for on-site consumption.
- Laboratories:Research and quality control facilities procure reference-grade spirulina for assay calibration and novel formulation development.
Food manufacturers command volume scale. Retail consumers are gaining share fastest.
Distribution Channel:
Channel economics reflect traceability requirements and certification documentation burdens, with direct procurement patterns reshaping traditional wholesale structures.
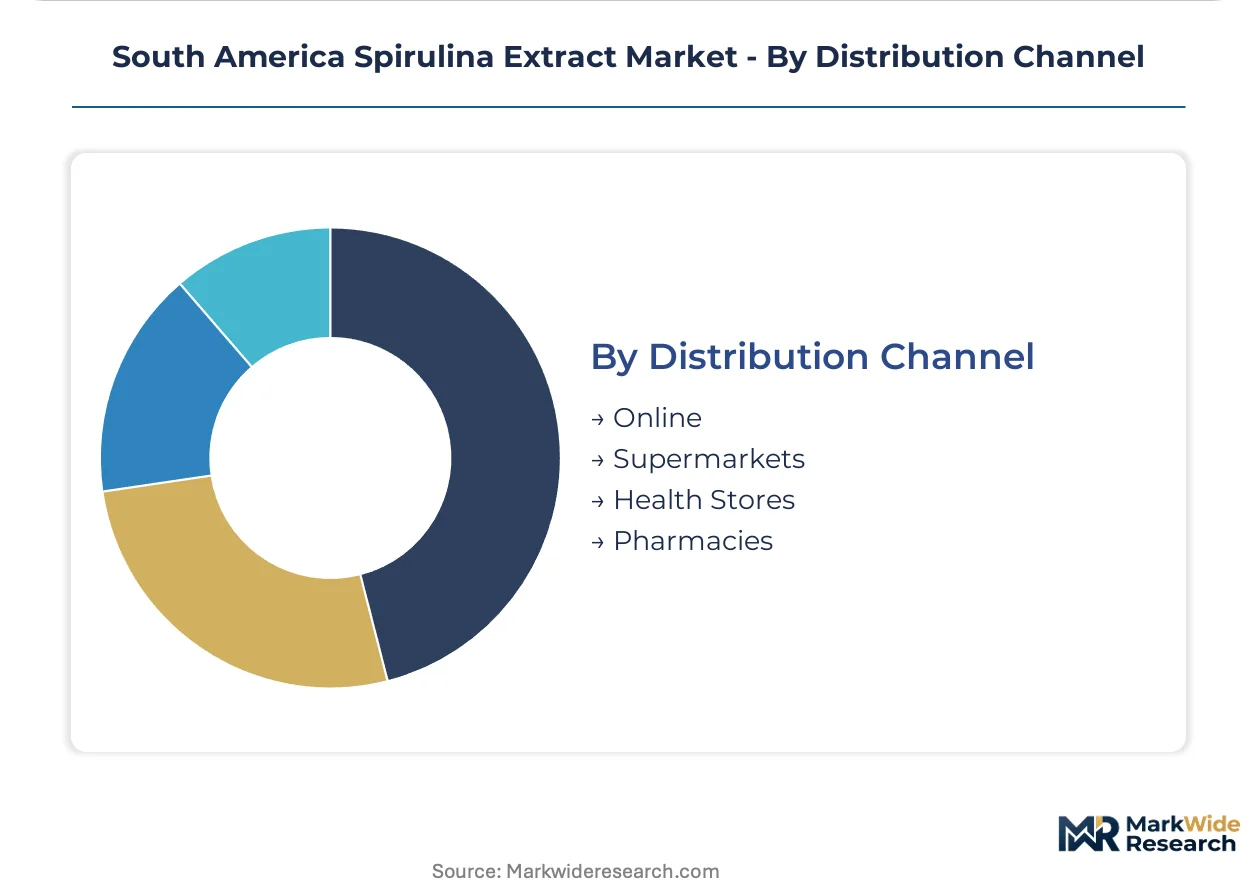
- Online:E-commerce platforms capture urban Brazilian and Colombian consumer segments seeking transparent phycocyanin concentration disclosures and MAPA-certified origin documentation, with São Paulo-based distributors investing in digital traceability interfaces.
- Health Stores:Specialized retailers in southeastern Brazil concentrate premium supplement assortments, with staff technical knowledge influencing spirulina format recommendations.
- Supermarkets:Mass-market food and beverage spirulina fortifications distribute through Brazilian retail chains, with private-label protein products expanding shelf presence.
- Pharmacies:Regulated channel positioning supports premium pricing for certified nutraceutical spirulina, with ANVISA compliance documentation visible at point of sale.
Health stores hold established positioning. Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports spirulina extract to Colombian nutraceutical formulators through Mercosur trade corridors, while Argentine biomass processors supply phycocyanin concentrates to Chilean dermocosmetic manufacturers.
Brazil
Protein-fortified supplement manufacturers in São Paulo state drive continental demand density. ANVISA's tightened novel food ingredient guidelines force extractors toward standardized phycocyanin certification. The southeastern health product manufacturing cluster anchors regional supply agreements with MAPA-certified algae farms.
Colombia
Bogotá and Medellín urban consumers exhibit protein-conscious consumption patterns comparable to São Paulo's baseline. The national food regulator enforces Mercosur-aligned labeling standards mandating phycocyanin concentration disclosures. Direct procurement from Brazilian cultivation facilities is displacing layered distributor networks in Andean nutraceutical supply chains.
Argentina
Cosmetics-grade radical-scavenging extracts command premium positioning in Buenos Aires dermocosmetic pipelines. The country's national food regulator enforces Mercosur-aligned standards that fragment cross-border formulation strategies. Algae cultivation facilities in Córdoba province pursue MAPA-equivalent organic certification to access Brazilian export channels.
Chile
Pasteurization-stable liquid spirulina formulations gain share in Santiago's ready-to-drink functional beverage sector. The national pharmaceutical regulator oversees novel food ingredient safety assessments for cyanobacterial products. Valparaíso's logistics infrastructure supports import-dependent formulators sourcing certified extracts from Mercosur origins.
Peru
Traditional medicine channels in Lima absorb lower-assay spirulina powders for indigenous wellness product lines. The country's national food safety agency applies evolving standards for microalgae-derived supplements. Andean highland cultivation pilots test altitude-adapted Arthrospira strains for regional biomass independence.
South America Spirulina Extract Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and captive cultivation control. The vendor base concentrates around integrated producers with in-house phycocyanin assay capabilities and mid-scale extractors dependent on third-party testing. Three archetypes dominate: multinational nutraceutical ingredient platforms, Japanese algae biotechnology conglomerates, and regional South American cultivation specialists. Competitive moves center on backward integration into controlled-environment algae farms and strategic partnerships with ANVISA-compliant testing laboratories.
Within the multinational platform tier, Cyanotech Corporation and Sensient Technologies Corporation exemplify integrated cultivation-extraction positioning. DIC Corporation anchors the Japanese biotechnology conglomerate archetype with controlled-environment production systems. These three entities represent contrasting approaches to batch-to-batch phycocyanin standardization that ANVISA mandates now privilege.
| Leading Market Players |
|---|
| Cyanotech Corporation |
| DIC Corporation |
| Parry Nutraceuticals |
| Earthrise Nutritionals |
| Sensient Technologies Corporation |
| NOW Foods |
| Algene Biotech |
| Döhler Group |
| Chr Hansen AS |
| Others |
Value Network & Pricing Analysis
Liquid extract substitution for powder formats in Colombian beverage applications is redrawing procurement geography toward São Paulo's certified extraction facilities while compressing margin structures for mid-tier powder suppliers lacking pasteurization-stable formulations. ANVISA's phycocyanin disclosure mandates simultaneously elevate testing costs and reward integrated producers with captive assay infrastructure.
Pricing Analysis
Spray-drying infrastructure generation gaps separate pricing tiers: legacy batch-dried powders trade at commodity benchmarks while inline moisture-sensor equipped facilities command formulation premiums. Three-tier pricing structure across premium, standard, and economy levels reflects E-grade certification intensity and MAPA organic traceability. Cost compression in standard-grade powder runs through distributor network displacement as São Paulo formulators source directly from certified algae farms. Retail consumers in health stores show highest price sensitivity; cosmetics-grade extract buyers exhibit lowest elasticity due to radical-scavenging assay requirements.
Supply Chain Analysis
MAPA certification chokepoints at southeastern Brazilian cultivation facilities filter cross-border supply access for Argentine and Colombian formulators seeking Mercosur-origin documentation. Biomass supply draws from São Paulo state algae farms, Córdoba province cultivation pilots, and emerging Peruvian highland operations. Phycocyanin assay reagents, spray-drying equipment, and gelatin encapsulation materials constitute critical input dependencies. Single-source vulnerability concentrates in spectrophotometric testing infrastructure controlled by legacy southern Brazilian operators. Distribution runs through direct procurement contracts displacing layered wholesale networks in nutraceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized aqueous extraction technician scarcity in southern Brazil constrains capacity expansion for new entrants while entrenching incumbents with legacy workforce pipelines. Spectrophotometric testing infrastructure gaps fragment quality assurance capabilities across mid-scale extractors.
For Market Incumbents: Fortify backward integration into controlled-environment algae cultivation to secure MAPA organic certification and reduce batch-to-batch phycocyanin variability. Expand in-house HPLC testing capacity to bypass external laboratory bottlenecks under ANVISA disclosure mandates. Lock in long-term supply agreements with São Paulo manufacturing clusters before Colombian market penetration accelerates. For New Entrants and Emerging Players: Differentiate on cosmetics-grade radical-scavenging assay capabilities where premium positioning remains undercontested by commodity powder specialists. Target Bogotá and Medellín beverage-grade liquid extract demand as the most penetrable white-space segment. Pursue direct e-commerce distribution with transparent phycocyanin concentration documentation to bypass established wholesale barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated producers with captive cultivation and testing infrastructure over distributor-dependent mid-scale extractors. Long-term viability hinges on regulatory compliance scalability across Mercosur harmonization scenarios. Acquisition targets should demonstrate MAPA certification, ANVISA-compliant assay capabilities, and established São Paulo manufacturing cluster relationships. Monitor pending arsenic and lead threshold alignment as the critical inflection signal for cross-border formulation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled-Environment Cultivation | MAPA organic certification secures traceability documentation for São Paulo manufacturing cluster contracts. |
| In-House HPLC Testing Infrastructure Deployment | ANVISA phycocyanin disclosure mandates compress time-to-market for certified extract introductions. |
| Cosmetics-Grade Radical-Scavenging Formulation Development | Buenos Aires dermocosmetic pipelines command premium positioning for enhanced antioxidant assay extracts. |
| Direct E-Commerce Distribution Launch | Bogotá and Medellín urban consumers seek transparent phycocyanin concentration documentation. |
| Mercosur Regulatory Harmonization Advocacy | Aligned heavy-metal thresholds would eliminate cross-border formulation fragmentation for integrated producers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with nutraceutical formulation executives, MAPA-certified algae farm operators, ANVISA regulatory affairs specialists, and São Paulo manufacturing cluster procurement directors. Secondary validation incorporated ANVISA novel food ingredient filings, MAPA organic certification registries, Mercosur trade corridor customs data, and Brazilian health product manufacturing association reports. Bottom-up volume estimates from cultivation facility outputs were triangulated against top-down nutraceutical formulation demand projections.
Across the analysis window, the forecasting framework modeled spirulina extract demand through product type segmentation, application tier stratification, and end-user procurement scale differentiation. CAGRs were derived from trajectory analysis of phycocyanin-certified extract volumes and cosmetics-grade assay formulation adoption curves. Industry-specific inputs included ANVISA compliance cost burdens, spray-drying technology penetration rates, and direct procurement displacement patterns in southeastern Brazilian supply chains.
Decision-makers should treat outputs as directional under sustained ANVISA standardization enforcement and Mercosur trade corridor stability; material deviation in regulatory harmonization timelines or chlorella substitution acceleration would warrant model refresh. Practitioners should keep alternative scenarios live as heavy-metal threshold alignment negotiations and Colombian market penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Almond Flour Market
Ingredients
United States Wheat Protein Market
Ingredients
Xylooligosaccharide Market
Ingredients
African Brewing Enzymes Market
Ingredients
Europe Insoluble Dietary Fibers Market
Ingredients
Cocoa Beans Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
European Brewing Enzymes Market
Ingredients
Middle East and Africa Dairy Protein Ingredients Market
Ingredients
South America Agar Market
Ingredients
United States Soy Protein Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Konjac Root Fiber Market
Ingredients
Amaranth Seed Oil Market
Ingredients
Egg Yolk Lecithin Market