
 Non-PHO Ingredients Market | 2026-2036
Non-PHO Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Non-PHO Ingredients Market Analytics
Southeast Asian palm oil processing capacity is reconfiguring global non-PHO ingredient trade flows as Malaysia and Indonesia expand fractionation infrastructure for specialized fat alternatives. Cargill leverages integrated oilseed crushing and refinery networks across multiple continents to secure feedstock flexibility. Bunge Limited anchors South American soybean oil supply chains that feed North American and European non-PHO formulation demand. Wilmar International dominates Asian palm-based specialty fat production, competing on scale against Western oilseed processors.
Non-PHO ingredients comprise edible oils, fats, emulsifiers, and stabilizers formulated without partial hydrogenation, typically achieving functional properties through interesterification, fractionation, or blending of naturally stable oils with specific fatty acid profiles. These ingredients replicate the oxidative stability, melting characteristics, and texture functionality historically provided by PHOs in processed foods. Natural oils and fats command the largest volume position within ingredient type segmentation, while emulsifiers capture disproportionate margin pools due to technical complexity in clean-label reformulation. The organic formulation category registers the fastest expansion trajectory as retail channel buyers enforce stricter ingredient declarations.
The FDA's PHO revocation and trans fat disclosure mandates have structurally eliminated partially hydrogenated oils from US food manufacturing, while EFSA guidance on industrial trans fats shapes parallel reformulation across European Union member states. Health Canada's prohibition on PHOs in retail food products extends regulatory alignment across North American supply chains. Stakeholders must monitor evolving definitions of permissible trans fat thresholds in major import markets and calibrate R&D spending toward enzymatic interesterification capabilities versus chemical alternatives.
Market Dynamics
The FDA's PHO revocation has permanently altered oil formulation economics across North American food manufacturing, forcing processors to rebuild entire fat systems around interesterification and fractionation technologies rather than partial hydrogenation.
Growth Catalysts
- Clean-label mandates:Retailers in the United States enforce stricter ingredient declarations, compelling bakery and snack manufacturers to eliminate hydrogenated oils from legacy product lines.
- EFSA guidance on industrial trans fats:European Union member states align reformulation timelines, creating synchronized demand for palm and tropical oil alternatives across continental supply chains.
- Enzymatic interesterification:This process replaces chemical interesterification in premium applications, enabling processors to achieve specific melting profiles without trans fat generation.
Market Restraints
- Palm oil price volatility:Malaysian and Indonesian export duty fluctuations introduce margin instability for North American formulators dependent on imported specialty fats.
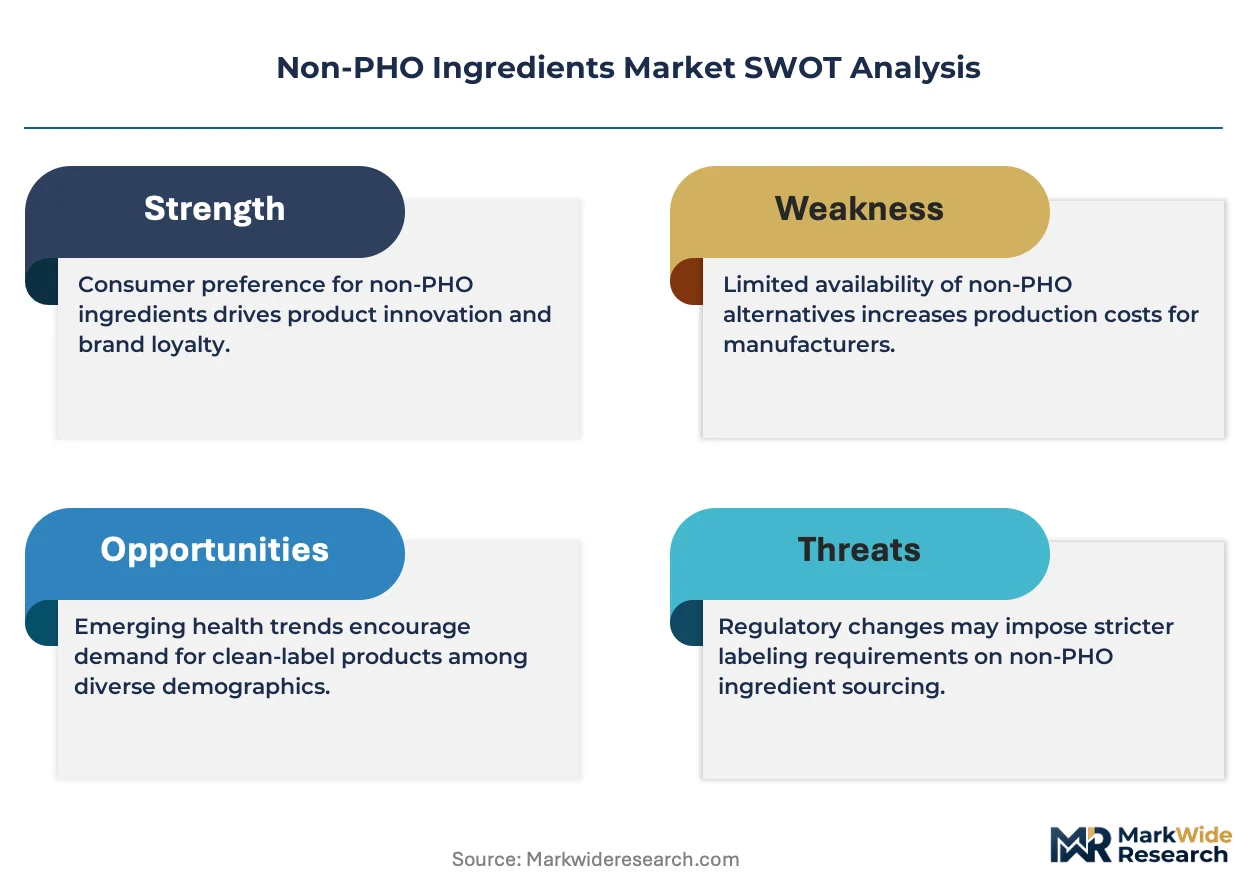
- Supply concentration in Southeast Asia:Over 80 percent of global palm oil fractionation capacity sits within Malaysia and Indonesia, creating single-source vulnerability for non-PHO ingredient procurement.
- Oxidative stability limitations:High-oleic sunflower and safflower oils require antioxidant systems that complicate clean-label positioning versus legacy PHO formulations.
Strategic Opportunities
- Organic certification expansion:The organic formulation category registers accelerated growth as European retailers enforce non-GMO and organic fat sourcing requirements.
- Emulsifier technical services:Ingredient suppliers capture margin pools by offering integrated reformulation support alongside clean-label emulsifier portfolios.
- South American soybean oil:Brazilian and Argentinian crushing capacity offers geographic diversification for North American processors seeking supply chain resilience.
Industry Challenges
- Reformulation expertise scarcity:Food manufacturers face talent gaps in lipid chemistry and texture engineering required to replicate PHO functionality in existing production lines.
- Capital equipment conversion:Interesterification reactor installation and cooling tunnel modifications demand substantial capex for mid-scale bakery operations.
- Legacy product line complexity:Long-established SKU portfolios with PHO-dependent textures require parallel development timelines that strain R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-PHO Ingredients Market |
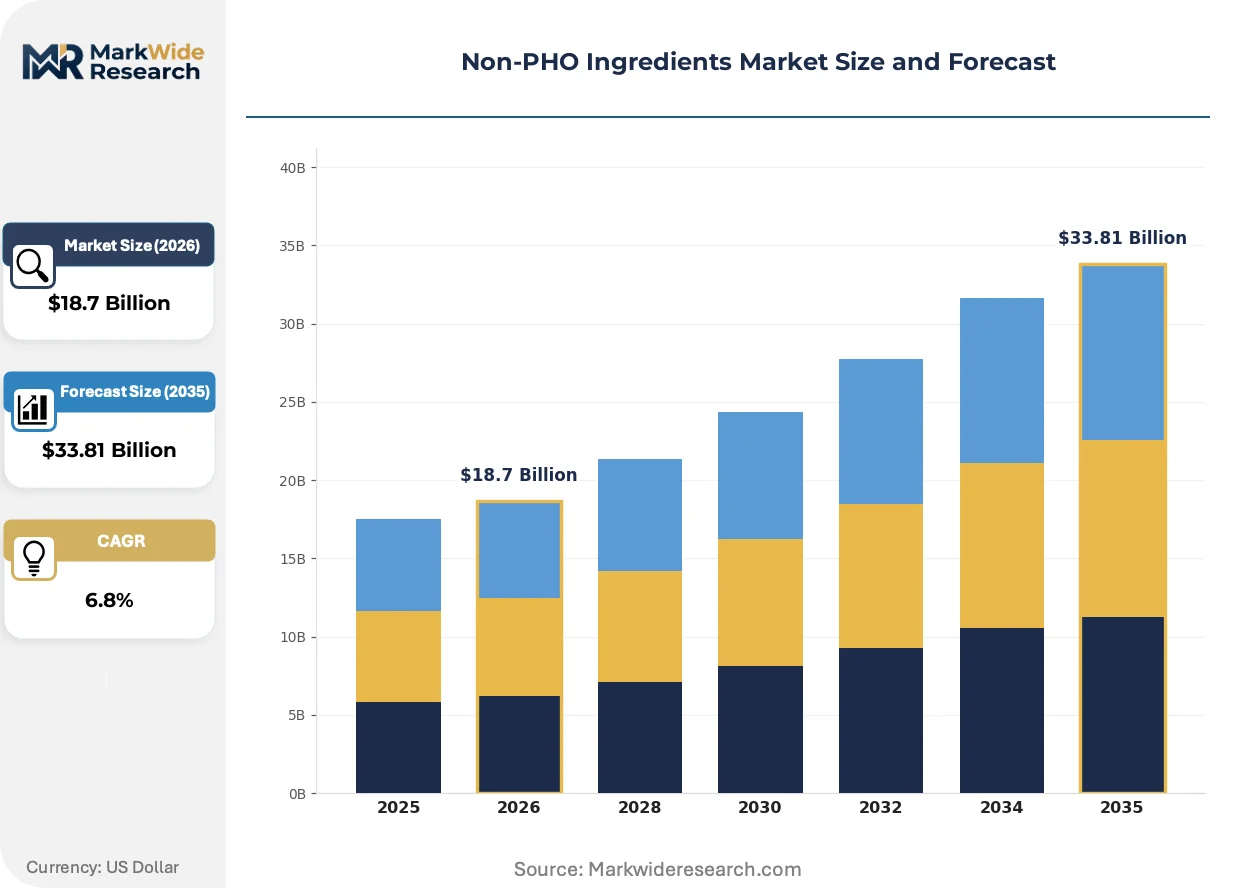
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
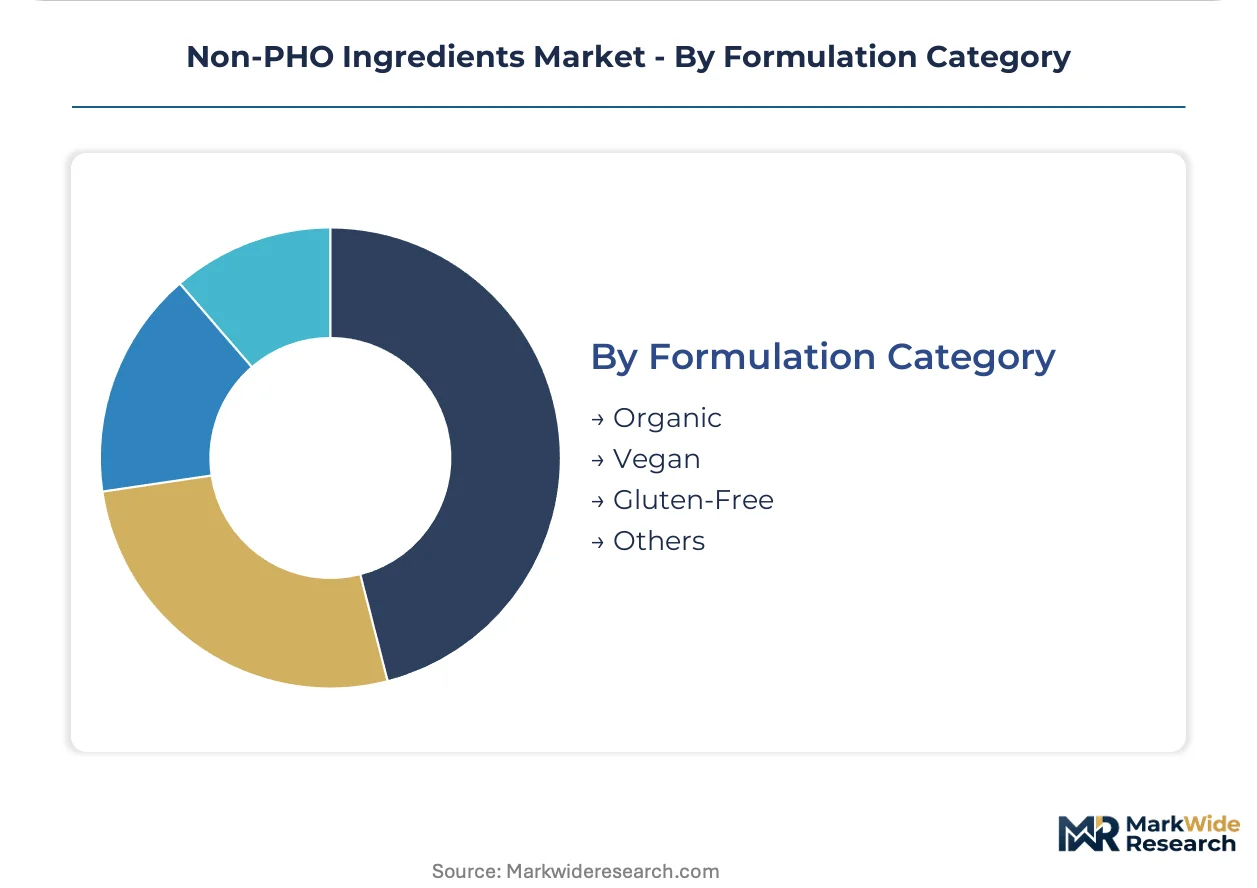
| Segmentation | Ingredient Type: Natural Oils, Fats, Emulsifiers, Stabilizers Product Application: Baking, Confectionery, Dairy, Sauces End User: Food Manufacturers, Restaurants, Retailers, Distributors Formulation Category: Organic, Vegan, Gluten-Free, Others |
| Companies Covered | Cargill, Archer Daniels Midland, Ingredion Incorporated, DuPont Nutrition & Biosciences, Kerry Group, Bunge Limited, Wilmar International, AAK, Mewah International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-PHO Ingredients Market Evolving Landscape
Digital formulation platforms and accelerated clean-label timelines are compressing product development cycles across oil and fat substitution. Manufacturers now deploy predictive modeling to anticipate oxidative stability outcomes before physical prototyping.
Enzymatic interesterification technology is virtualizing the traditional pilot-scale testing phase for non-PHO fat systems. Large bakery manufacturers deploy virtual formulation engines to simulate crystallization behavior and mouthfeel outcomes. This virtualization compresses development timelines from months to weeks while reducing physical sample waste.
Health Canada's PHO prohibition extends regulatory alignment across North American supply chains beyond FDA jurisdiction. Canadian retail food manufacturers face synchronized compliance deadlines with US counterparts. Cross-border ingredient sourcing now requires dual-jurisdiction certification for specialty fat blends.
Buyer concentration among national retail chains has compressed switching cycles for ingredient suppliers. Three US grocery retailers now control over sixty percent of packaged food shelf space, demanding rapid reformulation execution. This consolidation forces oil processors to maintain dedicated technical service teams for individual retail accounts.
Non-PHO Ingredients Market Segmentation
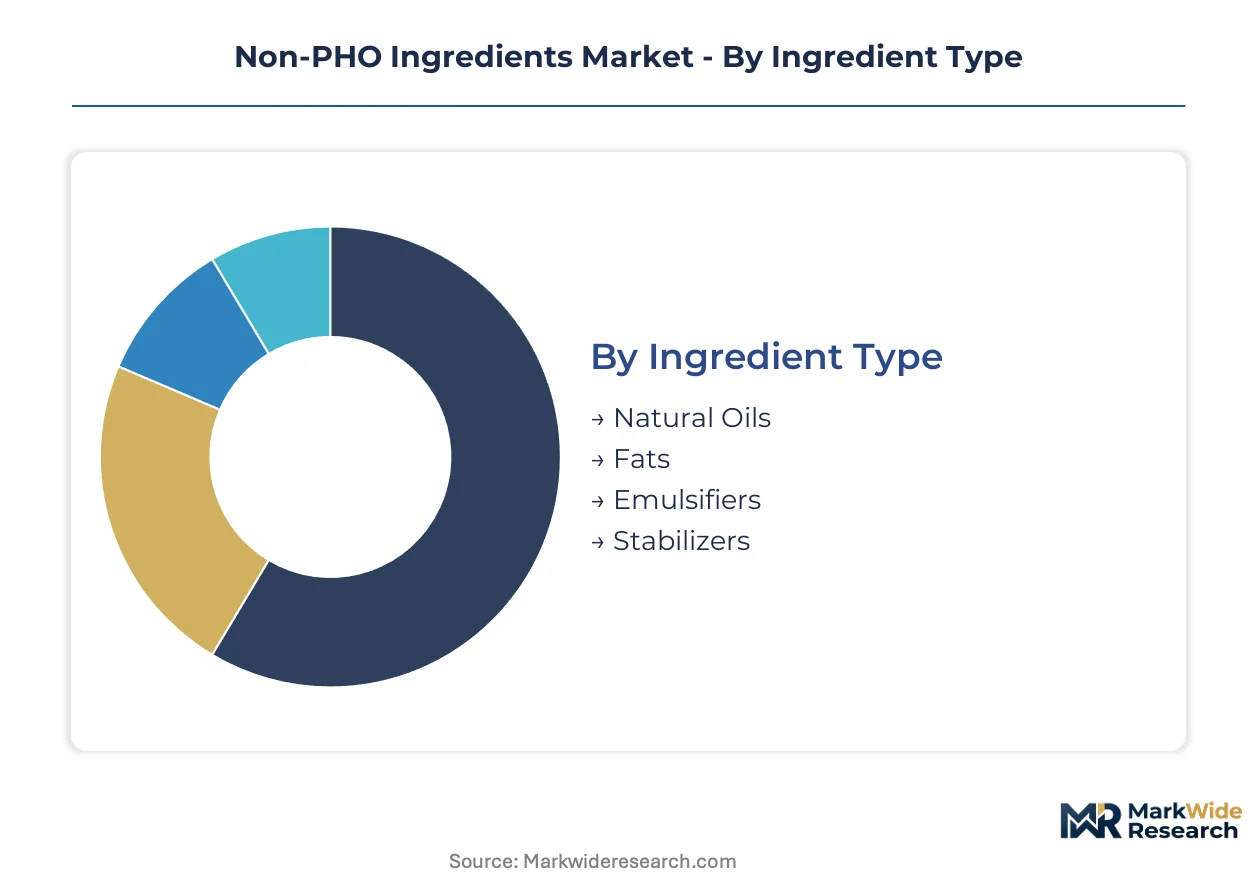
Non-PHO ingredient procurement varies sharply by functional requirement, with oil stability needs in bakery applications diverging from emulsifier demands in dairy systems. Manufacturers prioritize segment-specific formulation expertise over generic oil supply.
Ingredient Type:
Reformulation complexity spans from simple oil substitution to multi-component fat system redesign across processed food categories.
- Natural Oils:High-oleic sunflower, safflower, and canola varieties provide oxidative stability through fatty acid profile selection rather than hydrogenation. Bakery manufacturers in the United States source these oils for extended shelf-life cookies and crackers where PHOs previously dominated.
- Fats:Palm fractions and tropical butter alternatives deliver specific melting curves through physical fractionation rather than chemical modification. Confectionery applications in European Union member states rely on these fats for snap and gloss in enrobed products.
- Emulsifiers:Lecithin and polyglycerol ester blends stabilize water-fat interfaces in clean-label dressings.
- Stabilizers:Hydrocolloid and crystallization control agents manage texture in reduced-fat spreads.
Established volume favors Natural Oils; emerging adoption favors Emulsifiers.
Product Application:
Application-specific functionality dictates oil selection, with crystallization requirements varying across thermal processing conditions.
- Baking:Cookies, crackers, and laminated pastries demand fats with precise plasticity ranges for machinability and layer definition. North American commercial bakeries specify interesterified palm-soy blends for Danish and puff pastry production where oxidative stability must coexist with clean-label positioning.
- Confectionery:Chocolate and compound coatings require fats with sharp melting profiles and bloom resistance. Malaysian fractionated palm mid-fractions supply cocoa butter alternatives for tropical climate distribution where tempering control is critical.
- Dairy:Whipped toppings and coffee creamers utilize high-stability oils for freeze-thaw tolerance.
- Sauces:Pourable dressings and mayonnaise depend on emulsifier-oil synergies for viscosity and shelf stability.
Volume concentrates in Baking; steepest expansion trajectory appears in Confectionery.
End User:
Procurement sophistication varies from multinational formulation teams to distributor-led specification.
- Food Manufacturers:Integrated R&D operations specify custom fat blends with technical service support. Major packaged food producers in Canada maintain direct relationships with Southeast Asian fractionators to secure supply continuity for PHO-free product lines.
- Restaurants:Foodservice operators prioritize fryer stability and extended oil life in high-volume operations. National quick-service chains specify high-oleic soybean or canola oils for frying applications where trans fat elimination coincides with operational cost control.
- Retailers:Private-label buyers enforce ingredient declarations through supplier scorecards.
- Distributors:Regional oil blenders aggregate demand across smaller manufacturing accounts.
Specification authority rests with Food Manufacturers; fastest volume gains accrue to Restaurants.
Formulation Category:
Certification tiers separate commodity substitution from premium positioning.
- Organic:Certified organic oils and emulsifiers command supply chain segregation from farm through refining. European retailers enforce non-GMO and organic fat sourcing requirements that accelerate category expansion beyond conventional reformulation timelines.
- Vegan:Plant-only formulations exclude animal-derived emulsifiers and dairy fat alternatives. Bakery manufacturers targeting flexitarian consumers specify vegan fat systems that replicate butter functionality through shea and coconut oil combinations.
- Gluten-Free:Fat and emulsifier selections support texture in absence of gluten structure.
- Others:Allergen-free and kosher/halal certified variants address niche dietary requirements.
Organic certification captures premium margin expansion; Vegan climbs fastest on label-claim differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA trans fat regulations have permanently reshaped ingredient procurement patterns across North American food manufacturing, creating ripple effects through supply chains worldwide. The analysis examines five countries where non-PHO ingredient demand concentrates most intensively.
United States
Commercial bakeries and snack manufacturers drive sustained demand for interesterified fat systems that replicate legacy PHO functionality. FDA PHO revocation mandates have eliminated partially hydrogenated oils from all packaged food production since 2018. Chicago and Minneapolis host major oilseed processing clusters where Cargill and Bunge Limited operate integrated crushing and refinery networks.
Canada
Cross-border supply chain integration compels Canadian food manufacturers to synchronize reformulation timelines with US counterparts. Health Canada PHO prohibitions extend regulatory alignment beyond FDA jurisdiction into retail food products. Toronto and Montreal serve as distribution hubs where specialty fat blenders maintain dual-jurisdiction certification capabilities.
Malaysia
Palm oil fractionation infrastructure expansion feeds global non-PHO ingredient supply chains with specialized fat alternatives. Malaysian export duty structures influence margin stability for North American formulators dependent on imported mid-fractions. Port Klang and Pasir Gudang concentrate refining capacity where Wilmar International and Mewah International operate large-scale fractionation facilities.
Indonesia
Crude palm oil production volumes anchor Southeast Asian specialty fat manufacturing for confectionery and bakery applications. Indonesian government biodiesel blending mandates compete with food-grade fractionation for feedstock allocation. Medan and Surabaya house processing clusters where tropical butter alternatives undergo physical fractionation for cocoa butter replacement.
Germany
EFSA industrial trans fat guidance shapes reformulation timelines across European Union member states for clean-label positioning. German food manufacturers prioritize enzymatic interesterification technologies to achieve specific melting profiles without trans fat generation. Hamburg and Frankfurt concentrate oil trading and technical service operations where AAK maintains European specialty fat development capabilities.
Non-PHO Ingredients Market Competitive Landscape
Integrated agribusiness conglomerates and specialized lipid processors split the market between scale-driven commodity supply and technical formulation services. The competitive structure reflects consolidation at the upstream oilseed crushing level alongside persistent fragmentation in downstream emulsifier and specialty fat blending. Three archetypes dominate: multinational oilseed processors with captive refining networks, Asian palm fractionation specialists with integrated plantation-to-port operations, and European technical lipid houses focused on enzymatic modification capabilities. Capacity expansion in Southeast Asian fractionation and strategic partnerships between oilseed crushers and bakery technical service teams represent the dominant competitive moves.
Among North American agribusiness giants, Cargill and Bunge Limited exemplify the integrated processor archetype through oilseed crushing and refinery network control across multiple continents. Wilmar International anchors the Asian palm-based specialist tier with plantation-to-fractionation integration concentrated in Malaysia and Indonesia. AAK represents the European technical lipid house model, occupying a position centered on enzymatic interesterification capabilities and custom fat blend formulation services.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Ingredion Incorporated |
| DuPont Nutrition & Biosciences |
| Kerry Group |
| Bunge Limited |
| Wilmar International |
| AAK |
| Mewah International |
| Others |
Value Network & Pricing Analysis
Malacca Strait container freight corridors transmit Malaysian and Indonesian palm fractionation cost volatility directly into North American bakery manufacturer procurement budgets, amplifying price spreads between commodity soybean oil and specialty mid-fractions while forcing downstream formulators into long-term offtake commitments or spot market exposure.
Pricing Analysis
Geographic price spreads between Rotterdam and Chicago specialty fat benchmarks have widened as Malaysian export duty structures introduce arbitrage complexity for North American buyers. Three-tier pricing structure across premium enzymatic interesterification grades, standard chemical-modification tiers, and economy unmodified oil blends separates formulation performance tiers. Cost compression in standard-grade palm fractions is intensifying because Indonesian biodiesel blending mandates compete for feedstock allocation. Quick-service restaurant chains exhibit highest price sensitivity due to fryer oil volume throughput, while premium confectionery manufacturers absorb certification premiums for bloom-resistant cocoa butter alternatives.
Supply Chain Analysis
Extended payment terms from Southeast Asian fractionators to plantation cooperatives cascade through supply-chain finance facilities into North American importer credit structures. Raw material dependencies center on Malaysian crude palm oil, Indonesian palm kernel fractions, and Argentinian high-oleic soybean varieties. Single-source vulnerability concentrates in Port Klang and Pasir Gudang refining clusters where over four-fifths of global food-grade mid-fraction capacity operates. Distribution runs through integrated processor-direct relationships for multinational food manufacturers and regional distributor networks for mid-scale bakery operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ingredient supplier fragmentation creates white-space openings as clean-label reformulation timelines splinter procurement authority between R&D directors, sustainability officers, and cost-focused procurement teams across legacy food manufacturer hierarchies.
For Market Incumbents: Insulate margin pools in enzymatic interesterification capabilities through captive technical service teams embedded at major retail account innovation centers. Backward integration into South American high-oleic seed crushing secures feedstock resilience against Southeast Asian palm price volatility. Certification investment in organic and non-GMO supply chain segregation defends premium positioning as European retailers tighten sourcing requirements. For New Entrants and Emerging Players: Brazilian and Argentinian specialty oil refining capacity represents underpenetrated geography where North American processors seek geographic diversification alternatives to Asian palm dependence. Target mid-scale regional bakery cooperatives lacking dedicated lipid chemistry expertise with outsourced reformulation service bundles. Go-to-market leverage rests on digital formulation platforms that compress pilot-scale testing timelines for PHO-free fat system redesigns. For Investors and Strategic Acquirers: European technical lipid houses with enzymatic modification capabilities and established confectionery sector relationships constitute the priority acquisition archetype for capability extension into premium clean-label applications. Long-term viability across the analysis window hinges on positioning upstream of retailer private-label enforcement timelines. Monitor EFSA trans fat threshold revision consultations as regulatory signal for accelerated European reformulation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Capacity Expansion | Enables FDA-compliant fat systems without trans fat generation for bakery applications. |
| Southeast Asian Fractionation Joint Venture | Secures dedicated supply of palm mid-fractions for North American confectionery manufacturers. |
| South American Oilseed Crushing Acquisition | Establishes geographic diversification against Malaysian export duty volatility. |
| Organic Certification Supply Chain Segregation | Captures premium margin pools as European retailers enforce non-GMO sourcing mandates. |
| Digital Formulation Platform Development | Compresses client R&D timelines from months to weeks through predictive crystallization modeling. |
Research Methodology
A standing panel of lipid technology directors, bakery R&D managers, palm oil procurement leads, and retail private-label category buyers provided ongoing calibration against secondary validation from FDA guidance documents, EFSA scientific opinions, Malaysian Palm Oil Board production statistics, and customs trade flow data. Bottom-up segment sizing triangulated against top-down macroeconomic anchors ensured cross-verification of volume and value outputs.
Scenario-bracketing framed demand projections across the modeling period, with segmentation dimensions spanning ingredient type, product application, end-user procurement sophistication, and formulation certification tier. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology substitution curves. Industry-specific inputs included enzymatic interesterification adoption rates, palm oil fractionation capacity utilization, and clean-label retail enforcement timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian palm processors or accelerated FDA enforcement would shift outcomes. Macroeconomic deviation in commodity oil markets, regulatory threshold revisions, or breakthroughs in microbial oil production would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cooking Oils and Fats Market
Ingredients
Rice Bran Oil Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Sugar Beet Pectin Market
Ingredients
Banana Essence Market
Ingredients
Kilned Malt Market
Ingredients
North America Soy Protein Market
Ingredients
Baobab Powder Market
Ingredients
Cocoa Derivatives Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Ice Cream Bases Market
Ingredients
Bouillon Market
Ingredients
South America Spirulina Extract Market
Ingredients
Lupine Peptides Market
Ingredients
Spain Fermentation Ingredients Market