
 Cocoa Based Polyphenols Market | 2026-2036
Cocoa Based Polyphenols Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Based Polyphenols Market Intelligence
Asset-light toll manufacturing and third-party extraction leasing is narrowing the capital barrier for mid-tier entrants into cocoa polyphenol supply. Barry Callebaut AG leverages backward integration into West African bean sourcing to secure flavanol-rich feedstock. Cargill Incorporated anchors its position through controlled fermentation protocols that standardize polyphenol retention. Olam International Limited competes via geographic diversification across Indonesian and Ecuadorian origin supply chains.
Cocoa based polyphenols comprise flavanols, procyanidins, and anthocyanins extracted from Theobroma cacao bean material, typically standardized to epicatechin content between 10% and 90% by weight for nutraceutical applications. These compounds function primarily as antioxidant active ingredients in cardiovascular and cognitive health formulations. Extracts and powders dominate current volume flows, with extracts commanding premium positioning due to higher flavanol concentration and cleaner label profiles. Functional foods represent the fastest-expanding application channel as bakery and beverage manufacturers incorporate polyphenol fortification into mainstream product lines.
EFSA novel food assessments and FDA GRAS notifications jointly shape ingredient approval pathways and health claim substantiation requirements for cocoa polyphenol suppliers. REACH compliance and EU MDR frameworks further govern cosmetic-grade extract purity standards and traceability documentation. Stakeholders must monitor evolving regulatory divergence between European precautionary approval models and US self-affirmed GRAS pathways when allocating R&D and registration budgets.
Market Dynamics
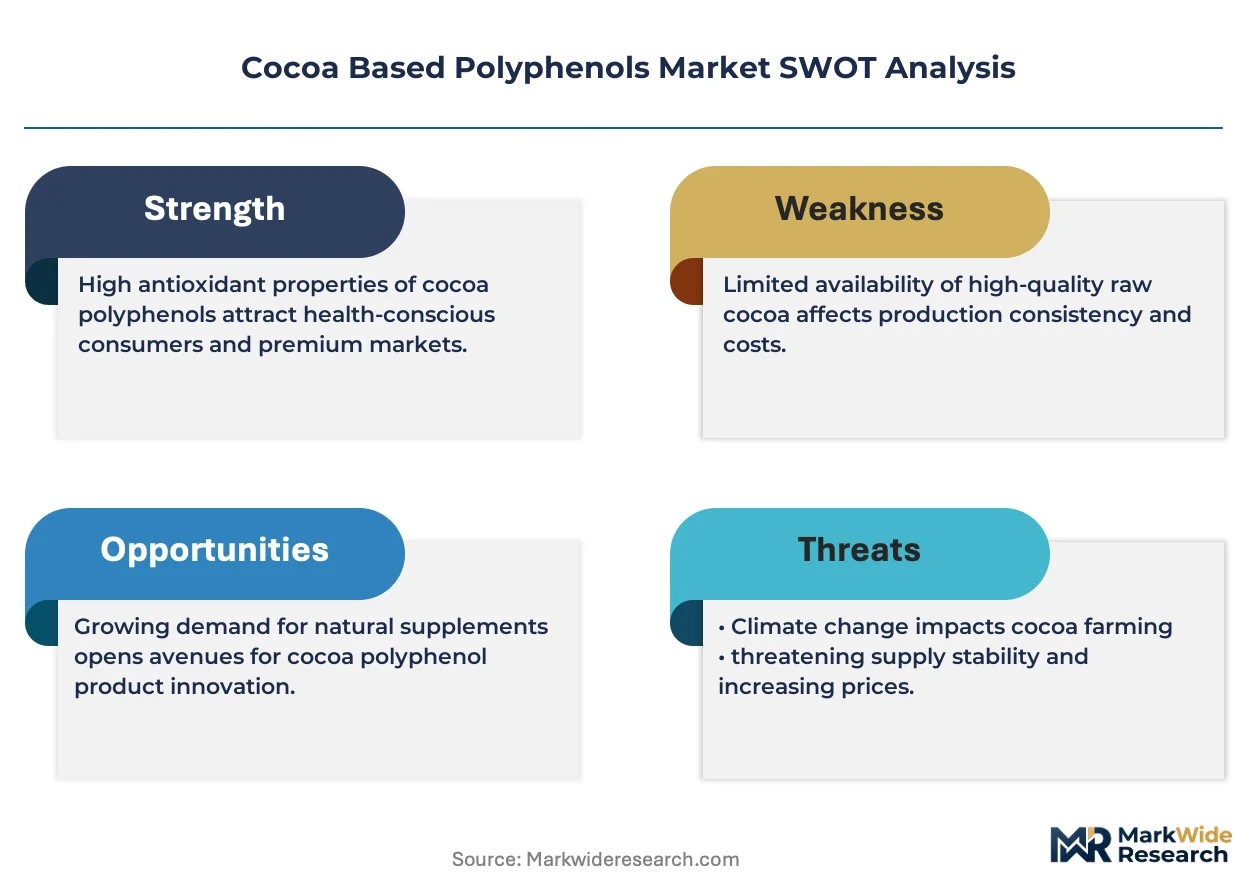
Clean-label extraction protocols are displacing solvent-based methods across cocoa polyphenol supply chains, compressing processing margins while opening premium positioning for compliant suppliers.
Growth Catalysts
- EFSA Health Claim Pathways:Nutraceutical formulators in Germany leverage EFSA-approved cardiovascular claims to differentiate fortified products, creating pull-through demand for standardized epicatechin extracts.
- Functional Food Integration:Bakery and beverage manufacturers embed polyphenol fortification into mainstream product lines, expanding addressable volume beyond traditional supplement channels.
- West African Feedstock Security:Backward integration into Ivorian and Ghanaian bean sourcing secures flavanol-rich raw material access for extraction specialists.
Market Restraints
- Cocoa Butter Price Volatility:Bean cost fluctuations in Côte d'Ivoire and Ghana directly compress extraction economics, forcing margin protection through long-term origin contracts.
- REACH Compliance Burden:ECHA registration requirements for novel cosmetic-grade extracts extend time-to-market by 18-24 months, elevating regulatory capital thresholds.
- Green Tea Polyphenol Substitution:Catechin-equivalent extracts from Camellia sinensis compete on cost in antioxidant applications, pressuring cocoa-derived pricing power.
Strategic Opportunities
- Cognitive Health Formulation White Space:Neuroprotective positioning for flavanol-rich extracts remains underdeveloped relative to cardiovascular claims, offering first-mover substantiation advantages.
- Swiss Innovation Hub Proximity:Zurich-Geneva corridor clustering enables toll manufacturing partnerships with Barry Callebaut's R&D infrastructure, reducing capex barriers for mid-tier entrants.
- EU Green Deal Bioeconomy Incentives:Circular extraction technologies utilizing cocoa pod husk waste streams qualify for CSRD-aligned sustainability financing mechanisms.
Industry Challenges
- Analytical Chemist Scarcity:Flavanol quantification expertise and HPLC method validation capabilities remain concentrated among legacy botanical extract houses, constraining quality team scaling.
- GRAS Self-Affirmation Complexity:FDA notification pathways for novel epicatechin concentrations require toxicology dossiers that extend commercialization timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Based Polyphenols Market |
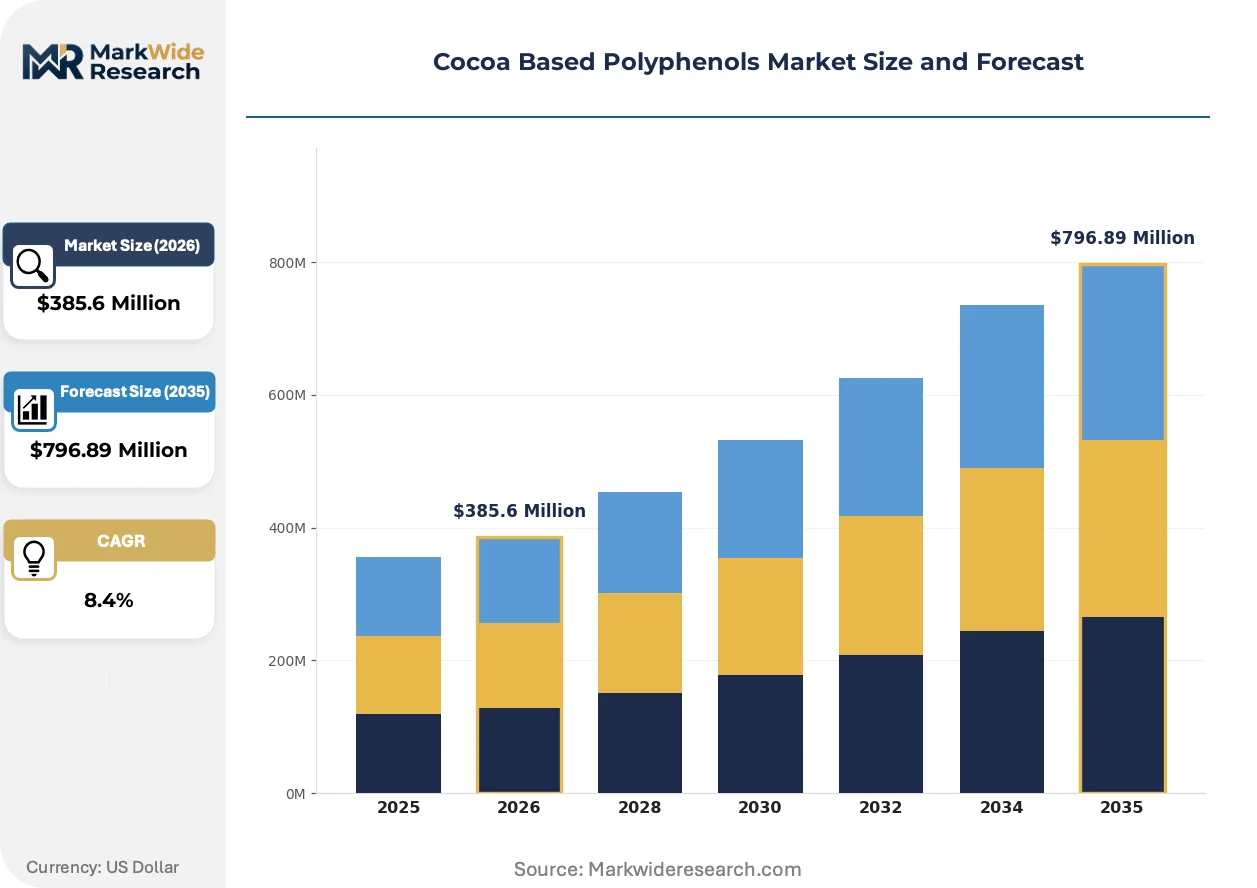
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Powders, Tablets, Capsules Application: Nutraceuticals, Dietary Supplements, Functional Foods, Cosmetics End User: Healthcare Providers, Retail Consumers, Food Manufacturers, Cosmetic Brands Distribution Channel: Online Stores, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Barry Callebaut AG, Cargill Incorporated, Archer Daniels Midland Company, Olam International Limited, Nestlé S.A., The Hershey Company, Mars Incorporated, Mondelez International Inc., Blommer Chocolate Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Based Polyphenols Market Strategic Shifts & Innovations
Supercritical CO2 extraction platforms are merging with pressurized water processing to eliminate residual solvent concerns while preserving heat-sensitive flavanol structures.
Pressurized liquid extraction (PLE) systems utilizing ethanol-water cosolvent blends is hybridizing batch and continuous processing architectures. Nutraceutical contract manufacturers in the Netherlands and Belgium adopt these hybrid platforms to serve clean-label brand requirements. The technology compresses extraction cycle times from 6 hours to 90 minutes while maintaining 85%+ epicatechin recovery rates.
REACH Annex XIV authorization requirements for residual dichloromethane in botanical extracts tighten purity thresholds for cosmetic-grade cocoa polyphenols. ECHA's 2023 update to residual solvent limits forces reformulation of legacy extraction processes. German and French cosmetic ingredient suppliers accelerate investment in supercritical fluid alternatives to maintain EU market access.
Ingredient procurement from toll manufacturers displaces captive extraction among mid-sized functional food brands. Swiss and Austrian chocolate manufacturers now source standardized extracts rather than maintaining in-house processing capabilities. This pattern concentrates most visible in premium confectionery segments where brand equity resides in formulation rather than upstream processing control.
Cocoa Based Polyphenols Market Segmentation
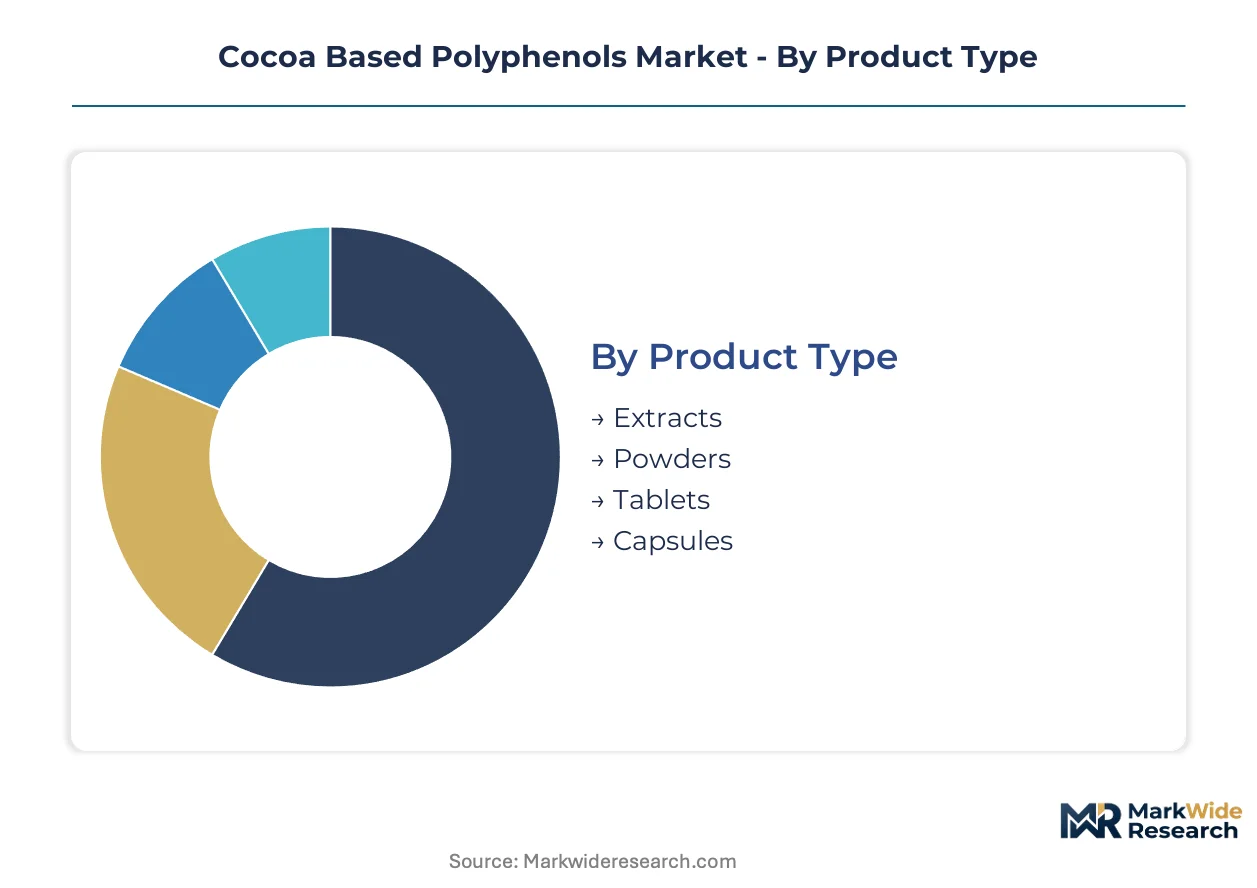
Cocoa polyphenol suppliers configure production lines around four distinct segmentation axes. Product format determines extraction investment and margin structure. Application channel dictates regulatory pathway and health claim substantiation burden.
Product Type:
Mature powder formats dominate volume flows while emerging delivery systems reshape bioavailability positioning.
- Extracts:Standardized to 10-90% epicatechin content through supercritical CO2 or pressurized liquid extraction. German nutraceutical formulators specify these for EFSA-compliant cardiovascular health claims, paying premium multiples for solvent-free certification.
- Powders:Spray-dried or freeze-dried bulk material serving functional food fortification. Swiss and Austrian chocolate manufacturers source standardized powders rather than maintaining captive extraction, concentrating procurement among toll manufacturers in the Zurich-Geneva corridor.
- Tablets:Compressed dosage forms with defined dissolution profiles. Dutch contract manufacturers blend cocoa polyphenols with green tea catechins for antioxidant synergy products.
- Capsules:Hard-shell and soft-gel configurations targeting direct-to-consumer supplement channels. Gelatin and plant-based shell alternatives split demand based on clean-label positioning requirements.
Extracts handle the majority of throughput; capsules are expanding most quickly on share as consumer self-dosing preferences shift from powders to unit-dose convenience.
Application:
Application channels separate by regulatory capital intensity and health claim permissibility.
- Nutraceuticals:EFSA Article 13.1 and 13.5 health claim pathways require dossier investment exceeding €500,000 per claim. German and Italian formulators lead cardiovascular positioning submissions.
- Dietary Supplements:FDA GRAS self-affirmation or NDI notification governs US market entry. Epicatechin concentrations above legacy thresholds trigger toxicology study requirements extending timelines 12-18 months.
- Functional Foods:Bakery and beverage fortification expands addressable volume beyond pills. Barry Callebaut's innovation hub supplies standardized extracts for premium confectionery polyphenol enrichment.
- Cosmetics:REACH Annex XIV residual solvent limits and EU MDR purity standards govern topical-grade extract qualification. French and German cosmetic ingredient suppliers accelerate supercritical fluid investment to maintain market access.
Functional foods is gaining share fastest as mainstream manufacturers embed fortification; nutraceuticals retains the highest margin per kilogram due to claim exclusivity barriers.
End User:
End user categories fragment by technical sophistication and procurement control points.
- Healthcare Providers:Clinical nutrition and medical food prescribers in Germany and Switzerland specify pharmacy-grade extracts with batch-specific CoA documentation.
- Retail Consumers:Direct-to-consumer supplement purchasers drive capsule and tablet volume through online channels and pharmacy retail.
- Food Manufacturers:Swiss chocolate producers and Belgian bakery groups source standardized powders for clean-label fortification without upstream processing investment.
- Cosmetic Brands:L'Oréal and Beiersdorf suppliers in France and Germany demand REACH-compliant extracts with full traceability to West African origin.
Food manufacturers handle the majority of volume throughput; cosmetic brands show the steepest expansion trajectory as topical antioxidant positioning proliferates in premium skincare.
Distribution Channel:
Channel structure reflects regulatory custody requirements and consumer education burden.
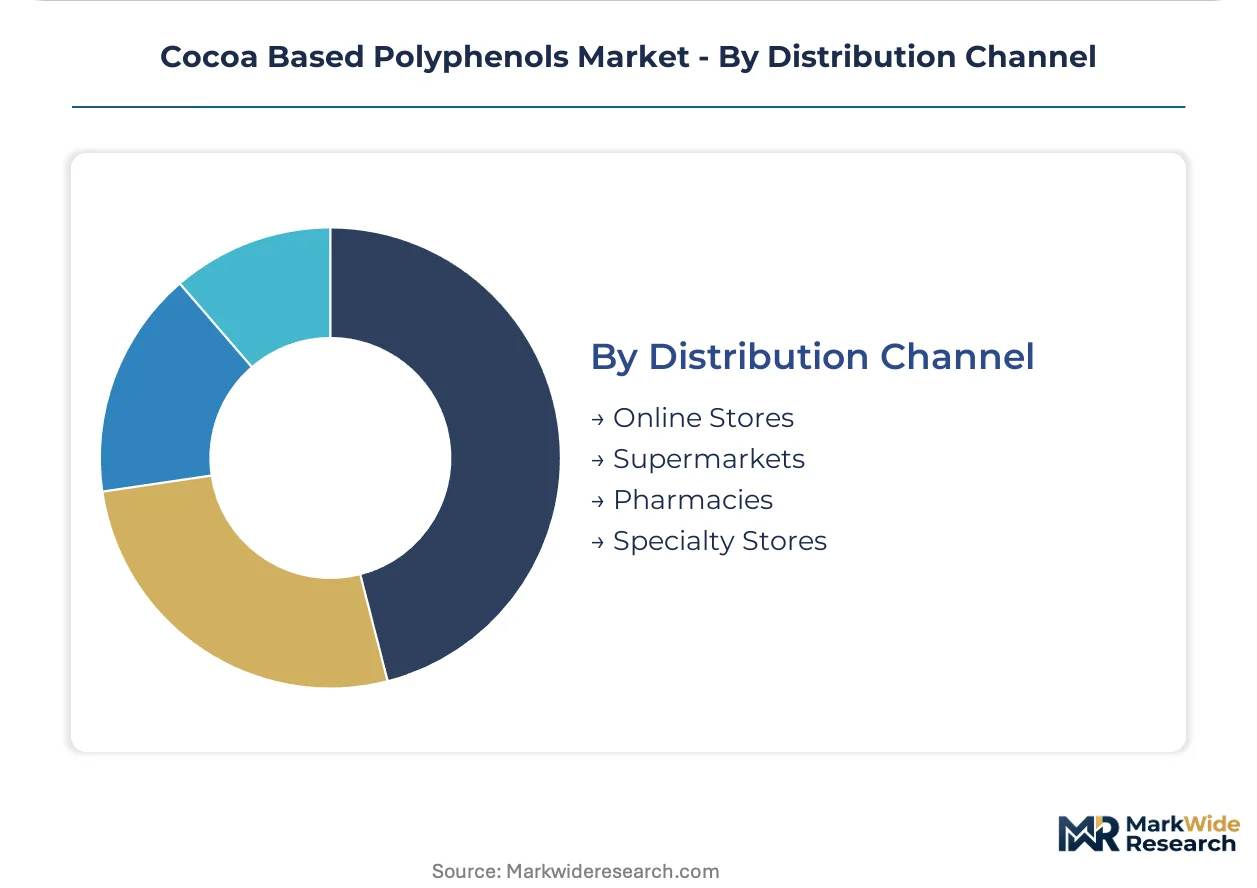
- Online Stores:Direct-to-consumer platforms capture supplement and cosmetic ingredient sales. Amazon and specialized nutraceutical e-tailers dominate in Germany and the UK.
- Supermarkets:Mass-market functional food placement requires retail-ready packaging and consumer-facing health claim language approved under national advertising standards.
- Pharmacies:German and Swiss pharmacy chains stock EFSA-claim-qualified products behind-counter or in self-selection areas based on reimbursement status.
- Specialty Stores:Organic and natural product retailers in Austria and Belgium curate clean-label cocoa polyphenol assortments with origin storytelling.
Pharmacies handle the majority of high-margin throughput; online stores are climbing the fastest on share as subscription supplement models reduce customer acquisition costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal bioeconomy incentives and EFSA health claim frameworks are redirecting investment toward sustainable extraction infrastructure across key European markets. Switzerland's innovation clustering and Germany's regulatory leadership position these countries as demand anchors. West African feedstock security concerns are prompting origin diversification into Indonesian and Ecuadorian supply chains.
Germany
Nutraceutical formulators in Germany leverage EFSA Article 13.1 cardiovascular health claims to differentiate fortified supplement products, creating specification pull-through for standardized epicatechin extracts. BfR safety assessments and ECHA REACH compliance requirements govern cosmetic-grade extract purity thresholds. The Frankfurt-Rhine-Main corridor hosts toll manufacturing partnerships serving mid-tier brands seeking clean-label certification without captive extraction investment.
Switzerland
Barry Callebaut's Zurich-Geneva innovation hub concentrates R&D infrastructure and backward integration into West African bean sourcing, securing flavanol-rich feedstock for extraction specialists. Swissmedic pharmaceutical-grade standards and proximity to EU regulatory frameworks attract contract manufacturers serving cross-border nutraceutical brands. Basel-area chemical suppliers provide supercritical CO2 equipment for solvent-free extraction platform deployment.
Netherlands
Dutch contract manufacturers adopt pressurized liquid extraction hybrid platforms to compress cycle times from six hours to ninety minutes while maintaining epicatechin recovery rates above eighty-five percent. The country's national food safety authority enforces residual solvent limits aligned with EFSA novel food assessment protocols. Rotterdam-Antwerp port logistics facilitate Indonesian and Ecuadorian origin cocoa polyphenol import flows for European distribution.
France
French cosmetic ingredient suppliers accelerate supercritical fluid investment to satisfy REACH Annex XIV authorization requirements for residual dichloromethane limits in botanical extracts. ANSM cosmetic safety evaluations and EU MDR traceability documentation govern topical-grade extract qualification. Paris-region formulators supply L'Oréal and Beiersdorf with origin-documented cocoa polyphenols for premium skincare antioxidant positioning.
United States
FDA GRAS self-affirmation pathways and NDI notification requirements govern dietary supplement market entry for novel epicatechin concentrations, extending commercialization timelines twelve to eighteen months for toxicology dossier completion. California and New Jersey-based nutraceutical brands drive capsule and tablet volume through direct-to-consumer online channels. Chicago-area functional food manufacturers embed polyphenol fortification into mainstream bakery and beverage product lines.
Cocoa Based Polyphenols Market Key Industry Players
On the supply side, the industry is consolidating around three distinct capability tiers. Integrated cocoa processors with captive bean sourcing dominate upstream flavanol-rich feedstock access. Mid-tier toll manufacturers concentrate extraction capacity in the Zurich-Geneva and Rotterdam-Antwerp corridors. Specialty botanical houses retain analytical chemistry expertise for HPLC method validation and batch-specific CoA documentation. Dominant competitive moves include backward integration into Ivorian and Ghanaian origin contracts and technology licensing agreements for supercritical CO2 platform deployment.
Among Swiss-integrated processors, Barry Callebaut AG exemplifies the captive-feedstock archetype through its West African sourcing infrastructure and innovation hub clustering. Cargill Incorporated occupies a position representing controlled-fermentation protocol standardization for polyphenol retention. Olam International Limited sits within the geographic-diversification archetype, anchoring supply chain resilience across Indonesian and Ecuadorian origins.
| Leading Market Players |
|---|
| Barry Callebaut AG |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Olam International Limited |
| Nestlé S.A. |
| The Hershey Company |
| Mars Incorporated |
| Mondelez International Inc. |
| Blommer Chocolate Company |
| Others |
Cost & Logistics Intelligence
The Zurich-Geneva corridor concentrates supercritical CO2 extraction capacity for cocoa polyphenols, and this geographic clustering grants toll manufacturers substantial leverage over mid-tier brands seeking clean-label certification without captive investment.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with EFSA-compliant cardiovascular health claim dossiers commanding multiples over generic antioxidant grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by epicatechin concentration and solvent-free verification. Cost compression in standard-grade extracts is intensifying because green tea catechin substitutes compete on equivalent antioxidant units. Food manufacturers show highest price sensitivity due to volume procurement and formulation flexibility, while German nutraceutical formulators exhibit lowest sensitivity given claim exclusivity barriers.
Supply Chain Analysis
Tariff exposure between Côte d'Ivoire and EU processing hubs dominates supply chain risk assessment for flavanol-rich feedstock. Geographic concentration centers on Ivorian and Ghanaian bean origins, with Indonesian and Ecuadorian supply chains providing diversification anchors. Raw material dependencies rest on fermented cacao liquor, cocoa pod husk waste streams, and standardized epicatechin reference materials. Single-source vulnerability persists in West African origin contracts due to political instability and climate disruption. Distribution runs through Rotterdam-Antwerp port logistics for European toll manufacturing, with Swiss innovation hub partnerships serving premium confectionery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around EFSA health claim dossiers creates switching costs that lock in formulation relationships across multi-year development cycles.
For Market Incumbents: Build regulatory entrenchment through accelerated EFSA Article 13.5 submissions for cognitive health positioning before first-mover windows close. Backward integration into Ivorian and Ghanaian long-term origin contracts protects margin structures against cocoa butter price volatility. Expand analytical chemistry capabilities in HPLC method validation to constrain quality team scaling among mid-tier competitors. For New Entrants and Emerging Players: Establish a beachhead in cosmetic-grade extracts where REACH Annex XIV compliance gaps create procurement friction for incumbent suppliers. The cognitive health application channel remains underpenetrated relative to cardiovascular claims, offering substantiation white space with lower competitive density. Partner with Dutch contract manufacturers adopting pressurized liquid extraction hybrid platforms to bypass capital-intensive infrastructure requirements. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-ingredient consolidation play because analytical chemist scarcity and regulatory dossier concentration favor scale economies in quality documentation. Target acquisition archetypes include mid-tier toll manufacturers with Swiss or Dutch facility footprints and existing EFSA notification experience. Monitor GRAS self-affirmation backlog at FDA as inflection indicator for US market entry timing and competitive pressure release.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into West African Origins | Barry Callebaut's Ivorian sourcing infrastructure secures flavanol-rich feedstock access against commodity volatility. |
| Supercritical CO2 Platform Deployment | German cosmetic ingredient suppliers eliminate residual dichloromethane concerns under tightened ECHA Annex XIV limits. |
| EFSA Cognitive Health Claim Submission | Neuroprotective positioning dossiers exploit underdeveloped substantiation relative to cardiovascular competitors. |
| Pressurized Liquid Extraction Licensing | Dutch contract manufacturers compress cycle times from six hours to ninety minutes for clean-label brand requirements. |
| Toll Manufacturing Partnership Expansion | Swiss chocolate producers source standardized extracts without maintaining captive processing capabilities. |
Research Approach
A spread of perspectives from extraction technology specialists, nutraceutical formulators, cosmetic ingredient procurement managers, and EFSA regulatory consultants converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against EU novel food assessment databases, REACH registration filings, FDA GRAS notification logs, and customs trade flow records. Bottom-up volume modeling from individual facility capacities and top-down demand segmentation from end-use applications were triangulated to constrain estimate variance.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product format, application channel, end user category, and geographic regulatory cluster. CAGRs were derived from growth driver elasticity estimates calibrated to historical adoption patterns in functional food fortification and cosmetic antioxidant positioning. Forecast inputs incorporated EFSA health claim approval timelines, cocoa butter futures volatility bands, and supercritical equipment deployment rates in the Zurich-Geneva and Rotterdam-Antwerp corridors.
Sensitivities concentrate around EFSA dossier rejection rates, West African origin supply disruptions, and green tea polyphenol substitution elasticity in antioxidant applications. Forecasts reflect assumptions about regulatory pathway efficiency and clean-label technology adoption curves that operating reality may revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Native Whey Protein Ingredients Market
Ingredients
White Wheat Malt Market
Ingredients
Egg Membrane Powder Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
Sea Buckthorn Berry Extract Market
Ingredients
United Kingdom Protein Market
Ingredients
Commercial Flour Market
Ingredients
Lime Seed Oils Market
Ingredients
Cooking Coconut Milk Market
Ingredients
Agar Market
Ingredients
Corn Steep Liquor Market
Ingredients
Specialty Fats and Oils Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Buckwheat Groat Flour Market
Ingredients
Millet Protein Market
Ingredients
Truffle Oil Market