
 Biotech Ingredients Market | 2026-2036
Biotech Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Biotech Ingredients Market Intelligence
Pharmaceutical formulation demand is rebalancing toward fermentation-derived actives as synthetic chemistry faces ESG scrutiny. DSM-Firmenich leverages integrated biotechnology platforms spanning enzymes and amino acids. Givaudan anchors its position in flavor and fragrance biotech through captive fermentation capacity. Evonik Industries specializes in high-purity nucleotides for cell culture media.
Biotech ingredients comprise metabolites, enzymes, nucleotides, and biomass produced via microbial fermentation, cell culture, or enzymatic catalysis, typically achieving purity grades above 98% for pharmaceutical applications and serving as functional inputs across nutrition, therapeutics, and agricultural formulations. Enzymes dominate current revenue pools due to their scale in food processing and detergent applications, while nucleotides represent the fastest-expanding segment driven by cell therapy media and mRNA manufacturing demand. Certification stratification creates margin divergence, with GMP-grade commands in pharmaceutical channels separating premium tiers from standard food-grade and economy feed-grade offerings.
FDA oversight of biotech-derived drug substances through CMC guidelines shapes purity benchmarks and facility inspection schedules for US-market suppliers. EMA's MDR and REACH frameworks in Europe impose traceability and sustainability disclosure requirements that filter down to ingredient sourcing decisions. China's NMPA biologics registration pathway and GB standards for fermentation products define market access rules for imported enzymes and amino acids. Stakeholders must monitor regulatory divergence between GMP harmonization initiatives and emerging national biosecurity controls over genetic resource access.
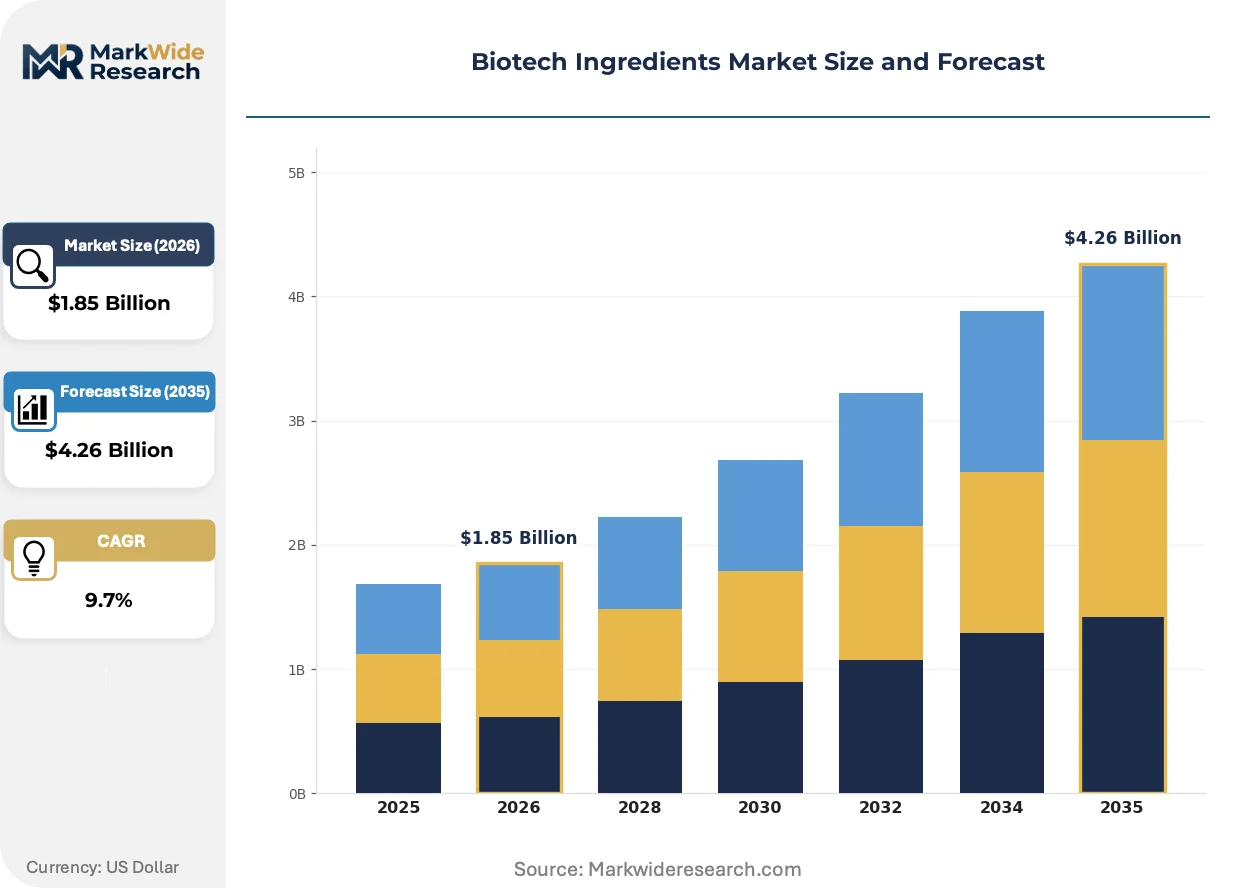
Market Dynamics
Pharmaceutical formulation demand is rebalancing toward fermentation-derived actives as synthetic chemistry faces ESG scrutiny. The EU Green Deal and REACH amendments are accelerating bioprocess validation requirements.
Growth Catalysts
- Cell therapy media demand:mRNA manufacturing and regenerative medicine applications are expanding nucleotide consumption. FDA CMC guidelines for biologics are tightening purity specifications.
- REACH amendments:European chemical sustainability disclosure mandates are redirecting procurement toward fermentation-derived alternatives. ECHA registration requirements favor biobased feedstocks.
- Industrial biotechnology clusters:Germany's Rhineland and Bavaria regions anchor contract manufacturing capacity for enzymes and nucleotides, concentrating technical talent and pilot-scale infrastructure.
Market Restraints
- Feedstock cost volatility:Corn-derived glucose and soy peptone prices fluctuate with agricultural commodity cycles, compressing margin stability for bulk enzyme producers.
- Facility concentration risk:GMP-grade fermentation capacity clusters in Switzerland and Germany, creating single-source dependencies for pharmaceutical-grade nucleotides.
- Contamination control limits:Endotoxin removal from gram-negative bacterial hosts remains technically constrained, restricting application in parenteral drug formulations.
Strategic Opportunities
- India biologics manufacturing:CDSCO's streamlined biologics registration pathway and PLI scheme incentives are attracting fermentation capacity investment for export-oriented enzyme production.
- Precision fermentation scale-up:Combining synthetic biology with continuous processing enables novel metabolite production at titers unachievable through traditional batch methods.
- Direct-to-formulator digital platforms:Specialty chemical distributors are launching e-procurement portals that bypass traditional multi-tier distribution for standard-grade enzymes.
Industry Challenges
- Bioprocess engineering talent scarcity:Scale-up specialists with simultaneous expertise in metabolic modeling and GMP compliance command premium compensation, constraining facility expansion timelines.
- Dual-use biosecurity licensing:Genetic resource access permits under national biosecurity frameworks are delaying strain development programs for novel biocatalysts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biotech Ingredients Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.26 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Amino Acids, Nucleotides, Biomass End Use Industry: Pharmaceuticals, Food & Beverages, Agriculture, Cosmetics Form: Liquid, Powder, Granular, Paste Certification: GMP, ISO, Non-GMO, Organic |
| Companies Covered | DSM-Firmenich, Givaudan, Fermenta Biotech Limited, Titan Biotech, Conagen, Inc., Evonik Industries, Symrise, Merck KGaA, International Flavors & Fragrances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biotech Ingredients Market Strategic Shifts & Innovations
Continuous processing architectures and synthetic biology toolkits are compressing development cycles for novel biotech ingredients. Regulatory frameworks are simultaneously tightening traceability requirements and sustainability disclosure standards.
Continuous fermentation systems are consolidating manufacturing economics for high-volume enzymes. Food and detergent formulators are retrofitting legacy batch facilities to capture 40-60% productivity gains. This technology is consolidating competitive position among mid-scale producers who can amortize capital conversion costs against multi-product flexibility.
EMA's MDR and EU Green Deal sustainability disclosure mandates are reshaping supplier qualification protocols. Pharmaceutical manufacturers must now document carbon intensity across upstream fermentation inputs. Cell culture media suppliers serving European markets are accelerating renewable energy procurement for production sites.
Formulator procurement teams are consolidating vendor panels around integrated biotechnology platforms. Multi-product suppliers offering enzymes, nucleotides, and amino acids are displacing single-category specialists in long-term supply agreements. This concentration is most visible in German and Swiss pharmaceutical clusters where technical integration and regulatory dossier continuity reduce qualification overhead.
Biotech Ingredients Market Segmentation
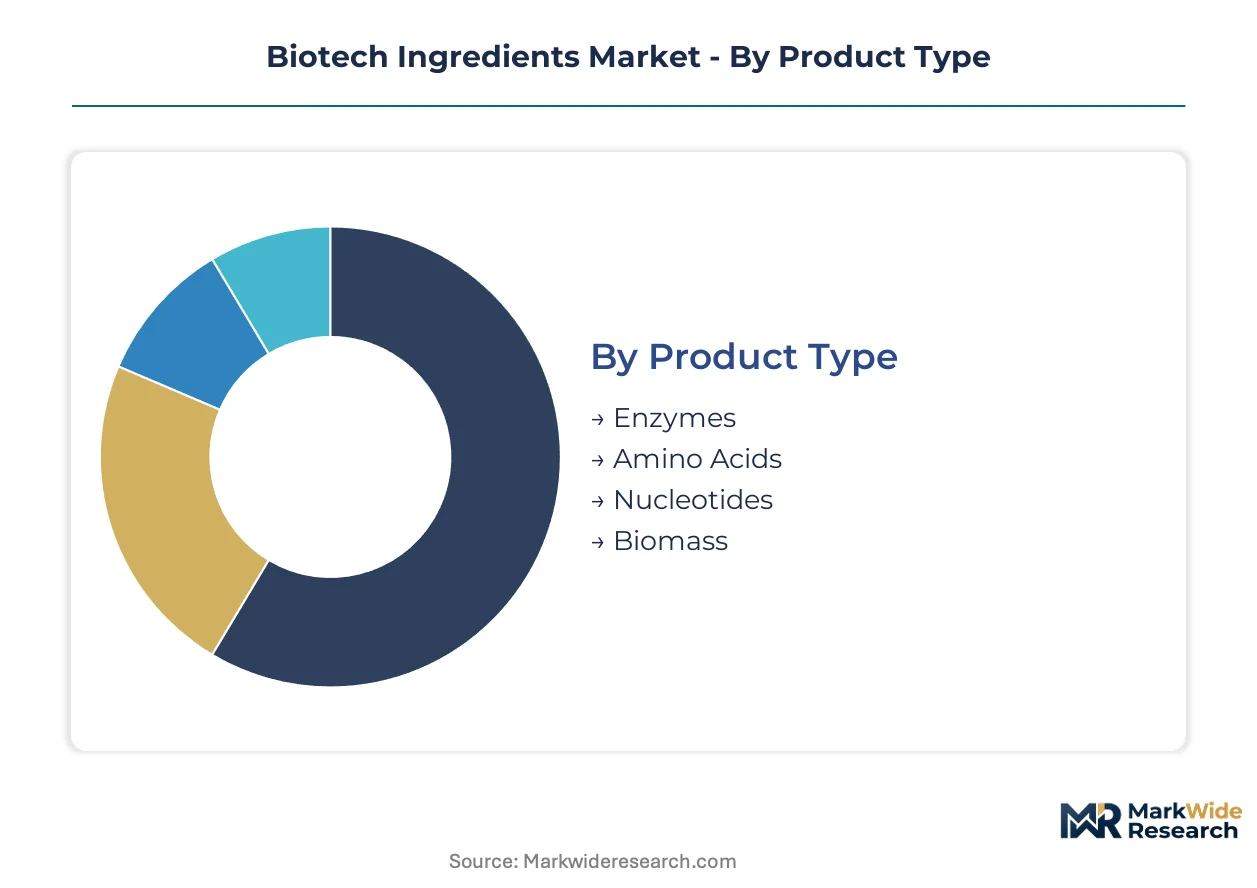
Biotech ingredient suppliers configure production assets around certification tiers and end-use purity requirements. Segmentation logic determines facility investment, regulatory dossier scope, and margin capture potential across pharmaceutical, nutrition, and industrial channels.
Product Type:
Supply concentration clusters around fermentation capacity with multi-product flexibility, particularly in German and Swiss industrial biotechnology corridors.
- Enzymes:Protein biocatalysts produced via microbial fermentation achieve titers above 100 g/L in optimized production strains. Food processing applications in Germany and detergent formulations in the US absorb bulk volumes, though pharmaceutical-grade specifications command 3-5x pricing premiums.
- Nucleotides:Purine and pyrimidine building blocks for cell culture media and mRNA manufacturing require endotoxin control below 0.25 EU/mg. Demand is concentrating in CDMO networks serving gene therapy developers in Basel and Boston, with synthetic biology approaches enabling novel modified nucleotide production.
- Amino Acids:Fermentation-derived L-enantiomers for parenteral nutrition and flavor enhancement.
- Biomass:Whole-cell preparations and protein concentrates for feed and agricultural applications.
Today's leader: Enzymes. Tomorrow's challenger: Nucleotides.
End Use Industry:
Application-driven purity requirements create three distinct cost tiers that reshape supplier qualification protocols.
- Pharmaceuticals:GMP-grade biotech ingredients for biologics manufacturing, cell therapy media, and active pharmaceutical ingredients. FDA CMC guidelines and EMA MDR impose facility inspection schedules, stability documentation, and viral clearance validation that filter supplier pools to Switzerland, Germany, and select US sites.
- Food & Beverages:Processing aids, flavor precursors, and nutritional fortificants operating under FSSAI, FDA GRAS, and EFSA frameworks. India's enzyme demand for dairy and brewing applications is expanding fastest among emerging markets.
- Agriculture:Feed enzymes, biofertilizer inoculants, and crop protection metabolites.
- Cosmetics:Fermentation-derived actives for skin microbiome and hair care formulations.
Pharmaceuticals extract maximum margin per kilogram. Food & Beverages deliver volume scale.
Form:
Physical presentation determines logistics economics, shelf stability, and formulation integration complexity for downstream customers.
- Liquid:Standardized enzyme solutions and cell culture media concentrates. Bulk tanker shipments to detergent and ethanol plants in the US Corn Belt and Rhineland minimize packaging costs.
- Powder:Spray-dried preparations for nutritional premixes and solid dosage forms. Hygroscopic nucleotides require nitrogen-flushed packaging and cold chain logistics for pharmaceutical customers.
- Granular:Dust-free enzyme preparations for feed applications.
- Paste:High-activity concentrated biocatalysts for specialized industrial processes.
Liquid dominates tonnage movements. Powder commands formulation flexibility premiums.
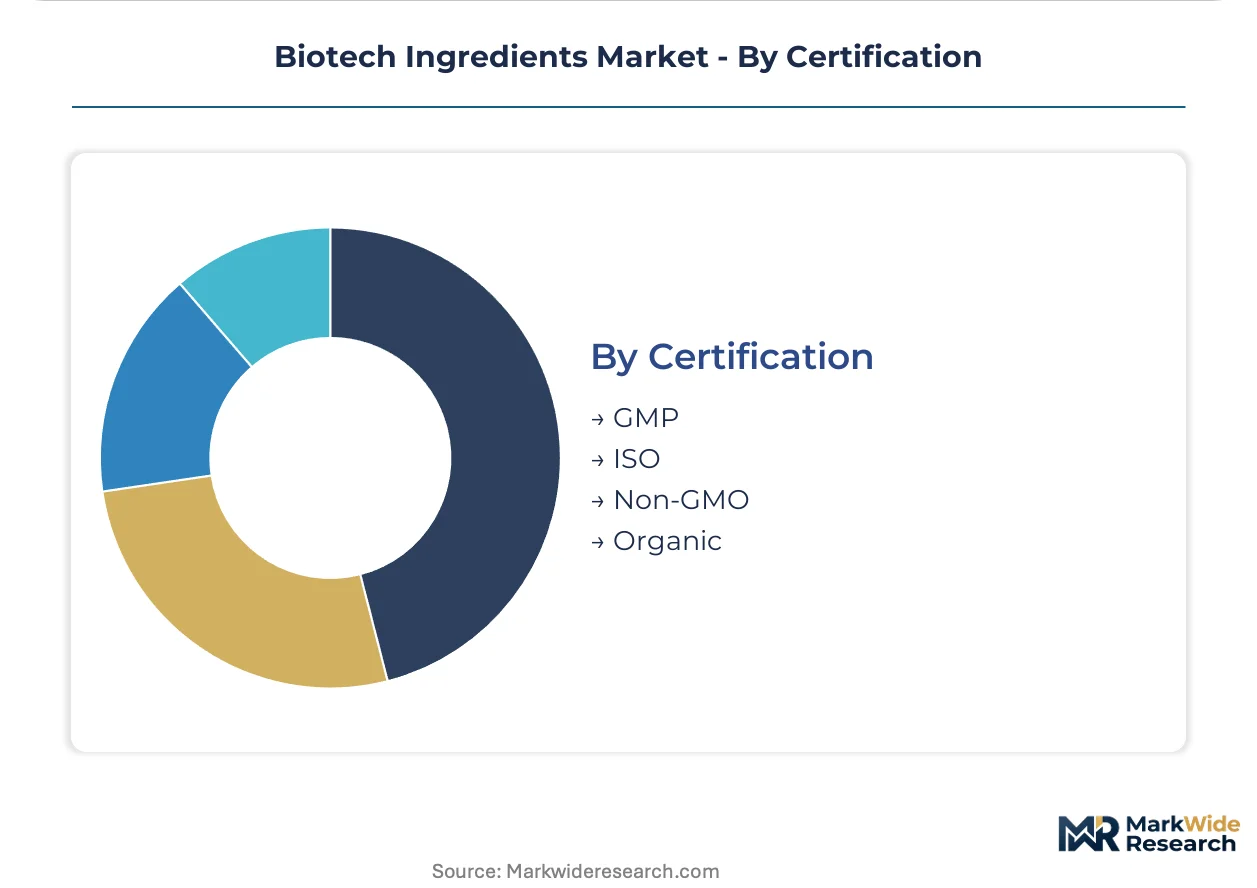
Certification:
Regulatory tiering separates premium channel access from commodity positioning, with documentation burden increasing exponentially across grades.
- GMP:Current Good Manufacturing Practice compliance for pharmaceutical and biologics applications. FDA and EMA facility inspections, process validation batches, and annual product reviews create entry barriers that sustain pricing power for established suppliers.
- ISO:Quality management and food safety certifications (ISO 9001, ISO 22000, FSSC 22000) enabling broad industrial and nutrition market access.
- Non-GMO:Identity preservation and testing protocols for European and North American consumer product formulations.
- Organic:USDA NOP and EU Organic certification for fermentation substrates and processing aids in certified finished goods.
GMP certification gates the highest-value applications. ISO remains the baseline for commercial viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhineland and Bavaria industrial biotechnology corridors anchor fermentation capacity for enzymes and nucleotides serving pharmaceutical and nutrition markets. The EU Green Deal and REACH amendments are redirecting procurement toward biobased feedstocks. Cluster concentration in Swiss and German GMP-grade facilities creates supply dependencies for cell therapy media manufacturers.
Germany
Pharmaceutical-grade nucleotide demand from Basel-oriented CDMOs and mRNA manufacturers drives fermentation capacity expansion. EMA's MDR and EU Green Deal sustainability disclosure mandates require carbon intensity documentation across upstream inputs. The Rhineland and Bavaria regions concentrate contract manufacturing infrastructure for enzymes and amino acids, with technical talent pools supporting pilot-scale bioprocess development.
United States
Cell therapy media and biologics manufacturing absorb high-purity nucleotides and recombinant enzymes for gene therapy applications. FDA CMC guidelines for biologics impose facility inspection schedules and viral clearance validation requirements that filter supplier pools. Greater Boston and San Francisco Bay Area clusters anchor demand from regenerative medicine developers, while the US Corn Belt supports bulk enzyme production for ethanol and detergent applications.
Switzerland
Gene therapy developers in Basel and pharmaceutical headquarters in Zurich drive GMP-grade nucleotide and cell culture media consumption. Swissmedic oversight aligns with EMA MDR frameworks, creating regulatory continuity for cross-border supply chains. The country's pharmaceutical manufacturing corridor concentrates technical expertise in endotoxin control and viral clearance validation for parenteral-grade biotech ingredients.
India
Dairy processing and brewing applications expand food-grade enzyme demand fastest among emerging markets. CDSCO's streamlined biologics registration pathway and PLI scheme incentives attract fermentation capacity investment for export-oriented production. Maharashtra and Gujarat industrial corridors anchor contract manufacturing for standard-grade enzymes serving nutrition and agricultural formulations.
China
Domestic biologics manufacturing scale-up and mRNA vaccine production infrastructure drive nucleotide consumption growth. NMPA biologics registration pathways and GB standards for fermentation products define market access rules for imported enzymes and amino acids. Yangtze River Delta biopharmaceutical clusters concentrate cell culture media demand, while Shandong Peninsula anchors bulk fermentation capacity for feed and industrial enzymes.
Biotech Ingredients Market Key Industry Players
Capacity expansion dominates the current landscape as fermentation facilities scale to capture cell therapy media and mRNA manufacturing demand. The vendor base stratifies across integrated biotechnology platforms, single-category specialists, and contract development manufacturers. Three archetypes prevail: multi-product suppliers spanning enzymes and nucleotides, captive flavor and fragrance biotech divisions, and precision fermentation scale-up ventures. M&A consolidation and geographic capacity expansion represent the dominant competitive moves as formulators consolidate vendor panels.
Within the integrated biotechnology platform tier, DSM-Firmenich and Givaudan exemplify multi-product positioning spanning enzymes, amino acids, and fermentation-derived actives. Evonik Industries occupies a specialized position in high-purity nucleotides for pharmaceutical applications. These European-anchored entities represent contrasting archetypes: broad-platform integration versus segment-specific depth, with each configuration serving distinct procurement patterns among pharmaceutical and nutrition formulators.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Givaudan |
| Fermenta Biotech Limited |
| Titan Biotech |
| Conagen, Inc. |
| Evonik Industries |
| Symrise |
| Merck KGaA |
| International Flavors & Fragrances |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap fermentation specialists in Germany and Switzerland anchor pricing discipline through captive GMP capacity, while private-equity-rolled-up enzyme distributors compress margins in standard-grade channels. Sovereign-backed Chinese producers in Shandong Peninsula undercut contract pricing for bulk industrial enzymes, forcing Western suppliers to defend pharmaceutical-grade premiums through certification differentiation.
Pricing Analysis
Distributor margin layers in biotech ingredients typically capture 15-25 points between ex-works fermentation sites and downstream formulators. Three-tier pricing structure across GMP-grade, food-grade, and feed-grade certifications separates premium pharmaceutical channels from commodity nutrition applications. Pricing pressure stems from corn-derived glucose cost volatility and soy peptone agricultural cycles, which squeeze bulk enzyme producers most acutely. Pharmaceutical CDMOs exhibit lowest price sensitivity due to regulatory qualification switching costs, while detergent and ethanol plant procurement teams drive hardest volume negotiations.
Supply Chain Analysis
Dual-sourcing requirements from Basel-oriented gene therapy developers and Boston cell therapy manufacturers mandate qualified secondary suppliers for GMP-grade nucleotides. Geographic supply concentration clusters in Germany, Switzerland, and select US sites for pharmaceutical-grade materials, with China and India anchoring bulk enzyme capacity. Raw material dependencies on corn glucose, soy peptone, and yeast extract tether margin stability to agricultural commodity cycles. Single-source vulnerability persists for endotoxin-controlled parenteral-grade nucleotides where Swiss and German facility concentration dominates. Distribution runs through specialty chemical distributors with multi-tier qualification protocols, though direct-to-formulator digital portals are displacing legacy channels for standard-grade enzymes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biotech ingredients function as a stable compounder anchored by irreversible substitution of synthetic chemistry with fermentation-derived actives under ESG mandates. Pharmaceutical formulation demand for cell therapy media and mRNA manufacturing provides durable growth visibility.
For Market Incumbents: To counter precision fermentation scale-up ventures with synthetic biology toolkits, incumbents should deepen backward integration into strain development capabilities and expand GMP capacity in German industrial biotechnology corridors. Certification investment in EMA MDR-aligned sustainability documentation preserves pricing power against lower-cost Asian entrants. For New Entrants and Emerging Players: Mid-tier Indian pharmaceutical formulators represent an underserved buyer archetype seeking qualified but cost-competitive nucleotide suppliers outside Swiss-German supply dependencies. Precision fermentation platforms targeting novel modified nucleotides for mRNA therapeutics offer the most penetrable white space. Go-to-market positioning should emphasize CDSCO registration support and PLI scheme alignment for export-oriented capacity. For Investors and Strategic Acquirers: Valuations sit cheapest among single-category enzyme specialists facing margin compression from agricultural feedstock volatility. Long-term viability favors integrated biotechnology platforms spanning enzymes, nucleotides, and amino acids with captive fermentation infrastructure. The signal to watch is consolidation of vendor panels by European pharmaceutical formulators around multi-product suppliers with regulatory dossier continuity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Synthetic biology-enabled continuous processing achieves titers unachievable through batch methods. |
| GMP Capacity Expansion | EMA MDR and FDA CMC inspection schedules filter supplier pools to established sites. |
| Backward Integration into Strain Development | In-house biocatalyst programs reduce licensing exposure to national biosecurity frameworks. |
| Sustainability Certification Investment | EU Green Deal carbon intensity documentation gates access to premium pharmaceutical channels. |
| Direct-to-Formulator Digital Platform Launch | E-procurement portals bypass distributor margins for standard-grade enzyme volumes. |
Research Approach
Multiple input streams — primary interviews with fermentation plant managers, bioprocess engineering directors, and pharmaceutical procurement leads; secondary validation through EMA inspection databases, FDA CMC guidance documents, and customs trade flows; and bottom-up capacity modeling against top-down end-use demand — were reconciled to produce segment-level estimates. Conversations with CDMO network planners and cell therapy media suppliers informed nucleotide demand projections. SEC filings from listed biotechnology platforms and Cefic industrial biotechnology reports provided production capacity benchmarks.
Historical volume trajectories were cross-referenced against panel input from bioprocess engineering specialists to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product type, certification tier, end-use industry, and regional production hub dimensions. CAGRs were derived from fitted growth curves applied to qualified capacity expansion timelines and downstream demand absorption rates. Forecast inputs included mRNA manufacturing scale-up assumptions, REACH amendment implementation pacing, and CDSCO biologics registration pathway adoption.
Underlying measurement precision varies by segment; GMP-grade pharmaceutical applications carry tighter precision than feed-grade enzyme volumes given facility-specific qualification visibility. Forecasts reflect assumptions regarding regulatory harmonization initiatives and agricultural commodity price stabilization. Deviation in national biosecurity licensing timelines for genetic resource access would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
China Corn Glucose Market
Ingredients
Whey Permeate Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Tuna and Algae Omega-3 Ingredient Market
Ingredients
Baking Ingredients Market
Ingredients
Coconut Oil Market
Ingredients
Africa Food Ingredients Market
Ingredients
Birch Sap Market
Ingredients
Potato Fiber Market
Ingredients
Rice Starch Market
Ingredients
Global Alpha-Lactalbumin Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Proteose Peptone Market
Ingredients
Asia-Pacific Brewing Enzymes Market
Ingredients
Banana Essence Market
Ingredients
Phytosterols Market