
 North America Dairy Ingredients Market | 2026-2036
North America Dairy Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dairy Ingredients Market Analytics
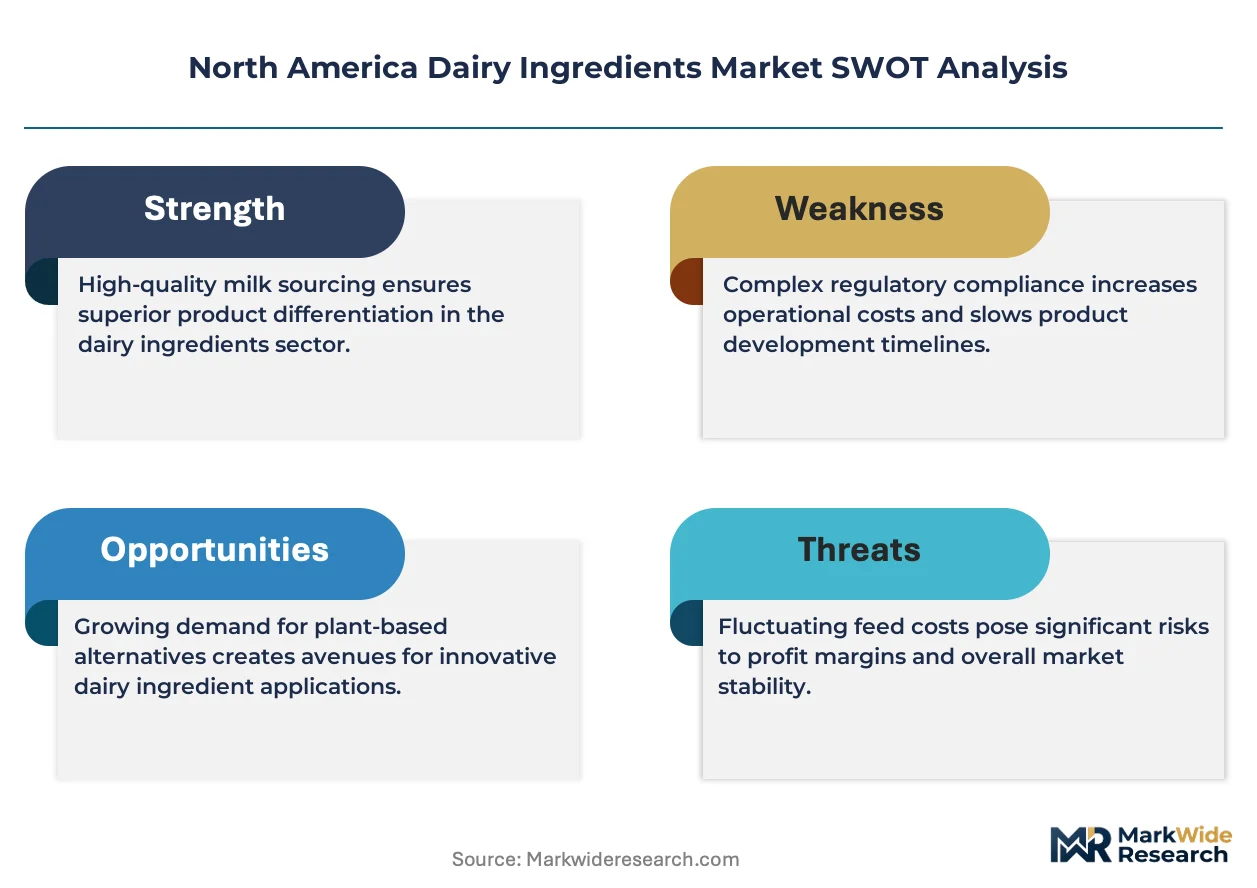
The EPA's Clean Air Act enforcement on dairy processing emissions is decoupling regional supply chains from legacy manufacturing nodes. Dairy Farmers of America leverages its cooperative structure to sustain volume leadership across fluid milk derivatives. Glanbia plc anchors its position through specialized whey protein isolate capacity in Idaho and Wisconsin. Leprino Foods Company dominates mozzarella and whey production through captive cheese manufacturing at scale.
North America dairy ingredients encompass dehydrated, fractionated, and concentrated milk-derived components standardized for protein content, fat ratio, moisture level, and microbiological purity. These ingredients function as functional binders, emulsifiers, and nutritional fortifiers across formulated foods and clinical nutrition. Whey protein commands premium positioning in nutritional supplements as sports recovery and senior nutrition applications expand. Milk powder retains mature volume leadership within bakery and confectionery channels where cost stability matters. Grade A quality specifications concentrate margin pools around infant formula and medical nutrition buyers demanding full traceability.
The USDA's Dairy Grading Branch enforces quality standards that gate market access for Grade A and organic classifications across interstate commerce. Health Canada and the FDA maintain divergent protein content labeling thresholds that complicate cross-border formulation strategies for multinational suppliers. State-level organic certification programs in Vermont and California add supplementary compliance layers for premium tier positioning. Stakeholders must monitor how pending amendments to the FDA Food Safety Modernization Act reshape pathogen testing protocols for powdered dairy exports.
Market Dynamics
The EPA's Clean Air Act enforcement on dairy processing emissions is decoupling regional supply chains from legacy manufacturing nodes. Suppliers face capital-intensive retrofits or relocation decisions as emission thresholds tighten across Wisconsin, Minnesota, and Iowa processing corridors.
Growth Catalysts
- Protein quality scoring mandates:The FDA's updated nutrition labeling rules for protein quality scoring are reshaping supplier certification requirements. Sports nutrition brands accelerate whey protein procurement to meet PDCAAS labeling standards.
- Upper Midwest processing concentration:Demand concentrates in the Wisconsin-Minnesota-Iowa dairy belt where fluid milk derivatives achieve lowest unit costs. Cooperative infrastructure supports volume scaling for fractionated ingredients.
- Fractionation technology maturation:Advanced membrane filtration and ion exchange processes enable higher-purity whey protein isolate production. Medical nutrition and infant formula buyers drive specification escalation.
Market Restraints
- Feed cost volatility:Corn and soybean meal price swings transmit directly to milk production economics. Dairy farmer margin compression constrains herd expansion in the Upper Midwest.
- Emission compliance capital burden:The EPA's Clean Air Act enforcement requires scrubber installations and energy recovery systems at legacy plants. Small and mid-scale processors face disproportionate retrofit costs.
- Plant protein substitution:Pea and oat protein isolates capture share in sports nutrition and bakery applications where complete amino acid profiles are not mandatory.
Strategic Opportunities
- Organic tier expansion:State-level organic certification programs in Vermont and California add supplementary compliance layers for premium tier positioning. Price premiums for organic dairy ingredients exceed conventional spreads.
- Medical nutrition channel development:Grade A quality specifications concentrate margin pools around infant formula and medical nutrition buyers demanding full traceability. Clinical enteral nutrition represents underpenetrated volume potential.
- Cross-border formulation harmonization:Health Canada and the FDA maintain divergent protein content labeling thresholds. Suppliers mastering dual-compliance protocols capture multinational brand accounts.
Industry Challenges
- Pathogen testing protocol adaptation:Pending amendments to the FDA Food Safety Modernization Act reshape testing protocols for powdered dairy exports. Validation timelines for rapid detection methods extend certification cycles.
- Skilled technician scarcity:Membrane filtration and chromatography operations require specialized operators. Rural processing locations face recruitment competition from urban biotech clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dairy Ingredients Market |
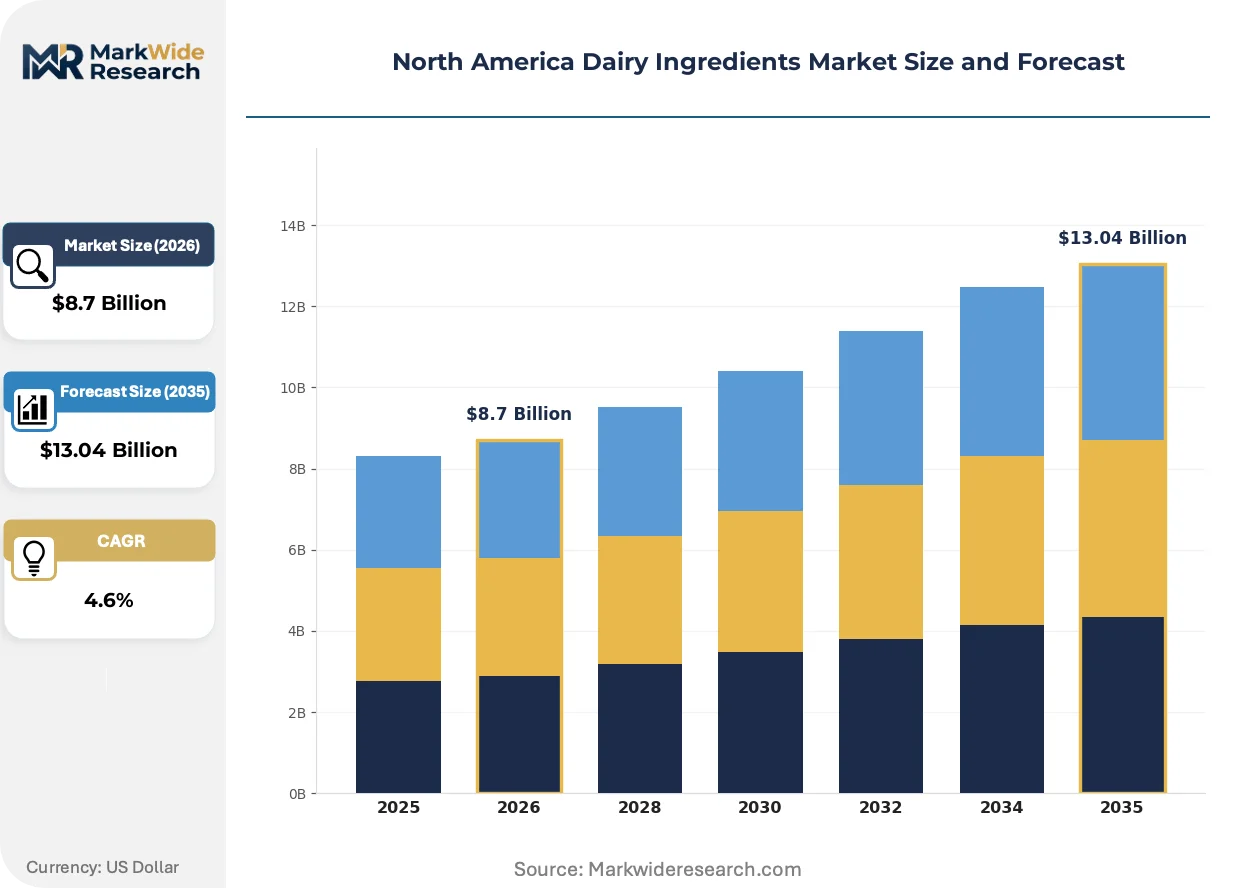
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Powder, Whey Protein, Cheese Powder, Cream Application: Dairy Products, Bakery, Confectionery, Nutritional Supplements End User: Food Manufacturers, Retailers, Food Service, Health Care Quality Grade: Grade A, Grade B, Organic, Non-GMO |
| Companies Covered | Arla Foods amba, Dairy Farmers of America, Fonterra Co-operative Group Ltd, Agropur Co-operative, Saputo, Inc., Land O'Lakes, Inc., Groupe Lactalis, Glanbia plc, Leprino Foods Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dairy Ingredients Market Evolving Landscape
Processing technology and regulatory precision are converging to redefine competitive positioning across whey fractionation and milk powder standardization. Suppliers invest in analytical capabilities and emission controls simultaneously.
Microfiltration and ultrafiltration membrane cascades are expanding into whey protein concentrate and isolate production. Sports nutrition brands and clinical nutrition formulators adopt higher-protein specifications at accelerating pace. This technology is expanding into mid-scale cooperative facilities previously limited to commodity powder output.
The FDA's updated nutrition labeling rules for protein quality scoring are compressing formulation flexibility. Multinational suppliers must maintain dual PDCAAS and PER calculation protocols for cross-border product lines. Infant formula and medical nutrition segments face the steepest compliance adaptation requirements.
Buyer specification consolidation is compressing supplier qualification cycles. Large sports nutrition brands and dairy cooperative procurement desks consolidate vendor panels around full-traceability suppliers. This concentration is most visible in the Upper Midwest, where Dairy Farmers of America and specialized whey processors compete for long-term supply agreements with volume guarantees.
North America Dairy Ingredients Market Segmentation
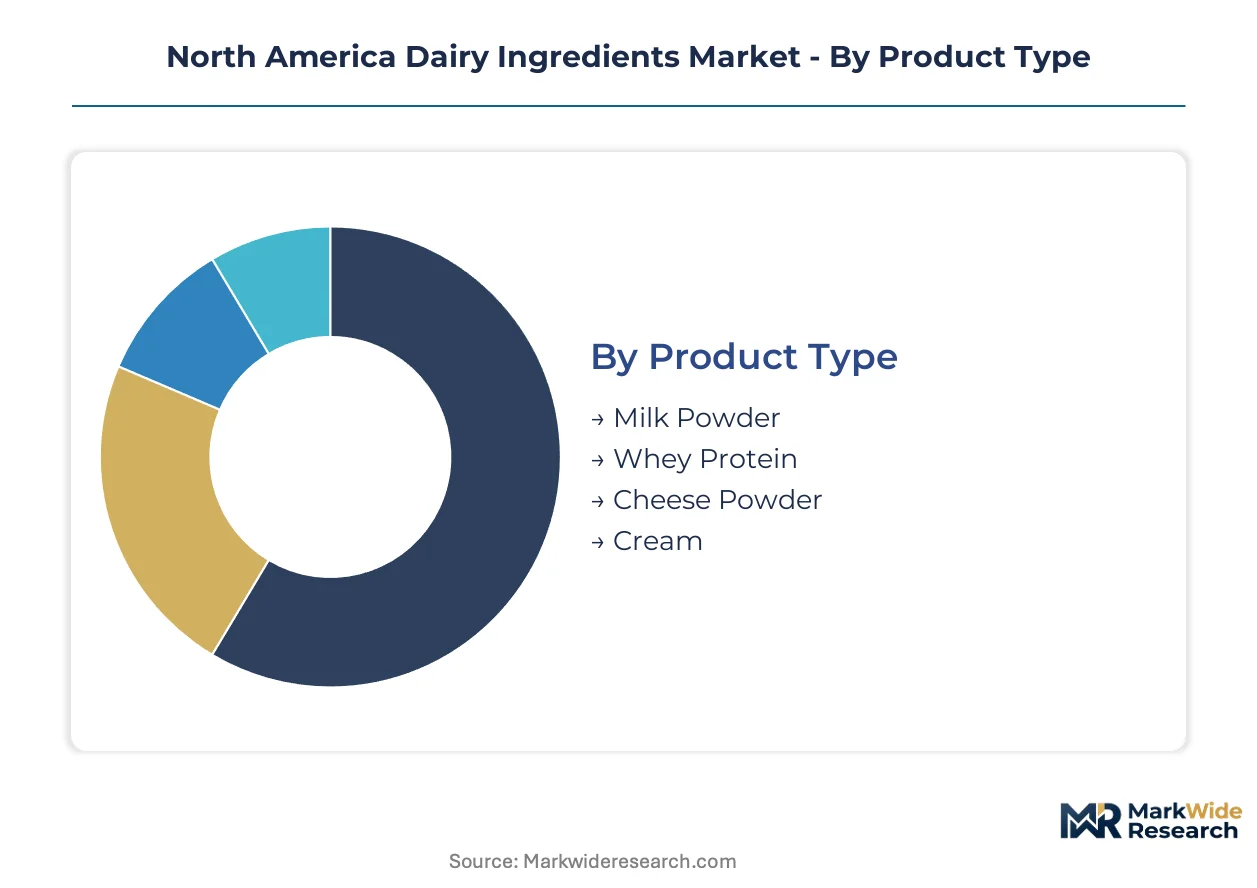
Dairy ingredient procurement in North America stratifies sharply across functional requirements and regulatory thresholds. Buyers select segments based on protein specification, microbiological purity, and traceability mandates rather than commodity pricing alone.
Product Type:
The customization-vs-standardization spectrum runs from commodity milk powders to precision-fractionated whey isolates requiring dedicated membrane infrastructure.
- Whey Protein:Fractionated concentrates and isolates deliver 80-90% protein content with defined amino acid profiles. Sports nutrition brands in the United States and Canada drive specification escalation for PDCAAS-compliant labeling. FDA protein quality scoring rules compress formulation flexibility for suppliers.
- Milk Powder:Dehydrated whole and skim milk powders standardize at 26-36% protein and 0.5-4% moisture. Bakery and confectionery channels in the Upper Midwest dairy belt prioritize cost stability over functional differentiation.
- Cheese Powder:Spray-dried cheese derivatives carry 35-55% fat content for flavor delivery. Snack seasoning and ready-meal applications concentrate demand.
- Cream:Concentrated butterfat products at 35-40% fat serve ice cream and premium dessert manufacturing. Cold chain requirements limit geographic sourcing radius.
Most installed capacity flows through milk powder. Expansion is steepest in whey protein.
Application:
Cost tier differentiation separates clinical-grade formulations from mass-market food manufacturing.
- Nutritional Supplements:Protein powders, meal replacements, and clinical nutrition require Grade A specifications with full lot traceability. Senior nutrition and sports recovery segments in the United States accelerate procurement of whey isolates.
- Dairy Products:Yogurt, cheese, and ice cream manufacturing consumes bulk milk powders and cream for texture and protein fortification. Cooperative supply agreements dominate volume flows.
- Bakery:Bread and pastry applications utilize non-fat dry milk for emulsification and browning. Price sensitivity constrains premium ingredient adoption.
- Confectionery:Chocolate and candy manufacturing demands milk powder with specific particle size and flavor neutrality. Seasonal demand patterns create procurement volatility.
Volume concentrates in dairy products. Margin expansion is climbing the fastest in nutritional supplements.
End User:
Customer type determines specification stringency and contract structure across the value chain.
- Food Manufacturers:Industrial formulators of packaged foods and beverages negotiate multi-year supply agreements with volume guarantees. Quality audits and certification maintenance consume supplier resources.
- Health Care:Enteral nutrition and medical food producers enforce Grade A standards with pathogen testing protocols exceeding FDA baseline requirements. Infant formula buyers demand single-source traceability.
- Food Service:Restaurant chains and institutional caterers prioritize cost-stable supply of cheese powder and cream for menu consistency.
- Retailers:Private label brands and specialty grocers source organic and non-GMO certified ingredients for premium positioning.
Contract volume flows through food manufacturers. Specification escalation is sharpest in health care.
Quality Grade:
Margin pools stratify across certification tiers with compliance cost barriers protecting premium positions.
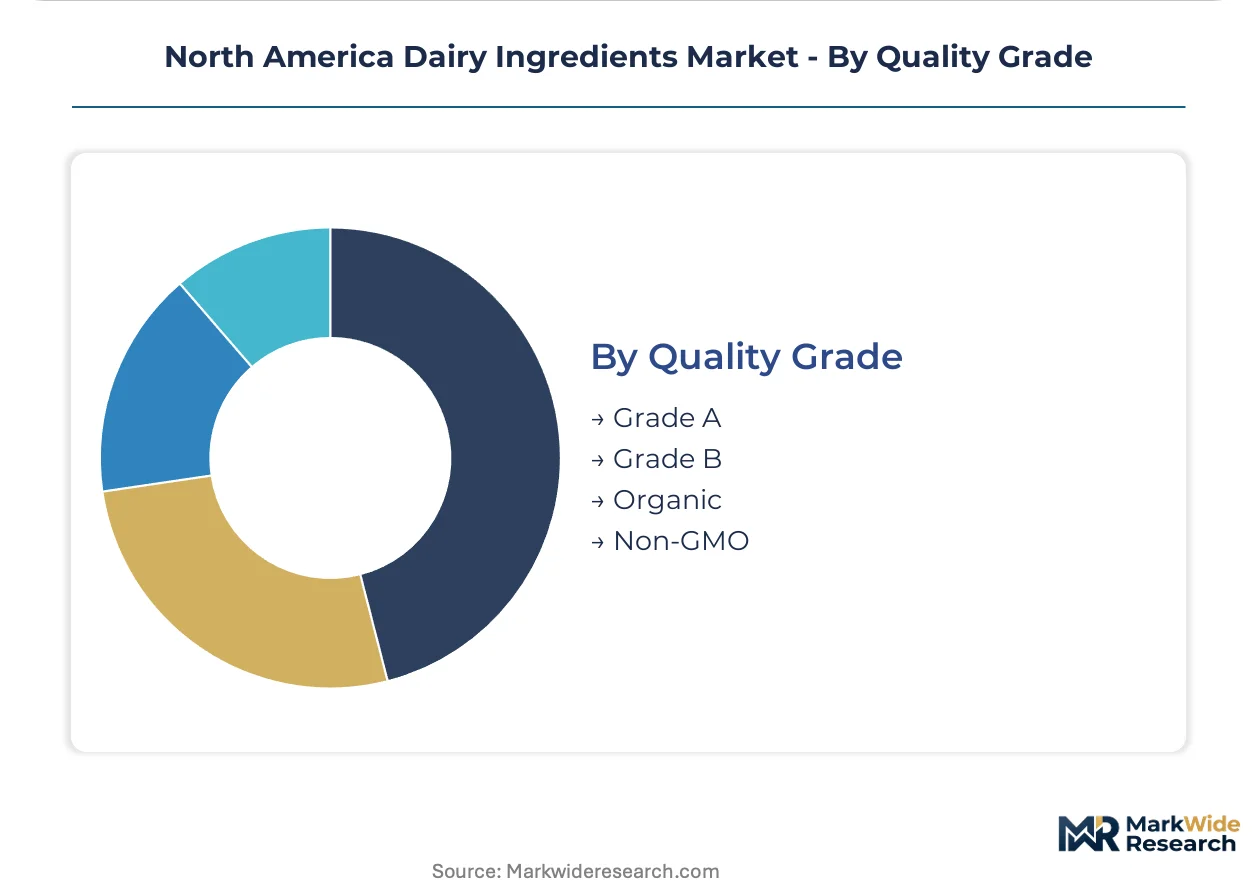
- Grade A:Full fluid milk origin with USDA Dairy Grading Branch enforcement enables interstate commerce access. Infant formula and medical nutrition buyers mandate this tier exclusively.
- Organic:State-level programs in Vermont and California add supplementary compliance layers. Price premiums exceed conventional spreads significantly.
- Non-GMO:Identity-preserved supply chains exclude genetically modified feed inputs. Verification costs limit supplier participation.
- Grade B:Manufacturing-grade milk derivatives serve industrial applications where microbiological thresholds permit higher somatic cell counts. Animal feed and non-food uses dominate offtake.
Most volume transacts at Grade A. Certification investment is expanding most quickly in organic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial dairy ingredient processing in North America traces its modern lineage to Wisconsin's cooperative creameries of the late 19th century, which established the Upper Midwest as the continent's primary concentration of fluid milk derivatives and fractionated protein capacity.
United States
Sports nutrition brands and infant formula manufacturers drive procurement of whey protein isolates and Grade A milk powders. The FDA's updated protein quality scoring rules compress formulation flexibility for cross-state suppliers. Processing gravity concentrates in Wisconsin, Minnesota, and Iowa, where Dairy Farmers of America and Leprino Foods operate major fractionation facilities.
Canada
Health Canada maintains divergent protein content labeling thresholds from FDA standards, complicating formulation strategies for multinational suppliers serving both markets. The Canadian Dairy Commission's supply management system stabilizes farmgate pricing but constrains herd expansion in Quebec and Ontario. Toronto and Montreal anchor industrial dairy processing for bakery and confectionery channels.
Mexico
Bakery and confectionery manufacturers import milk powders for cost-stable emulsification and browning applications. The Secretariat of Economy's dairy sector modernization programs support cold chain infrastructure expansion in central Mexico. Querétaro and Guanajuato host emerging processing clusters for cheese powder and cream derivatives.
California
State-level organic certification programs command price premiums exceeding conventional spreads for premium-tier positioning. The California Department of Food and Agriculture enforces supplementary compliance layers for Grade A and organic classifications. The Central Valley's dairy corridor sustains volume leadership in fluid milk derivatives despite feed cost volatility.
Idaho
Specialized whey protein isolate capacity anchors Glanbia's position in sports nutrition and medical nutrition supply chains. The Idaho State Department of Agriculture coordinates with USDA Dairy Grading Branch for interstate commerce access. The Magic Valley processing cluster leverages low-cost electricity for energy-intensive membrane filtration operations.
North America Dairy Ingredients Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with Grade A and organic specifications protecting price spreads. The vendor base organizes around cooperative structures, specialized fractionators, and diversified dairy conglomerates. Three archetypes dominate: cooperative-owned processors with captive milk supply, specialized whey fractionators with membrane filtration expertise, and diversified food conglomerates with cross-category dairy portfolios. Competitive moves concentrate on emission compliance retrofits and long-term supply agreements with volume guarantees.
Within the cooperative tier, Dairy Farmers of America and Fonterra Co-operative Group Ltd represent archetypes of member-owned volume leadership. Among specialized fractionators, Glanbia plc and Leprino Foods Company exemplify positions built on whey protein isolate capacity and captive cheese manufacturing. At the diversified end, Groupe Lactalis and Saputo, Inc. occupy positions spanning multiple dairy categories across North American markets.
| Leading Market Players |
|---|
| Arla Foods amba |
| Dairy Farmers of America |
| Fonterra Co-operative Group Ltd |
| Agropur Co-operative |
| Saputo, Inc. |
| Land O'Lakes, Inc. |
| Groupe Lactalis |
| Glanbia plc |
| Leprino Foods Company |
| Others |
Value Network & Pricing Analysis
Grade A certification ladders in North American dairy ingredients create divergent margin pools that simultaneously stratify pricing power and concentrate supply chain investment around USDA-inspected fluid milk corridors. Premium organic tiers command spreads exceeding conventional benchmarks while tethering procurement to Vermont and California state-level programs, whereas commodity milk powder flows through cost-optimized cooperative networks in the Upper Midwest.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs North American dairy ingredient transactions. Grade A quality specifications and organic certification status serve as primary price differentiation drivers, with infant formula buyers absorbing premiums for full traceability that bakery channels reject. Cost compression in commodity milk powder intensifies because corn and soybean meal volatility transmits directly to farmgate economics. Food manufacturers exhibit highest price sensitivity through multi-year volume-guarantee negotiations, while health care buyers prioritize specification compliance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for dairy ingredients center on membrane filtration equipment refurbishment and spent resin regeneration cycles that extend chromatography column lifespans. Supply concentrates in the United States, Canada, and Mexico, with fluid milk derivatives drawing from Wisconsin-Minnesota-Iowa processing corridors and specialized whey isolate capacity anchored in Idaho. Raw material dependencies rest on corn silage, alfalfa hay, and soybean meal for dairy herd nutrition. Single-source vulnerability emerges from EPA Clean Air Act enforcement decoupling legacy manufacturing nodes. Distribution runs through cooperative-owned logistics networks and multinational food conglomerate procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American dairy ingredients function as a geographic-arbitrage play where Idaho's low-cost electricity for membrane filtration operations contrasts with California's premium organic certification premiums, enabling margin capture through strategic facility placement.
For Market Incumbents: Acquire specialized whey protein isolate capacity in the Magic Valley region to consolidate sports nutrition supply relationships. Plant protein substitution from pea and oat isolates threatens volume retention in bakery and confectionery channels. Emission compliance retrofits at legacy Wisconsin plants represent critical defensive investment against EPA enforcement escalation. Backward integration into captive cheese manufacturing secures whey stream availability for fractionation expansion. For New Entrants and Emerging Players: The FDA's updated protein quality scoring rules in the United States open a window for PDCAAS-compliant whey isolate specialists to capture sports nutrition brand procurement. Medical nutrition and clinical enteral nutrition segments present underpenetrated white-space targets with Grade A specification barriers protecting margin pools. A go-to-market angle emphasizing dual-compliance protocols for Health Canada and FDA labeling thresholds unlocks multinational account access. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale cooperative processors possessing organic certification infrastructure and membrane filtration capabilities. Long-term viability across the next decade hinges on emission-compliant facility footprints and traceability-verified supply chains. Acquisition targets should demonstrate established relationships with infant formula or medical nutrition buyers demanding single-source lot tracking. Monitor EPA enforcement patterns in the Upper Midwest for early signals of supply chain displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Emission Compliance Retrofit | EPA Clean Air Act enforcement in Wisconsin and Minnesota compels scrubber installation at legacy processing plants. |
| Organic Certification Investment | Vermont and California state programs unlock premium tier positioning with spreads exceeding conventional benchmarks. |
| Membrane Filtration Scale-Up | Advanced ultrafiltration cascades in Idaho enable higher-purity whey protein isolate production for sports nutrition. |
| Dual-Compliance Protocol Development | Harmonized PDCAAS and PER calculation systems capture multinational brands serving FDA and Health Canada markets. |
| Long-Term Supply Agreement | Volume-guaranteed contracts with Dairy Farmers of America secure fluid milk derivative access for fractionation expansion. |
Research Methodology
Direct dialogue with dairy cooperative procurement managers, whey fractionation plant engineers, infant formula regulatory affairs specialists, and sports nutrition brand supply chain directors grounded qualitative findings across the North American dairy ingredients value chain. Secondary validation drew from USDA Dairy Grading Branch enforcement records, FDA Food Safety Modernization Act amendment filings, Health Canada labeling guidance documents, and EPA Clean Air Act compliance disclosures. Bottom-up capacity assessments at individual processing facilities triangulated against top-down demand modeling from end-use application channels.
Segmented outputs across product type, application, end user, and quality grade dimensions stabilized over the projection horizon through iterative refinement. CAGRs emerged from regression analysis against protein quality scoring adoption curves, emission compliance investment cycles, and organic certification penetration patterns. Feed cost volatility indices and dairy herd expansion constraints in the Upper Midwest informed supply-side elasticity assumptions.
Revisions become necessary when EPA enforcement timelines accelerate, FDA pathogen testing protocols for powdered dairy exports materialize, or plant protein substitution rates in sports nutrition exceed modeled thresholds. Practitioners should monitor Health Canada-FDA labeling harmonization negotiations and membrane filtration technician wage inflation in rural processing locations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Soy Protein Market
Ingredients
Pepsin Market
Ingredients
South America Feed Yeast Market
Ingredients
Volatile Fatty Acids Market
Ingredients
Sesame Oil Market
Ingredients
Asia-Pacific Yeast and Yeast Extract Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Homecare Ingredients Market
Ingredients
Confectionery Ingredients Market
Ingredients
Dried Distillers' Grains with Soluble Market
Ingredients
Coconut Oil Market
Ingredients
Almond Flour Market
Ingredients
Horehound Extract Market
Ingredients
Mineral Premix Market
Ingredients
Cacao Bean Market
Ingredients
Philippines Edible Oils & Fats Market