
 Global Tomato Powder Market | 2026-2036
Global Tomato Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tomato Powder Market Foresight
Multi-source procurement from both captive tomato processing operations and third-party ingredient specialists is pivoting toward vertically integrated suppliers with cold-chain-adjacent drying capabilities. COFCO Tunhe leverages its Xinjiang tomato belt sourcing to control raw material quality from seed to powder. Conesa anchors European demand through its Murcia-region processing infrastructure. Lycored differentiates via carotenoid-retention technology in its spray-dried offerings.
Tomato powder is a dehydrated tomato product typically manufactured through spray-drying or freeze-drying of tomato pulp concentrate to below five percent moisture, yielding a free-flowing red powder with standardized lycopene content for industrial formulation. Its primary commercial purpose is to deliver concentrated tomato flavor, color, and nutritional value in dry-format food systems where water activity constraints prohibit paste or fresh tomato use. Spray-dried tomato powder dominates volume due to cost efficiency in beverage flavoring and soup base applications, while freeze-dried variants command premium positioning in nutraceutical capsules where heat-sensitive vitamin retention determines efficacy. Organic tomato powder occupies a narrowing but high-margin niche as European retailers tighten pesticide-residue specifications under EFSA-aligned private standards.
FDA food facility registration requirements and FSSC 22000 certification shape market access for suppliers targeting US food and beverage manufacturers, while EU REACH and CE-marked processing equipment standards govern import eligibility for non-European processors. China's SAMR national food safety standards and GB specifications for dehydrated vegetables create a dual-compliance burden for exporters serving both Western and Chinese markets. Stakeholders must monitor evolving lycopene-content labeling claims and novel food approvals as nutraceutical applications expand beyond traditional food processing demand.
Market Dynamics
Food processors are consolidating supplier relationships around vertically integrated tomato processors with captive drying infrastructure, compressing procurement cycles and raising barriers for standalone ingredient traders.
Growth Catalysts
- EU Green Deal sustainability mandates:REACH compliance requirements on food contact materials are disqualifying non-certified suppliers and redirecting volume toward processors with verified carbon-accounting systems.
- Ready-meal sector expansion:Shelf-stable tomato powder replaces paste in retort pouch formulations where water activity constraints prohibit liquid ingredients.
- Spray-drying efficiency gains:Advanced atomization technologies are reducing energy consumption per kilogram of powder output in high-volume beverage flavoring applications.
Market Restraints
- Fresh tomato input volatility:Xinjiang and California growing regions face irrigation water allocation uncertainty that transmits directly to concentrate pricing.
- Freeze-drying capex intensity:Vacuum sublimation equipment requires substantially higher capital deployment than spray-drying, limiting premium powder supply expansion.
- Substitution by tomato paste:Cost-sensitive soup manufacturers in emerging markets revert to paste where cold-chain reliability permits.
Strategic Opportunities
- India nutraceutical penetration:FSSAI novel food approval pathways for lycopene-fortified supplements remain underutilized relative to population scale.
- SAMR-aligned organic certification:China's national food safety standards for pesticide residue create premium positioning for certified organic powder in domestic retail channels.
- Blockchain traceability integration:Immutable seed-to-powder records satisfy EU CSRD supply-chain disclosure requirements for institutional foodservice buyers.
Industry Challenges
- FSSC 22000 certification timelines:US-bound suppliers face 12-18 month facility validation periods that delay market entry.
- Carotenoid retention expertise:Heat-sensitive lycopene stabilization requires specialized process engineering talent concentrated in Mediterranean processing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tomato Powder Market |
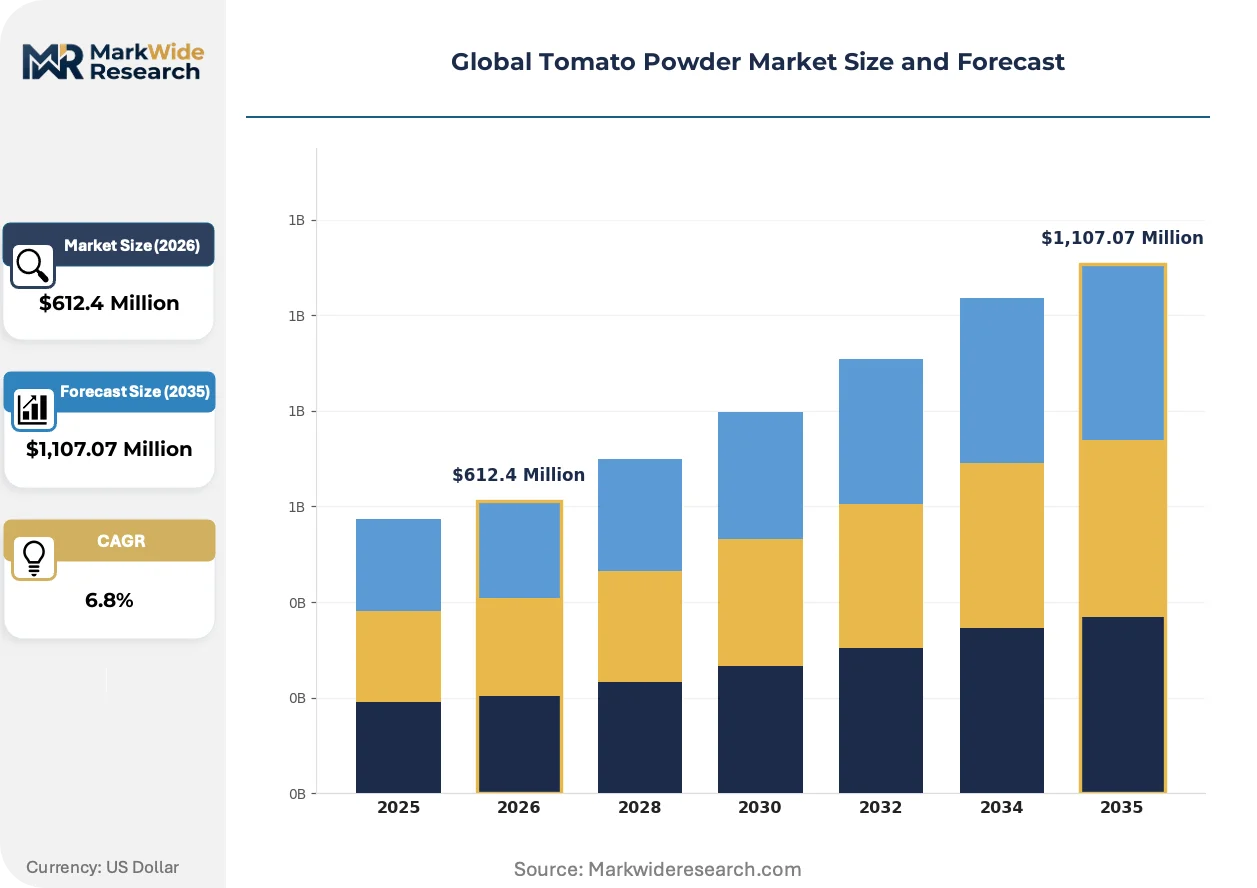
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dehydrated Tomato Powder, Freeze-Dried Tomato Powder, Spray-Dried Tomato Powder, Organic Tomato Powder Application: Food Processing, Beverage Flavoring, Nutraceuticals, Cosmetic Products, Animal Feed Packaging Type: Stand-Up Pouches, Sachets, Bulk Bags, Resealable Bags, Drums End User: Food & Beverage Manufacturers, Dietary Supplement Producers, Personal Care Companies, Feed Mills |
| Companies Covered | COFCO Tunhe Tomato Co. Ltd., Kagome Co. Ltd., Conesa Group, Aarkay Food Products Ltd., Diana Foods Inc., Transa S.A., Gansu Dunhuang Seed Industry Fruit and Vegetable Products Co. Ltd., Cham Foods, Lycored, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tomato Powder Market Shifts & Advancements
Processing technology convergence with digital traceability systems is compressing quality verification cycles and enabling real-time specification adjustments during production runs.
Low-temperature spray-drying with nitrogen blanketing is rewriting lycopene retention benchmarks in standard-grade powder. Nutraceutical formulators in Germany and Switzerland are adopting this modified process at pilot scale. The technology is compressing the historical price gap between freeze-dried and spray-dried variants.
REACH Annex XVII restrictions on food contact substances are forcing reformulation of packaging films used for tomato powder bulk shipment. European importers are rejecting non-compliant flexible intermediate bulk containers. Suppliers serving Netherlands and UK retail channels are accelerating migration to ECHA-registered barrier materials.
Direct contracting between tomato processors and ready-meal manufacturers is displacing layered distributor networks. Large European and North American foodservice operators now specify origin-verified powder lots with single-source documentation. This pattern is most visible in Germany, where Edeka and Metro Group procurement teams have eliminated secondary trading intermediaries.
Global Tomato Powder Market Segmentation
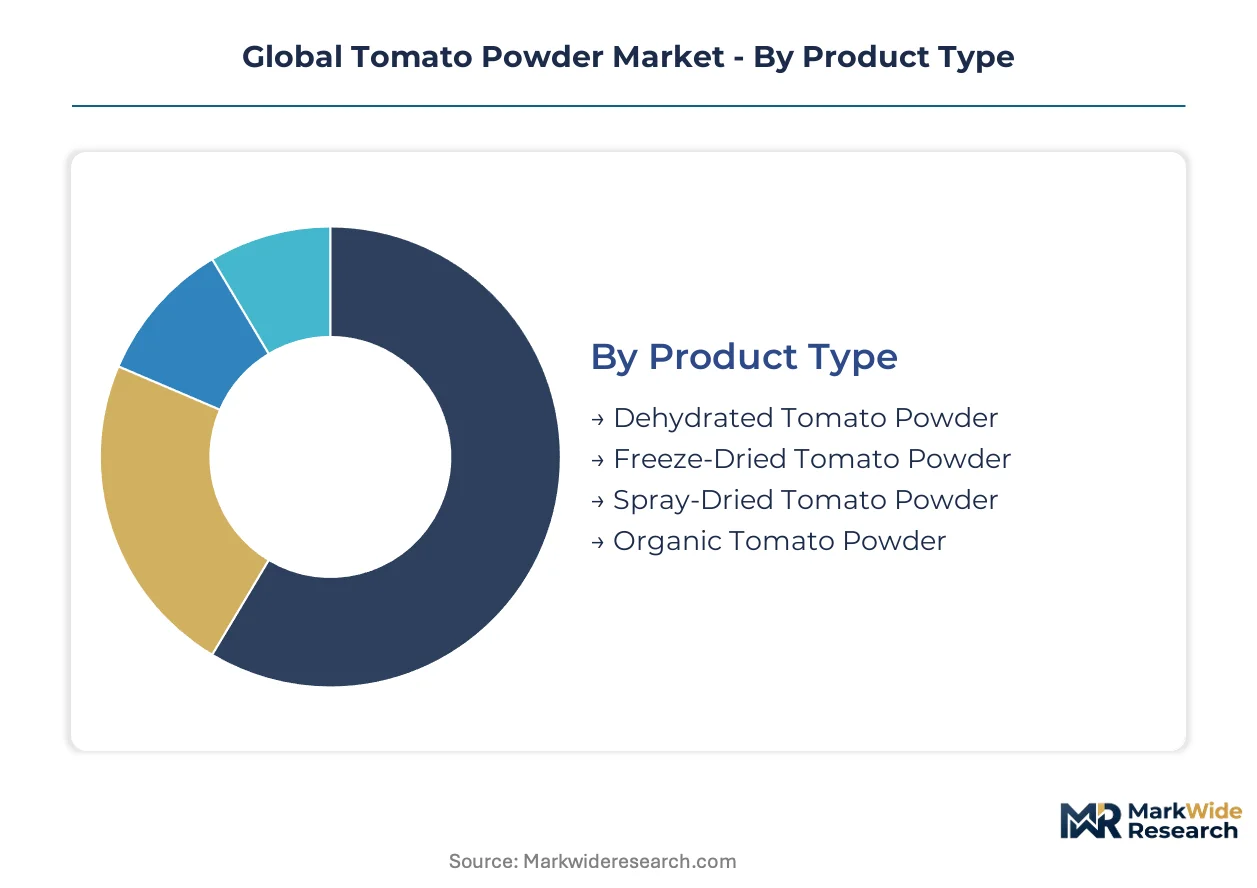
Tomato powder segmentation reveals a market bifurcated between commodity-scale food processing demand and precision-formulated nutraceutical applications. Understanding these divides enables suppliers to align drying technology investments with margin profiles and compliance requirements.
Product Type:
Spray-dried variants dominate tonnage, while freeze-dried commands unit premiums in pharmaceutical-grade applications.
- Dehydrated Tomato Powder:Conventional hot-air dehydration produces irregular particle sizes with moderate lycopene degradation. Demand concentrates in emerging-market soup manufacturers seeking cost-efficient tomato flavor delivery where color consistency requirements remain relaxed.
- Freeze-Dried Tomato Powder:Vacuum sublimation preserves cellular structure and heat-sensitive carotenoids at 95%+ retention rates. Nutraceutical capsule formulators in Germany and Switzerland source this grade for lycopene supplement claims requiring stability validation.
- Spray-Dried Tomato Powder:Atomized concentrate drying yields free-flowing spheres with standardized moisture below 5%. Beverage flavoring houses in the US deploy this grade for instant drink mixes where solubility speed determines formulation acceptance.
- Organic Tomato Powder:Certified cultivation with EFSA-aligned residue limits commands 40-60% premiums over conventional. European retail private-label programs specify this grade for clean-label ready-meal positioning.
Mature deployment sits with Spray-Dried Tomato Powder. Newer deployment is concentrated in Organic Tomato Powder.
Application:
Food processing absorbs volume, but nutraceuticals generate margin expansion through lycopene-content specifications.
- Food Processing:Sauce, soup, and ready-meal manufacturers incorporate powder for shelf-stable tomato flavor without cold-chain dependency. Retort pouch producers in Italy and Spain specify spray-dried grades for water-activity-controlled formulations.
- Beverage Flavoring:Instant drink and smoothie base applications demand rapid-dissolving particle engineering. Japanese beverage compounders prioritize low-hygroscopicity variants for humidity-stable premixes.
- Nutraceuticals:Lycopene extraction and direct encapsulation require freeze-dried or nitrogen-blanketed spray-dried inputs with verified carotenoid retention. Swiss and German supplement brands lead procurement for prostate health positioning.
- Cosmetic Products:Antioxidant serum and mask formulations utilize microfine tomato powder for topical lycopene delivery. South Korean skincare manufacturers drive specification development for particle sizes below 50 microns.
- Animal Feed:Poultry and aquaculture feed incorporates powder as natural colorant for egg yolk and flesh pigmentation. Chinese feed mills source bulk spray-dried grades for cost-controlled integration.
Established demand anchors Food Processing. Steepest expansion trajectory runs through Nutraceuticals.
Packaging Type:
Format selection tracks customer scale, with industrial buyers favoring bulk formats and retail channels demanding convenience features.
- Stand-Up Pouches:Flexible format with resealable zipper suits specialty retail and foodservice portion control. European organic brands specify high-barrier laminates for moisture protection.
- Sachets:Single-serve units serve instant soup and beverage sampling programs. Southeast Asian convenience food marketers deploy this format for on-the-go consumption.
- Bulk Bags:Flexible intermediate bulk containers carry 500-1000kg loads for industrial food processors. REACH-compliant barrier materials are displacing conventional PE constructions in EU-bound shipments.
- Resealable Bags:Consumer retail format with zip-lock closure targets home cooks and small-scale food manufacturers. US club store channels specify this grade for warehouse packaging.
- Drums:Steel or fiber drums with liner bags protect hygroscopic powder during ocean freight. Nutraceutical ingredient distributors in the Netherlands and Germany require UN-certified drums for pharmaceutical-grade material.
Volume concentration rests with Bulk Bags. Premium positioning clusters around Stand-Up Pouches.
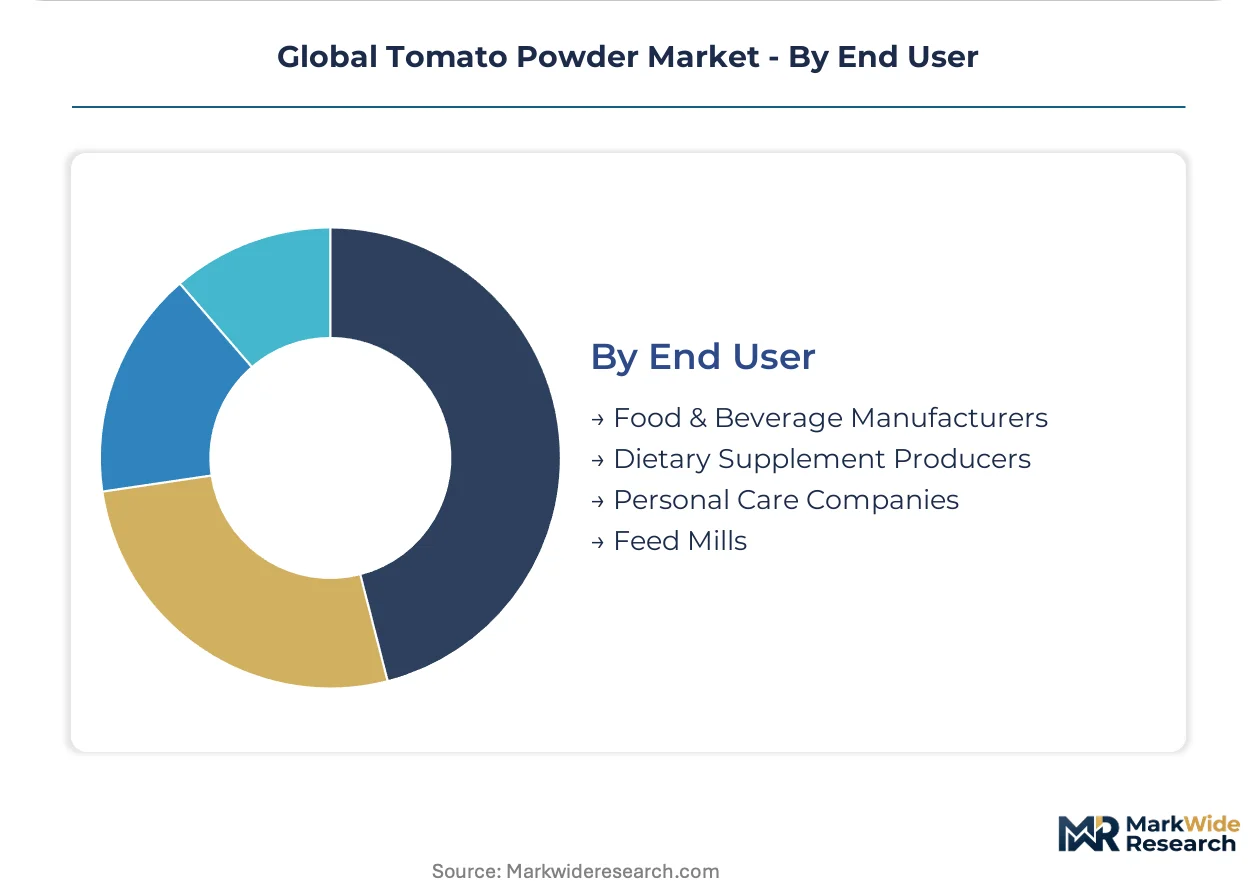
End User:
Customer type determines specification stringency, from food-grade compliance to pharmaceutical validation tiers.
- Food & Beverage Manufacturers:Ready-meal, sauce, and soup producers specify powder for formulation stability and lot-to-lot consistency. Major European retailers now mandate origin-verified documentation with blockchain traceability.
- Dietary Supplement Producers:Capsule and tablet formulators require COA-verified lycopene content and heavy-metal testing. German and Swiss brands lead in novel food approval pathways for lycopene health claims.
- Personal Care Companies:Cosmetic formulators prioritize micronized particle sizes and microbial specification compliance. South Korean and Japanese skincare manufacturers drive demand for cosmetic-grade certification.
- Feed Mills:Poultry and aquaculture operations utilize powder for natural pigmentation without synthetic additive labeling. Chinese integrated agribusinesses source through direct processor contracts for cost control.
Procurement scale concentrates with Food & Beverage Manufacturers. Specification intensity peaks with Dietary Supplement Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang's tomato belt anchors raw material supply for powder production, with irrigation-fed processing clusters converting paste concentrate into dehydrated formats for export and domestic formulation.
China
COFCO Tunhe and Gansu Dunhuang Seed Industry control captive drying infrastructure serving both local ready-meal manufacturers and export processors. SAMR national food safety standards and GB specifications for dehydrated vegetables create compliance benchmarks for domestic retail channels. Xinjiang's Changji Hui Autonomous Prefecture hosts the country's largest spray-drying capacity for industrial-grade powder output.
United States
Beverage flavoring houses and soup base manufacturers drive procurement of spray-dried grades for instant formulation applications. FDA food facility registration requirements and FSSC 22000 certification shape supplier qualification timelines for domestic food processors. California's Central Valley processing clusters face irrigation water allocation uncertainty that transmits directly to concentrate input costs.
Germany
Ready-meal manufacturers and nutraceutical formulators source origin-verified powder lots with blockchain traceability documentation. EU Green Deal sustainability mandates and REACH compliance requirements on food contact materials disqualify non-certified suppliers. Hamburg and Frankfurt serve as primary import gateways for bulk shipments from Mediterranean and Chinese processors.
Spain
Conesa anchors European demand through Murcia-region processing infrastructure with integrated spray-drying capabilities. EFSA-aligned private standards for pesticide residue limits govern organic certification requirements for retail private-label programs. The Campo de Cartagena agricultural district supplies fresh tomato feedstock to regional dehydration facilities.
India
FSSAI novel food approval pathways for lycopene-fortified supplements remain underutilized relative to population scale and nutraceutical demand potential. BIS standards for dehydrated vegetables create quality benchmarks for domestic manufacturers. Maharashtra's Nashik district hosts emerging processing capacity targeting both food-grade and supplement-grade powder production.
Global Tomato Powder Market Competitive Landscape
Global majors compete with regional champions across captive supply chain control, with market structure tiering between vertically integrated processors and standalone ingredient specialists. Three to five dominant operators anchor volume procurement relationships with institutional foodservice buyers. Strategic archetypes include seed-to-powder integrators, carotenoid-retention technology specialists, and regional paste-to-powder converters. Competitive moves concentrate on backward integration into tomato cultivation and certification-driven capacity expansion for EU and North American market access.
Among China-based integrated processors, COFCO Tunhe Co. Ltd. and Gansu Dunhuang Seed Industry Fruit and Vegetable Products Co. Ltd. exemplify the captive supply chain archetype with Xinjiang belt sourcing control. Lycored occupies a position representing technology-differentiated specialists focused on carotenoid stabilization. These three anchors illustrate the competitive spectrum from commodity-scale volume production to premium-grade nutraceutical positioning.
| Leading Market Players |
|---|
| COFCO Tunhe Tomato Co. Ltd. |
| Kagome Co. Ltd. |
| Conesa Group |
| Aarkay Food Products Ltd. |
| Diana Foods Inc. |
| Transa S.A. |
| Gansu Dunhuang Seed Industry Fruit and Vegetable Products Co. Ltd. |
| Cham Foods |
| Lycored |
| Others |
Supply & Pricing Matrix
Xinjiang irrigation water allocation uncertainty feeds directly into concentrate input costs, transmitting volatility through spray-dried grades to ready-meal manufacturers while freeze-dried premiums absorb upstream shocks through nutraceutical contract structures.
Pricing Analysis
Certification bundling separates REACH-compliant European deliveries from unverified Asian spot sales, with FSSC 22000 validation commanding 15-20 point premiums for US-bound shipments. Three-tier pricing structure across organic, nitrogen-blanketed spray-dried, and conventional hot-air grades tracks lycopene retention specifications and residue testing intensity. Cost compression in standard spray-dried tiers is intensifying because Chinese processors are absorbing Xinjiang water-cost volatility to defend export share. Emerging-market soup manufacturers exhibit highest price sensitivity, while Swiss nutraceutical formulators prioritize carotenoid retention over unit economics.
Supply Chain Analysis
Seasonal labor availability in Xinjiang's Changji Prefecture and Murcia's Campo de Cartagena constrains peak-harvest processing throughput, forcing capacity buffers into annual planning. Raw material sourcing draws from Xinjiang's tomato belt, California's Central Valley, and Spain's Mediterranean coast, with paste-to-powder conversion resting on spray-drying infrastructure concentration in China and Spain. Single-source vulnerability sits with Xinjiang water-rights allocation decisions that cascade through global concentrate supply. Distribution runs through Rotterdam and Hamburg bulk terminals for European formulation houses, with direct processor-to-manufacturer contracting displacing layered trader networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-temperature nitrogen-blanketed spray-drying is displacing legacy hot-air dehydration as the dominant process technology, compressing the historical premium gap with freeze-dried grades and forcing incumbent reinvestment cycles.
For Market Incumbents: Deploy blockchain traceability infrastructure to defend shelf space against direct-contracting ready-meal manufacturers demanding seed-to-powder documentation. COFCO Tunhe's captive Xinjiang sourcing and Lycored's carotenoid retention patents illustrate defensive moats against commodity traders facing REACH disqualification. Capacity addition in Murcia-region spray-drying with EFSA-aligned organic certification anchors European retail access. For New Entrants and Emerging Players: Nitrogen-blanketed spray-drying pilot capacity offers entry into German nutraceutical supply chains where lycopene retention requirements have historically frozen out non-freeze-dried suppliers. India's FSSAI novel food approval pathway for lycopene supplements remains underpenetrated relative to population scale, presenting white-space expansion for carotenoid-stabilization specialists. Direct technical sales to Swiss capsule formulators bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor Mediterranean-region processors with idle spray-drying capacity and pending REACH packaging compliance investments. Long-term viability centers on backward integration into irrigation-secure tomato cultivation or patented low-temperature drying IP. Watch EU CSRD supply-chain disclosure enforcement as inflection indicator for traceability-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Irrigation-Secure Cultivation | Xinjiang water-rights volatility makes controlled sourcing a margin defense mechanism for powder processors. |
| Nitrogen-Blanketed Spray-Drying Capacity Expansion | German nutraceutical formulators are adopting this modified process to compress freeze-dried premium gaps. |
| Blockchain Traceability System Deployment | Edeka and Metro Group procurement teams now mandate immutable seed-to-powder documentation. |
| REACH-Compliant Packaging Migration | Netherlands and UK retail channels are rejecting non-ECHA-registered flexible intermediate bulk containers. |
| FSSAI Novel Food Approval Pursuit | Indian lycopene supplement penetration lags population scale, creating first-mover positioning for approved suppliers. |
Research Methodology
Trade flow databases, EFSA pesticide residue monitoring reports, and SAMR national food safety standards formed the secondary backbone, cross-referenced with primary interviews of spray-drying plant engineers, ready-meal procurement directors, nutraceutical formulation scientists, and REACH compliance officers. Bottom-up capacity modeling across Xinjiang, Murcia, and California processing clusters was triangulated against top-down demand estimates from beverage flavoring houses and dietary supplement contract manufacturers.
Historical trendline analysis of lycopene-content pricing spreads and organic certification premiums informed projection frameworks across the analysis window. Segmentation dimensions modeled include drying technology tier, application end-use, certification grade, and regional regulatory cluster. CAGRs were derived from installed capacity utilization rates and substitution elasticity between paste and powder formats in retort pouch formulations.
Several conditions sit outside the modeled scope, including abrupt Xinjiang irrigation policy changes, EFSA novel food approval reversals for lycopene health claims, and breakthrough freeze-drying capex efficiency gains. Forecasts reflect documented assumptions about water allocation stability and REACH enforcement intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Oak Chips White Extract Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
Asia-Pacific Prebiotic Ingredients Market
Ingredients
Global Pregelatinized Starch Market
Ingredients
Canada Soy Protein Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Specialty Fats and Oils Market
Ingredients
Mastic Gum Market
Ingredients
Commercial Amino Acids Market
Ingredients
Vegetable Fats Market
Ingredients
Cheese Powder Market
Ingredients
United States Avocado Oil Market
Ingredients
US Vegetable Oil Market
Ingredients
Rice Bran Oil Market
Ingredients
Global Distillers Corn Oil Market