
 Baking Ingredients Market | 2026-2036
Baking Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Baking Ingredients Market Analysis
Multi-source procurement toward regional ingredient mills is rebalancing supply chain risk for industrial bakers. Cargill Incorporated leverages its North American grain origination network to secure flour supply contracts. Kerry Group Plc anchors its position through specialized enzyme and emulsifier portfolios for clean-label applications. Lesaffre dominates global yeast supply through fermentation technology leadership and geographic manufacturing scale.
Baking ingredients encompass flours, leavening agents, fats, emulsifiers, and enzymes formulated to control dough rheology, moisture retention, and shelf stability in finished baked goods. Wheat flour protein content, typically ranging from 8% to 14%, determines gluten network strength for specific bread and pastry applications. Enzyme-modified flours and specialized yeast strains capture expanding margin pools as bakeries reformulate for extended shelf life without chemical preservatives. Food manufacturers represent the fastest-growing end-user channel, driving bulk procurement of standardized ingredient systems for private-label production.
The FDA governs GRAS determinations for novel enzymes and emulsifiers entering U.S. commercial baking, while EFSA evaluates food additive safety under EU regulatory frameworks. BIS certification requirements in India mandate quality standards for imported wheat derivatives and packaged baking inputs. Stakeholders must monitor evolving clean-label definitions and regional allergen labeling mandates to maintain formulation compliance and market access across jurisdictions.
Market Dynamics
The EU Green Deal's sustainable sourcing mandates are forcing industrial bakers to requalify entire supplier bases, while enzyme-modified flours and specialized yeast strains capture expanding margin pools as bakeries reformulate for extended shelf life without chemical preservatives.
Growth Catalysts
- Clean-label reformulation:Bakeries are eliminating chemical preservatives through enzyme technology and fermentation science, creating pull for specialized ingredient portfolios across industrial production lines.
- EU regulatory mandates:The EU Green Deal's sustainable sourcing requirements are accelerating supplier requalification cycles and favoring ingredient systems with verified traceability documentation.
- Food manufacturer channel expansion:Private-label producers in China, India, and Brazil are driving bulk procurement of standardized ingredient systems for regional bakery product manufacturing.
Market Restraints
- Wheat protein volatility:Protein content fluctuations in North American and Black Sea wheat harvests create formulation inconsistency for high-gluten bread applications requiring 12-14% protein thresholds.
- Yeast supply concentration:Global fermentation capacity clusters in Western Europe and select Asian manufacturing hubs, creating geographic risk exposure for just-in-time bakery operations.
- Emulsifier regulatory friction:EFSA's evolving food additive safety evaluations under EU frameworks are extending approval timelines for novel emulsifier chemistries targeting clean-label positioning.
Strategic Opportunities
- Brazilian industrial baking expansion:Food manufacturers in São Paulo and Minas Gerais states are scaling automated production lines, creating demand for bulk enzyme and emulsifier systems with technical service support.
- Dual carbon alignment in China:NMPA and MEE guidelines on carbon intensity are incentivizing domestic mills to source low-carbon wheat derivatives for bakery ingredient production.
- Direct-to-bakery digital platforms:Specialized ingredient distributors are bypassing traditional wholesale channels to connect regional mills with artisan bakery clusters in Indian metropolitan markets.
Industry Challenges
- Fermentation technologist scarcity:Industrial bakeries face recruitment gaps for specialists capable of optimizing yeast strain performance across variable temperature and humidity conditions.
- Clean-label certification timelines:BIS quality standard verification for imported wheat derivatives in India extends procurement lead times by 8-12 weeks for new supplier onboarding.
- Legacy formulation integration:Replacing chemical preservatives with enzyme-based shelf-life extension requires revalidation of entire production parameters without line shutdown tolerance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baking Ingredients Market |
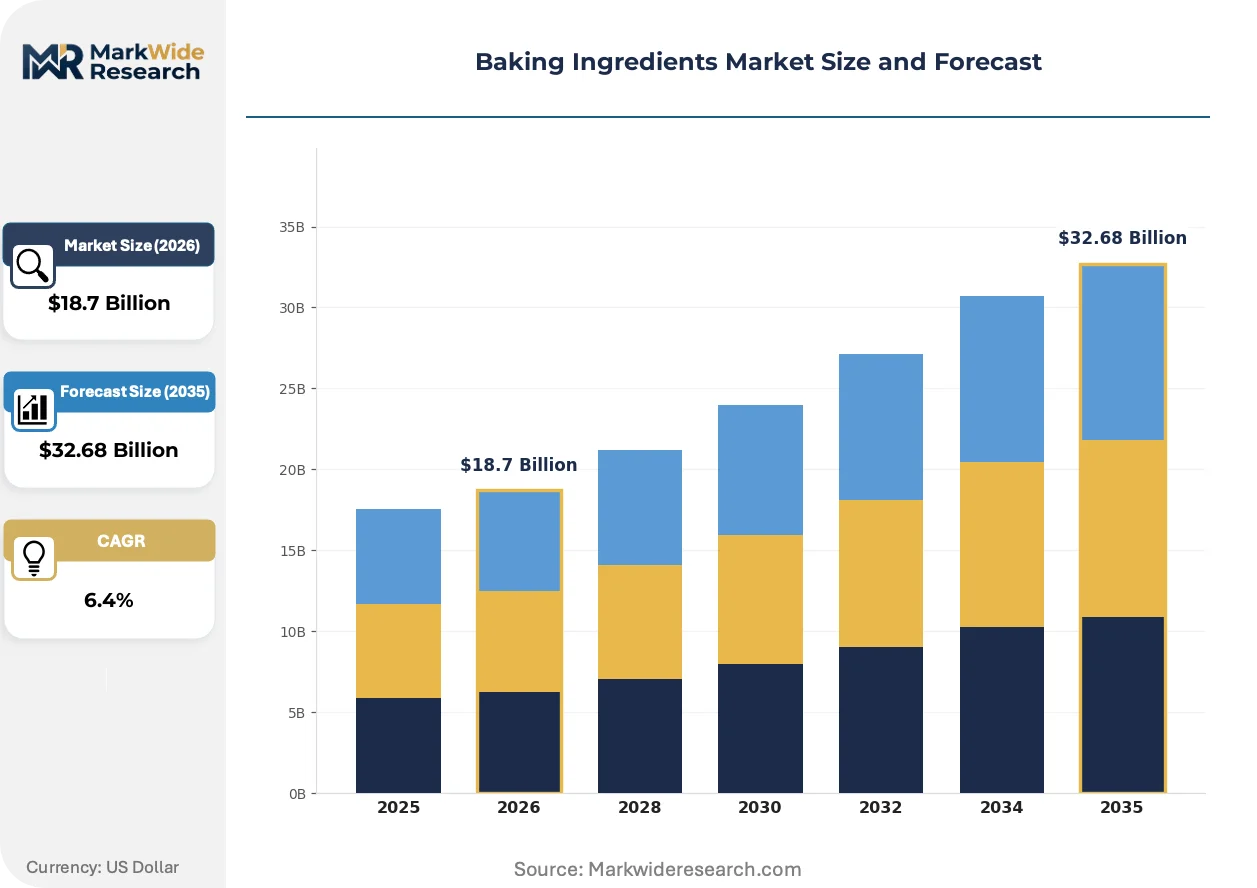
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flours, Sugars, Baking Powder, Yeast Application: Breads, Cakes, Pastries, Cookies End User: Bakeries, Restaurants, Home Bakers, Food Manufacturers Packaging Type: Bags, Boxes, Tubs, Sachets |
| Companies Covered | Koninklijke DSM N.V., Corbion, Cargill Incorporated, AAK AB, Lesaffre, Archer Daniels Midland Company, Kerry Group Plc, BASF SE, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baking Ingredients Market Emerging Trajectories
Active enzyme engineering and regional supply chain reconfiguration are compressing traditional ingredient sourcing models while regulatory frameworks accelerate clean-label adoption timelines across industrial baking.
Enzyme-modified flour systems incorporating amylase and xylanase blends are consolidating performance advantages for industrial bread manufacturers seeking extended freshness windows without calcium propionate or sorbate additives. Food manufacturers in Germany and the Netherlands have adopted these systems at scale for private-label sandwich bread production. The technology is consolidating margin pools toward enzyme suppliers with fermentation capabilities while marginalizing commodity flour traders lacking technical service depth.
EFSA's tightened food additive safety evaluations under EU regulatory frameworks are compressing approval pathways for novel emulsifiers targeting clean-label positioning. Industrial bakers are responding by accelerating reformulation timelines and pre-qualifying alternative ingredient systems before regulatory determinations finalize. The enzyme and leavening agent segments face the most acute compliance pressure, with manufacturers stockpiling GRAS-affirmed alternatives to maintain formulation continuity.
Artisan bakeries are consolidating procurement volumes through regional mill cooperatives, displacing traditional national distributor relationships that dominated ingredient sourcing for decades. This channel compression is most visible in French and Italian metropolitan clusters where bakery associations negotiate directly with wheat processors for protein-specified flour contracts. The shift is forcing ingredient suppliers to reconfigure sales organizations around technical service rather than bulk commodity logistics.
Baking Ingredients Market Segmentation
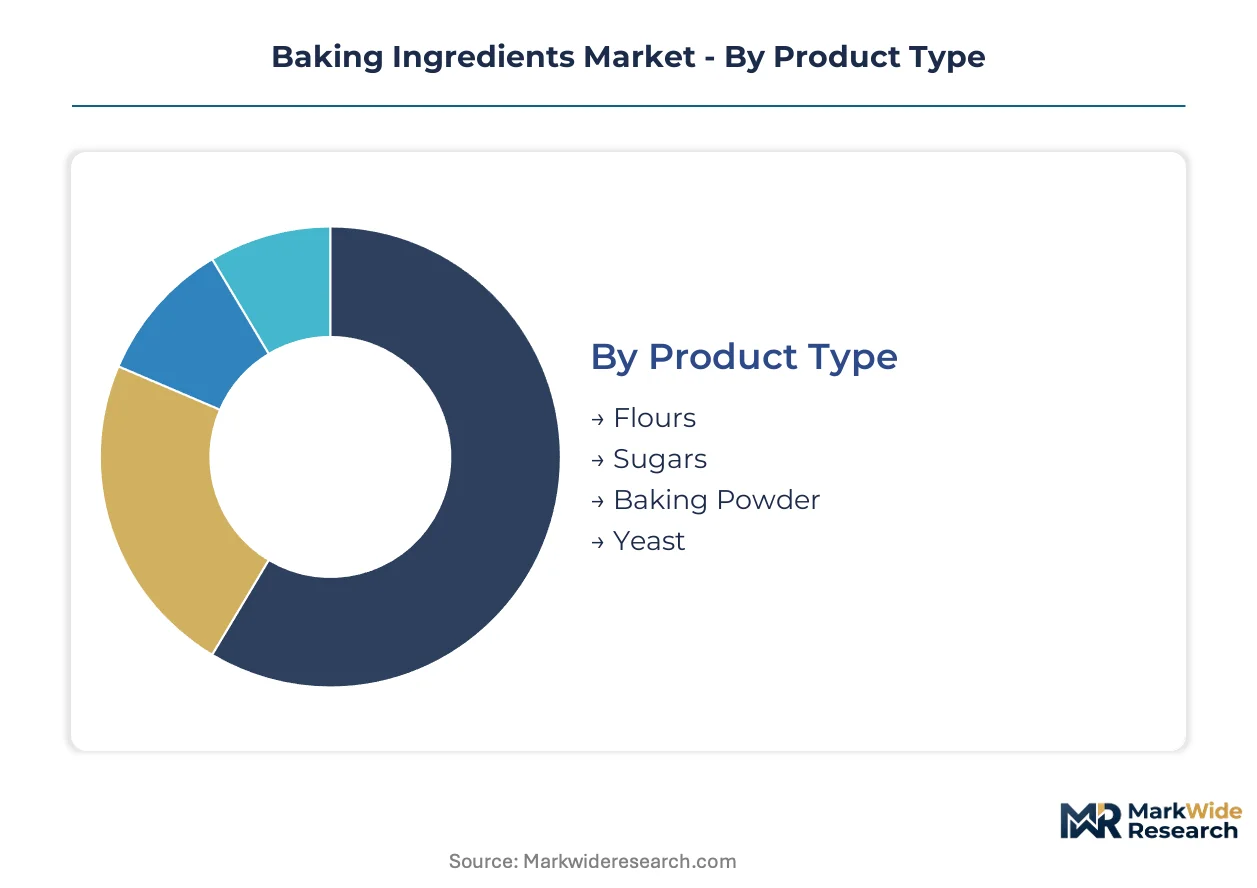
Baking ingredients segment along four functional dimensions that determine procurement patterns and margin capture. Product type and application segments drive technical specification requirements, while end-user channels dictate packaging formats and service intensity.
Product Type:
Reformulation cycles are shortening as bakeries replace legacy ingredient systems with enzyme-modified and clean-label alternatives across all four product categories.
- Flours:Wheat flour protein specifications ranging from 8% to 14% determine gluten network formation for bread versus pastry applications. Industrial bakeries in Germany and the Netherlands are consolidating procurement around enzyme-modified flour systems that extend shelf life without chemical preservatives.
- Sugars:Granulated, brown, and specialty sugar grades provide fermentation substrate, moisture retention, and Maillard browning control. Food manufacturers in São Paulo state are scaling automated lines that demand standardized sugar particle size distributions for consistent dough rheology.
- Baking Powder:Dual-action sodium bicarbonate systems release carbon dioxide across temperature ranges to control rise timing in cakes and quick breads.
- Yeast:Active dry, instant, and fresh yeast strains from specialized fermentation facilities drive leavening performance across variable humidity conditions.
Flours sit at the top of the volume ranking, with enzyme-modified flour systems climbing the fastest as bakeries eliminate chemical preservatives.
Application:
End-use application determines ingredient specification intensity, with industrial bread production demanding the tightest protein and enzyme tolerances.
- Breads:Sandwich loaves, artisan boules, and regional specialty breads require high-gluten flour above 12% protein for structural integrity. Chinese food manufacturers are driving bulk procurement of extended-shelf-life ingredient systems for private-label sandwich bread production.
- Cakes:Layer cakes and pound cakes depend on precise emulsifier and leavening agent ratios for crumb structure and moisture retention. EFSA's tightened additive safety evaluations are compressing approval timelines for novel clean-label emulsifiers targeting this segment.
- Pastries:Croissants, puff pastries, and laminated doughs require specialized fat-inclusion techniques for flake development.
- Cookies:Drop, rolled, and molded cookie formats use lower-protein flours to minimize gluten development and maintain tender texture.
Breads command the largest ingredient volume, while cakes are expanding most quickly as clean-label reformulation accelerates across European markets.
End User:
Customer type segments separate bulk industrial procurement from service-intensive artisan channels with diverging technical support requirements.
- Food Manufacturers:Private-label producers operate automated production lines requiring standardized ingredient systems with batch-to-batch consistency. Facilities in Minas Gerais state are scaling bulk enzyme and emulsifier procurement with embedded technical service agreements.
- Bakeries:Artisan and retail bakery operations demand protein-specified flours and specialized yeast strains with fermentation optimization support. French and Italian metropolitan bakery associations now negotiate directly with regional wheat processors for contract terms.
- Restaurants:Foodservice operations require smaller-format packaging with rapid delivery cycles for menu-item production.
- Home Bakers:Consumer channel purchases drive retail-packaged volumes through grocery and specialty store distribution.
Food Manufacturers lead procurement volume, with Bakeries gaining share fastest as regional mill cooperatives displace national distributors.
Packaging Type:
Packaging configuration aligns with end-user scale and shelf-life requirements across the supply chain.
- Bags:Multi-wall paper and woven polypropylene bags handle bulk flour and sugar shipments to industrial facilities.
- Boxes:Corrugated containers protect retail-format products through distribution to grocery and specialty channels.
- Tubs:Rigid plastic containers package fresh yeast and high-moisture ingredients requiring vapor barrier protection.
- Sachets:Single-use foil and film packets serve foodservice and home baker segments with portion-controlled convenience.
Bags dominate industrial shipment volumes, with Sachets expanding fastest as foodservice operators optimize portion control and waste reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr and Rhine-Main industrial corridors anchor European baking ingredient demand through dense networks of industrial bakeries and food manufacturers. The EU Green Deal's sustainable sourcing mandates are reshaping procurement compliance across member states. Artisan bakery clusters in France and Italy are consolidating volumes through direct mill negotiations.
United States
Midwest grain origination networks supply protein-specified flours to automated bread production lines across Illinois and Ohio. FDA GRAS determinations govern novel enzyme approvals for clean-label reformulation. Minneapolis-St. Paul hosts technical service centers supporting industrial bakeries transitioning to enzyme-based shelf-life extension.
China
Shanghai and Yangtze River Delta food manufacturers drive bulk procurement of standardized ingredient systems for private-label sandwich bread. NMPA and MEE dual carbon guidelines incentivize low-carbon wheat derivative sourcing. Shandong Province milling clusters are upgrading fermentation capacity to meet industrial yeast demand from automated bakery lines.
Brazil
São Paulo and Minas Gerais states scale automated production lines requiring bulk enzyme and emulsifier systems with embedded technical support. ANVISA regulates food additive safety for imported baking inputs. Campinas industrial corridor concentrates procurement volumes from regional distributors serving multinational food manufacturers.
India
Maharashtra and Gujarat food manufacturers expand private-label bakery production for metropolitan retail chains. BIS certification requirements extend procurement lead times for imported wheat derivatives by 8-12 weeks. Mumbai-Pune industrial belt attracts direct-to-bakery digital platforms connecting regional mills with artisan clusters.
France
Paris metropolitan bakery associations negotiate protein-specified flour contracts directly with regional wheat processors. EFSA food additive safety evaluations compress approval timelines for novel clean-label emulsifiers. Lyon and Auvergne-Rhône-Alpes host specialized enzyme production facilities serving reformulating industrial bakers.
Baking Ingredients Market Vendor Landscape
Global majors compete with regional champions across ingredient technology and geographic coverage. The market structure consolidates around fermentation technology leaders, grain origination networks, and specialized enzyme portfolios. Three archetypes dominate: multinational agribusiness conglomerates with captive supply chains, European fermentation specialists with yeast technology leadership, and diversified ingredient science companies with clean-label enzyme platforms. Competitive moves center on backward integration into grain origination and technology licensing partnerships for enzyme-modified flour systems.
Within the fermentation technology tier, Lesaffre exemplifies geographic manufacturing scale, while Koninklijke DSM N.V. occupies a position in enzyme science specialization. Among grain-origination anchored conglomerates, Cargill Incorporated represents the archetype of North American supply network leverage. These three companies anchor the competitive structure through distinct capability configurations rather than overlapping strategic positioning.
| Leading Market Players |
|---|
| Koninklijke DSM N.V. |
| Corbion |
| Cargill Incorporated |
| AAK AB |
| Lesaffre |
| Archer Daniels Midland Company |
| Kerry Group Plc |
| BASF SE |
| Ingredion Incorporated |
| Others |
Supply Flow & Price Mechanics
Enzyme-modified flour systems are simultaneously compressing ingredient cost economics and concentrating supply relationships around fermentation-capable suppliers with technical service depth. This technology transition rewards backward-integrated mill networks while marginalizing commodity traders lacking formulation expertise.
Pricing Analysis
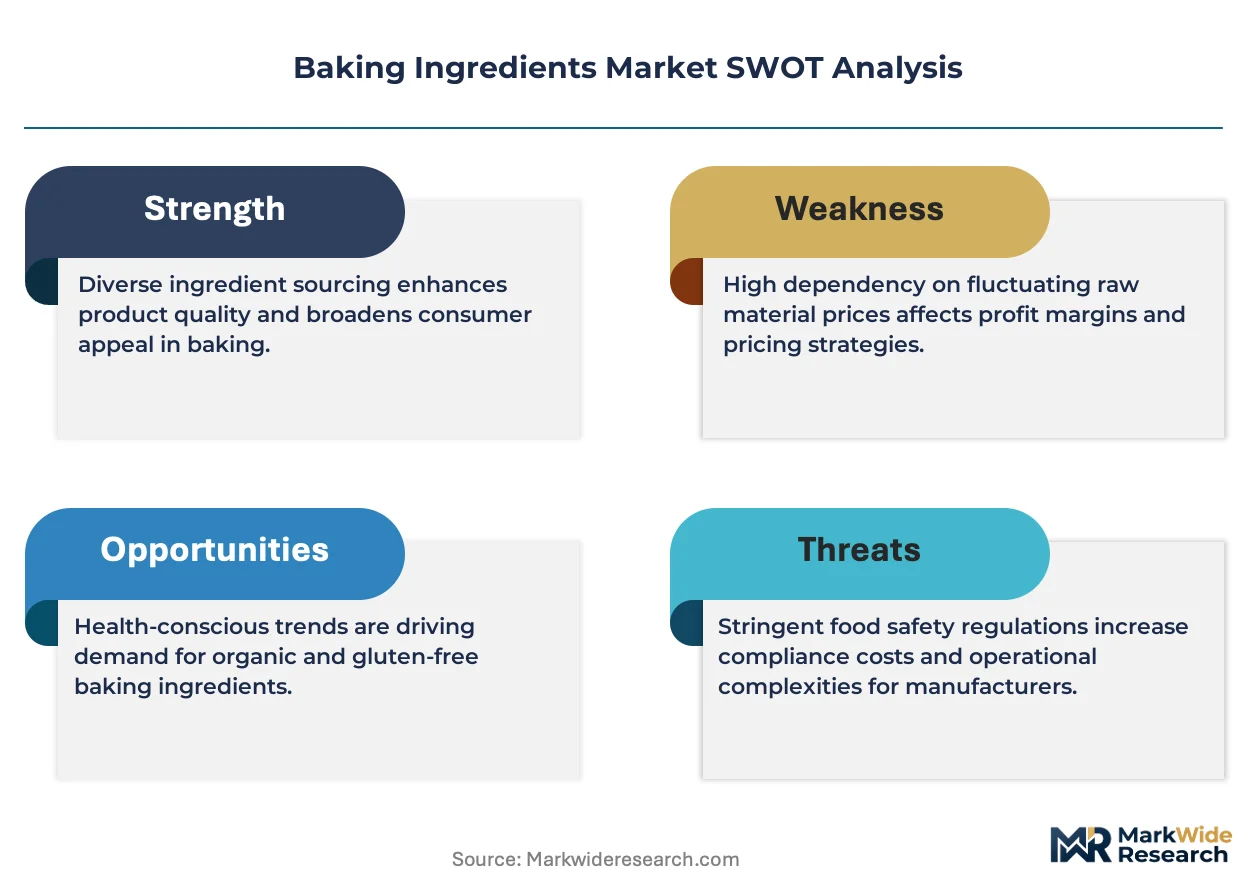
Input-cost pass-through from wheat protein volatility and fermentation capacity constraints shapes contract structures across the ingredient stack. Three-tier pricing structure across premium enzyme-modified, standard commodity, and economy bulk flour tiers separates technical service bundles from basic volume deliveries. Pricing pressure stems from EFSA's extended additive approval timelines forcing pre-qualification stockpiling. Food manufacturers exhibit highest price sensitivity due to private-label margin compression, while artisan bakeries absorb premiums for protein-specified contracts.
Supply Chain Analysis
Single-source vulnerability sits with Western European fermentation hubs dominating global yeast capacity and North American grain origination networks controlling high-protein wheat flows. Raw material dependencies center on Black Sea and North American wheat harvests, specialized fermentation feedstocks, and palm-derived emulsifier oils. Tariff exposure looms over enzyme import flows into Brazil and India under evolving ANVISA and BIS frameworks. Distribution runs through regional mill cooperatives displacing national wholesale channels in French and Italian metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's sustainable sourcing mandates compound procurement complexity, creating sustained demand for traceability-verified ingredient systems across European industrial baking.
For Market Incumbents: Cement fermentation technology leadership through geographic capacity expansion in Shandong Province and Campinas corridor. Defend margin pools by locking long-term enzyme supply contracts with automated bread manufacturers before regulatory determinations finalize. Prioritize certification investment for dual carbon alignment under China's NMPA guidelines. For New Entrants and Emerging Players: Launch via direct-to-bakery digital platforms connecting regional Indian mills with Maharashtra and Gujarat artisan clusters. Target white-space in technical service-light emulsifier segments where legacy distributors dominate. Exploit BIS certification bottlenecks by building domestic milling partnerships that compress procurement lead times for food manufacturers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional mill cooperatives lacking enzyme modification capabilities but holding protein-specified flour contracts. Long-term viability favors acquisition targets with captive fermentation assets and clean-label certification pipelines. Watch EFSA additive safety determinations as inflection signal for enzyme supplier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill's North American network secures protein-specified flour supply against Black Sea harvest volatility. |
| Fermentation Capacity Expansion | Lesaffre's Shandong facility upgrades capture industrial yeast demand from Yangtze Delta food manufacturers. |
| Clean-Label Certification Investment | Kerry Group's enzyme portfolios align with EU Green Deal traceability mandates for Dutch sandwich bread producers. |
| Direct-to-Bakery Digital Platform Launch | Mumbai-Pune platforms bypass wholesale channels to connect regional mills with Maharashtra artisan clusters. |
| Technical Service Partnership | Minas Gerais bulk procurement with embedded support addresses Brazilian food manufacturer automation scaling. |
Methodological Framework
Bottom-up food manufacturer and bakery modeling reconciled against top-down grain origination and fermentation capacity tracking forms the analytical core. Primary interviews with industrial bakery procurement directors, artisan association negotiators, enzyme R&D leads, and regional mill operations managers combined with secondary validation from EFSA additive safety filings, FDA GRAS determinations, BIS certification records, and customs trade data. Triangulation across supply-side capacity announcements and demand-side procurement patterns anchors volume estimates.
Input-output matrices map wheat protein specifications, enzyme modification rates, and fermentation throughput against end-use application requirements across the projection horizon. Segmentation dimensions span product type, application, end-user channel, and packaging format, with regional regulatory clusters modeled separately. CAGRs derive from compound growth of ingredient procurement volumes against baseline production capacity. Forecast inputs incorporate EU Green Deal compliance timelines and NMPA dual carbon incentive structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under wheat harvest disruption and regulatory approval delays. Assumptions reflect sustained clean-label reformulation momentum and automation scaling in Brazilian and Chinese food manufacturing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Ximenia Oil Market
Ingredients
Vegan Ingredients Market
Ingredients
Corn Steep Liquor Market
Ingredients
Tryptose Market
Ingredients
Plant Based Premix Market
Ingredients
Food Ingredients Market
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
Modified Soya Flour Market
Ingredients
Asia-Pacific Yeast Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Virginiamycin Market
Ingredients
Malted Barley Flour Market
Ingredients
Potato Starch Market
Ingredients
African Brewing Enzymes Market
Ingredients
Hydrolyzed Starch Market
Ingredients
Ingredients Market