
 Baobab Ingredient Market | 2026-2036
Baobab Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Baobab Ingredient Market Analysis
The baobab ingredient category is recalibrating around a sharp split between certified organic powder commanding specialty premiums and bulk commodity pulp sold into industrial blending. Aduna Limited leverages its direct-trade relationships with Malian and Ghanaian harvester cooperatives to sustain price premiums in UK and German health food channels. Baobab Foods LLC anchors North American supply through its Seattle-based processing facility, while Afriplex Pty Ltd dominates southern African extraction with vertically integrated drying and milling operations near Limpopo.
Baobab ingredient denotes the processed pulp, seed oil, and leaf extract derived from Adansonia digitata, a sub-Saharan tree whose dried fruit powder contains approximately 50% dietary fiber and vitamin C levels exceeding six times that of oranges by weight. Pulverized powder leads volume due to its incorporation into smoothie formulations and baked goods, while oil extracts capture concentrated margin pools in dermocosmetic applications. The dietary supplements segment grows fastest as encapsulation technologies improve bioavailability claims, whereas nutraceuticals remains mature with established brands defending shelf placement.
EFSA novel food authorizations govern EU market entry for baobab pulp, while FDA GRAS self-determination shapes US commercialization pathways without mandatory pre-market approval. Organic certification under EU Regulation 2018/848 and USDA National Organic Program standards increasingly filters market access for non-certified suppliers. Stakeholders must monitor evolving novel food dossier requirements in target jurisdictions before committing to processing capacity expansion.
Market Dynamics
The baobab ingredient market is being restructured by EFSA novel food authorization requirements that filter European market access and concentrate processing capacity around certified organic supply chains. This regulatory gatekeeping creates a bifurcation between premium-certified and commodity-grade product streams.
Growth Catalysts
- EFSA Novel Food Framework:The EU's structured safety assessment pathway for Adansonia digitata pulp provides legal certainty for formulators, accelerating new product introductions in German and French nutraceutical channels.
- Encapsulation Technology:Advanced lipid-based delivery systems are improving vitamin C bioavailability claims in dietary supplement applications, expanding addressable use cases beyond traditional powder formats.
- Senegal's Cooperative Infrastructure:Harvester collectives in Fatick and Kaolack regions have established traceable supply pipelines that satisfy European organic certification requirements.
Market Restraints
- Raw Material Volatility:Wild-harvested baobab fruit supply fluctuates with Sahel rainfall patterns, creating input cost instability for processors dependent on non-irrigated sources.
- Geographic Supply Concentration:Over 70% of export-grade pulp originates from Malian and Senegalese cooperatives, exposing buyers to regional political and logistical disruption risk.
- Regulatory Asymmetry:FDA GRAS self-determination in the United States creates divergent compliance burdens versus EFSA's mandatory pre-market authorization, fragmenting go-to-market strategies.
Strategic Opportunities
- EFSA 2018/848 Organic Certification:The EU's tightened organic regulation creates competitive moats for early-certified suppliers while disqualifying non-compliant competitors from premium pricing tiers.
- Dermocosmetic Oil Extraction:Cold-pressed seed oil applications in premium skincare remain underdeveloped relative to pulp powder, offering margin expansion potential for processors with extraction capabilities.
- Direct-to-Consumer E-commerce:UK and German health food brands are building subscription revenue models that bypass traditional retail slotting fee structures.
Industry Challenges
- Novel Food Dossier Compilation:EFSA's toxicological and nutritional safety requirements demand specialized regulatory affairs expertise that smaller cooperatives cannot access without external consultancy support.
- Post-Harvest Processing Capital:Solar drying and mechanical milling equipment for GACP-compliant production requires upfront investment that limits cooperative scaling velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baobab Ingredient Market |
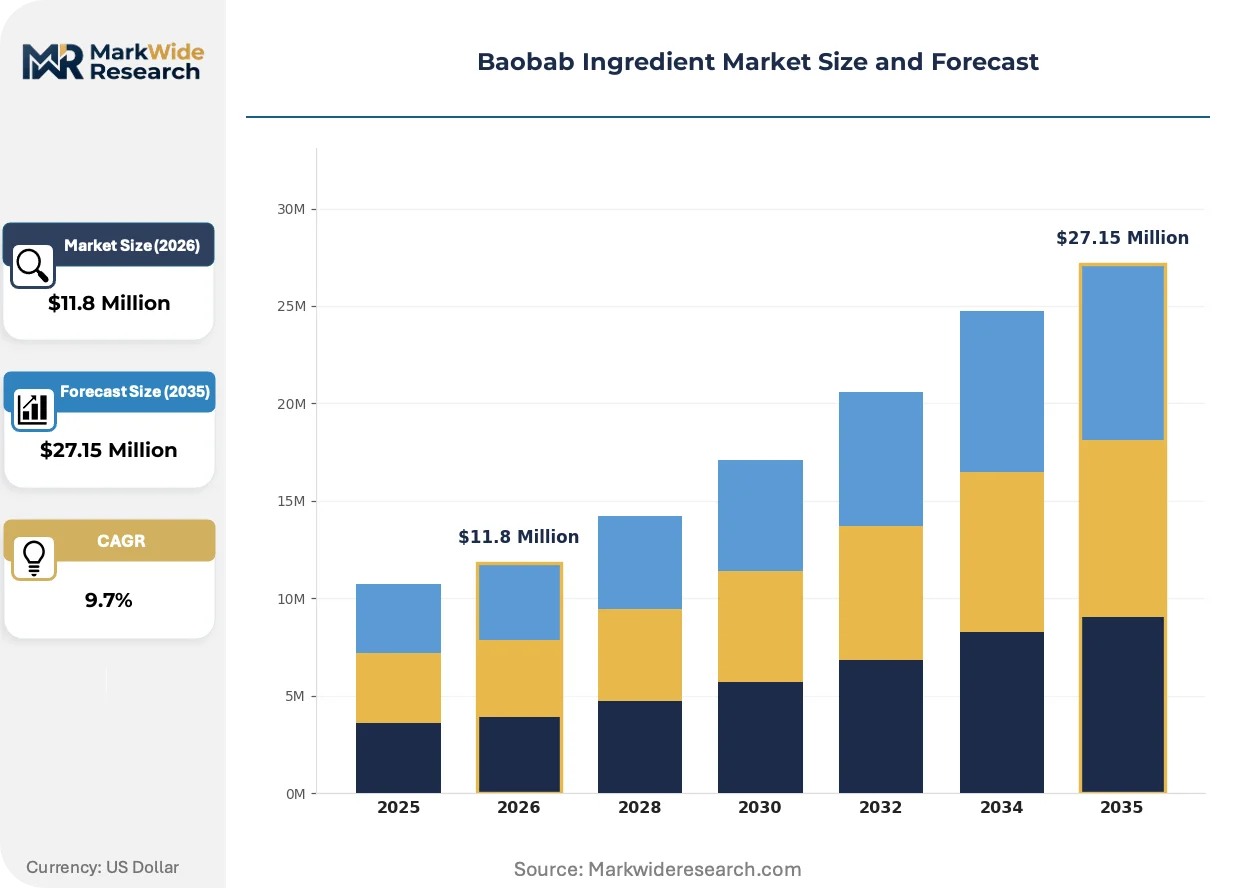
| Market Size in 2026 | $11.8 Million |
| Market Size in 2035 | $27.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulverized Powder, Oil, Capsules, Extracts Application: Nutraceuticals, Food & Beverage, Cosmetics, Dietary Supplements End User: Food Manufacturers, Cosmetic Companies, Health Stores, Pharmacies Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | Aduna Limited, Baobab Foods LLC, Afriplex Pty Ltd, Nexira, Baobab Fruit Company Senegal, Mighty Baobab Ltd, Organic Africa, B'Ayoba Pvt Ltd, Woodland Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baobab Ingredient Market Emerging Trajectories
Processing technology and regulatory frameworks are converging to reshape competitive positioning in baobab ingredients, with automation and certification protocols driving capability differentiation among suppliers.
Near-infrared spectroscopy coupled with machine vision sorting is automating quality grading at receiving stations in Senegalese and Malian processing hubs. European importers adopting this technology reduce manual inspection labor while achieving consistent moisture and fiber content specifications. The capital barrier is compressing margins for smaller processors unable to match precision standards.
EFSA's 2023 updated guidance on novel food safety dossiers is tightening toxicological data requirements for botanical ingredients. The industrial consequence is extended approval timelines and elevated consultancy costs for first-time market entrants. German and French formulators are responding by consolidating supplier relationships with established authorization holders rather than sponsoring new dossiers.
Long-term offtake agreements are displacing spot-market purchasing among major UK health food retailers. This procurement consolidation locks in volume commitments for certified organic suppliers while marginalizing non-certified harvesters from premium channel access. The shift is most visible in German drugstore chains where private-label baobab SKUs now carry multi-year supply contracts.
Baobab Ingredient Market Segmentation
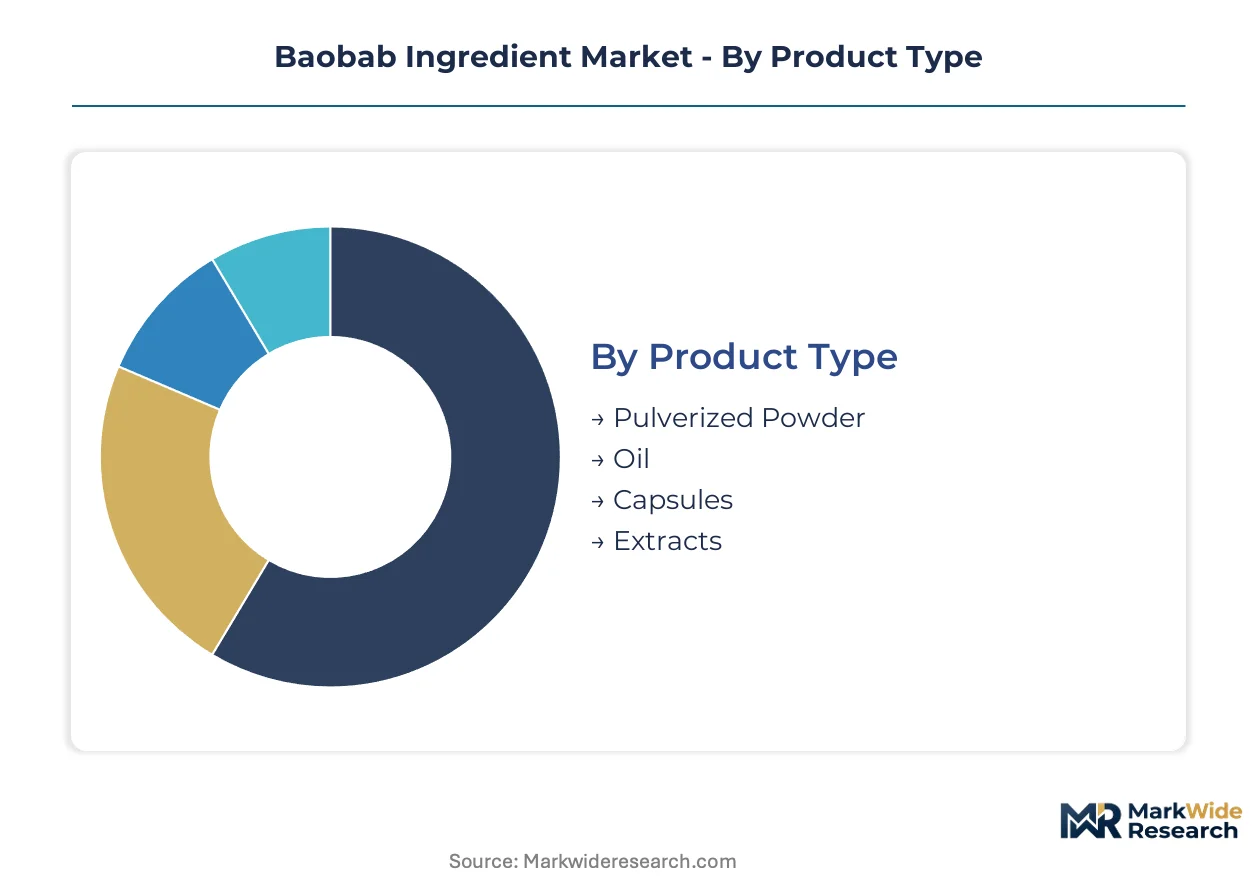
Baobab ingredient segmentation reveals how regulatory certification requirements concentrate value capture in specific product formats while channel fragmentation creates divergent margin structures across end-use verticals. Understanding these splits enables processors to prioritize capacity investments toward highest-return specifications.
Product Type:
EFSA novel food authorization applies differentially across formats, with whole pulp powders facing streamlined safety reviews while concentrated extracts trigger extended toxicological dossier requirements.
- Pulverized Powder:Dried fruit pulp milled to 200-mesh particle size containing approximately 50% dietary fiber and elevated vitamin C concentration. German nutraceutical formulators drive procurement under EFSA 2018/848 organic certification, though Sahel rainfall volatility constrains raw material planning.
- Oil:Cold-pressed seed oil rich in linoleic acid and sterols for dermocosmetic applications. Premium skincare brands in France and UK command concentrated margins, yet extraction capacity bottlenecks limit supply expansion.
- Capsules:Encapsulated powder or oil in gelatin or vegetable shells for precise dosing.
- Extracts:Concentrated bioactive fractions requiring comprehensive novel food safety dossiers.
Leading the category by volume: Pulverized Powder. Growing fastest: Capsules.
Application:
Application segments diverge sharply in margin structure, with cosmetics commanding price premiums per kilogram while food and beverage absorbs volume at compressed unit economics.
- Nutraceuticals:Functional food and beverage products with health positioning. Established German brands defend shelf placement through multi-year supply contracts with Senegalese cooperatives, locking out spot-market competitors.
- Food & Beverage:Smoothie formulations, baked goods, and beverage fortification. UK health food retailers consolidate procurement through direct-trade relationships, bypassing traditional distributor markups.
- Cosmetics:Seed oil and leaf extracts in premium skincare formulations.
- Dietary Supplements:Encapsulated or tableted products with bioavailability claims.
Highest revenue per kilogram: Cosmetics. Steepest expansion trajectory: Dietary Supplements.
End User:
End user concentration determines certification burden intensity, with pharmaceutical-channel buyers imposing GACP-compliant documentation that informal harvesters cannot satisfy.
- Food Manufacturers:Industrial-scale buyers integrating baobab into packaged consumer goods. Processors with EFSA-authorized supply chains capture recurring volume commitments from German and French producers.
- Cosmetic Companies:Formulators of premium skincare and haircare products. Cold-pressed oil specifications demand traceable Malian and Ghanaian sourcing that vertically integrated suppliers control.
- Health Stores:Specialty retailers focusing on organic and natural product assortments.
- Pharmacies:Drugstore and apothecary channels with stringent quality documentation requirements.
Most demanding certification requirements: Pharmacies. Fastest procurement consolidation: Food Manufacturers.
Distribution Channel:
Channel selection directly shapes working capital requirements and customer acquisition economics, with direct sales minimizing intermediaries but demanding dedicated field presence.
- Online Retail:E-commerce platforms and brand-direct subscription models. UK and German health food brands build recurring revenue streams that eliminate retail slotting fees while requiring digital marketing investment.
- Supermarkets:Mass-market grocery and hypermarket chains. Private-label baobab SKUs in German drugstore chains now carry multi-year offtake agreements that marginalize non-certified suppliers.
- Health Food Stores:Specialty brick-and-mortar natural product retailers.
- Direct Sales:Producer-to-buyer relationships bypassing intermediaries.
Fastest-growing channel: Online Retail. Highest entry barriers: Supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fatick and Kaolack in Senegal anchor the raw pulp supply infrastructure that feeds European nutraceutical formulators seeking EFSA-compliant organic certification.
Germany
Drugstore chains in Berlin and Hamburg consolidate procurement through multi-year offtake agreements with Senegalese cooperatives. EFSA novel food guidelines under EU Regulation 2015/2283 govern all baobab pulp introductions, forcing formulators to document toxicological safety dossiers. The Rhine-Ruhr industrial corridor hosts processing facilities that convert raw pulp into encapsulated supplements for pharmacy distribution.
United Kingdom
London-based health food retailers build direct-to-consumer subscription models that bypass traditional supermarket slotting fees. The Food Standards Agency applies retained EU novel food rules post-Brexit, maintaining alignment with EFSA safety assessments. Manchester and Birmingham distribution hubs handle inbound organic-certified shipments from Malian harvester collectives.
France
Parisian dermocosmetic laboratories drive cold-pressed seed oil demand for premium skincare formulations. ANSM and DGCCRF enforce cosmetic ingredient safety standards alongside EFSA novel food protocols for ingestible applications. The Provence-Alpes-Côte d'Azur region concentrates essential oil extraction expertise that baobab processors increasingly leverage.
Senegal
Fatick and Kaolack cooperatives supply traceable organic pulp that satisfies German and French certification requirements. The country's national food safety authority, ANSSA, coordinates with EU border inspection posts to expedite export documentation. Dakar's port infrastructure handles bulk shipments to Rotterdam and Hamburg for onward European distribution.
United States
Seattle anchors North American processing capacity with facilities converting African-sourced pulp into retail-ready powder formats. FDA GRAS self-determination allows market entry without pre-market authorization, diverging from EU regulatory burdens. California health food brands in Los Angeles and San Francisco drive West Coast demand for smoothie formulation ingredients.
Baobab Ingredient Market Vendor Landscape
Capital-heavy processors with captive drying and milling equipment compete with asset-light traders sourcing through third-party cooperatives. The supplier base concentrates around vertically integrated African operators and European brand-holders with direct-trade relationships. Three archetypes dominate: certified-organic processors controlling upstream harvester networks, private-label formulators leveraging EFSA authorization expertise, and commodity traders arbitraging spot pulp availability. Competitive moves center on multi-year offtake contracting and backward integration into cooperative equity stakes.
Within the certified-organic processor tier, Afriplex Pty Ltd and Baobab Fruit Company Senegal exemplify upstream control strategies, while Aduna Limited occupies a position bridging African sourcing with European brand retail. These three entities represent distinct geographic anchoring—Southern African extraction capacity, Senegalese cooperative infrastructure, and UK-German channel access—without overlapping operational footprints.
| Leading Market Players |
|---|
| Aduna Limited |
| Baobab Foods LLC |
| Afriplex Pty Ltd |
| Nexira |
| Baobab Fruit Company Senegal |
| Mighty Baobab Ltd |
| Organic Africa |
| B'Ayoba Pvt Ltd |
| Woodland Foods |
| Others |
Supply Flow & Price Mechanics
Backward integration into Senegalese and Malian harvester cooperatives anchors supply security and pricing power for European processors navigating EFSA organic certification requirements. This upstream control enables premium capture in German pharmacy channels while insulating margins from Sahel rainfall volatility.
Pricing Analysis
Certification-grade pricing anchors value capture in the baobab ingredient market, with EFSA 2018/848 organic compliance commanding substantial premiums over uncertified commodity pulp. Price differentiation separates traceable Fatick-sourced powder from spot-market alternatives, with volume scale and cold-pressed oil extraction capability as secondary tiering factors. Cost compression in standard-grade powder is intensifying as automated near-infrared sorting reduces manual labor differentials. Food manufacturers exhibit highest price sensitivity due to thin formulation margins, while French dermocosmetic laboratories show lowest sensitivity given concentrated oil yields.
Supply Chain Analysis
Dual-sourcing requirements from German drugstore chains mandate qualified supplier networks spanning both Senegal and Mali to mitigate single-origin disruption risk. Raw material dependencies center on wild-harvested Adansonia digitata fruit, solar drying infrastructure, and mechanical milling equipment for GACP-compliant production. Tariff exposure through Rotterdam and Hamburg port entry points creates landed cost volatility for non-EU processors. Distribution runs through Dakar bulk shipment consolidation, European import processing hubs, and direct-to-retailer contracting for certified organic volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baobab ingredient market functions as a vertical-integration race where upstream cooperative equity stakes and downstream EFSA authorization expertise determine competitive survival. Players are pursuing captive supply control over Fatick and Kaolack harvester networks as the decisive lever.
For Market Incumbents: Acquire drying and milling assets in Senegal's Fatick region to lock in traceable organic supply pipelines. Consolidate multi-year offtake agreements with German pharmacy chains before EFSA dossier costs escalate further. Defend against emerging private-label entrants by accelerating novel food authorization coverage for concentrated extract formats. For New Entrants and Emerging Players: The premium-to-economy price gap in cold-pressed seed oil offers entry opportunity for extraction-capable processors targeting French dermocosmetic laboratories. Target underdeveloped UK subscription-commerce channels with encapsulated supplement formats bypassing retail slotting structures. Establish direct-trade relationships with Ghanaian harvester collectives outside Senegalese supply concentration. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by European brand-holders seeking backward integration into certified organic supply. Long-term viability favors processors with captive Senegalese cooperative relationships and EFSA authorization expertise. Watch EFSA novel food dossier backlog duration as inflection signal for regulatory capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Harvester Cooperatives | Captive supply from Fatick and Kaolack secures EFSA 2018/848 organic certification pipelines. |
| Encapsulation Technology Investment | Lipid-based delivery systems expand addressable use cases in German dietary supplement channels. |
| Direct-to-Consumer Subscription Launch | UK health food brands bypass supermarket slotting fees through recurring revenue models. |
| Cold-Pressed Oil Extraction Scale-Up | Dermocosmetic applications in France command concentrated margins relative to commodity pulp. |
| Novel Food Dossier Sponsorship | EFSA authorization expertise creates competitive moats against unqualified spot-market suppliers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with cooperative managers, EFSA regulatory consultants, German pharmacy procurement officers, and Senegalese export coordinators. EFSA novel food authorization databases, ANSSA export documentation, EU organic certification registries, and Rotterdam port customs declarations provided validation triangulation against bottom-up cooperative production estimates.
Granularity-level modeling addressed product type splits across powder, oil, capsule, and extract formats; application segments spanning nutraceuticals, food and beverage, cosmetics, and dietary supplements; and end-user categories including food manufacturers, cosmetic companies, health stores, and pharmacies. CAGRs were derived through demand-side consumption modeling and supply-side capacity assessment, incorporating Sahel rainfall pattern volatility and EFSA approval timeline uncertainty as industry-specific inputs.
Inputs from Senegalese cooperative production records and German import statistics were available through the study window; gaps in Malian informal harvester output introduce uncertainty bands around total addressable supply estimates. Forecasts reflect documented assumptions regarding EFSA regulatory capacity and organic certification adoption velocity. A model refresh is warranted upon material change in EFSA novel food dossier processing timelines or Sahel rainfall disruption severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydrolyzed Starch Market
Ingredients
Zea Mays Starch Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Calcium Caseinate Market
Ingredients
Dry Molasses Products Market
Ingredients
Global Autolyzed Yeast Extract Market
Ingredients
Sesame Seed Extract Market
Ingredients
China Beer Adjuncts Market
Ingredients
Edible Fiber Market
Ingredients
Collagen Casings Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
Codonopsis Extract Market
Ingredients
Rice Starch Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Chewing Gum Base Market
Ingredients
Pet Food Ingredients Market