
 Modified Wheat Starch Market | 2026-2036
Modified Wheat Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Wheat Starch Market Analytics
Food carbohydrate chemist availability is bifurcating the competitive landscape between multinational ingredient houses and regional specialists. Cargill, Incorporated leverages its integrated grain origination network to secure consistent feedstock for acid-thinned and oxidized wheat starch lines across North American milling assets. Roquette Frères competes through pea-wheat hybrid research while sustaining European manufacturing scale at its Lestrem facility. Grain Processing Corporation anchors Midwest supply with dedicated modified starch capacity serving domestic baking and snack segments.
Modified wheat starch denotes wheat endosperm-derived polysaccharides subjected to physical, enzymatic, or chemical alteration to modify viscosity, gelatinization temperature, or retrogradation behavior, typically achieving amylose/amylopectin ratios between 25:75 and 28:72 depending on modification intensity. These altered starches primarily serve as texture-modifying ingredients in heat-processed foods where native starch would synerese or break down under shear and thermal stress. Among product type segments, thickening agents occupy the dominant volume position in sauces and dressings where process tolerance requirements are most stringent, while stabilizers represent the fastest-growing category as clean-label frozen dessert formulations displace locust bean gum and carrageenan. The food industry end user segment captures the deepest margin pools through long-term supply agreements with industrial bakery and ready-meal manufacturers, whereas pharmaceutical sector demand for tablet binders remains structurally smaller but commands premium pricing due to excipient certification overhead.
FDA food additive regulations under 21 CFR 172.892 govern chemically modified wheat starch use in US food applications, while EFSA evaluates novel modification processes under updated food enzyme guidance that affects enzymatically treated variants entering European commerce. REACH registration requirements for acetylated and oxidized starch derivatives constrain market access for non-European manufacturers lacking European Union-based only representative structures. Stakeholders must monitor evolving definitions of "natural" and "clean label" across multiple jurisdictions, as regulatory divergence between FDA enforcement discretion and EU pre-market authorization pathways will determine which modification technologies retain commercial viability in premium positioning segments.
Market Dynamics
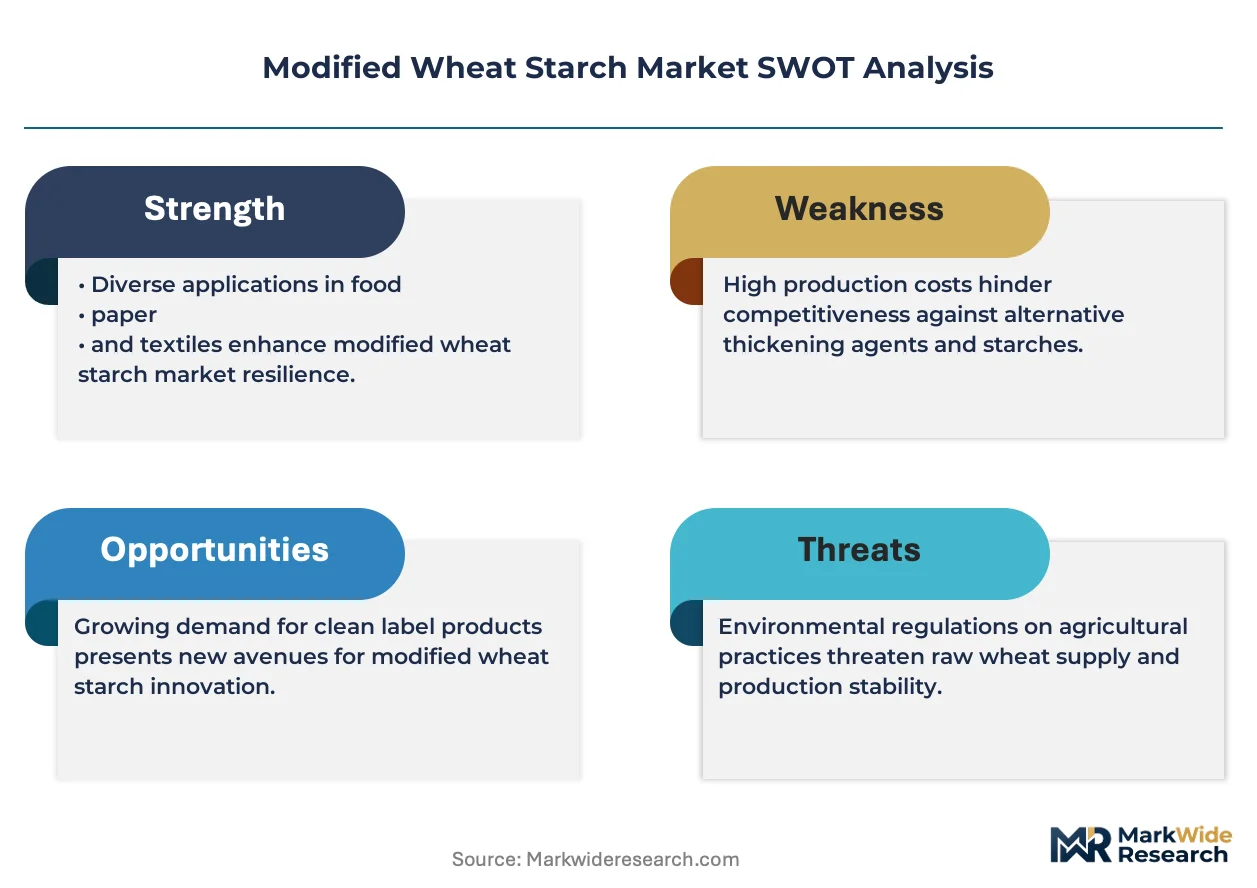
The Modified Wheat Starch Market pivots on regulatory divergence between FDA enforcement discretion and EU pre-market authorization, which is fragmenting modification technology viability across Atlantic trade corridors and forcing manufacturers to maintain parallel product lines.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Tighter additive disclosure rules across Germany, France, and the Netherlands accelerate reformulation toward enzymatically processed variants. Industrial bakeries in Hamburg and Frankfurt logistics corridors absorb larger clean-label volumes.
- Clean-label frozen dessert formulations:Stabilizer-grade modified wheat starch displaces locust bean gum and carrageenan in premium ice cream and plant-based frozen novelties. Food manufacturers prioritize physically processed starches for label simplicity.
- Pharmaceutical excipient certification:Tablet binder applications command premium pricing due to certification overhead, drawing specialty carbohydrate chemists into modified starch process development for oral solid dosage forms.
Market Restraints
- Wheat feedstock price volatility:Input cost swings tied to Black Sea grain flows and North American drought cycles compress margin predictability for acid-thinned and oxidized starch lines.
- REACH registration barriers:Acetylated and oxidized starch derivatives require European Union-based only representative structures, excluding non-European manufacturers lacking established EU legal entities from premium derivative segments.
- Native starch substitution in low-shear applications:Unmodified tapioca and potato starches satisfy viscosity requirements in cold-process sauces, limiting modified wheat starch penetration in cost-sensitive dressing formulations.
Strategic Opportunities
- Underpenetrated pharmaceutical markets in India and Brazil:Generic tablet manufacturing expansion creates demand for certified excipient-grade modified wheat starch as domestic formulators seek alternatives to imported microcrystalline cellulose.
- Pea-wheat hybrid research convergence:Novel protein-starch complexes from legume-cereal breeding programs enable clean-label texturizers with enhanced freeze-thaw stability for ready-meal applications.
- Direct-to-industrial-bakery distribution channels:Ingredient distributors bypass traditional broker networks to supply modified starch blends with just-in-time delivery to mid-sized plant bakeries in Poland and the Czech Republic.
Industry Challenges
- Food carbohydrate chemist scarcity:Specialized expertise in amylose/amylopectin ratio manipulation and gelatinization temperature tuning concentrates at multinational ingredient houses, constraining regional specialist R&D capacity.
- Dual regulatory compliance timelines:Parallel FDA food additive petitions and EFSA novel food enzyme evaluations extend product launch cycles by 18-36 months for enzymatically modified variants targeting both markets.
- Legacy spray-dryer retrofit requirements:Physical modification capacity expansion demands capital-intensive equipment upgrades for pre-gelatinized starch production, burdening mid-tier manufacturers with debt service obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Wheat Starch Market |
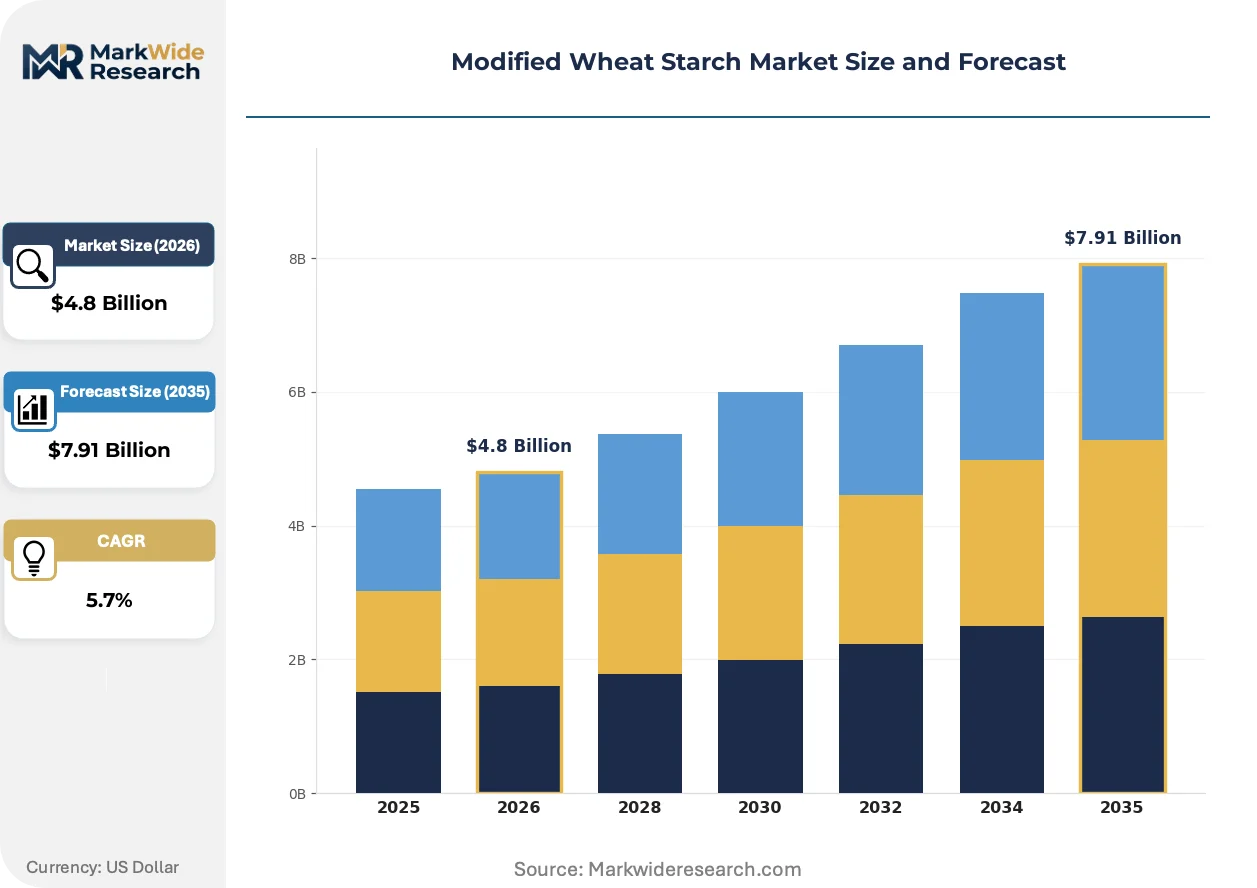
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thickening Agents, Stabilizers, Binders, Fillers Application: Baking, Confectionery, Sauces, Dressings End User: Food Industry, Pharmaceutical Sector, Personal Care, Textile Industry Packaging Type: Bag, Drum, Bulk, Sachet |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Tereos Group, Roquette Frères, Avebe U.A., AGRANA Beteiligungs-AG, Grain Processing Corporation, Emsland-Stärke GmbH, Manildra Group USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Wheat Starch Market Evolving Landscape
Enzymatic modification protocols are displacing chemical processing routes as the dominant innovation vector, with viscosity-building and retrogradation-control functionalities now achievable through targeted amylase treatments rather than acid-thinning or oxidation.
Dual-enzyme systems combining α-amylase and glucoamylase treatments are miniaturizing the molecular weight distribution of wheat starch polymers while preserving process tolerance in high-shear sauce applications. Mid-sized sauce manufacturers in the United States adopt these systems at pilot scale to reduce chemical additive declarations. The technology is compressing the cost gap between clean-label and conventional modified starches in premium private-label condiment lines.
EFSA updated food enzyme guidance now requires comprehensive toxicological dossiers for enzymatically treated starches entering European commerce, extending evaluation timelines for novel processing aids. Industrial consequence includes consolidation of approved enzyme supplier lists among major starch processors. Frozen dessert and ready-meal segments in Germany and France face reformulation delays as manufacturers await positive opinions on next-generation amylase variants.
Ingredient procurement from regional milling clusters now bypasses traditional national distributor networks, with industrial bakeries in Poland and the Czech Republic sourcing modified wheat starch directly from Lestrem and Hamburg production facilities. This channel disintermediation compresses working capital cycles for plant bakeries while exposing them to currency fluctuation risks on euro-denominated contracts. The shift is most visible in Central European markets where logistics infrastructure supports just-in-time bulk delivery.
Modified Wheat Starch Market Segmentation
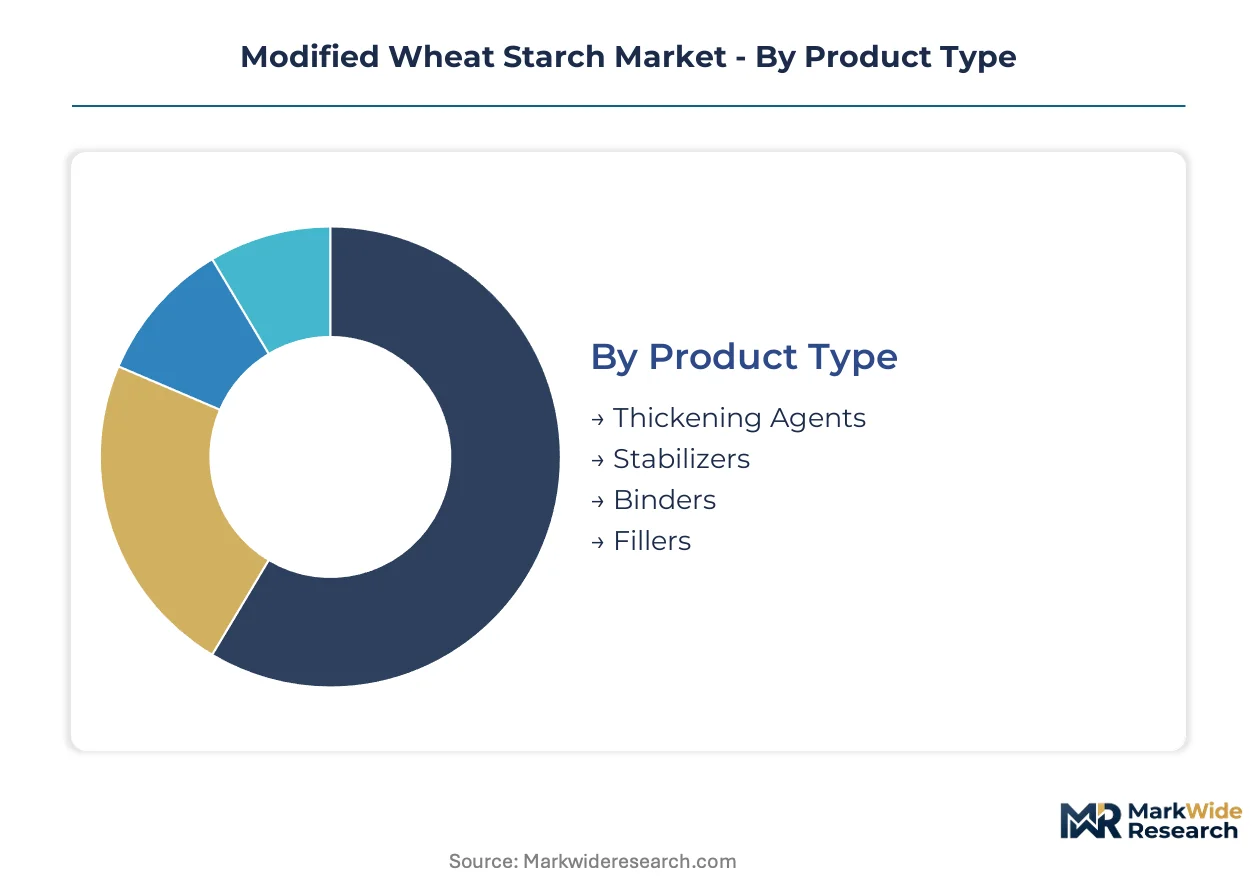
Segmentation in modified wheat starch reveals how regulatory divergence between FDA and EFSA pathways fragments technology viability across end-use applications. Each dimension exposes distinct margin structures, certification overhead, and supply chain configurations that determine competitive positioning.
Product Type:
FDA food additive regulations under 21 CFR 172.892 and EFSA food enzyme guidance create divergent compliance burdens across modification chemistries, concentrating R&D investment in enzymatically processed variants.
- Thickening Agents:Acid-thinned and oxidized wheat starches achieve viscosity stability under high-shear thermal processing. Industrial sauce manufacturers in the United States absorb the largest volumes, though EFSA evaluation timelines delay European adoption of novel enzymatic alternatives.
- Stabilizers:Retrogradation-controlled variants displace locust bean gum and carrageenan in clean-label frozen desserts. German and French formulators drive demand as they await positive opinions on next-generation amylase treatments under updated enzyme guidance.
- Binders:Excipient-grade specifications command premium pricing through pharmaceutical certification overhead.
- Fillers:Lower-modification-intensity variants serve cost-sensitive baking applications with minimal regulatory documentation.
Thickening agents handle the majority of throughput; stabilizers are climbing the fastest on share.
Application:
Application concentration tracks logistics infrastructure density, with industrial bakery clusters around Hamburg and Frankfurt absorbing bulk volumes through just-in-time delivery channels.
- Baking:Texture-modified starches control crumb structure and shelf-life extension in heat-processed goods. Mid-sized plant bakeries in Poland and the Czech Republic source directly from Lestrem production facilities, bypassing traditional distributor networks.
- Sauces:Process tolerance requirements are most stringent here, demanding dual-enzyme systems that miniaturize molecular weight distribution. United States private-label condiment manufacturers pilot these systems to reduce chemical additive declarations.
- Confectionery:Viscosity control in high-sugar matrices favors specific amylose/amylopectin ratios.
- Dressings:Cold-process formulations face substitution pressure from native tapioca and potato starches in cost-sensitive segments.
Baking commands the deepest volume pools; sauces show the steepest expansion trajectory as clean-label reformulation accelerates.
End User:
End-user segmentation separates margin structures: food industry agreements deliver volume certainty while pharmaceutical certification creates pricing power through technical barriers.
- Food Industry:Long-term supply agreements with industrial bakery and ready-meal manufacturers capture predictable offtake. Hamburg and Frankfurt logistics corridors concentrate demand from reformulation activity tied to EU Green Deal Farm to Fork disclosure rules.
- Pharmaceutical Sector:Tablet binder applications remain structurally smaller but command premium pricing due to excipient certification overhead. Generic manufacturing expansion in India and Brazil creates demand for certified alternatives to imported microcrystalline cellulose.
- Personal Care:Rheology modification in emulsions drives modest specialty volumes.
- Textile Industry:Sizing applications compete with synthetic polymer alternatives on cost-performance metrics.
Food industry relationships anchor volume throughput; pharmaceutical sector engagement delivers the highest unit margins.
Packaging Type:
Packaging configuration reflects customer scale and inventory velocity, with bulk formats dominating industrial accounts and smaller units serving specialty formulators.
- Bulk:Tanker and silo delivery to large-scale industrial bakeries and sauce manufacturers minimizes handling costs. Central European logistics infrastructure supports just-in-time bulk programs that compress working capital cycles.
- Bag:Standard industrial units serve mid-tier manufacturers with moderate volume requirements and storage constraints.
- Drum:Pharmaceutical and personal care sectors prefer sealed containers for contamination-sensitive applications.
- Sachet:Small-format packaging enables sampling and specialty product development in regional laboratories.
Bulk packaging moves the largest tonnage; sachet formats are gaining share fastest in specialty ingredient distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA food enzyme guidance and EU Green Deal Farm to Fork strategy anchor European regulatory influence over global modified wheat starch trade corridors. National implementation varies across industrial bakery clusters and pharmaceutical manufacturing zones.
Germany
Industrial bakeries around Hamburg and Frankfurt logistics corridors absorb enzymatically modified wheat starch volumes for clean-label reformulation. EU Green Deal disclosure rules tighten additive labeling requirements nationwide. Bavaria-based ingredient distributors consolidate procurement from Lestrem production facilities.
United States
FDA 21 CFR 172.892 governs chemically modified wheat starch use in sauces and dressings across Midwest manufacturing zones. Dual-enzyme system pilots reduce chemical additive declarations in private-label condiment lines. Illinois and Ohio sauce manufacturers drive adoption of miniaturized molecular weight distribution technologies.
France
Roquette Frères sustains European manufacturing scale at its Lestrem facility to supply Central European bakery chains. EFSA updated food enzyme guidance delays reformulation timelines for next-generation amylase variants. Paris-region frozen dessert formulators await positive opinions on novel enzymatic stabilizers.
India
Generic tablet manufacturing expansion creates demand for certified excipient-grade modified wheat starch as domestic formulators seek alternatives to imported microcrystalline cellulose. FSSAI food additive regulations govern import and domestic production standards. Maharashtra and Gujarat pharmaceutical clusters concentrate formulation R&D activity.
Brazil
Domestic pharmaceutical sector growth drives excipient certification requirements for tablet binder applications. ANVISA pharmaceutical regulations establish import quality standards for modified starch derivatives. São Paulo-state manufacturing zones absorb specialty carbohydrate ingredients for oral solid dosage forms.
Modified Wheat Starch Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in modified wheat starch supply. Multinational ingredient houses leverage grain origination networks and captive milling assets to secure consistent feedstock for acid-thinned and oxidized product lines. Regional specialists compete through hybrid research programs and direct-to-bakery distribution channels. Capacity expansion and enzymatic process licensing constitute the dominant competitive moves across both tiers.
Among integrated North American operators, Cargill, Incorporated and Grain Processing Corporation exemplify scale-driven archetypes with captive supply chain control. Roquette Frères occupies a position within the European specialist tier, representing pea-wheat hybrid research convergence and cross-border logistics integration. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Tereos Group |
| Roquette Frères |
| Avebe U.A. |
| AGRANA Beteiligungs-AG |
| Grain Processing Corporation |
| Emsland-Stärke GmbH |
| Manildra Group USA |
| Others |
Value Network & Pricing Analysis
FDA food additive regulations under 21 CFR 172.892 and EFSA food enzyme guidance gate both supply qualification and price differentiation simultaneously, as enzymatically processed variants command premium positioning while chemically modified alternatives face disclosure-driven compression. Certification overhead for pharmaceutical excipient grades creates a parallel tier where tablet binder specifications sustain elevated unit economics against commodity food-grade volumes.
Pricing Analysis
North American enzymatically modified wheat starch carries a 15-25% premium over chemically processed equivalents in European procurement, reflecting EFSA evaluation timelines and clean-label reformulation urgency in Germany and France. Three-tier pricing structure across premium excipient-grade, standard food-grade, and economy modified starch levels segments buyers by certification intensity and volume scale. Cost compression in economy tiers is intensifying because native tapioca and potato starches satisfy viscosity requirements in cold-process applications. Industrial sauce manufacturers in the United States exhibit highest price sensitivity due to private-label margin constraints, while pharmaceutical formulators in India and Brazil absorb premium positioning for certified tablet binder alternatives.
Supply Chain Analysis
Just-in-time inventory programs for Central European industrial bakeries compress lead times to 48-72 hours from Lestrem and Hamburg production facilities, exposing buyers to euro-denominated currency fluctuation risks on bulk contracts. Supply concentrates in Germany, France, and the United States, with Roquette Frères at Lestrem, Cargill across North American milling assets, and Grain Processing Corporation in the Midwest anchoring feedstock origination. Wheat grain from Black Sea and North American origins, enzymatic processing aids, and pharmaceutical certification documentation constitute critical input dependencies. Single-source vulnerability runs through approved enzyme supplier lists consolidated under EFSA guidance, constraining formulation flexibility for frozen dessert manufacturers awaiting positive opinions on next-generation amylase variants. Distribution runs through direct-to-bakery channels bypassing traditional broker networks in Poland and the Czech Republic, alongside conventional ingredient distributor relationships for smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Modified Wheat Starch Market is entering a cyclical recovery phase as EU Green Deal Farm to Fork disclosure rules force system-wide reformulation, creating replacement demand that absorbs excess capacity and restores pricing discipline across enzymatic processing lines.
For Market Incumbents: Fortify captive feedstock control through backward integration into regional wheat milling clusters or long-term origination agreements with Black Sea suppliers, insulating acid-thinned and oxidized product lines from input cost volatility. Secure dual regulatory compliance capacity by maintaining parallel FDA food additive petition and EFSA novel food enzyme evaluation tracks, defending against specialty carbohydrate chemist scarcity that concentrates R&D leverage at multinational ingredient houses. For New Entrants and Emerging Players: Differentiate on pharmaceutical excipient certification in underpenetrated generic tablet manufacturing zones in India and Brazil, where domestic formulators seek alternatives to imported microcrystalline cellulose. Target direct-to-industrial-bakery distribution in Poland and the Czech Republic, leveraging just-in-time logistics infrastructure to bypass entrenched broker networks and capture mid-sized plant bakery volumes. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic modification capacity as legacy spray-dryer retrofit requirements burden mid-tier manufacturers with debt service obligations, creating distressed acquisition opportunities. Focus on regional specialists with hybrid research pipelines bridging pea-wheat protein-starch complexes and established European manufacturing footprints. Watch EFSA positive opinion issuance timelines for next-generation amylase variants as the inflection signal for clean-label stabilizer-grade demand acceleration in frozen dessert and ready-meal segments.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Licensing | Dual-enzyme system adoption by U.S. private-label condiment manufacturers reduces chemical additive declarations. |
| Backward Integration into Milling | Cargill's captive grain origination network secures consistent feedstock for acid-thinned wheat starch lines. |
| Pharmaceutical Excipient Certification | Generic tablet manufacturing expansion in Maharashtra and Gujarat pharmaceutical clusters creates premium pricing power. |
| Direct-to-Bakery Channel Development | Mid-sized plant bakeries in Poland and Czech Republic compress working capital cycles through bulk just-in-time delivery. |
| Pea-Wheat Hybrid R&D Convergence | Roquette Frères' legume-cereal breeding programs enable clean-label texturizers with enhanced freeze-thaw stability. |
Research Methodology
The analysis maps enzymatically modified, chemically modified, and physically processed wheat starch sub-sectors, each validated through carbohydrate chemists at multinational ingredient houses, procurement leads at industrial bakeries, regulatory affairs specialists navigating FDA and EFSA pathways, and distribution channel partners in Central European logistics corridors. Primary interview insights triangulate against secondary sources including FDA 21 CFR 172.892 filings, EFSA food enzyme guidance updates, EU Green Deal Farm to Fork strategy documents, and customs trade data on wheat starch derivative flows. Bottom-up volume builds from end-use application segments reconcile with top-down market sizing derived from grain origination and milling capacity disclosures.
Consistency checks validate volume and value outputs against external benchmarks including industrial bakery production indices in Germany, pharmaceutical excipient import records for India and Brazil, and frozen dessert formulation trend reports from French and German food manufacturers. The analytical framework models product type, application, end user, and packaging format dimensions across the projection horizon, with CAGRs derived from regression analysis of historical modification technology adoption curves and regulatory-driven reformulation timelines. Forecast inputs incorporate wheat feedstock price volatility indices, EFSA evaluation pipeline status for novel amylase variants, and pharmaceutical sector generic manufacturing expansion rates.
Material uncertainties — Black Sea grain flow disruptions, North American drought cycles, EFSA positive opinion delays for next-generation enzymes, and REACH registration barriers for non-European manufacturers — sit outside the modeled envelope. Forecasts reflect documented assumptions on clean-label adoption velocity and pharmaceutical certification penetration timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Horseradish Peroxidase Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Europe Food Premix Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
India Food Hydrocolloids Market
Food Components and Additives
Food Grade Sodium Carbonate Market