
 Homecare Ingredients Market | 2026-2036
Homecare Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Homecare Ingredients Market Analysis
Concentrated refill pods and modular dosing systems are shifting how households and commercial buyers configure their cleaning routines. BASF SE leverages its integrated surfactant production network across Ludwigshafen and Antwerp to sustain cost advantages in anionic and non-ionic chemistries. Croda International Plc differentiates through bio-based ethoxylates derived from seed oil feedstocks, occupying a premium tier in European formulations. Dow Inc. competes on manufacturing scale in propylene oxide derivatives, anchoring supply for North American dishwashing liquid brands.
Homecare ingredients encompass the functional chemical constituents—surfactants, solvents, emulsifiers, and fragrances—formulated into products for surface cleaning, fabric care, and air treatment, typically specified by active content percentage, HLB balance, and biodegradability half-life under OECD 301 test protocols. Their primary commercial purpose is to reduce surface tension, suspend soils, or deliver controlled release of aromatic compounds in aqueous or aerosol matrices. Surfactants lead the active ingredient hierarchy due to irreplaceable roles in emulsification and wetting, while fragrances command disproportionate margin pools through proprietary encapsulation technologies. Fabric softeners within the product type dimension represent the fastest-growing category as Asian consumers upgrade from basic detergents to conditioning treatments.
EPA Safer Choice labeling in the United States and REACH registration requirements in Europe jointly elevate compliance costs for novel preservative systems and fragrance allergens. ECHA restrictions on microplastic-containing leave-on products indirectly constrain glitter and encapsulated fragrance formats, forcing reformulation toward cellulose-based alternatives. Formulators must monitor evolving state-level disclosure laws in California and New York that mandate ingredient transparency beyond current federal requirements.
Market Dynamics
Concentrated refill formats are compressing traditional single-use packaging economics across residential and institutional channels, forcing surfactant suppliers to reconfigure dosing precision and stability specifications for smaller, higher-potency SKUs.
Growth Catalysts
- EU Green Deal mandates:REACH registration requirements for biodegradable surfactants accelerate reformulation investments across European formulators, pulling demand toward ethoxylates with OECD 301-compliant half-lives.
- Institutional cleaning contracts:United States healthcare and hospitality procurement consolidations drive bulk anionic surfactant volumes, favoring suppliers with captive alkylene oxide production.
- Seed oil feedstock refining:Bio-based emulsifiers derived from rapeseed and palm kernel oils gain specification share in premium fabric softener formulations, displacing petrochemical alternatives in Asian markets.
Market Restraints
- Propylene oxide supply concentration:North American derivative production clusters along the Gulf Coast expose surfactant manufacturers to hurricane-related disruption and feedstock price volatility.
- ECHA microplastic restrictions:Encapsulated fragrance formats containing synthetic polymers face phase-out timelines, forcing costly cellulose-based alternative development.
- Quaternary ammonium compound substitution:Cationic surfactants in disinfectant applications face displacement by peracetic acid and hydrogen peroxide systems in institutional settings.
Strategic Opportunities
- Modular dosing hardware:Connected dispensing systems for concentrated refills create recurring surfactant revenue streams and lock-in relationships with multi-site facility managers.
- California SB 312 disclosure mandates:Ingredient transparency requirements exceeding federal standards favor suppliers with clean-label certification infrastructure and existing fragrance allergen databases.
- India PLI scheme for specialty chemicals:Domestic production incentives for ethoxylate and betaine manufacturing reduce import dependence for South Asian detergent formulators.
Industry Challenges
- Toxicological assessor scarcity:REACH-compliant safety data sheet authoring and hazard classification expertise concentrates in Western European consultancies, creating bottlenecks for Asian entrants.
- Legacy aerosol propellant infrastructure:Hydrocarbon-based air treatment product lines require capital-intensive retooling to accommodate compressed gas or pump alternatives under evolving volatile organic compound limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homecare Ingredients Market |
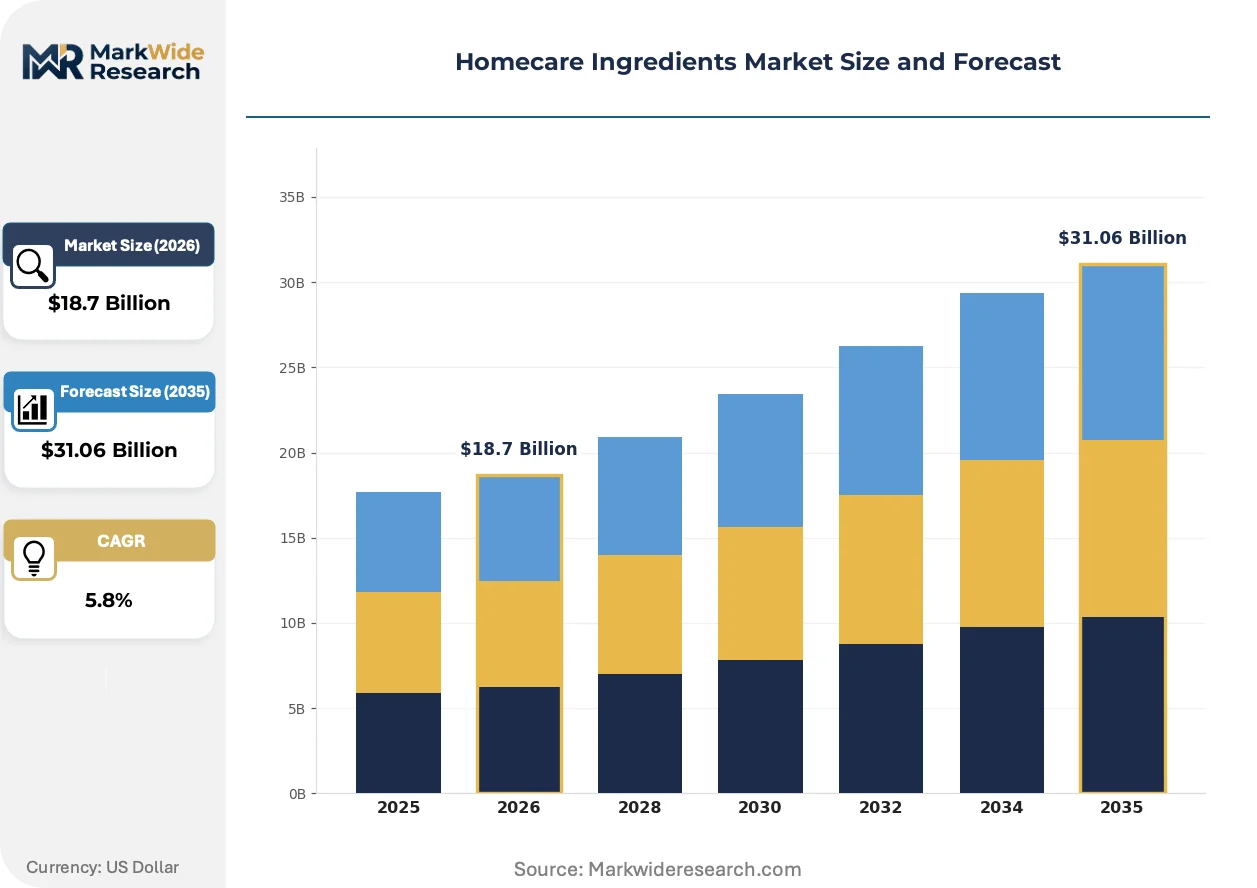
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Cleaners, Fabric Softeners, Dishwashing Liquids, Air Fresheners Active Ingredient: Surfactants, Solvents, Emulsifiers, Fragrances Application: Household Use, Institutional Cleaning, Commercial Use, Industrial Cleaning Packaging Type: Bottles, Bags, Tubs, Pouches |
| Companies Covered | Evonik Industries AG, Ashland Global Holdings Inc., BASF SE, Akzo Nobel N.V., DuPont de Nemours, Inc., Dow Inc., Croda International Plc, Cargill, Incorporated, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homecare Ingredients Market Emerging Trajectories
Formulation chemistry and delivery hardware are fusing into integrated cleaning systems, with active ingredient specifications increasingly dictated by dispensing mechanism constraints rather than standalone performance metrics.
Enzymatic stabilization technology is converging with cold-water surfactant systems to enable wash-temperature reduction without sacrificing soil removal efficiency. European household brands specify these combinations for energy-label compliance. The convergence is compressing traditional hot-water detergent categories and rewarding suppliers with protease-lipase compatibility expertise.
EPA Safer Choice labeling requirements now extend to fragrance allergens and preservative systems beyond core surfactant actives, elevating third-party certification costs for novel formulations. United States formulators must maintain dual inventory streams: certified SKUs for retail channels and conventional alternatives for price-sensitive institutional buyers. Fabric care segments face the steepest compliance burden due to prolonged skin contact exposure scenarios.
Refill subscription models displace supermarket detergent aisles as the primary household procurement channel in urban United States markets. Direct-to-consumer brands specify concentrated anionic pastes and dissolvable film pods that bypass dilute liquid logistics entirely. This channel rotation concentrates volume with suppliers capable of small-batch flexibility and rapid fragrance variant cycling.
Homecare Ingredients Market Segmentation
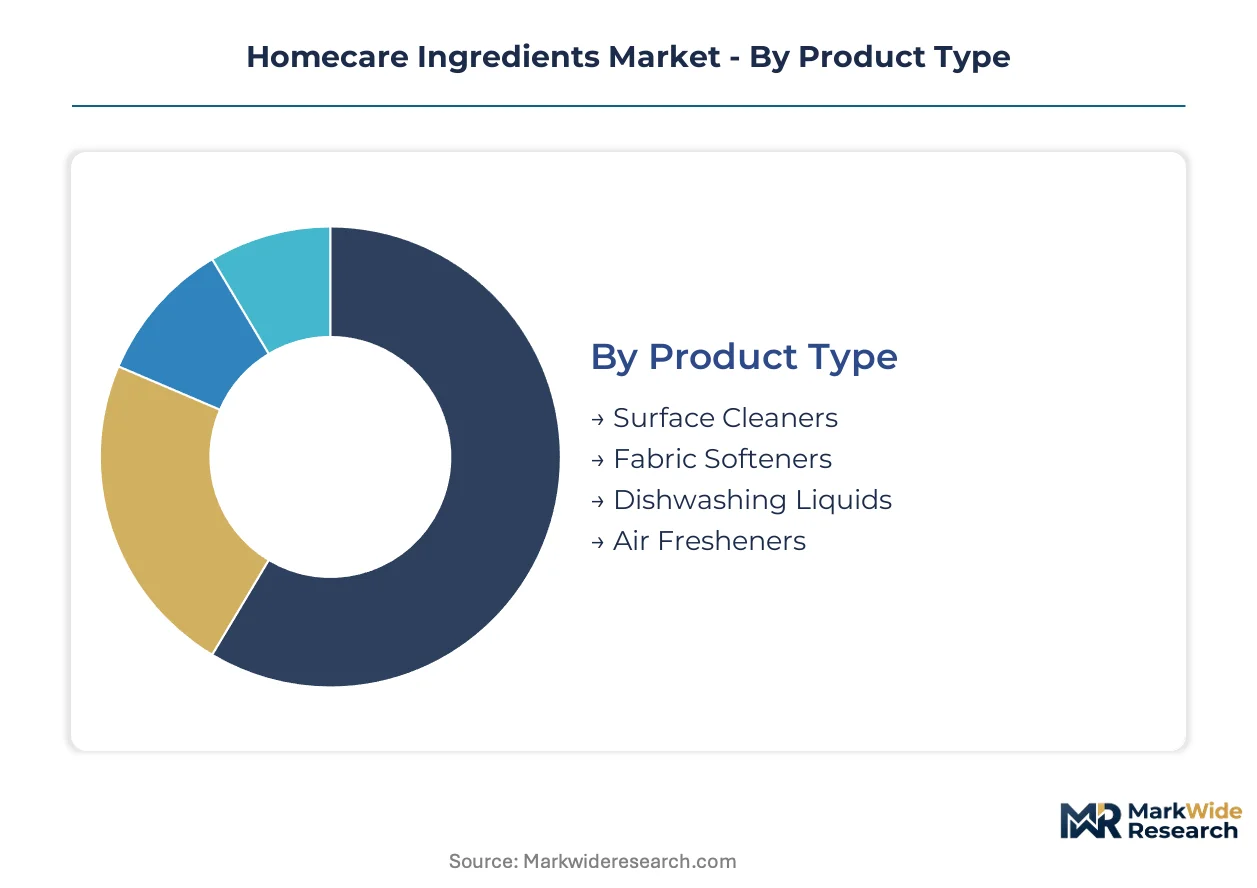
Ingredient specifications in homecare formulations diverge sharply across end-use contexts, with surfactant selection, fragrance load, and packaging compatibility requirements varying by cleaning task intensity and regulatory exposure. Suppliers configure production assets around these segment-specific technical profiles rather than generic chemical commodity positions.
Product Type:
Supply concentration in anionic surfactant production favors segments with high-volume, standardized formulation requirements over niche specialty lines.
- Fabric Softeners:Cationic quaternary ammonium compounds and silicone emulsions condition fibers while reducing static cling. Asian households in South Korea and Japan drive specification intensity as consumers upgrade from basic detergents to conditioning treatments, pulling ethoxylated amine demand toward premium conditioning actives.
- Surface Cleaners:Multi-purpose formulations blend anionic and non-ionic surfactants with alkaline builders for grease cutting on hard surfaces. Institutional procurement contracts in the United States concentrate volume with suppliers offering bulk alkylbenzene sulfonate and alcohol ethoxylate supply security.
- Dishwashing Liquids:High-foaming anionic systems with hydrotrope coupling agents for grease emulsification in hard water.
- Air Fresheners:Encapsulated fragrance delivery systems and volatile organic compound-compliant propellant bases.
Surface cleaners absorb the bulk of installed capacity; fabric softeners are expanding most quickly.
Active Ingredient:
Cost tier differentiation separates commodity surfactant feedstocks from premium bio-based and specialty encapsulated systems.
- Surfactants:Anionic, non-ionic, cationic, and amphoteric structures reduce surface tension for soil suspension and emulsification. REACH-compliant biodegradable grades from rapeseed and palm kernel oil feedstocks gain share in European fabric care as formulators phase out petrochemical alternatives under EU Green Deal timelines.
- Fragrances:Proprietary encapsulation technologies and allergen-controlled compositions command disproportionate margin pools through controlled-release matrices. California SB 312 disclosure mandates exceed federal requirements, favoring suppliers with pre-existing fragrance allergen databases and clean-label certification infrastructure.
- Solvents:Glycol ethers, alcohols, and terpenes for grease dissolution and viscosity modification.
- Emulsifiers:Sorbitan esters and polysorbates for stabilizing oil-in-water dispersions in cream and lotion formats.
Surfactants anchor volume throughput; fragrances capture the steepest margin expansion trajectory.
Application:
Customer type determines specification rigor, with institutional buyers prioritizing bulk dosing efficiency and residential channels demanding concentrated convenience formats.
- Institutional Cleaning:Healthcare and hospitality procurement consolidations in the United States specify bulk anionic surfactant volumes with precise dosing systems for infection control compliance. Gulf Coast propylene oxide derivative clusters supply captive alkylene oxide production to major contract holders, though hurricane exposure creates supply continuity risks.
- Household Use:Direct-to-consumer subscription channels in urban United States markets specify concentrated anionic pastes and dissolvable film pods that bypass dilute liquid logistics. Small-batch flexibility and rapid fragrance variant cycling concentrate volume with agile suppliers.
- Commercial Use:Retail and food service maintenance with intermediate volume and performance requirements.
- Industrial Cleaning:Heavy-duty degreasing and equipment maintenance with high-alkalinity and solvent-heavy formulations.
Institutional cleaning absorbs the bulk of installed capacity; household use is gaining share fastest through channel rotation toward subscription models.
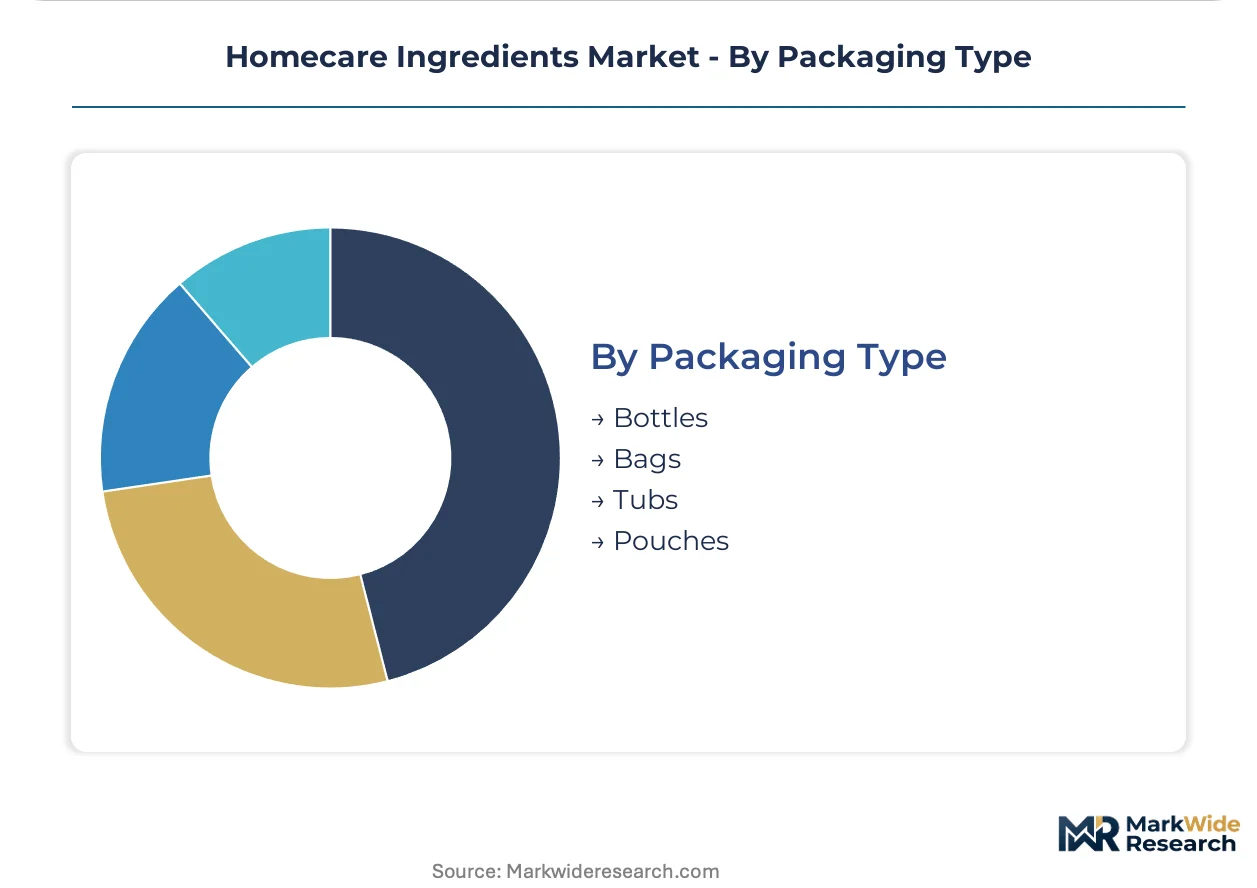
Packaging Type:
Volume economics and logistics efficiency dictate format selection, with concentrated refill systems compressing traditional bottle economics.
- Pouches:Flexible film structures for concentrated refill formats reduce shipping weight and storage footprint. European retailers specify OECD 301-compliant biodegradable surfactant concentrates in pouch formats to meet EU Green Deal packaging reduction targets while maintaining dosing precision.
- Bottles:Rigid polyethylene terephthalate and high-density polyethylene containers remain dominant for dilute ready-to-use formulations. United States supermarket and mass retail channels continue to stock bottle formats for price-sensitive consumer segments despite refill growth.
- Bags:Industrial bulk containers for institutional and commercial concentrate delivery.
- Tubs:Wide-mouth containers for powder and tablet formats in fabric care and automatic dishwashing.
Bottles retain the bulk of installed capacity; pouches are climbing the fastest on concentrated refill adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta concentrate surfactant manufacturing capacity for export-oriented fabric care brands. India's Petroleum, Chemicals and Petrochemicals Investment Regions attract ethoxylate producers with tax holidays and duty exemptions. Gulf Coast chemical clusters in the United States anchor propylene oxide derivative supply for North American institutional buyers.
United States
Healthcare and hospitality procurement consolidations specify bulk anionic surfactant volumes with precise dosing systems for infection control compliance. EPA Safer Choice labeling requirements now extend to fragrance allergens and preservative systems beyond core surfactant actives. Gulf Coast propylene oxide derivative clusters supply captive alkylene oxide production to major contract holders, though hurricane exposure creates supply continuity risks.
Germany
REACH registration requirements for biodegradable surfactants accelerate reformulation investments across European formulators. EU Green Deal mandates pull demand toward ethoxylates with OECD 301-compliant half-lives. Ludwigshafen and Antwerp host integrated surfactant production networks sustaining cost advantages in anionic and non-ionic chemistries.
China
Dual carbon goals under MEE supervision constrain coal-to-chemical surfactant feedstock expansion in Shandong and Jiangsu provinces. Domestic detergent brands upgrade from basic formulations to premium fabric softener conditioning treatments. Yangtze River Delta chemical parks concentrate ethoxylate and betaine manufacturing capacity for Southeast Asian export markets.
India
PLI scheme incentives for specialty chemicals reduce import dependence for South Asian detergent formulators. BIS standards for biodegradable surfactant active content create compliance thresholds for imported raw materials. Gujarat and Maharashtra host expanding seed oil feedstock refining capacity for bio-based emulsifier production.
Japan
METI energy-label compliance requirements specify enzymatic stabilization technology converged with cold-water surfactant systems. Household brands in Kansai and Kanto regions drive specification intensity as consumers upgrade from basic detergents to conditioning treatments. Osaka-based formulators specify premium ethoxylated amine demand for fiber conditioning actives.
Homecare Ingredients Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across differentiated tier positions. The market structure concentrates volume among integrated chemical majors with captive alkylene oxide production and captive seed oil feedstock refining. Three archetypes dominate: integrated petrochemical majors with backward control over propylene oxide supply, bio-based specialty houses with seed oil refining capabilities, and regional toll manufacturers serving local detergent formulators. Competitive moves center on modular dosing hardware partnerships and clean-label certification infrastructure investments.
Within the integrated petrochemical tier, BASF SE and Dow Inc. anchor positions through manufacturing scale in derivative chemistries. Croda International Plc exemplifies the bio-based specialty archetype with seed oil feedstock positioning. Evonik Industries AG occupies a position among European diversified chemical houses with formulation technology capabilities. These three represent distinct strategic postures: scale-driven commodity supply, premium bio-based differentiation, and technical service-intensive specialty positioning.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Ashland Global Holdings Inc. |
| BASF SE |
| Akzo Nobel N.V. |
| DuPont de Nemours, Inc. |
| Dow Inc. |
| Croda International Plc |
| Cargill, Incorporated |
| Clariant AG |
| Others |
Supply Flow & Price Mechanics
Propylene oxide feedstock costs cascade through anionic surfactant tiers, with Gulf Coast petrochemical clusters anchoring standard-grade pricing while European bio-based ethoxylates command premiums through REACH compliance overhead.
Pricing Analysis
Margin tightening in standard-grade surfactants reflects propylene oxide volatility and concentrated Gulf Coast production exposure. Three-tier pricing structure across premium bio-based, standard petrochemical, and economy bulk grades separates suppliers by certification infrastructure and feedstock origin. Institutional buyers in United States healthcare procurement drive cost-down pressure through consolidated contract volumes, while Asian fabric softener formulators absorb premium cationic surfactant prices with limited substitution options.
Supply Chain Analysis
Single-source vulnerability sits with propylene oxide derivative production clustered along the United States Gulf Coast, exposing surfactant manufacturers to hurricane-related disruption. China, Germany, and Belgium anchor ethoxylate and alkylbenzene sulfonate capacity through Yangtze River Delta parks, Ludwigshafen-Antwerp networks, and seed oil refining hubs. Raw material dependencies span palm kernel and rapeseed oils, ethylene oxide, and linear alkylbenzene. Tariff exposure on Southeast Asian oleochemical imports threatens bio-based supply continuity. Distribution runs through bulk tanker shipments to institutional buyers and concentrated pouch formats to direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alkylene oxide capacity constraints in Western Europe prop pricing premiums for REACH-compliant biodegradable grades, sustaining supplier margin pools despite feedstock volatility.
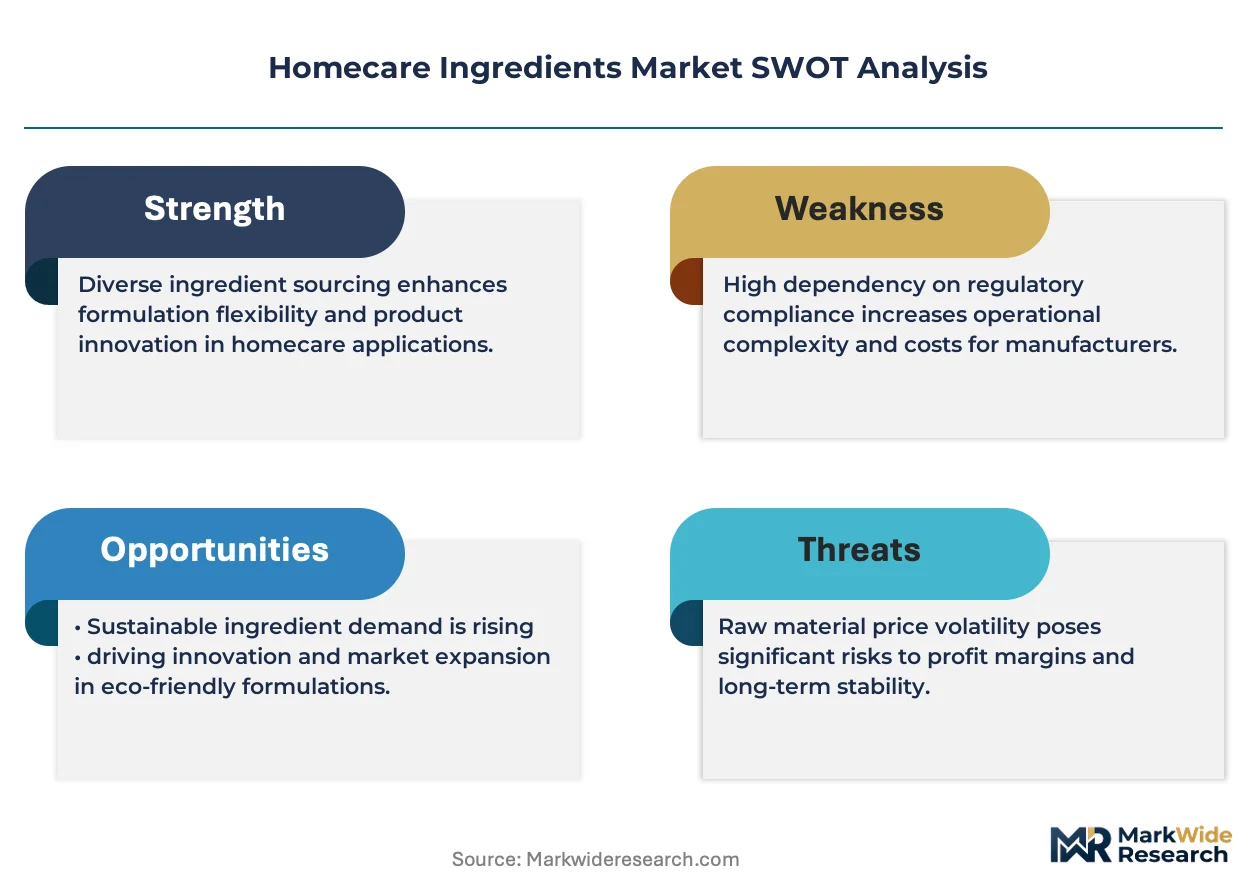
For Market Incumbents: Acquire modular dosing hardware capabilities to lock in recurring surfactant revenue streams with multi-site facility managers. BASF SE and Dow Inc. should expand captive seed oil refining partnerships in India and Southeast Asia to hedge Gulf Coast propylene oxide concentration. ECHA microplastic restrictions on encapsulated fragrances threaten specialty margin pools; cellulose-based alternative R&D is essential. For New Entrants and Emerging Players: Direct-to-consumer subscription channels in urban United States markets offer the most penetrable entry vector for concentrated anionic paste suppliers. Small-batch flexibility and rapid fragrance variant cycling capabilities separate agile entrants from legacy commodity players. California SB 312 disclosure mandates create compliance barriers favoring suppliers with pre-existing clean-label certification infrastructure. For Investors and Strategic Acquirers: India PLI scheme announcements for specialty chemicals are the leading indicator that domestic ethoxylate and betaine manufacturing will displace import-dependent supply chains. Long-term viability rests on backward integration into seed oil feedstock refining and modular dosing hardware partnerships. Target acquisition archetype: regional toll manufacturers with BIS-compliant biodegradable surfactant capabilities and established relationships with South Asian detergent formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Oil Feedstock | Croda International Plc's rapeseed and palm kernel refining secures bio-based ethoxylate cost advantages under EU Green Deal timelines. |
| Modular Dosing Hardware Partnership | Connected dispensing systems for concentrated refills create recurring revenue streams with United States healthcare procurement consolidations. |
| REACH-Compliant Biodegradable Reformulation | OECD 301-compliant surfactant half-lives satisfy ECHA registration requirements and command premium positioning in European fabric care. |
| California SB 312 Certification Infrastructure | Pre-existing fragrance allergen databases enable rapid compliance with disclosure mandates exceeding federal EPA Safer Choice standards. |
| India PLI Scheme Manufacturing Expansion | Domestic ethoxylate and betaine production reduces import dependence for South Asian detergent formulators and captures tax incentives. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant managers at integrated surfactant facilities, procurement leads at United States healthcare and hospitality contract holders, distribution channel partners in European retail, and technical R&D directors at bio-based specialty houses. Bottom-up volume modeling triangulated against top-down value estimates derived from ACC, Cefic, and SEC 10-K disclosures.
Segmentation granularity spanned product type, active ingredient chemistry, application context, and packaging format across the projection horizon. CAGRs were derived from fitted growth curves incorporating alkylene oxide capacity expansion timelines, REACH registration phase-in schedules, and channel shift velocities toward subscription-based concentrated refills. Forecast inputs included institutional procurement contract renewal patterns and enzymatic stabilization technology adoption rates in cold-water detergent systems.
Caveats apply where ECHA microplastic restriction enforcement timelines, Gulf Coast hurricane disruption frequency, or India PLI scheme allocation outcomes could materially shift the outlook. Forecasts reflect assumptions about regulatory implementation consistency and feedstock price normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Soy Protein Ingredients Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Refined Coconut Oil Market
Ingredients
Boysenberry Extract Market
Ingredients
China Gelatin Market
Ingredients
Distiller's Dried Grains with Solubles (DDGS) Feed Market
Ingredients
Italy Soy Protein Market
Ingredients
Functional Flours Market
Ingredients
Europe Amino Acid Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Bovine Gelatin Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Clean Label Starch Market
Ingredients
Codonopsis Extract Market
Ingredients
Seaweed Derivatives Market
Ingredients
Revivable Yeast Market