
 Instant Ramen Market | 2026-2036
Instant Ramen Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Ramen Market Insights
EU Green Deal nutrition labeling standards is pivoting the cost-of-entry calculus for manufacturers seeking European market access. Nissin Foods Holdings leverages its R&D intensity to reformulate recipes ahead of compliance deadlines. PT Indofood CBP Sukses Makmur anchors its dominance through backward integration into palm oil and wheat flour supply chains. Nongshim competes via specialized spicy flavor profiles that differentiate its portfolio in crowded Asian retail channels.
Instant ramen denotes wheat-based alkaline noodles that undergo steaming, oil-frying or air-drying, then pairing with dehydrated seasoning oil and powder sachets for reconstitution in boiling water within three minutes. The primary commercial purpose centers on delivering shelf-stable, low-cost caloric intake to time-constrained consumers without refrigeration infrastructure. Packets sustain the largest volume share due to minimal packaging cost and transport efficiency, while bowls command premium shelf positioning in convenience stores across Japan and South Korea. Spicy flavor profiles represent the fastest-expanding category as younger demographics in Mexico and Nigeria develop tolerance for capsaicin-forward formulations. Online retailers are displacing traditional supermarket channels for bulk purchases, though convenience stores retain impulse-buy dominance in dense East Asian urban corridors.
FDA sodium reduction targets and Japan's Consumer Affairs Agency front-of-pack labeling mandates compel reformulation investments that favor large-scale manufacturers with dedicated nutrition science teams. China's SAMR food safety standards and Indonesia's BPOM halal certification requirements create layered compliance barriers for new entrants. Stakeholders must monitor regulatory divergence between sodium-limiting Western frameworks and permissive Asian standards that preserve traditional taste profiles.
Market Dynamics
FDA sodium reduction targets and Japan's Consumer Affairs Agency front-of-pack labeling mandates compel manufacturers to reformulate core recipes. Large-scale producers with dedicated nutrition science teams capture compliance advantages while smaller competitors face exit pressures.
Growth Catalysts
- Urbanization in emerging economies:College students and young professionals in Indonesia and Vietnam drive adoption of convenient meal solutions without refrigeration infrastructure.
- EU Green Deal nutrition standards:The framework is pivoting cost-of-entry calculus for manufacturers, rewarding early reformulators with preferential shelf positioning.
- Air-drying technology:Non-fried noodle production methods reduce oil content and align with health-positioned product lines in premium segments.
Market Restraints
- Wheat and palm oil input volatility:Commodity price swings compress margins for manufacturers lacking backward integration into agricultural supply chains.
- Halal certification complexity:Indonesia's BPOM requirements and divergent national standards create layered compliance barriers for new entrants seeking Southeast Asian market access.
- Fresh prepared meal substitution:Cold-chain expansion in dense East Asian urban corridors enables refrigerated alternatives that compete on perceived freshness.
Strategic Opportunities
- Nigeria and Mexico demand expansion:Younger demographics in these markets develop tolerance for capsaicin-forward formulations, opening premium spicy product lines.
- Online bulk purchasing channels:E-commerce platforms displace traditional supermarket channels for volume sales, reducing intermediary costs.
- Non-fried production incentives:Japan's health-oriented labeling schemes reward manufacturers investing in air-drying capital equipment.
Industry Challenges
- Reformulation R&D talent scarcity:Nutrition science expertise for sodium reduction without taste degradation concentrates at established firms, constraining smaller competitors.
- Dual certification timelines:Simultaneous compliance with China's SAMR food safety standards and halal requirements extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Ramen Market |
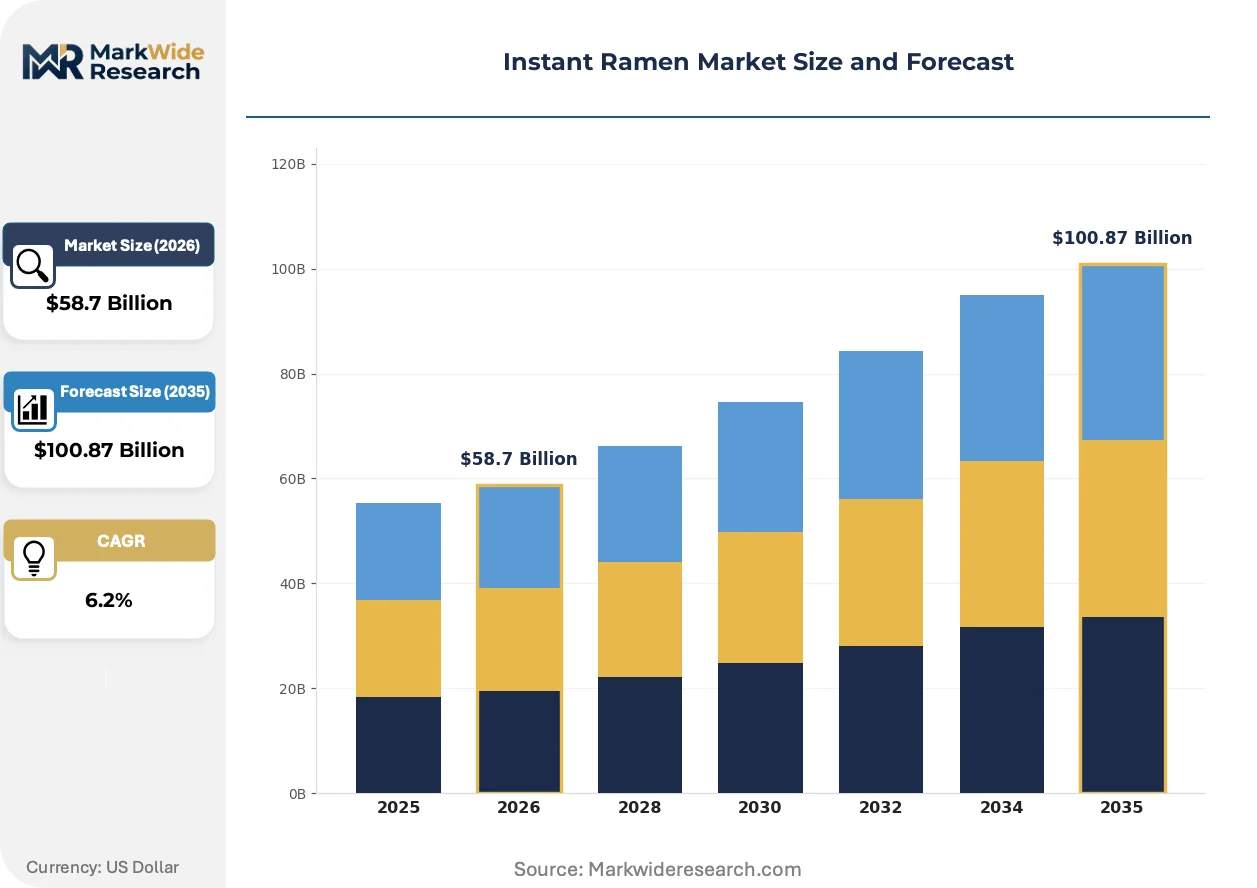
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $100.87 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bowls, Cups, Packets, Cups with Noodles Flavor Profile: Spicy, Chicken, Beef, Seafood Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores Packaging Type: Plastic, Foam, Paper, Aluminum |
| Companies Covered | Nissin Foods Holdings Co., Ltd., PT Indofood CBP Sukses Makmur Tbk, Nongshim Co., Ltd., Tingyi (Cayman Islands) Holding Corp., Samyang Foods, Toyo Suisan Kaisha, Ltd., Ottogi Corporation, Acecook Co., Ltd., Uni-President Enterprises Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Ramen Market Trends and Innovations
Reformulation investments are absorbing capital flows as manufacturers confront divergent regulatory frameworks. Health-positioned product architectures and channel restructuring dominate strategic planning.
Air-drying production technology is absorbing facility upgrade budgets across mid-scale manufacturers. The process eliminates oil-frying stages while preserving shelf stability. Health-conscious buyers in South Korea and Japan are adopting these products at accelerating rates. The technology is absorbing market share from traditional fried-noodle segments in premium retail channels.
Japan's Consumer Affairs Agency front-of-pack labeling mandates force disclosure of sodium and fat content. Manufacturers must reformulate or accept degraded shelf positioning. Bowl-format products in Japanese convenience stores face the steepest compliance costs due to their premium positioning.
Bulk purchasing through e-commerce platforms is fragmenting traditional supermarket dominance. Young urban professionals in dense East Asian corridors now order multi-month supplies online. Convenience stores retain impulse-buy traffic but lose planned purchases. This channel rotation is most visible in Tokyo and Seoul metropolitan areas.
Instant Ramen Market Segmentation
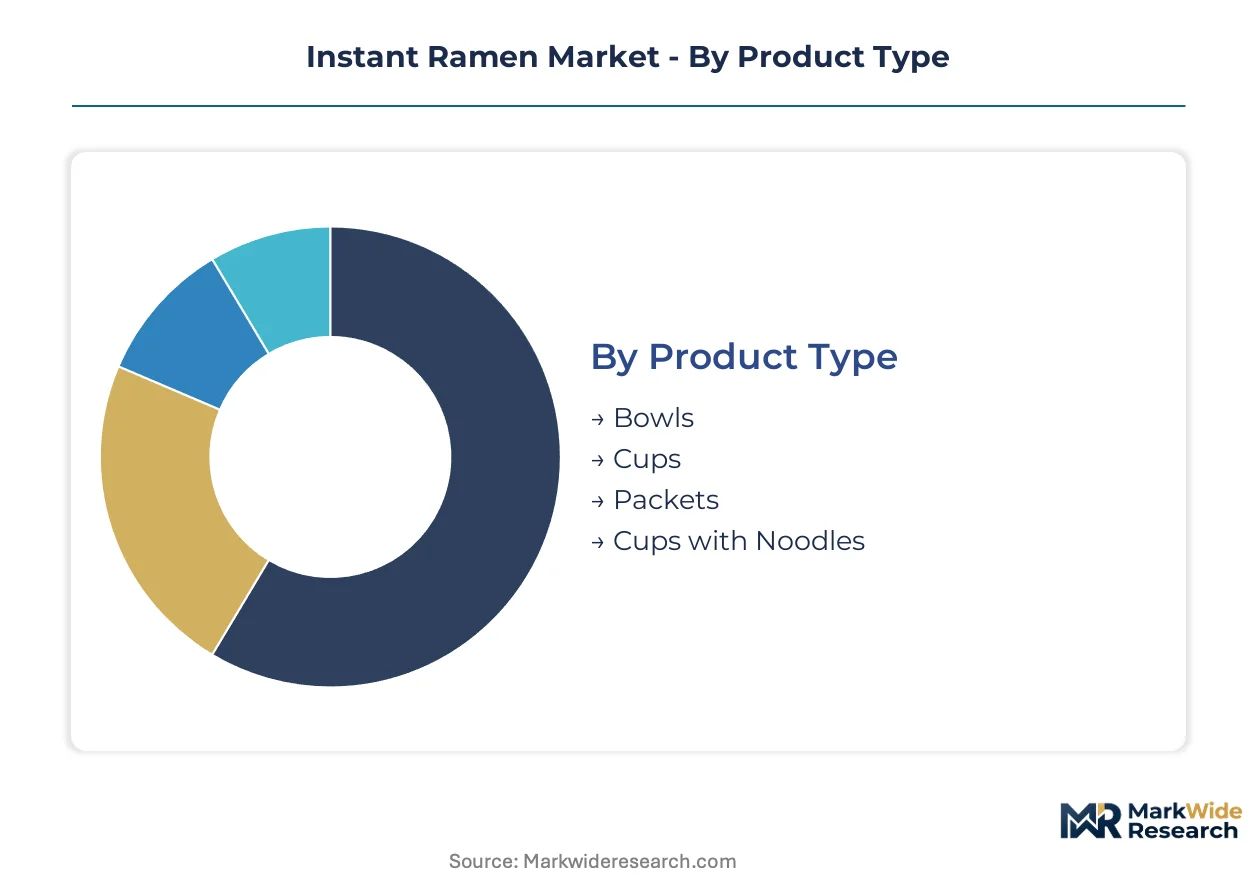
Segmentation in instant ramen determines capital allocation priorities across production equipment, packaging lines, and distribution partnerships. Manufacturers must match facility investments to format-specific requirements while navigating divergent regulatory thresholds by geography.
Product Type:
Capital intensity varies sharply across formats, with bowl production requiring molded-fiber or thermoforming equipment that multiplies fixed costs against packet lines.
- Packets:Flat, rectangular foil-laminate pouches containing compressed noodle blocks and sachets of seasoning oil and powder. Demand concentrates in Indonesian and Vietnamese households purchasing multi-unit bundles for home preparation, driven by minimal unit economics that sustain penetration in price-sensitive emerging markets.
- Bowls:Round, wide-mouth containers with integrated lids housing wider noodles, dehydrated vegetables, and liquid seasoning pouches. Demand concentrates in Japanese and South Korean convenience stores where premium shelf positioning targets urban professionals seeking immediate consumption without additional dishware, constrained by front-of-pack labeling mandates that elevate compliance costs.
- Cups:Tapered cylindrical containers with peel-back foil lids designed for single-serve portability. Commuter corridors in dense East Asian cities sustain procurement.
- Cups with Noodles:Hybrid formats combining cup convenience with enhanced noodle texture through separate compartmentalization. Niche positioning in premium Japanese retail channels.
Most installed capacity flows through Packets. Expansion is steepest in Bowls.
Flavor Profile:
Flavor positioning determines raw material sourcing complexity and R&D amortization timelines, with spicy variants demanding specialized chili supply chains and tolerance-calibrated formulation.
- Spicy:Capsaicin-forward formulations ranging from mild heat to extreme Scoville ratings, often incorporating chili oil, fermented pepper pastes, or extract concentrates. Younger demographics in Mexico and Nigeria drive procurement as capsain tolerance develops through repeated exposure, opening premium pricing tiers previously unavailable to wheat-noodle categories.
- Chicken:Mild, umami-rich profiles built on hydrolyzed soy protein, yeast extract, and poultry-derived flavor bases. Southeast Asian mass-market penetration sustains volume leadership despite compressed margins.
- Beef:Hearty profiles emphasizing hydrolyzed vegetable protein and caramelized note systems. Established presence in North American and European ethnic food aisles.
- Seafood:Delicate profiles incorporating dried shrimp, fish sauce powders, and kelp-derived glutamates. Coastal East Asian markets anchor demand with freshness-perception constraints limiting inland expansion.
Chicken retains the largest production base. Spicy profiles are climbing the fastest.
Distribution Channel:
Channel selection dictates working capital requirements and margin structure, with direct-to-consumer platforms demanding logistics investment against traditional retail's slotting fee burdens.
- Supermarkets:Full-format retail with dedicated ethnic or instant noodle aisles, requiring trade promotion spending and shelf-space negotiation. Indonesian and Vietnamese hypermarket chains sustain volume through promotional bundling.
- Online Retailers:E-commerce platforms enabling bulk purchasing with reduced intermediary layers. Tokyo and Seoul metropolitan areas show the steepest platform migration as young professionals order multi-month supplies.
- Convenience Stores:Dense urban networks emphasizing impulse procurement and immediate consumption. Japanese 7-Eleven and Lawson chains retain traffic through 24-hour availability and heated water stations.
- Specialty Stores:Asian grocery chains and ethnic food importers curating premium or import-exclusive SKUs. North American and European Korean and Japanese specialty retailers anchor this channel.
Supermarkets still process the highest absolute volume. Online Retailers show the steepest channel-share gain.
Packaging Type:
Material selection determines regulatory compliance exposure and sustainability positioning, with plastic facing substitution pressure from fiber-based alternatives in premium segments.
- Plastic:Polypropylene or polyethylene containers and films offering moisture barrier properties and microwave compatibility. Southeast Asian cost optimization sustains dominance despite EU Green Deal circularity pressures.
- Foam:Expanded polystyrene bowls providing thermal insulation and structural rigidity at minimal weight. Japan's Consumer Affairs Agency disclosure requirements and municipal waste regulations accelerate phase-out.
- Paper:Molded fiber or coated paperboard formats aligning with health-positioned and sustainability-marketed product lines. South Korean and Japanese premium segments absorb price premiums for perceived environmental credentials.
- Aluminum:Metallized films and foil lids providing complete light and oxygen barriers for extended shelf stability. High-value export and military-specification applications sustain niche demand.
Plastic retains the largest installed base. Paper formats are gaining share fastest in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production talent and R&D expertise cluster around established manufacturing corridors in East and Southeast Asia, with formulation scientists and process engineers concentrated in legacy noodle-producing regions.
Indonesia
College students and young urban professionals in Jakarta and Surabaya drive household demand for packet-format products. BPOM halal certification requirements create compliance barriers that favor established domestic producers. Manufacturing capacity concentrates in West Java industrial zones where palm oil and wheat flour supply chains anchor backward integration.
Japan
Convenience store networks in Tokyo and Osaka metropolitan areas sustain premium bowl-format procurement. Consumer Affairs Agency front-of-pack labeling mandates force sodium disclosure and recipe reformulation. Nagoya and Yokohama production clusters absorb air-drying technology investments to meet health-positioned product demand.
South Korea
Spicy flavor tolerance among Seoul Capital Area consumers supports premium capsaicin-forward product lines. MFDS nutrition labeling standards align with Japan's disclosure frameworks. Busan-Ulsan manufacturing corridors specialize in non-fried noodle production for health-conscious export markets.
Vietnam
Urban wage growth in Ho Chi Minh City and Hanoi expands middle-class adoption of convenient meal solutions. National food safety standards from the Vietnam Food Administration reshape import requirements. Mekong Delta agricultural zones supply wheat and palm oil inputs to domestic manufacturers.
China
SAMR food safety standards and dual carbon goals pressure manufacturers toward cleaner production methods. Yangtze River Delta and Pearl River Delta industrial clusters house the largest installed production capacity. E-commerce platforms in Shanghai and Shenzhen displace traditional retail for bulk purchasing among young professionals.
Instant Ramen Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Large-scale manufacturers with captive agricultural supply chains and dedicated nutrition science teams capture compliance advantages from sodium reduction mandates. Three archetypes dominate: integrated agribusiness-noodle conglomerates controlling upstream inputs; R&D-intensive Japanese and South Korean innovators; and regional specialists leveraging localized flavor profiles. Competitive moves concentrate on backward integration into palm oil and wheat flour supply chains, plus air-drying technology licensing to meet health-positioned demand.
Among Japan-based innovators, Nissin Foods Holdings Co., Ltd. and Toyo Suisan Kaisha, Ltd. exemplify the R&D-intensive archetype with reformulation capabilities ahead of regulatory deadlines. South Korea's Nongshim Co., Ltd. occupies a position within the flavor-specialist tier, while Indonesia's PT Indofood CBP Sukses Makmur Tbk represents the integrated conglomerate model with upstream control over critical agricultural inputs. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive positioning in a market where compliance scale and supply chain ownership determine viability.
| Leading Market Players |
|---|
| Nissin Foods Holdings Co., Ltd. |
| PT Indofood CBP Sukses Makmur Tbk |
| Nongshim Co., Ltd. |
| Tingyi (Cayman Islands) Holding Corp. |
| Samyang Foods |
| Toyo Suisan Kaisha, Ltd. |
| Ottogi Corporation |
| Acecook Co., Ltd. |
| Uni-President Enterprises Corp. |
| Others |
Pricing and Supply Chain Analysis
Wheat futures on the Chicago Board of Trade and palm oil benchmarks from the Bursa Malaysia Derivatives Exchange cascade through instant ramen manufacturing into three distinct pricing tiers. Commodity volatility compresses margins at the economy end while premium bowl formats absorb input cost spikes through brand equity buffers in Japanese convenience stores.
Pricing Analysis
Bundled bowl formats with integrated dehydrated vegetables and liquid seasoning pouches command shelf price premiums against unbundled packet products requiring separate ingredient procurement. Three-tier pricing structure across premium, standard, and economy levels separates air-dried health-positioned lines from traditional fried-noodle staples and entry-level mass-market packets. Pricing pressure stems from EU Green Deal circularity mandates elevating fiber-based packaging costs. College students in Indonesian and Vietnamese markets exhibit highest price sensitivity, while young urban professionals in Tokyo and Seoul absorb premiums for convenience and health positioning.
Supply Chain Analysis
Freight cost differentials between containerized ocean lanes and regional trucking networks concentrate procurement power among manufacturers with captive logistics assets. Production gravity centers on Indonesia, China, and Japan, with Mekong Delta and Yangtze River Delta agricultural zones feeding wheat and palm oil inputs. Manufacturing draws from specialized seasoning concentrate suppliers in South Korea and thermoforming equipment vendors in Japan. Single-source vulnerability in chili paste supply chains for spicy flavor profiles exposes reformulation timelines to harvest volatility. Distribution runs through layered wholesaler networks in Southeast Asia against direct-store-delivery systems in East Asian convenience corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Japan's Consumer Affairs Agency front-of-pack labeling mandates accelerate R&D investment cycles and consolidate advantage among scaled reformulators.
For Market Incumbents: Anchor compliance scale through dedicated nutrition science teams capable of sodium reduction without taste degradation, insulating against FDA and Japan Consumer Affairs Agency mandates that threaten smaller competitors. Deepen backward integration into Indonesian palm oil estates and Chinese wheat milling capacity to neutralize commodity volatility compressing economy-tier margins. Control air-drying technology licensing to capture premium positioning as health-conscious buyers migrate from fried-noodle segments. For New Entrants and Emerging Players: Air-drying production technology offers a technology-first wedge for mid-scale manufacturers seeking health-positioned differentiation without legacy fried-noodle asset burdens. Target Nigeria and Mexico spicy flavor expansion where capsaicin tolerance development among younger demographics opens premium pricing tiers unavailable to established players. Pursue e-commerce bulk purchasing channels in Tokyo and Seoul metropolitan areas to bypass supermarket slotting fees that entrench incumbent distribution control. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing halal certification infrastructure and localized flavor R&D capabilities in Southeast Asian markets. Five-to-ten year viability hinges on regulatory compliance scalability rather than volume share alone. Watch BPOM and SAMR enforcement intensity as the inflection signal separating consolidatable mid-tier assets from distressed exits.| Strategic Initiative | Industry Significance |
|---|---|
| Air-Drying Technology Licensing | Captures health-positioned demand under Japan's Consumer Affairs Agency labeling incentives. |
| Backward Integration into Palm Oil | Neutralizes Bursa Malaysia price volatility threatening Indonesian and Vietnamese economy-tier margins. |
| Halal Certification Infrastructure | Unlocks BPOM-compliant access to Southeast Asian markets where religious dietary requirements gate distribution. |
| E-Commerce Channel Expansion | Displaces supermarket intermediaries in Tokyo and Seoul bulk purchasing corridors among young professionals. |
| Spicy Flavor R&D Investment | Targets Nigeria and Mexico demographic shifts toward capsaicin-forward premium positioning. |
Research Methodology
Multiple input streams — formulation scientist interviews, retail channel audits, and commodity trade data — were reconciled to construct bottom-up and top-down market estimates. Primary fieldwork captured perspectives from instant ramen brand managers, convenience store category buyers at Japanese 7-Eleven and Lawson chains, palm oil procurement leads at Indonesian agribusiness conglomerates, and regulatory affairs specialists navigating BPOM and SAMR compliance pathways. Secondary validation drew from FDA sodium reduction guidance documents, Japan Consumer Affairs Agency labeling rulemakings, Bursa Malaysia Derivatives Exchange palm oil futures data, and Nielsen retail audit series for East Asian noodle categories.
Data-stream reconciliation across product format segmentation, flavor profile demand curves, and distribution channel economics anchored the analytical framework over the projection horizon. Modeled dimensions encompassed packet-bowl-cup format splits, spicy-chicken-beef-seafood flavor positioning, and supermarket-online retail-convenience store channel shares. CAGRs were derived from elasticity-calibrated demand functions incorporating urbanization rates, regulatory compliance cost trajectories, and commodity input price scenarios. Air-drying technology adoption curves and halal certification penetration timelines fed industry-specific forecast inputs.
The model holds under stable regulatory enforcement intensity and contained commodity volatility; deviation in BPOM or SAMR rulemaking stringency, or sustained wheat and palm oil price spikes, would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Convenience Food Market
Packaged Foods
Japan Packaged Food Products Market
Packaged Foods
Condensed Canned Soups Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Pre-Packaged Food Market
Packaged Foods
Iraq Dried Pasta Market
Packaged Foods
Instant Noodles Market
Packaged Foods
Peanut Butter Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
India Packaged Food Products Market
Packaged Foods
Global Oven Bags Market
Packaged Foods
Quinoa Pasta Market
Packaged Foods
South America Canned Fruits Market
Packaged Foods
Spreads Market