
 Steam Trap Monitor Market | 2026-2036
Steam Trap Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Trap Monitor Market Outlook
ISO 9001 certification for quality management systems is bifurcating the competitive landscape between established industrial automation suppliers and emerging IoT-native entrants. Forbes Marshall Private Limited leverages decades of steam system expertise to anchor its position in process-intensive manufacturing sectors across South Asia. Spirax-Sarco Engineering plc sustains technology leadership through deep specialization in thermal efficiency optimization and predictive diagnostics. Emerson Electric Co. competes by extending its automation portfolio into cloud-integrated condition monitoring for distributed steam networks.
A steam trap monitor is a sensing and communication device that detects operational states—temperature differentials, acoustic signatures, or conductivity changes—to identify steam trap failures, stuck-open conditions, or condensate backup in pressurized steam distribution systems. These instruments typically operate at temperatures exceeding 200°C with ingress protection ratings of IP65 or higher to survive saturated industrial environments, enabling facilities to prevent energy losses that otherwise waste 10-20% of generated steam. Electronic product types command the widest deployment footprint due to their compatibility with plant-wide IoT architectures and real-time alert capabilities. Cloud-based technology segments are attracting disproportionate R&D investment as operators seek centralized dashboards spanning multi-site boiler operations. Energy efficiency applications generate the most consistent procurement pull because steam losses translate directly into fuel expenditure and carbon emissions liabilities.
The U.S. Environmental Protection Agency enforces emissions reporting requirements that pressure industrial facilities to quantify and reduce energy waste from failed steam traps. Germany's Federal Environment Agency aligns with EU Green Deal targets by tightening efficiency standards for steam-intensive process industries. India's Bureau of Energy Efficiency mandates periodic energy audits under the Perform Achieve Trade scheme that explicitly catalog steam system losses, creating compliance-driven procurement cycles. Stakeholders must weigh the trade-off between retrofitting legacy mechanical traps with add-on sensors versus full replacement with integrated smart traps as capital planning horizons compress.
Market Dynamics
EU Green Deal emissions benchmarks are forcing pharmaceutical and chemical manufacturers to quantify steam losses with precision, compressing replacement cycles for legacy mechanical traps and accelerating procurement of sensor-based predictive maintenance platforms.
Growth Catalysts
- EU Green Deal alignment:Germany's Federal Environment Agency tightens efficiency standards for steam-intensive process industries, mandating documented energy audits that catalog trap failures as direct carbon liabilities.
- Sensor fusion architectures:Temperature differential detection combined with acoustic signature analysis enables real-time failure classification, cutting diagnostic latency from weeks to minutes in pressurized distribution systems.
- Gulf Coast chemical clusters:Concentrated petrochemical infrastructure along the Texas-Louisiana corridor generates concentrated retrofit demand as operators face EPA emissions reporting requirements for quantified energy waste reduction.
Market Restraints
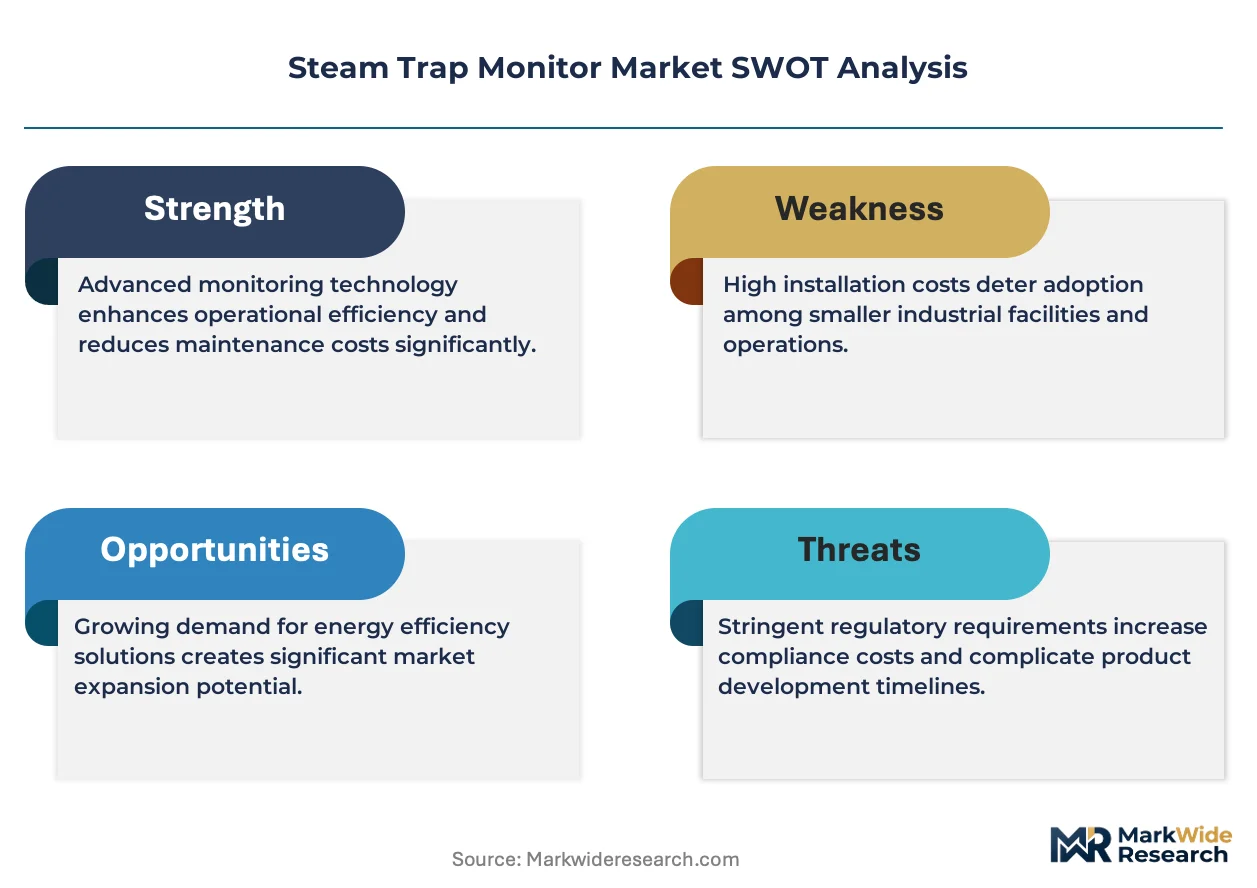
- High-temperature electronics cost:Components rated for sustained operation above 200°C with IP65 ingress protection carry 3-4x material premiums versus standard industrial sensors, compressing margins on entry-tier offerings.
- Legacy trap installed base:Decades-old mechanical trap populations in mature industrial regions create sunk-cost resistance to full replacement versus add-on sensor retrofit approaches.
- Specialized installation labor:Certified technicians capable of hot-tap sensor deployment in live steam systems remain concentrated in established industrial automation hubs, constraining rollout velocity in peripheral markets.
Strategic Opportunities
- India Perform Achieve Trade scheme:Bureau of Energy Efficiency mandates create compliance-driven procurement cycles for energy audit equipment, including explicit steam system loss cataloging requirements.
- Cloud-integrated multi-site dashboards:Centralized monitoring spanning distributed boiler operations addresses operator needs for visibility across fragmented facility portfolios without on-premise infrastructure investment.
- Integrated smart trap form factors:Full replacement units with embedded sensing eliminate retrofit installation complexity, capturing preference from capital planners with compressed planning horizons.
Industry Challenges
- Thermodynamic modeling expertise:Facilities lack in-house capability to interpret acoustic signature patterns and temperature differential data, creating dependency on vendor-provided analytics and slowing autonomous troubleshooting.
- ISO 9001 certification timelines:Quality management system audits for supplier qualification extend procurement cycles by 6-12 months, favoring incumbent industrial automation suppliers over IoT-native entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Trap Monitor Market |
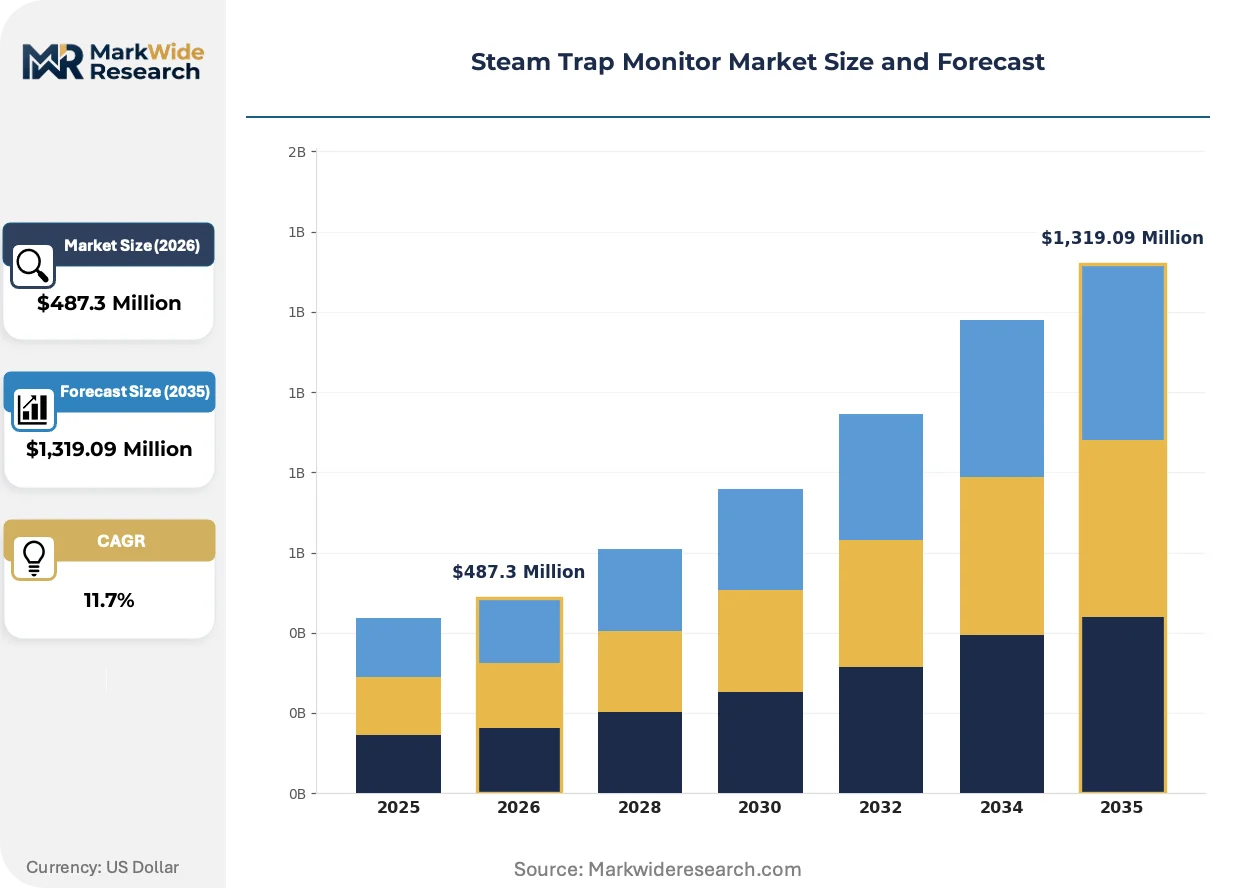
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electronic, Thermal, Hybrid Technology: Sensors, IoT, Data Analytics, Cloud-based End User: Manufacturing, Power Generation, Food Processing, Pharmaceuticals Application: Energy Efficiency, Preventive Maintenance, Leak Detection, Performance Monitoring |
| Companies Covered | Forbes Marshall Private Limited, GESTRA AG, Spirax-Sarco Engineering plc, Yoshitake Inc., IMI Critical Engineering, Armstrong International Inc., Thermax Limited, Emerson Electric Co., TLV Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Trap Monitor Market Strategic Shifts
Steam trap monitoring hardware is undergoing radical size and connectivity transformation as edge computing capabilities migrate into sensing nodes. These shifts compress deployment costs and expand addressable infrastructure.
MEMS-based acoustic sensors is miniaturizing failure detection equipment from rack-mounted analyzers to palm-sized modules that clamp directly onto trap bodies. Pharmaceutical cleanroom operators in Germany adopt these reduced-footprint devices to avoid contamination risks from bulky instrumentation. The form factor reduction enables trap-by-trap deployment economics that were previously viable only on critical high-pressure headers.
The U.S. Environmental Protection Agency enforces emissions reporting requirements that pressure industrial facilities to quantify and reduce energy waste from failed steam traps. Chemical processors along the Gulf Coast now treat trap monitoring data as auditable compliance documentation rather than operational convenience. This regulatory framing elevates procurement authority from maintenance departments to sustainability officers with direct C-suite reporting lines.
Buyer preference is consolidating around subscription-structured condition monitoring services that bundle hardware, connectivity, and predictive analytics into per-trap monthly fees. Equipment distributors in process-intensive manufacturing sectors are repositioning as managed service providers, displacing traditional capital equipment sales cycles. This shift is most visible in United States chemical processing clusters where operating expense treatment of monitoring costs accelerates internal approval workflows.
Steam Trap Monitor Market Segmentation
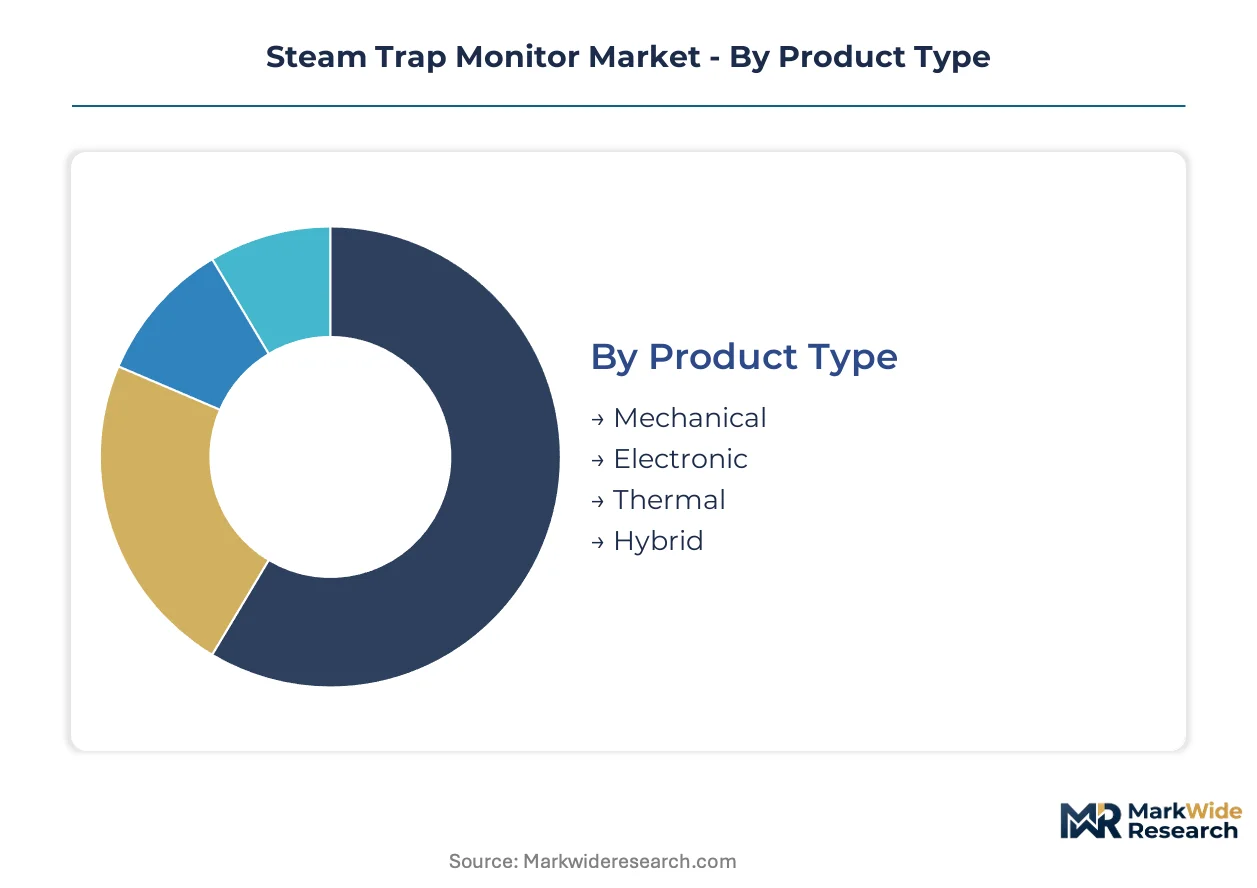
Steam trap monitor procurement decisions fragment across technical specifications, connectivity architectures, and compliance-driven use cases. Each segmentation axis carries distinct regulatory implications that reshape vendor qualification criteria and installation protocols.
Product Type:
EPA emissions reporting requirements and EU Green Deal benchmarks create divergent certification burdens across mechanical versus electronic form factors, with thermal and hybrid designs occupying intermediate compliance positions.
- Electronic:Microprocessor-driven units integrate temperature differential sensors and acoustic signature analysis for real-time failure classification. Chemical processing clusters along the Texas-Louisiana corridor favor these for auditable compliance documentation under EPA mandates.
- Mechanical:Bimetallic or thermostatic actuation without electrical components survives in explosion-rated zones where intrinsic safety overrides connectivity demands. Pharmaceutical cleanroom operators in Germany specify these where electromagnetic interference risks contaminate sensitive processes.
- Thermal:Infrared or thermographic detection identifies steam loss through surface temperature mapping without trap intrusion. Refinery operators deploy these for non-invasive screening of high-pressure headers.
- Hybrid:Combines mechanical actuation with bolt-on sensor modules for phased retrofit economics. Mature industrial regions with sunk-cost mechanical trap populations drive procurement here.
Electronic units handle the majority of throughput; hybrid designs are expanding most quickly as capital planners weigh replacement against retrofit economics.
Technology:
Cost tier stratification separates premium cloud-integrated platforms from entry sensor hardware, with IoT middleware and analytics layers capturing disproportionate margin expansion.
- Cloud-based:Centralized dashboards aggregate multi-site boiler operations without on-premise infrastructure. Food processing chains across distributed geographies subscribe to per-trap monthly fee structures that accelerate internal approval workflows.
- IoT:Edge computing nodes embed wireless connectivity and local data buffering for intermittent network environments. Power generation utilities specify these for remote substations with unreliable backhaul.
- Data Analytics:Machine learning models interpret acoustic signatures and thermal patterns to classify failure modes. Facilities lacking in-house thermodynamic expertise depend on vendor-provided analytics packages.
- Sensors:Discrete temperature, acoustic, or conductivity probes without integrated intelligence. Entry-tier procurement for single-trap monitoring in non-critical steam lines.
Cloud-based platforms dominate value capture; IoT connectivity is climbing the fastest on deployment volume.
End User:
Application maturity varies sharply, with pharmaceutical and food processing sectors leading predictive maintenance adoption while power generation lags in legacy infrastructure lock-in.
- Pharmaceuticals:Cleanroom-compatible miniaturized sensors avoid contamination risks from bulky instrumentation. EU Green Deal emissions benchmarks compress replacement cycles for legacy mechanical traps in German manufacturing facilities.
- Manufacturing:Process-intensive sectors including chemicals, pulp and paper, and textiles generate baseline demand for energy loss reduction. India's Bureau of Energy Efficiency mandates under Perform Achieve Trade create compliance-driven procurement cycles.
- Food Processing:Hygienic design requirements and HACCP protocols dictate stainless steel enclosures with IP69K washdown ratings. Steam sterilization lines in canning and dairy operations drive sensor density.
- Power Generation:Centralized boiler operations with established maintenance regimes show slower adoption of distributed monitoring. Coal and combined-cycle plants prioritize critical high-pressure headers over comprehensive trap coverage.
Pharmaceuticals command premium pricing tiers; manufacturing delivers the broadest installed base expansion.
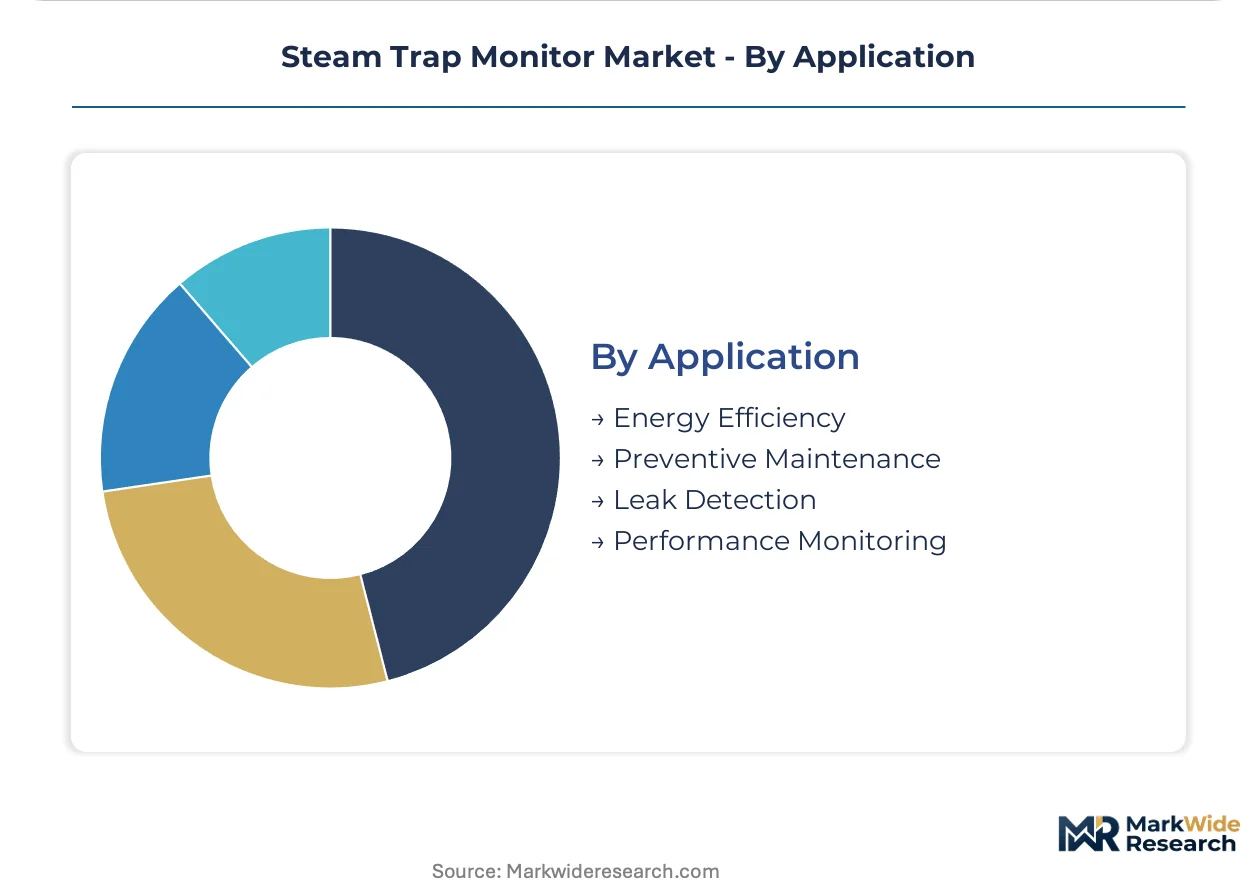
Application:
Customer type differentiation separates sustainability officers with C-suite reporting lines from maintenance departments focused on operational uptime metrics.
- Energy Efficiency:Quantified fuel expenditure and carbon emissions liabilities translate steam loss data into financial and regulatory reporting. Gulf Coast chemical processors treat monitoring data as auditable EPA compliance documentation.
- Preventive Maintenance:Scheduled replacement based on operational hours or condition indicators rather than catastrophic failure. Extends trap service life and reduces unplanned shutdowns in continuous process industries.
- Leak Detection:Rapid identification of stuck-open or blow-through conditions that vent live steam to atmosphere. Acoustic signature analysis pinpoints failures in noisy plant environments.
- Performance Monitoring:Continuous tracking of condensate removal efficiency and backpressure conditions. Optimization of steam distribution balance across multi-header systems.
Energy efficiency anchors procurement authority migration to sustainability functions; preventive maintenance shows the steepest expansion trajectory as subscription service models displace capital sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates with sustainability officers in chemical processing clusters, maintenance managers in pharmaceutical cleanrooms, and energy auditors under compliance mandates. Facility operators across industrialized economies retrofit legacy steam infrastructure with sensor-based predictive maintenance platforms.
United States
Chemical processors along the Texas-Louisiana Gulf Coast drive concentrated retrofit demand for auditable emissions documentation. EPA reporting requirements pressure facilities to quantify energy waste from failed steam traps as direct carbon liabilities. Houston-area petrochemical complexes treat monitoring data as compliance evidence rather than operational convenience.
Germany
Pharmaceutical manufacturers accelerate adoption of connected monitoring systems ahead of EU Green Deal emissions benchmarks. The Federal Environment Agency tightens efficiency standards mandating documented energy audits that catalog trap failures. Cleanroom operators in Baden-Württemberg specify miniaturized sensors to avoid contamination risks from bulky instrumentation.
India
Process-intensive manufacturing sectors generate compliance-driven procurement cycles under Bureau of Energy Efficiency mandates. The Perform Achieve Trade scheme requires periodic energy audits with explicit steam system loss cataloging. Maharashtra and Gujarat textile clusters retrofit mechanical trap populations with add-on sensor modules for phased economics.
China
Dual carbon goals pressure state-owned chemical enterprises to quantify steam losses with precision across distributed boiler operations. The Ministry of Ecology and Environment tightens emissions verification protocols for industrial steam systems. Yangtze River Delta manufacturing hubs deploy cloud-integrated multi-site dashboards spanning fragmented facility portfolios.
Japan
Power generation utilities specify edge computing nodes with wireless connectivity for remote substations with unreliable backhaul. METI efficiency standards drive condition monitoring adoption in centralized boiler operations with established maintenance regimes. Kansai region industrial operators prioritize critical high-pressure headers over comprehensive trap coverage.
Steam Trap Monitor Market Competitive Environment
Player mix skews toward established industrial automation suppliers with decades of steam system expertise alongside emerging IoT-native entrants seeking cloud-integrated positioning. Market structure consolidates around three strategic tiers: legacy specialists with thermal efficiency deep knowledge, diversified automation conglomerates extending condition monitoring portfolios, and connectivity-focused challengers betting on subscription service models. Dominant competitive moves include strategic partnerships between sensor hardware vendors and cloud platform providers, plus portfolio diversification into predictive analytics layers.
Within the legacy specialist tier, Forbes Marshall Private Limited and Spirax-Sarco Engineering plc exemplify archetypes anchored in process-intensive manufacturing expertise. Emerson Electric Co. occupies a position representing diversified automation conglomerates extending into cloud-integrated condition monitoring. These three companies illustrate the competitive tension between decades of thermodynamic specialization and the pressure to deliver centralized dashboard architectures without on-premise infrastructure investment.
| Leading Market Players |
|---|
| Forbes Marshall Private Limited |
| GESTRA AG |
| Spirax-Sarco Engineering plc |
| Yoshitake Inc. |
| IMI Critical Engineering |
| Armstrong International Inc. |
| Thermax Limited |
| Emerson Electric Co. |
| TLV Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for high-temperature sensor components concentrate supply leverage with semiconductor foundries in South Korea and Taiwan, compressing margin flexibility for entry-tier monitor assemblers while amplifying pricing power for integrated smart trap manufacturers with captive component stocks.
Pricing Analysis
Cost-plus contracts with quarterly indexation to copper and rare-earth oxide benchmarks dominate procurement between sensor module vendors and steam trap integrators. Three-tier pricing structure across premium, standard, and economy levels separates cloud-integrated predictive analytics bundles from basic temperature-differential hardware and stripped sensor-only configurations. Cost compression in the economy tier is intensifying because MEMS acoustic sensor volumes are scaling from pharmaceutical cleanroom deployments into general manufacturing. Maintenance departments in mature industrial regions exhibit the highest price sensitivity, while sustainability officers with EPA compliance mandates accept premium positioning.
Supply Chain Analysis
Just-in-time inventory strategies prevail among IoT-native entrants with fabless semiconductor sourcing, while established industrial automation suppliers maintain strategic stockpiles of IP65-rated enclosures and high-temperature cabling. Component manufacturing concentrates in China, Germany, and Japan. Raw material dependencies include copper for thermal sensors, neodymium for magnetic acoustic pickups, and fluoropolymers for high-temperature insulation. Single-source vulnerability runs through specialized MEMS foundries serving the sub-200°C precision segment. Distribution runs through authorized industrial automation distributors with certified technician networks rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steam trap monitoring sits in early-cycle expansion as EU Green Deal compliance deadlines force quantified emissions reporting across process industries, accelerating replacement of decades-old mechanical infrastructure.
For Market Incumbents: Compound defensive positioning by deepening backward integration into MEMS acoustic sensor production and accelerating ISO 9001 certification timelines for cloud-analytics platforms. The threat from IoT-native subscription challengers demands channel control through exclusive distributor partnerships with certified hot-tap installation networks. For New Entrants and Emerging Players: Differentiate on edge-computing form factors for intermittent-connectivity environments in remote power substations and fragmented manufacturing portfolios. White-space targets include textile clusters in Maharashtra under India's Perform Achieve Trade audit mandates and coal-plant critical-header monitoring in Japan's Kansai region. A per-trap monthly fee SaaS model bypasses capital-committee approval friction. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automation conglomerates seeking to divest non-core steam system assets with embedded thermodynamic expertise. Long-term viability hinges on regulatory stickiness as emissions verification protocols tighten across industrialized economies. Watch for inflection signals when sustainability procurement authority consolidates under single C-suite reporting lines in Gulf Coast chemical processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Sensors | Captive supply of acoustic detection modules insulates margin from rare-earth price volatility. |
| Cloud-Platform Partnership | Integration with industrial hyperscaler dashboards accelerates multi-site deployment velocity. |
| Certified Technician Network Expansion | Hot-tap installation capacity constraints rollout in India's textile clusters and peripheral markets. |
| Subscription Service Repositioning | OpEx treatment of monitoring costs displaces capital-sales cycles in EPA-regulated facilities. |
| Integrated Smart Trap Form Factor | Embedded sensing eliminates retrofit complexity for compressed capital-planning horizons. |
Study Parameters
Desk research of trade customs data, industrial automation distributor filings, and Bureau of Energy Efficiency audit protocols preceded structured interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary fieldwork across chemical processing clusters in Texas and Louisiana, pharmaceutical cleanrooms in Baden-Württemberg, and textile operations in Maharashtra validated secondary estimates. Bottom-up trap-by-trap deployment modeling and top-down energy audit extrapolation were triangulated against EPA emissions reporting databases.
Variance-decomposition analysis isolated volume, pricing, and mix effects across product type, technology architecture, and end-use vertical dimensions. Modeled segments included electronic, mechanical, thermal, and hybrid product configurations; cloud-based, IoT, data analytics, and sensor technology tiers; and pharmaceutical, manufacturing, food processing, and power generation end-use categories. CAGRs were derived from regression against historical energy audit penetration rates and regulatory compliance deadline clustering. Industry-specific inputs included EU Green Deal implementation timelines and Perform Achieve Trade scheme audit cycle frequencies.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of emissions verification protocols would require recalibration. Forecasts reflect assumptions regarding certification timeline compression and cloud-platform adoption curves. Practitioners should keep alternative scenarios live as MEMS sensor cost curves and hot-tap technician availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
Air Particle Monitor System Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Condition Monitoring System Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Vacuum Pressure Sensors Market
Sensors and Controls
Corrosion Monitoring Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
United States (US) Industrial Sensors Market