
 Remote Plasma Source Market | 2026-2036
Remote Plasma Source Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Plasma Source Market Outlook
ISO 14644 cleanroom certification is reorganizing supplier eligibility for remote plasma source vendors serving leading-edge semiconductor fabs. MKS Instruments leverages its pressure measurement heritage to anchor gas delivery integration around plasma ignition modules. Oxford Instruments plc sustains differentiation through superconducting magnet expertise that extends into plasma confinement subsystems for etch applications.
A remote plasma source generates reactive species—ions, radicals, and excited neutrals—externally from a process chamber, typically via radio-frequency or microwave excitation at 13.56 MHz or 2.45 GHz, then transports these species through a delivery manifold for downstream surface modification. Inductively coupled plasma configurations dominate current semiconductor manufacturing installations due to superior ion density control at low chamber pressures. Microwave plasma sources represent the fastest-expanding technology segment as atomic layer etch and deposition processes require precise radical flux without direct ion bombardment damage.
EPA regulations in the United States mandate fluorinated greenhouse gas abatement from etch and CVD operations, directly elevating remote plasma source deployment for exhaust treatment. REACH compliance across Europe restricts perfluorinated compound usage in semiconductor processes, compelling fabs to adopt plasma-based local scrubbing architectures. Semiconductor equipment buyers must weigh technology roadmaps against evolving regional emissions frameworks when qualifying second-source plasma suppliers.
Market Dynamics
Semiconductor manufacturers in Taiwan and South Korea are expanding cleanroom capacity for advanced node production, creating concentrated demand pull for remote plasma sources capable of atomic layer precision without direct ion bombardment damage.
Growth Catalysts
- EPA emissions mandates:Stricter fluorinated greenhouse gas abatement rules in the United States are pushing fabs toward remote plasma abatement systems for exhaust treatment.
- Atomic layer processing:Microwave plasma sources are gaining traction for atomic layer etch and deposition processes requiring precise radical flux control.
- East Asian foundry clusters:Contract foundry concentration in Taiwan and South Korea is driving equipment qualification cycles for remote plasma ignition modules.
Market Restraints
- Specialized gas supply concentration:High-purity fluorinated precursor supply chains concentrate among limited German and Japanese chemical suppliers, creating input vulnerability.
- Cleanroom certification barriers:ISO 14644 certification timelines extend 18-24 months, freezing out unqualified vendors from leading-edge fab procurement lists.
- Capital intensity thresholds:Remote plasma source qualification requires parallel process chamber investment, compressing accessible buyer pools to top-tier semiconductor manufacturers.
Strategic Opportunities
- India semiconductor fabrication:PLI scheme subsidies for domestic chip manufacturing are creating first-mover advantage windows for plasma source vendors establishing local service infrastructure.
- Superconducting magnet convergence:Plasma confinement subsystem integration with cryogenic magnet technology opens differentiation paths for equipment suppliers with magnet heritage.
- REACH compliance tailwinds:European perfluorinated compound restrictions are accelerating plasma-based local scrubbing architecture adoption beyond traditional exhaust treatment.
Industry Challenges
- Plasma physics specialization gaps:The intersection of RF engineering, gas dynamics, and surface chemistry requires scarce cross-functional talent that fabs and vendors compete to secure.
- Legacy chamber integration friction:Retrofitting remote plasma delivery manifolds onto existing inductively coupled plasma etch platforms demands custom mechanical interfaces and control system harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Plasma Source Market |
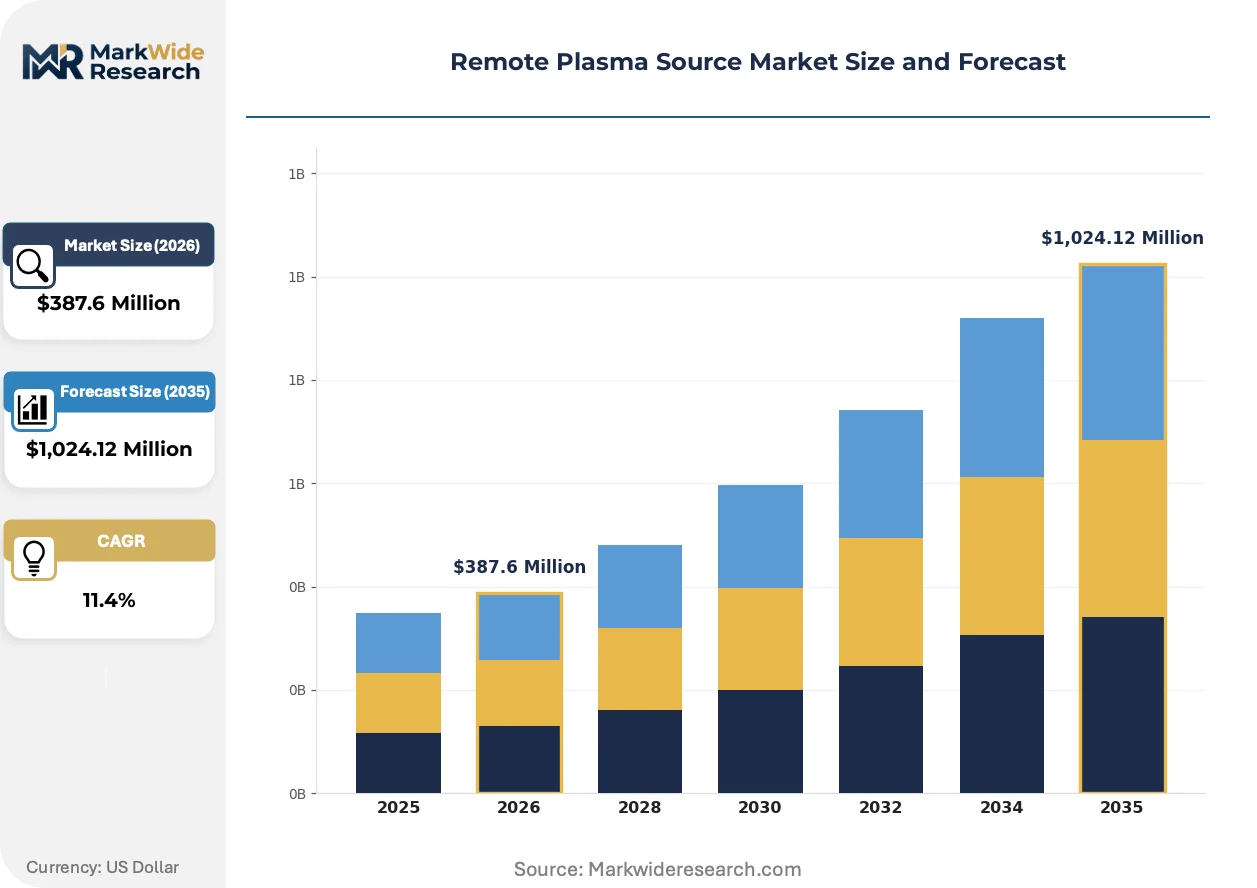
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitively Coupled Plasma, Inductively Coupled Plasma, Microwave Plasma, Dielectric Barrier Discharge Technology: Low-Pressure, Atmospheric-Pressure, Pulsed Discharge, Continuous Wave Application: Semiconductor Manufacturing, Surface Treatment, Thin Film Deposition, Material Etching End User: Electronics, Healthcare, Automotive, Aerospace |
| Companies Covered | PIE Scientific LLC, Oxford Instruments plc, MKS Instruments, Sentech Instruments GmbH, Plasma-Therm, Advanced Energy Industries, Muegge GmbH, Lam Research Corporation, Samco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Plasma Source Market Strategic Shifts
Microwave excitation architectures are fragmenting traditional RF-dominated plasma source portfolios as process engineers seek radical-selective delivery without substrate damage. Three concurrent developments are compressing technology refresh cycles.
Inductively coupled plasma configurations is fragmenting into specialized sub-variants optimized for specific pressure regimes and radical chemistries. Memory manufacturers in South Korea are adopting multi-frequency ICP sources for high-aspect-ratio contact etch, while logic foundries in Taiwan prioritize single-frequency designs for gate stack precision. This technical divergence is compressing vendor R&D spreads as equipment makers must maintain parallel development tracks rather than consolidating on universal platforms.
EPA fluorinated greenhouse gas regulations are mandating point-of-use abatement for etch and CVD exhaust streams, elevating remote plasma sources from process tools to environmental compliance infrastructure. Semiconductor equipment buyers in the United States now weight plasma source selection against emissions audit trajectories, not merely process performance. This regulatory embedding is lengthening vendor qualification timelines as environmental engineering teams gain veto power over procurement decisions.
Equipment procurement patterns are compressing as foundries consolidate supplier lists to reduce qualification overhead. Buyers in Taiwan and South Korea are bundling remote plasma sources with gas delivery and pressure measurement subsystems under single-vendor frameworks, displacing standalone component sourcing. This bundling behavior is most pronounced at 3nm and below nodes where chamber-matching tolerances tighten and vendor accountability spans complete subsystems.
Remote Plasma Source Market Segmentation
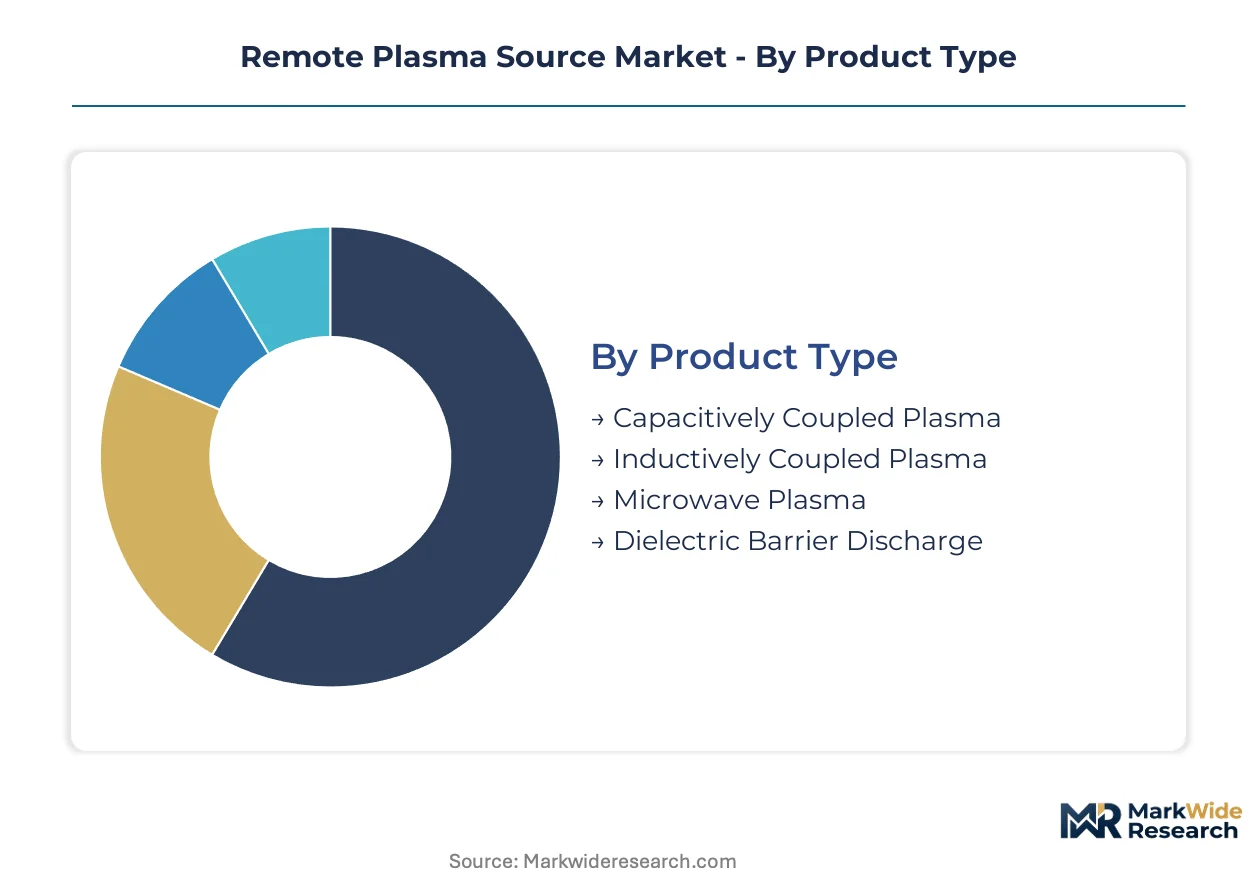
Remote plasma source procurement patterns diverge sharply across technology architectures and pressure regimes. Semiconductor fabs prioritize radical flux precision over cost minimization, while surface treatment buyers trade ion density for capital efficiency.
Product Type:
Capacitively coupled configurations face acute substitution pressure from microwave architectures in atomic layer processing applications.
- Inductively Coupled Plasma:Toroidal coil configurations generate high-density plasmas at 13.56 MHz with superior ion flux control at sub-10 mTorr pressures. Taiwan foundries deploy ICP sources for 3nm gate stack etch where chamber matching tolerances compress below 2%. EPA fluorinated gas abatement mandates in the United States elevate ICP deployment for exhaust treatment scrubbing.
- Microwave Plasma:2.45 GHz excitation produces radical-rich, ion-soft flux ideal for atomic layer etch and deposition without substrate damage. South Korea memory manufacturers adopt microwave architectures for high-aspect-ratio contact etch as device scaling demands damage-free processing.
- Capacitively Coupled Plasma:Parallel-plate electrode designs dominate legacy etch platforms with simpler power delivery requirements.
- Dielectric Barrier Discharge:Atmospheric-pressure operation suits surface activation and coating applications outside vacuum environments.
Inductively coupled plasma anchors the volume base while microwave plasma gains share at the steepest rate.
Technology:
Pressure regime selection concentrates cost differentiation between vacuum infrastructure and open-atmospheric systems.
- Low-Pressure:Sub-atmospheric operation below 100 Pa enables precise radical transport through delivery manifolds with minimal gas-phase recombination. Taiwan and South Korea foundries standardize on low-pressure architectures for sub-5nm node production where contamination control dictates vacuum isolation.
- Atmospheric-Pressure:Open-air plasma generation eliminates vacuum pumping infrastructure, compressing capital outlay for surface treatment buyers. Automotive coating lines in Germany adopt atmospheric-pressure systems for polymer activation prior to adhesive bonding.
- Pulsed Discharge:Modulated power delivery reduces thermal loading on sensitive substrates through duty cycle control.
- Continuous Wave:Steady-state excitation maximizes radical throughput for high-volume exhaust abatement applications.
Low-pressure technology captures the dominant revenue share while atmospheric-pressure platforms expand most quickly in non-semiconductor verticals.
Application:
Process specificity determines vendor qualification depth and replacement cycle length across end-use segments.
- Semiconductor Manufacturing:Etch, deposition, and cleaning steps require plasma sources qualified to ISO 14644 cleanroom standards with 18-24 month certification timelines. South Korea and Taiwan foundries bundle plasma sources with gas delivery subsystems under single-vendor accountability frameworks at advanced nodes.
- Material Etching:Precision removal applications in compound semiconductor and MEMS fabrication demand radical selectivity without physical sputtering damage.
- Surface Treatment:Activation and functionalization of polymers, metals, and ceramics prior to coating or bonding operations.
- Thin Film Deposition:Plasma-enhanced chemical vapor deposition for barrier and passivation layers across electronics and packaging.
Semiconductor manufacturing commands the premium pricing tier while material etching applications broaden the addressable buyer base.
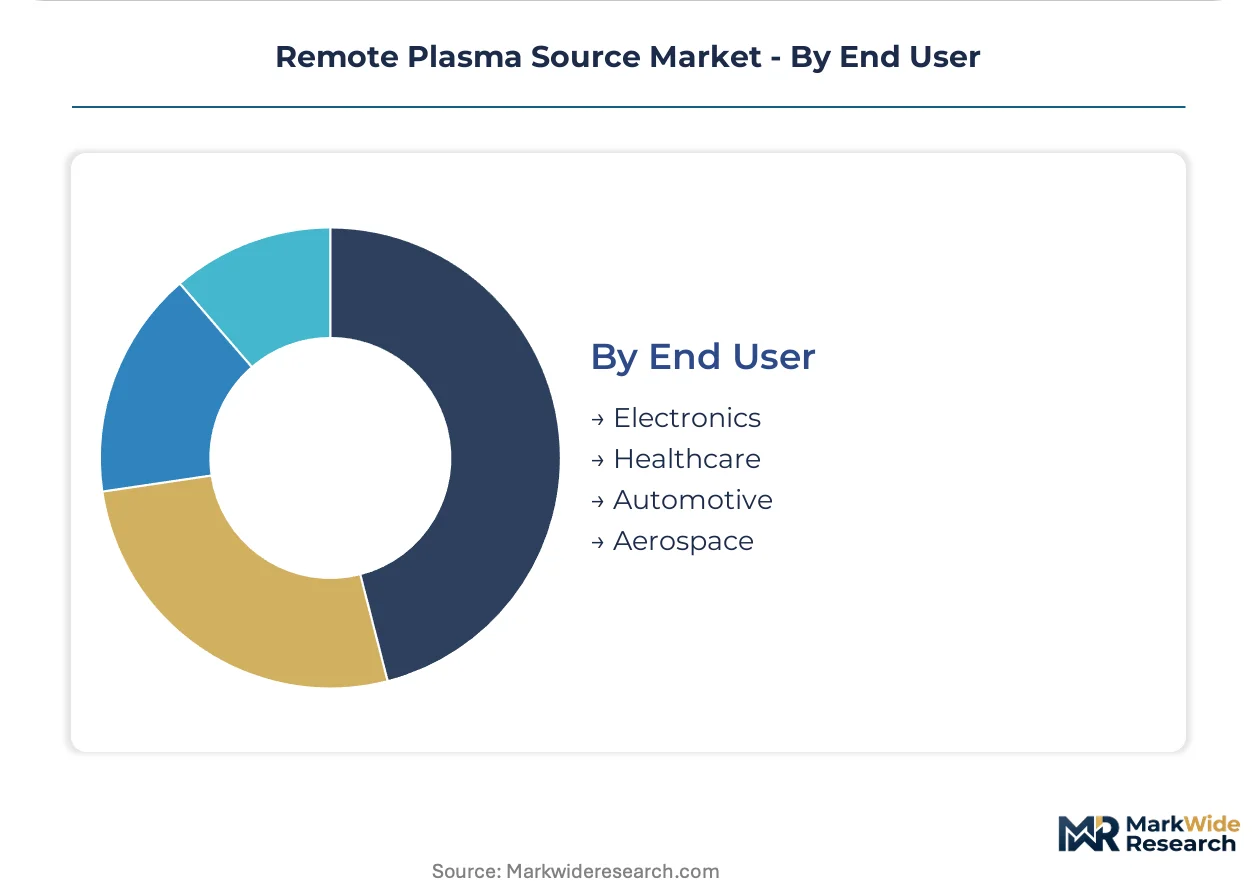
End User:
Customer concentration patterns split between capital-intensive fab operators and price-sensitive industrial processors.
- Electronics:Contract foundries and IDMs in Taiwan, South Korea, and the United States drive equipment procurement with technology roadmaps tied to node migration schedules. EPA emissions audits now embed plasma source selection within environmental compliance infrastructure rather than pure process engineering.
- Automotive:Electric vehicle battery manufacturing and lightweight material bonding activate demand for atmospheric-pressure surface treatment systems.
- Healthcare:Medical device sterilization and implant surface modification require biocompatible plasma processing with validated cleaning protocols.
- Aerospace:Component coating and composite bonding applications prioritize reliability certification over processing speed.
Electronics end users dominate current procurement volumes while automotive buyers emerge as the fastest-expanding customer category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract foundries in Taiwan and South Korea concentrate equipment procurement for advanced node production, while EPA mandates in the United States reshape abatement infrastructure requirements. Cleanroom expansion timelines and emissions compliance frameworks determine regional demand intensity.
Taiwan
TSMC and United Microelectronics Corporation drive cleanroom capacity expansion for 3nm and 2nm node ramps. The National Development Council's chip industry support programs accelerate equipment depreciation schedules. Hsinchu Science Park anchors the densest cluster of remote plasma source qualification activity for atomic layer etch applications.
South Korea
Samsung Electronics and SK Hynix deploy microwave plasma architectures for high-aspect-ratio contact etch in DRAM and NAND production. METI-aligned bilateral agreements with Japanese suppliers stabilize fluorinated precursor access. The Pyeongtaek semiconductor complex hosts the fastest-growing installation base for remote plasma abatement systems.
United States
Intel and GlobalFoundries retrofit legacy fabs with point-of-use plasma scrubbers to meet EPA fluorinated greenhouse gas abatement deadlines. The Inflation Reduction Act's domestic manufacturing incentives compress equipment procurement cycles. Arizona and Ohio greenfield sites concentrate new remote plasma source deployments for leading-edge logic production.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor domestic supply chains for high-purity process gases and chamber components. METI's semiconductor equipment localization subsidies reduce import dependency for plasma ignition modules. The Kyushu region maintains specialized foundry capacity for power semiconductor and sensor applications.
Germany
Bosch and Infineon expand 300mm capacity for automotive and industrial power semiconductors. REACH compliance restrictions on perfluorinated compounds accelerate plasma-based local scrubbing adoption. Dresden's Silicon Saxony cluster concentrates equipment qualification for automotive-grade process reliability.
Remote Plasma Source Market Competitive Environment
Player mix skews toward diversified semiconductor equipment conglomerates with adjacent gas delivery and pressure measurement portfolios. Market structure exhibits moderate consolidation with tiered specialization across process tool integration and standalone subsystem supply. Equipment makers with superconducting magnet heritage and RF power management expertise occupy differentiated strategic positions. Competitive moves concentrate on subsystem bundling under single-vendor accountability frameworks and geographic expansion into India under PLI scheme windows.
Among US-based diversified equipment suppliers, MKS Instruments and Advanced Energy Industries occupy positions anchored by gas delivery integration and RF power management expertise respectively. Oxford Instruments plc represents the superconducting magnet convergence archetype, extending cryogenic confinement capabilities into plasma subsystem architectures. Lam Research Corporation exemplifies the process tool integration model, bundling remote plasma sources within complete etch platform offerings for foundry qualification cycles.
| Leading Market Players |
|---|
| PIE Scientific LLC |
| Oxford Instruments plc |
| MKS Instruments |
| Sentech Instruments GmbH |
| Plasma-Therm |
| Advanced Energy Industries |
| Muegge GmbH |
| Lam Research Corporation |
| Samco Inc. |
| Others |
Value Chain & Pricing Dynamics
Cleanroom capacity utilization rates above 85% in Taiwan and South Korea compress pricing power toward high-volume contract foundries while elevating cost floors for qualified subsystem vendors serving ISO 14644-certified fabs. This scale concentration binds pricing models to long-term equipment procurement cycles and creates asymmetric leverage between consolidated buyers and specialized plasma source suppliers.
Pricing Analysis
Cost-plus contracts with fluorinated precursor indexation dominate equipment procurement between Taiwanese foundries and Japanese-German chemical suppliers. Price differentiation rests on ISO 14644 certification tier and after-sales service bundling rather than base hardware specifications. Cost compression in atmospheric-pressure systems is intensifying because automotive surface treatment buyers prioritize capital efficiency over radical flux precision. Contract foundries exhibit the lowest price sensitivity due to node migration timelines, while industrial coating operators in Germany demonstrate acute responsiveness to capital outlay variations.
Supply Chain Analysis
Inventory lead times for superconducting magnet components and RF power modules extend 16-20 weeks, tethering production schedules to cryogenic equipment and semiconductor-grade ceramic foundry capacity. Supply concentrates in Japan, Germany, and the United States for high-purity gas delivery manifolds, RF generators, and vacuum chamber subsystems. Single-source vulnerability pervades fluorinated precursor supply chains anchored in Japanese chemical conglomerates. Distribution runs through direct OEM integration for semiconductor equipment and regional distributor networks for atmospheric-pressure industrial systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote plasma source demand is accelerating through EPA fluorinated gas abatement mandates and atomic layer processing requirements at 3nm nodes. These dual inflections compress technology refresh cycles and extend vendor qualification timelines beyond historical norms.
For Market Incumbents: Shield installed base relationships by deepening backward integration into RF power module production and securing captive fluorinated precursor supply through long-term offtake agreements with Japanese chemical suppliers. Microwave architecture substitution threatens ICP-dominant portfolios; counter by bundling plasma sources with gas delivery and pressure measurement subsystems under single-vendor accountability frameworks at Taiwan foundries.
For New Entrants and Emerging Players: Aftermarket service coverage gaps in India's PLI-subsidized fab construction present immediate white-space opportunity. Target atmospheric-pressure surface treatment segments in automotive coating lines where ISO 14644 certification barriers do not apply. Establish local technical service infrastructure in Gujarat and Karnataka before incumbent qualification cycles conclude.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with superconducting magnet heritage extending into plasma confinement subsystems. Long-term viability favors equipment suppliers with parallel gas delivery integration capabilities rather than standalone plasma source specialists. Monitor EPA enforcement intensity on fluorinated greenhouse gas emissions as the critical inflection signal for abatement infrastructure demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into RF Power Modules | Captive supply of 13.56 MHz generators reduces qualification risk for Taiwan foundry contracts. |
| India Local Service Infrastructure Buildout | PLI scheme subsidies create first-mover advantage windows before incumbent presence solidifies. |
| Superconducting Magnet Convergence | Cryogenic confinement expertise from Oxford Instruments plc extends into differentiated plasma architectures. |
| Single-Vendor Subsystem Bundling | Accountability consolidation at 3nm nodes displaces standalone component procurement patterns. |
| EPA Compliance-Aligned Product Positioning | Point-of-use abatement certification embeds plasma sources within environmental audit infrastructure. |
Study Parameters
Operator-level perspectives from fab process engineers, equipment procurement managers, cleanroom certification auditors, and EPA environmental compliance officers anchored the qualitative base. Primary interview insights combined with secondary validation from SEC equipment supplier filings, EPA emissions enforcement databases, Taiwan National Development Council subsidy disclosures, and METI industrial policy documents. Bottom-up equipment installation counts triangulated against top-down semiconductor capital expenditure forecasts.
Sensitivity analysis tested forecast robustness across fluorinated precursor price volatility, EPA enforcement intensity, and node migration acceleration scenarios. Segmentation dimensions modeled include plasma architecture type, pressure regime, application specificity, and end-user concentration pattern. CAGRs derived from equipment procurement cycle analysis and foundry capacity expansion timelines across the projection horizon. Forecast inputs incorporated cleanroom certification queue lengths and REACH perfluorinated compound restriction implementation trajectories.
Forecasts assume regulatory continuity in EPA fluorinated gas abatement mandates and REACH perfluorinated compound restrictions; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Photolithography Equipment Market
Semiconductor Equipment
Tape on Reel Feeder Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
Sample Preparation Equipment Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Asia-Pacific Aligner Sheet Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Global Semiconductor Front-End Equipment Market
Semiconductor Equipment
Unscrambling Machine Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
UV-Based Nanoimprint Lithography (UV-NIL) System Market