
 Elemental Analyzer Market | 2026-2036
Elemental Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Elemental Analyzer Market Analysis
Environmental agencies are unwinding their historical dominance over elemental analyzer procurement as pharmaceutical quality control laboratories accelerate capital spending on ICP-OES and combustion systems. Bruker Corporation leverages its XRF technology leadership to anchor European metals analysis workflows. Thermo Fisher Scientific Inc. sustains broad laboratory channel control across North American pharmaceutical and environmental testing segments. Shimadzu Corporation dominates atomic spectroscopy installations in East Asian industrial quality control settings.
An elemental analyzer quantifies carbon, hydrogen, nitrogen, sulfur, and oxygen content in solid or liquid samples through high-temperature combustion or inert gas fusion, typically operating at detection limits reaching parts-per-billion for trace sulfur and nitrogen determinations. These instruments serve as gatekeeping tools for regulatory compliance in pharmaceutical raw material verification, environmental contaminant monitoring, and alloy composition certification. XRF Analyzer systems capture the largest installed base among product types due to their non-destructive testing advantage across metals analysis and soil screening applications, while ICP-OES segments generate premium pricing from pharmaceutical quality control laboratories requiring multi-element trace analysis under USP and EP methodologies. Optical Emission Spectroscopy technology leads industrial metals testing for ferrous and non-ferrous alloy certification, whereas Thermal Analysis segments occupy narrower but defensible positions in polymer and coal research laboratories.
FDA enforces ICH Q3D elemental impurity guidelines that mandate validated analytical methods for pharmaceutical starting materials and drug products, directly expanding ICP-OES and combustion analyzer qualification requirements across US manufacturing facilities. EMA applies parallel standards through its quality working party, while China's NMPA aligns domestic pharmaceutical testing protocols with international elemental impurity thresholds, creating synchronized compliance demand across three major regulatory zones. Stakeholders must monitor evolving pharmacopeial method harmonization between USP, EP, and ChP standards to anticipate capital replacement cycles and qualification service revenue pools.
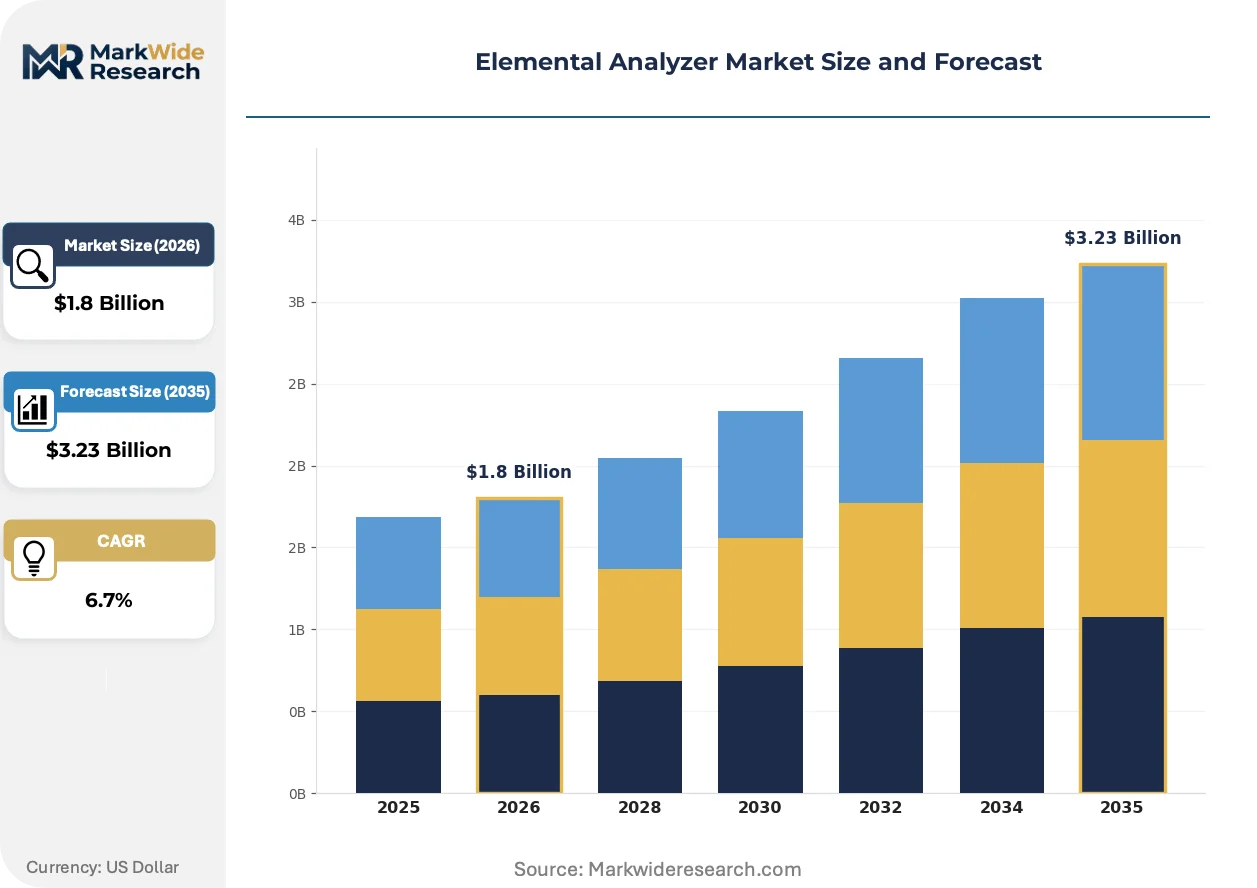
Market Dynamics
Pharmaceutical quality control laboratories are displacing environmental agencies as the dominant procurement segment, driven by tightening elemental impurity thresholds under harmonized pharmacopeial standards.
Growth Catalysts
- ICH Q3D Implementation:FDA and EMA enforcement of elemental impurity limits for drug substances and products mandates validated analytical methods, expanding qualification requirements for ICP-OES and combustion analyzer installations across manufacturing facilities.
- East Asian Industrial Quality Control:Metals certification and alloy composition verification in Japan, South Korea, and China sustain atomic spectroscopy demand from automotive and electronics supply chains.
- Non-Destructive Testing Preference:XRF technology captures expanding metals analysis workflows due to elimination of sample preparation steps and preservation of specimen integrity for downstream testing.
Market Restraints
- Helium Supply Concentration:Inert gas fusion and ICP-OES operations depend on helium imports concentrated in Qatar and the United States, exposing laboratories to price volatility and allocation disruptions.
- Instrument Capital Intensity:Premium ICP-MS and high-resolution ICP-OES systems require substantial upfront investment, constraining adoption among mid-tier contract testing laboratories.
- Method Transfer Complexity:USP and EP pharmacopeial method harmonization remains incomplete, forcing duplicate validation studies and delaying instrument deployment timelines.
Strategic Opportunities
- Portable XRF Expansion:Handheld metals analyzers penetrate field-based environmental screening and scrap metal sorting applications previously served by laboratory-bound systems.
- Biopharmaceutical Raw Material Testing:Cell culture media and excipient verification for monoclonal antibody production creates incremental demand for sulfur and nitrogen determination at trace levels.
- China NMPA Alignment:Domestic pharmaceutical testing protocol harmonization with international elemental impurity thresholds synchronizes compliance demand and accelerates capital replacement cycles.
Industry Challenges
- Analytical Chemist Shortage:Specialized expertise in method development for multi-element trace analysis and instrument troubleshooting constrains laboratory throughput expansion.
- Legacy System Integration:Enterprise LIMS connectivity and data integrity compliance with 21 CFR Part 11 requirements complicate qualification of new analyzer installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elemental Analyzer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CHNS Analyzer, ICP-OES, XRF Analyzer, Combustion Analyzer End User: Laboratories, Research Institutions, Environmental Agencies, Industrial Units Technology: Optical Emission Spectroscopy, X-Ray Fluorescence, Electrochemical Analysis, Thermal Analysis Application: Soil Testing, Food Safety, Metals Analysis, Pharmaceutical Quality Control |
| Companies Covered | Bruker Corporation, HORIBA Ltd., Thermo Fisher Scientific Inc., Malvern Panalytical Ltd., Analytik Jena AG, Agilent Technologies Inc., Shimadzu Corporation, LECO Corporation, PerkinElmer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elemental Analyzer Market Emerging Trajectories
Benchtop analyzer architectures are compressing footprint and operational cost barriers while regulatory harmonization pressures and service model unbundling reshape vendor-customer relationships.
Micro-XRF and handheld LIBS technology is miniaturizing elemental analysis capabilities for point-of-need deployment. Mining exploration teams and scrap metal processors adopt these systems for rapid screening without sample transport logistics. The technology is miniaturizing what previously required centralized laboratory infrastructure, fragmenting demand across distributed field applications.
EMA quality working party guidance on elemental impurity risk assessment forces pharmaceutical manufacturers to expand testing beyond finished products into starting materials and excipients. This industrial consequence extends analyzer utilization rates and accelerates replacement cycles for aging combustion systems. European contract manufacturing organizations respond by consolidating multi-site instrument fleets under single-vendor service agreements.
Service contract unbundling is separating preventive maintenance, consumables supply, and application support into discrete purchasing decisions. Large pharmaceutical quality control laboratories negotiate direct consumables sourcing while retaining OEM service for warranty-critical repairs. This behavior shift concentrates in North American and Western European markets with mature installed bases and sophisticated procurement functions.
Elemental Analyzer Market Segmentation
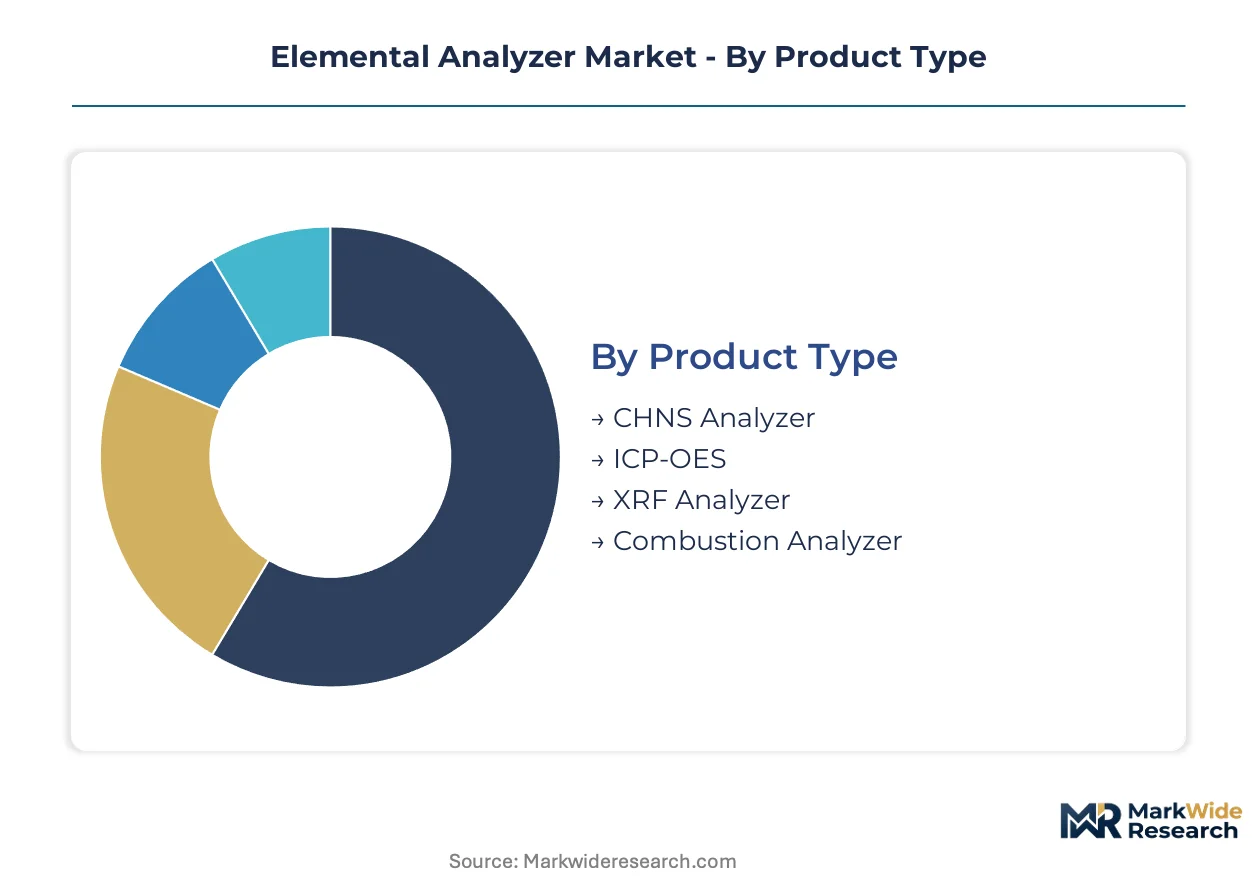
Segmentation reveals how elemental analyzer demand fragments across incompatible technical requirements and regulatory compliance thresholds. Procurement patterns diverge sharply between laboratories seeking trace-level pharmaceutical validation and industrial users prioritizing throughput economics.
Product Type:
XRF Analyzer and ICP-OES face the strongest substitution pressure from portable handheld systems and benchtop LIBS technology, while CHNS and combustion analyzers defend their positions through irreplaceable organic elemental determination capabilities.
- XRF Analyzer:Non-destructive X-ray fluorescence systems detect elemental composition from sodium to uranium without sample digestion. Mining exploration teams in Australia and scrap metal processors in Germany adopt handheld variants for field screening, displacing laboratory-bound installations.
- ICP-OES:Inductively coupled plasma optical emission spectrometers deliver multi-element trace analysis at parts-per-billion detection limits for pharmaceutical quality control. FDA and EMA enforcement of ICH Q3D guidelines sustains demand across US and European manufacturing facilities despite helium supply volatility.
- CHNS Analyzer:Combustion-based systems quantify carbon, hydrogen, nitrogen, and sulfur in organic materials through high-temperature oxidation. Academic polymer research and coal characterization laboratories anchor the installed base.
- Combustion Analyzer:Dedicated sulfur and nitrogen determination instruments serve petroleum refining and natural gas processing for regulatory compliance with product quality specifications.
XRF Analyzer anchors the volume base while ICP-OES gains share at the steepest rate.
End User:
Laboratories and industrial units sit at opposite ends of the cost-versus-capability spectrum, with procurement authority shifting toward quality control functions as regulatory enforcement tightens.
- Laboratories:Commercial testing facilities and corporate quality control labs execute validated analytical methods for regulatory submission. These operations concentrate instrument purchasing power through multi-year service contracts and consumables bundling.
- Industrial Units:Manufacturing facilities embed analyzers directly into production lines for real-time alloy verification and raw material acceptance. Metals producers in Japan and South Korea sustain atomic spectroscopy demand through automotive supply chain certification requirements.
- Research Institutions:University and government research centers pursue novel method development and materials characterization, prioritizing analytical flexibility over throughput metrics.
- Environmental Agencies:Historical procurement leaders now face budget constraints and competition from privatized testing services, though soil contamination screening and emissions monitoring sustain baseline demand.
Industrial Units dominate current procurement volume while Laboratories capture margin expansion through qualification services and compliance-driven replacement cycles.
Technology:
Maturity gradients separate established optical methods from emerging electrochemical approaches, with deployment economics determining competitive boundaries.
- X-Ray Fluorescence:Energy-dispersive and wavelength-dispersive configurations serve non-destructive metals analysis across foundries, scrap yards, and archaeological conservation. Miniaturization trends compress unit economics for point-of-need deployment.
- Optical Emission Spectroscopy:Spark OES dominates ferrous and non-ferrous alloy certification in metals production, delivering rapid multi-element quantification for melt chemistry control.
- Thermal Analysis:Thermogravimetric and differential scanning calorimetry methods occupy specialized polymer and pharmaceutical stability testing niches with limited substitute threat.
- Electrochemical Analysis:Potentiometric and voltammetric techniques serve ion-selective measurements in water quality and corrosion monitoring, competing with ICP-MS at lower capital intensity.
Optical Emission Spectroscopy retains the largest installed base while X-Ray Fluorescence climbs the fastest through portable system penetration.
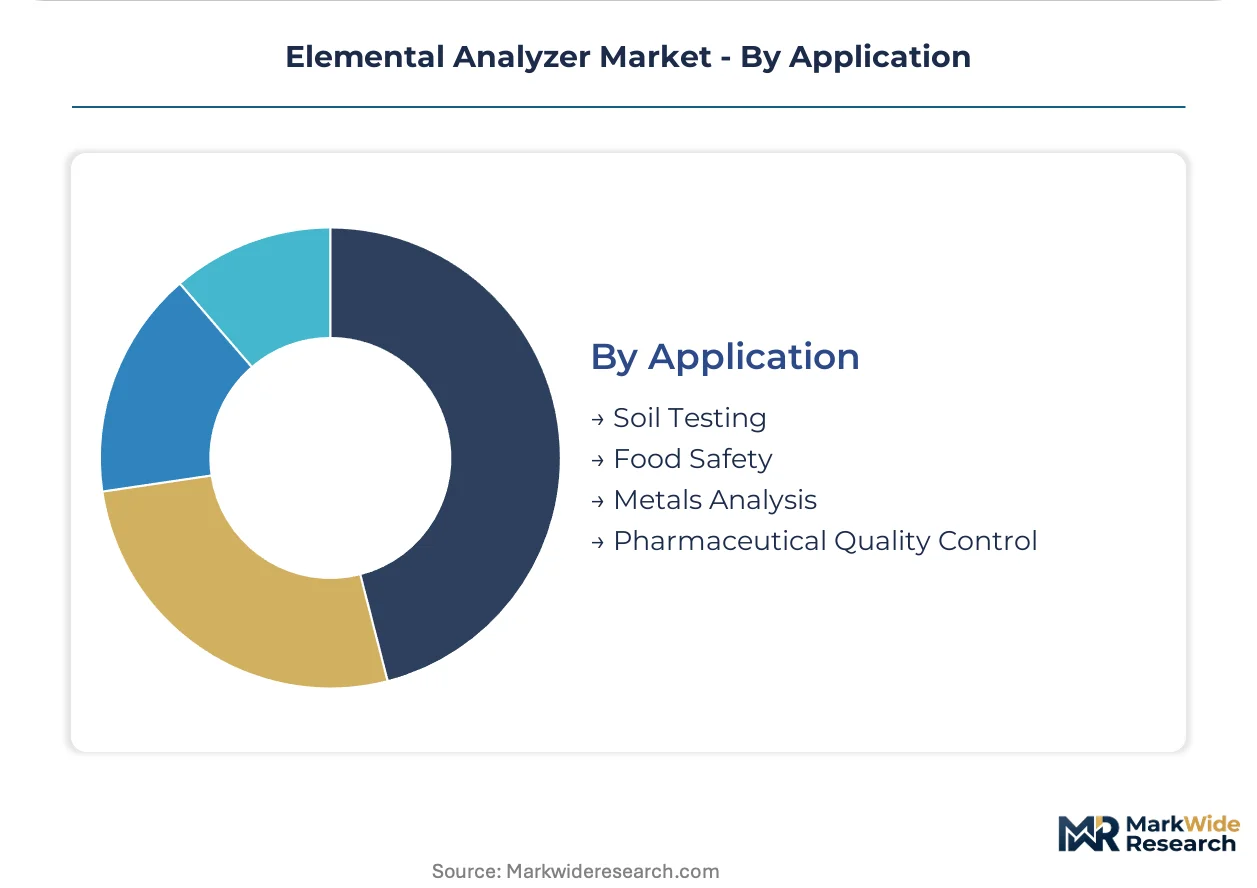
Application:
Regulatory stringency varies dramatically across end-uses, with pharmaceutical compliance costs far exceeding environmental monitoring thresholds.
- Pharmaceutical Quality Control:Elemental impurity testing under USP, EP, and ChP pharmacopeial standards mandates validated ICP-OES and combustion methods for starting materials and drug products. EMA quality working party guidance extends testing scope into excipients and cell culture media.
- Metals Analysis:Alloy composition verification and scrap sorting sustain XRF and OES demand across automotive, aerospace, and electronics supply chains. Certification requirements from original equipment manufacturers enforce instrument standardization.
- Food Safety:Heavy metal screening in agricultural products and processed foods employs atomic absorption and ICP-MS methods, with China's national food safety standards driving procurement in domestic testing networks.
- Soil Testing:Environmental contamination assessment and agricultural nutrient analysis utilize portable XRF for rapid screening and laboratory combustion for organic carbon determination.
Metals Analysis commands the broadest geographic deployment while Pharmaceutical Quality Control generates the steepest expansion trajectory through regulatory harmonization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German elemental analyzer manufacturers export combustion and XRF systems to pharmaceutical quality control laboratories across the United States and East Asia, anchoring a trade corridor that supplies regulatory-driven demand for ICH Q3D compliance instrumentation.
United States
FDA enforcement of elemental impurity limits under ICH Q3D guidelines drives ICP-OES and combustion analyzer procurement across pharmaceutical manufacturing facilities. The agency's quality working party inspections extend testing requirements into starting materials and excipients. Boston and Raleigh-Durham pharmaceutical clusters sustain concentrated instrument demand from contract manufacturing organizations.
Germany
LECO and Bruker anchor European manufacturing and R&D clusters for combustion and XRF systems serving metals analysis and pharmaceutical applications. EMA quality working party guidance on elemental impurity risk assessment accelerates replacement cycles for aging laboratory infrastructure. The Ruhr industrial basin and Bavarian precision manufacturing zones concentrate atomic spectroscopy demand from automotive supply chain certification.
China
NMPA alignment of domestic pharmaceutical testing protocols with international elemental impurity thresholds synchronizes compliance demand across domestic and export-oriented manufacturers. The regulator's quality standards for monoclonal antibody production expand sulfur and nitrogen determination requirements. Shanghai and Suzhou biopharmaceutical clusters drive premium ICP-OES installations for cell culture media verification.
Japan
METI industrial standards enforcement sustains atomic spectroscopy demand from automotive and electronics supply chains requiring alloy composition certification. PMDA pharmaceutical quality guidelines mirror ICH Q3D thresholds for elemental impurity testing in drug substances. The Nagoya automotive manufacturing corridor and Osaka pharmaceutical production zones concentrate XRF and OES instrument deployment.
India
CDSCO implementation of ICH Q3D-aligned standards for active pharmaceutical ingredients expands validated analytical method requirements across export-oriented manufacturing facilities. The regulator's quality guidelines for generic drug production drive combustion analyzer adoption for elemental impurity screening. Hyderabad and Ahmedabad pharmaceutical clusters concentrate ICP-OES procurement from contract research and manufacturing organizations.
Elemental Analyzer Market Vendor Landscape
Player mix skews toward diversified analytical instrumentation conglomerates with combustion system specialists occupying defensible niches. Market structure concentrates around vendors with established pharmaceutical quality control channel relationships and qualification service capabilities. Strategic archetypes include full-spectrum laboratory platform providers, dedicated elemental analysis specialists, and precision metals testing equipment fabricators. Competitive moves center on service contract unbundling and portable system miniaturization for field-based applications.
Among diversified analytical instrumentation providers, Thermo Fisher Scientific Inc. and Agilent Technologies Inc. exemplify platform-scale archetypes with broad laboratory channel control, while Bruker Corporation occupies a position representing XRF technology leadership. LECO Corporation and Shimadzu Corporation sit within the combustion and atomic spectroscopy specialist tier, anchoring regional manufacturing clusters in North America and East Asia respectively.
| Leading Market Players |
|---|
| Bruker Corporation |
| HORIBA Ltd. |
| Thermo Fisher Scientific Inc. |
| Malvern Panalytical Ltd. |
| Analytik Jena AG |
| Agilent Technologies Inc. |
| Shimadzu Corporation |
| LECO Corporation |
| PerkinElmer Inc. |
| Others |
Supply Flow & Price Mechanics
ICH Q3D compliance certification gates both supplier qualification and price differentiation simultaneously, forcing pharmaceutical manufacturers to pay premiums for validated ICP-OES systems while mid-tier laboratories face exclusion from premium service tiers due to incomplete method transfer capabilities.
Pricing Analysis
Next-generation benchtop LIBS and micro-XRF systems command 40-60% premiums over prior-generation laboratory-bound installations, while legacy combustion analyzers face accelerating price erosion. Three-tier pricing structure across premium, standard, and economy levels separates qualification-bundled pharmaceutical systems from industrial metals testing units and portable field screening devices. Pricing pressure stems from helium supply volatility and service contract unbundling, which compresses recurring revenue pools. Contract manufacturing organizations exhibit highest price sensitivity due to capital intensity constraints, while Big Pharma quality control functions prioritize compliance assurance over unit economics.
Supply Chain Analysis
Germany and the United States anchor precision manufacturing for combustion and XRF optical subassemblies, while Japan and South Korea supply high-purity detector crystals and plasma torch components. Production draws from concentrated helium reserves in Qatar and the US, high-grade ceramic crucibles from German specialty ceramics producers, and precision optics from Japanese glass manufacturers. Single-source vulnerability in helium allocation exposes ICP-OES operators to forced downtime and spot market price spikes. Distribution runs through authorized distributor networks for industrial segments and direct OEM relationships for pharmaceutical qualification service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Elemental analyzer demand is recovering from a cyclical trough as ICH Q3D enforcement waves trigger replacement cycles across pharmaceutical manufacturing infrastructure.
For Market Incumbents: Fortify qualification service capabilities to defend against portable XRF substitution in metals analysis workflows. Deepen backward integration into helium recycling and alternative carrier gas technologies to mitigate supply concentration risk. Secure multi-site service agreements with European contract manufacturing organizations consolidating instrument fleets under single-vendor frameworks. For New Entrants and Emerging Players: Lead with handheld LIBS systems targeting scrap metal sorting and mining exploration applications where laboratory infrastructure gaps persist. Penetrate Chinese domestic pharmaceutical testing networks where NMPA alignment creates demand for mid-tier ICP-OES installations. Deploy application-specific method development partnerships to bypass entrenched OEM service relationships. For Investors and Strategic Acquirers: ICH Q3D pharmacopeial harmonization reshapes the acquisition landscape toward combustion system specialists with validated pharmaceutical method libraries. Long-term viability centers on recurring consumables revenue density rather than instrument placement volume. Monitor EMA quality working party guidance expansion into biopharmaceutical raw materials as the signal for accelerated replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Alternative Development | Plasma source innovation reduces dependency on Qatar and US supply concentration. |
| Portable XRF Miniaturization | Handheld systems capture field screening applications from laboratory-bound competitors. |
| Pharmaceutical Method Libraries | Pre-validated USP/EP/ChP protocols accelerate instrument qualification timelines. |
| Service Contract Unbundling | Discrete consumables sourcing appeals to sophisticated North American procurement functions. |
| Biopharmaceutical Raw Material Testing | Cell culture media verification expands sulfur and nitrogen determination addressable market. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical quality control directors, environmental laboratory managers, metals testing facility supervisors, and OEM service contract administrators. Secondary validation incorporated FDA warning letter databases, EMA quality working party guidance documents, USP and EP pharmacopeial method updates, and customs trade data for analyzer instrument categories. Bottom-up installation base modeling triangulated against top-down market size estimates from published financial disclosures of listed analytical instrumentation providers.
Across the analysis window, the forecast framework segmented volume and value outputs by product type, end user archetype, technology platform, and application vertical, with additional granularity for regulatory compliance tier. CAGRs were derived from instrument replacement cycle analysis, regulatory enforcement timeline phasing, and helium supply scenario modeling. Key inputs included pharmaceutical manufacturing facility expansion pipelines, automotive supply chain certification requirements, and mining exploration expenditure forecasts.
Forecasts assume regulatory continuity in FDA, EMA, and NMPA enforcement regimes; material policy shifts would require re-modeling of replacement cycle timing and qualification service revenue pools. Recalibration cycles align with material shifts in pharmacopeial method harmonization progress and helium market structural changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Precision Balances Market
Analytical Instruments
Logic Analyzer Market
Analytical Instruments
Micro Balances Market
Analytical Instruments
North America Liquid Chromatography Devices Market
Analytical Instruments
Microchip Electrophoresis Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Global IR Spectroscopy Market
Analytical Instruments
Electron Microscope Sample Preparation Market
Analytical Instruments
Mass Spectrometer Market
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
Trace Oxygen Analyzer Market
Analytical Instruments
NIR and Raman Spectroscopy Market
Analytical Instruments
Spectroscopy Software Market
Analytical Instruments
Laser-Based Gas Analyzers Market