
 Sputtering Target Market | 2026-2036
Sputtering Target Market Size, Share, and Industry Trends Forecast 2026-2036
Sputtering Target Market Outlook
REACH chemical restrictions is recalibrating the cost-of-entry calculus for European sputtering target suppliers, forcing investments in conflict-mineral traceability and ultra-high-purity refining. JX Nippon Mining & Metals Corporation anchors its position through captive refining of copper and titanium ores. Plansee SE differentiates via tungsten and molybdenum refractory metal targets for extreme-thickness applications. Materion Corporation leverages advanced alloy development capabilities to serve aerospace and defense coating requirements.
A sputtering target is a high-purity material disc or plate, typically 99.99% to 99.9999% pure, that serves as the cathode source in physical vapor deposition systems where argon plasma ejects atoms onto a substrate to form thin films. Metal targets dominate current volume consumption across semiconductor interconnect and barrier layer applications, while compound targets command premium pricing in optoelectronics and transparent conductive oxide deposition. End user demand from semiconductor manufacturers absorbs the largest share of high-purity metal and alloy targets, whereas solar cell producers increasingly specify ceramic targets for cadmium telluride and copper indium gallium selenide absorber layers.
EPA hazardous waste rules, China's MEE environmental compliance protocols, and Japan's METI resource security policies collectively shape raw material access, recycling mandates, and regional supply chain configuration. The EU's F-Gas Regulation indirectly constrains process gas availability for certain deposition chemistries, pushing equipment makers toward alternative plasma configurations. Stakeholders must monitor how Japan's METI and China's SAMR coordinate rare metal stockpile policies, as these decisions will determine titanium and zirconium feedstock allocation priority across target producers.
Market Dynamics
Semiconductor interconnect scaling below 3nm nodes is compressing impurity tolerances for copper and ruthenium targets, forcing suppliers to recalibrate refining infrastructure around atomic-level contamination control rather than conventional bulk purity metrics.
Growth Catalysts
- AI accelerator fab buildouts:Taiwan Semiconductor Manufacturing Company and Samsung Electronics are expanding Hsinchu and Pyeongtaek capacity, pulling ultra-high-purity tantalum and cobalt targets for through-silicon via applications.
- China's GB standards escalation:MIIT-mandated purity thresholds for electronic-grade materials now exceed 5N specifications for domestic semiconductor procurement, creating certified-supplier premiums.
- Indium tin oxide substitution:Silver nanowire and metal mesh alternatives are failing cost-performance tests in large-format displays, preserving sputtered ITO demand for automotive and foldable device panels.
Market Restraints
- Rare metal feedstock concentration:Zirconium sponge supply from Russian and Ukrainian refiners faces ECHA REACH conflict-mineral traceability barriers, elevating working capital requirements for European target fabricators.
- Plasma etch chemistry lock-in:Fluorinated process gases under EU F-Gas Regulation phase-down schedules constrain deposition chemistry flexibility for tungsten silicide targets in legacy memory nodes.
- Refractory metal processing limits:Molybdenum and tungsten target machining requires electron-beam melting capacity concentrated in Austria and Japan, creating single-source vulnerability for extreme-thickness applications.
Strategic Opportunities
- India's semiconductor PLI scheme:Gujarat and Karnataka fab incentives are attracting target qualification programs from suppliers seeking geographic diversification beyond East Asian clusters.
- Perovskite solar commercialization:Tandem cell architectures specify doped tin oxide and nickel oxide ceramic targets for hole transport layers, opening volume demand outside semiconductor cyclicality.
- Japan METI rare metal stockpile coordination:Bilateral titanium sponge allocation agreements with Australian miners are creating preferential feedstock access for domestic target producers.
Industry Challenges
- Ultra-high-purity metallurgist scarcity:Zone refining and electron-beam melting expertise concentrates at aging technical institutes in Germany and Japan, constraining talent pipelines for new production facilities.
- Multi-generation equipment interoperability:Target bonding and backing plate designs must accommodate both legacy 200mm and advanced 300mm platform geometries without process requalification penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sputtering Target Market |
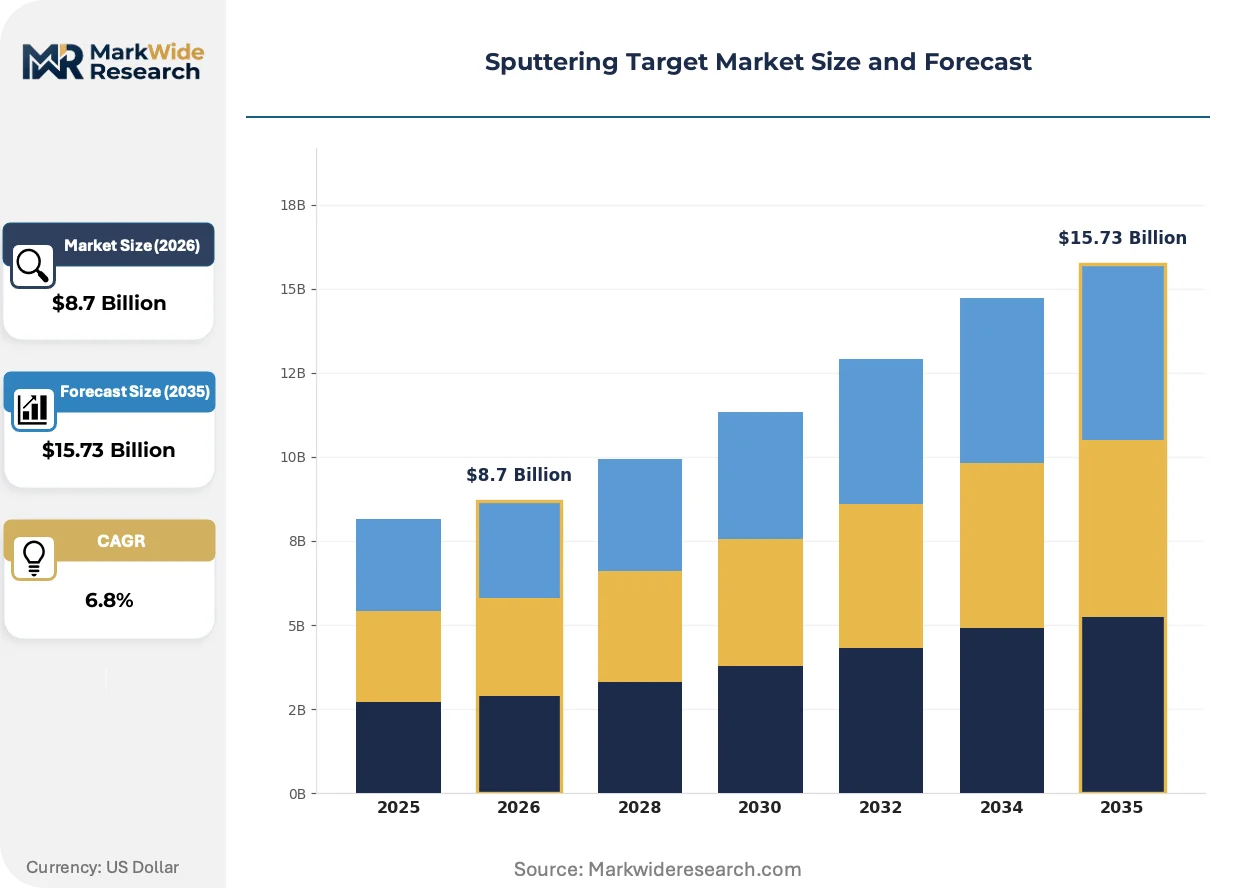
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Targets, Alloy Targets, Compound Targets, Ceramic Targets End User: Semiconductor Manufacturers, Optoelectronics, Solar Cells, Data Storage Material: Titanium, Copper, Aluminum, Zirconium Application: Coating, Thin Film Deposition, Surface Modification, Decorative Finishes |
| Companies Covered | Praxair Technology, Inc., Stanford Advanced Materials, JX Nippon Mining & Metals Corporation, GRIKIN Advanced Material Co., Ltd., ULVAC, Inc., Materion Corporation, Plansee SE, Kurt J. Lesker Company, Mitsui Mining & Smelting Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sputtering Target Market Strategic Shifts
Atomic layer deposition precursors and directed energy deposition are fragmenting traditional sputtering applications, yet advanced node interconnect requirements are simultaneously deepening target purity specifications beyond alternative deposition methods.
Rotatable cylindrical magnetron targets are rewriting material utilization economics in architectural glass and display panel production. Saint-Gobain and AGC are retrofitting planar cathode systems in Ohio and South Carolina facilities to capture 30% higher material yield rates. The geometry is compressing per-square-meter coating costs for low-emissivity and solar control glass, displacing planar target configurations in volume applications.
EPA hazardous waste generator status revisions are tightening spent target and backing plate classification thresholds, forcing semiconductor fabs in Arizona and Texas to consolidate recycling relationships with RCRA-permitted reclaimers. The rule shift is elevating closed-loop tantalum and precious metal recovery economics, particularly for ion implantation source material streams.
Consignment inventory programs are displacing spot purchasing for high-value precious metal targets among memory manufacturers. Micron and SK Hynix are requiring suppliers to hold refined platinum and gold sponge on their balance sheets until target consumption triggers payment, transferring metal price risk upstream. The model is most pronounced in Boise and Icheon operations where working capital optimization outweighs unit price negotiation.
Sputtering Target Market Segmentation
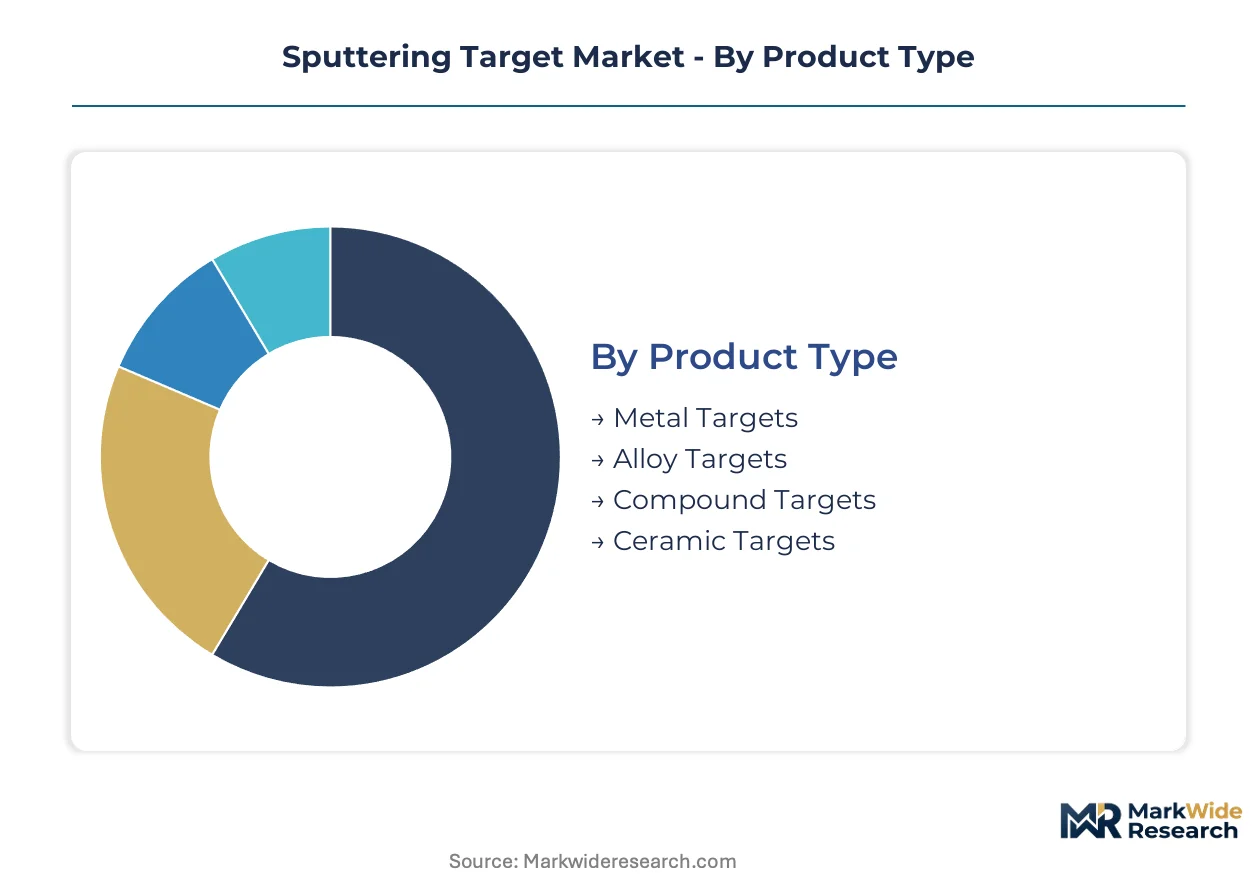
Sputtering target segmentation reveals how material purity thresholds and deposition chemistry requirements fragment supplier capabilities across end-use verticals. Each dimension carries distinct certification burdens and metallurgical expertise demands that reshape competitive positioning.
Product Type:
Metal targets function as standalone cathode sources in legacy planar magnetron systems, while compound and ceramic variants embed into specialized plasma configurations for reactive sputtering applications.
- Metal Targets:High-purity elemental discs of copper, titanium, and aluminum serve as cathode sources for interconnect and barrier layer deposition in semiconductor fabs. Taiwan Semiconductor Manufacturing Company and Samsung Electronics pull ultra-high-purity tantalum and cobalt variants for through-silicon via applications at Hsinchu and Pyeongtaek facilities.
- Alloy Targets:Multi-component metallurgical systems combine controlled ratios of refractory and conductive elements to achieve specific film stoichiometry. Aerospace coating operations in the United States specify nickel-chromium and cobalt-chrome compositions for turbine blade thermal barrier systems.
- Compound Targets:Pre-reacted ceramic-metal composites enable reactive sputtering without separate gas-phase chemistry control.
- Ceramic Targets:Oxide and nitride compositions serve optoelectronics and transparent conductive oxide applications.
Metal targets lead volumes today; ceramic targets are gaining share fastest.
End User:
Customer concentration varies sharply by purity tier, with semiconductor fabs consolidating procurement around qualified suppliers while solar cell producers prioritize cost-per-watt metrics over certification depth.
- Semiconductor Manufacturers:Logic and memory fabs specify 5N to 6N purity grades with atomic-level contamination controls for sub-3nm interconnect scaling. China's MIIT-mandated GB standards now exceed 5N specifications for domestic procurement, creating certified-supplier premiums for qualified vendors.
- Optoelectronics:Display panel and LED manufacturers drive indium tin oxide and aluminum zinc oxide consumption for transparent electrode layers. Automotive and foldable device panels preserve sputtered ITO demand as silver nanowire alternatives fail cost-performance thresholds.
- Solar Cells:Cadmium telluride and copper indium gallium selenide absorber layer deposition specifies ceramic targets outside semiconductor cyclicality.
- Data Storage:Magnetic recording media requires cobalt-chromium-platinum alloy targets with precise grain structure control.
Semiconductor manufacturers anchor revenue concentration; perovskite tandem solar applications show steepest expansion trajectory.
Material:
Feedstock access constraints and refining infrastructure availability segment supplier capabilities by elemental scarcity and purification complexity.
- Titanium:Sponge supply from Australian miners feeds electron-beam melting capacity in Japan and Austria for aerospace and medical implant targets. Japan METI bilateral allocation agreements create preferential feedstock access for domestic producers.
- Copper:JX Nippon Mining & Metals Corporation anchors position through captive refining of copper ores for semiconductor interconnect applications.
- Aluminum:Standard-grade sputtering targets serve decorative and architectural coating segments with lower purity thresholds.
- Zirconium:Sponge supply from Russian and Ukrainian refiners faces ECHA REACH conflict-mineral traceability barriers.
Copper dominates unit volumes; zirconium commands premium pricing due to supply concentration.
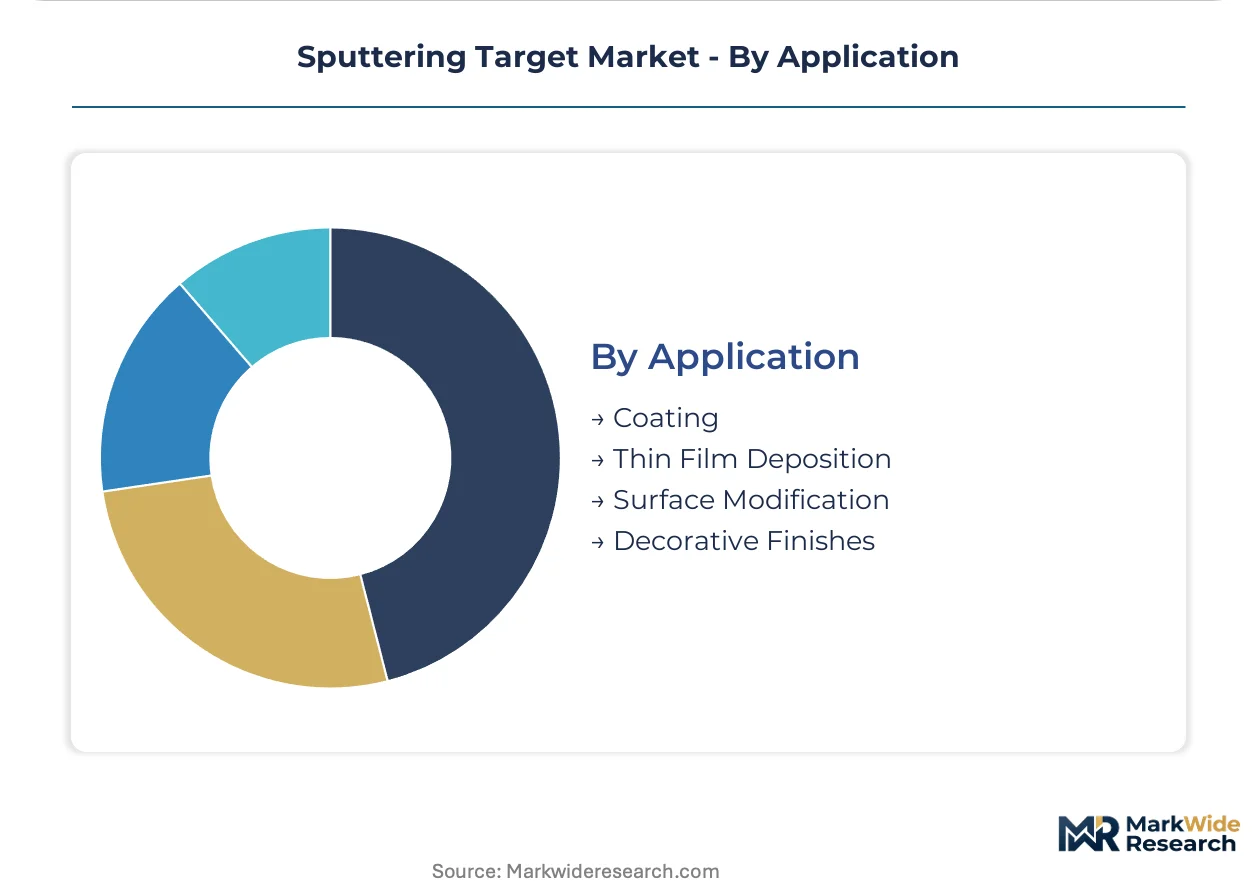
Application:
Process integration depth separates batch-scale research applications from continuous production systems requiring target bonding and backing plate standardization.
- Coating:Architectural glass and automotive trim operations utilize rotatable cylindrical magnetron configurations for 30% higher material yield rates than planar cathode systems.
- Thin Film Deposition:Physical vapor deposition for semiconductor interconnects, barrier layers, and seed layers requires ultra-high-purity metal and alloy targets with documented impurity spectra.
- Surface Modification:Tribological and corrosion-resistant coatings for industrial components employ mid-purity targets with less stringent certification requirements.
- Decorative Finishes:Consumer electronics and jewelry applications prioritize aesthetic consistency over functional film properties.
Thin film deposition commands the largest value share; coating applications are expanding most quickly through cylindrical target adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-purity metallurgists concentrate in aging technical institutes across Germany and Japan, constraining talent pipelines for new production facilities worldwide. Semiconductor clusters in Taiwan and South Korea pull disproportionate target volumes for AI accelerator fabrication. Regulatory divergence between EPA hazardous waste rules, China's MEE protocols, and ECHA REACH restrictions fragments supplier compliance architectures.
United States
Memory manufacturers in Boise and Austin drive consignment inventory programs for precious metal targets, transferring working capital risk to suppliers. EPA hazardous waste generator status revisions tighten spent target classification thresholds, forcing Arizona and Texas fabs to consolidate recycling with RCRA-permitted reclaimers. Closed-loop tantalum recovery economics improve as semiconductor operations expand in Phoenix and Dallas suburbs.
China
MIIT-mandated GB standards for electronic-grade materials now exceed 5N purity thresholds for domestic semiconductor procurement, creating certified-supplier premiums. MEE environmental compliance protocols shape raw material access and recycling mandates for target fabricators. Hsinchu-adjacent demand patterns influence Yangtze River Delta supplier qualification timelines as domestic logic capacity scales.
Japan
METI bilateral titanium sponge allocation agreements with Australian miners create preferential feedstock access for domestic target producers. Electron-beam melting capacity concentrates in technical corridors linking Nagoya and Osaka, anchoring refractory metal target fabrication. JIS standards and resource security policies coordinate rare metal stockpile decisions with industrial procurement cycles.
South Korea
Samsung Electronics expands Pyeongtaek fab capacity for AI chip production, pulling ultra-high-purity tantalum and cobalt targets for through-silicon via applications. MFDS pharmaceutical-grade material protocols indirectly elevate purity expectations for adjacent electronics material suppliers. Icheon memory operations require suppliers to hold refined platinum sponge on consignment until consumption triggers payment.
Germany
ECHA REACH conflict-mineral traceability barriers elevate working capital requirements for European target fabricators sourcing zirconium sponge. Zone refining expertise concentrates at technical institutes in Saxony and Bavaria, constraining talent replication for new facilities. Plansee SE anchors tungsten and molybdenum refractory metal production for extreme-thickness applications from Austrian-adjacent Central European refining corridors.
Sputtering Target Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across material purity tiers and end-use verticals. The supplier base stratifies between captive refiners controlling ore-to-target value chains and independent fabricators purchasing high-purity sponge. Three archetypes dominate: mining-backed integrated producers, refractory metal specialists with electron-beam melting assets, and advanced alloy developers serving aerospace certification requirements. Capacity expansion and strategic partnerships constitute the primary competitive vectors as fabs demand geographic supplier diversification.
Among Japanese integrated producers, JX Nippon Mining & Metals Corporation and Mitsui Mining & Smelting Co., Ltd. exemplify mining-backed vertical control over copper and titanium feedstocks. Austrian-based Plansee SE occupies a distinctive position in refractory metal targets for extreme-thickness applications. These three anchors represent divergent strategic postures: captive ore refining, electron-beam melting specialization, and refractory alloy expertise.
| Leading Market Players |
|---|
| Praxair Technology, Inc. |
| Stanford Advanced Materials |
| JX Nippon Mining & Metals Corporation |
| GRIKIN Advanced Material Co., Ltd. |
| ULVAC, Inc. |
| Materion Corporation |
| Plansee SE |
| Kurt J. Lesker Company |
| Mitsui Mining & Smelting Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
EPA hazardous waste generator status revisions gate qualified supply access for semiconductor fabs in Arizona and Texas, while simultaneously compressing premium-tier pricing power for RCRA-permitted reclaimers handling closed-loop tantalum recovery. The regulation creates a bifurcation where certified recyclers command material premiums against non-compliant spot suppliers.
Pricing Analysis
Consignment inventory programs for precious metal targets versus spot purchasing for standard-grade ceramics define the bundled-unbundled service split. Memory manufacturers in Boise and Icheon transfer working capital risk upstream by requiring suppliers to hold refined platinum sponge until consumption triggers payment, while solar cell producers transact on immediate delivery terms. Price differentiation rests on certification depth versus volume scale, with 5N to 6N purity grades commanding substantial premiums over standard electronic-grade material. Cost compression in mid-tier alloy targets is intensifying as China's MIIT-mandated GB standards escalate domestic qualification thresholds. Semiconductor fabs show least price sensitivity for through-silicon via applications, whereas architectural glass coaters prioritize per-square-meter economics above certification pedigree.
Supply Chain Analysis
Single-source vulnerability sits with electron-beam melting capacity concentrated in Austria and Japan for extreme-thickness molybdenum and tungsten targets. Raw material supply draws from Australian titanium sponge under Japan METI bilateral allocation agreements, Russian and Ukrainian zirconium refiners facing ECHA REACH traceability barriers, and captive copper ore refining by integrated Japanese producers. Logistics chokepoints emerge at refractory metal machining nodes where aging technical institutes in Germany and Japan constrain talent replication for new facilities. Distribution runs through qualified supplier programs directly into Hsinchu and Pyeongtaek fab clusters, bypassing traditional distributor channels for ultra-high-purity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sputtering target market functions as a regulatory compounder where EU F-Gas Regulation phase-down schedules for fluorinated process gases are accelerating equipment retrofits and pulling premium-grade alternative chemistry targets into qualification pipelines.
For Market Incumbents: Cement position by securing captive refining of copper and titanium ores following JX Nippon Mining & Metals Corporation's vertical model, and by embedding zone refining expertise through technical institute partnerships in Saxony and Bavaria before talent scarcity worsens. Atomic layer deposition precursors threaten traditional sputtering applications at research scale, making electron-beam melting asset control the priority defensive lever.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in ceramic targets for perovskite solar applications offers white-space entry outside semiconductor procurement cyclicality. India's Gujarat and Karnataka fab incentives under the semiconductor PLI scheme represent the most penetrable geography for qualification programs, with doped tin oxide and nickel oxide hole transport layer specifications as the specific go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for refractory metal specialists with electron-beam melting assets because extreme-thickness applications lack alternative deposition methods and customer switching costs embed deeply in process qualification cycles. Over a five-to-ten-year viability window, target fabricators holding RCRA permits and bilateral titanium sponge allocation agreements represent the acquisition archetype. The signal to monitor is Japan METI rare metal stockpile coordination with Australian miners, as allocation priority shifts will restructure feedstock access tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore Refining | JX Nippon Mining & Metals Corporation anchors copper supply through captive refining, insulating against sponge price volatility. |
| Consignment Inventory Programs | Micron and SK Hynix transfer working capital risk upstream, forcing suppliers to hold precious metal sponge on balance sheets. |
| Cylindrical Magnetron Retrofit | Saint-Gobain and AGC capture 30% higher material yield rates in Ohio and South Carolina architectural glass facilities. |
| Technical Institute Partnerships | German and Japanese zone refining expertise concentrates at aging institutes, constraining talent pipelines for new production facilities. |
| RCRA-Permitted Reclaimer Consolidation | Arizona and Texas fabs consolidate recycling relationships as EPA hazardous waste rules tighten spent target classification thresholds. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fab procurement managers, zone refining metallurgists, electron-beam melting operators, and RCRA-permitted reclaimer executives with secondary validation. SEC 10-K filings from diversified materials conglomerates, Japan METI resource security policy documents, ECHA REACH restriction dossiers, and customs trade data for titanium sponge and zirconium feedstocks anchored the secondary foundation. Bottom-up target consumption estimates by fab capacity and top-down materials flow analysis triangulated to constrain forecast variance.
Historical reference periods spanning pre-pandemic baseline through AI accelerator fab buildout acceleration anchored the forecast window across the projection horizon. Segmentation dimensions modeled include material purity tier, target geometry configuration, end-use vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to qualified supplier penetration rates and capacity expansion announcements. Industry-specific forecast inputs incorporated MIIT-mandated GB standards escalation timelines and perovskite solar tandem cell commercialization trajectories.
The model assumes a particular technology adoption path; alternative pathways for atomic layer deposition precursors would alter the outlook for traditional sputtering target demand. Forecasts reflect assumptions regarding semiconductor node scaling cadence, rare metal stockpile coordination between Japan METI and China's SAMR, and EPA hazardous waste rule enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
Polysilicon for Solar Semiconductor Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
ITO Nanoparticles Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Polymethylhydrosiloxane Market