
 Semiconductor Silicon Wafer Market | 2026-2036
Semiconductor Silicon Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Silicon Wafer Market Outlook
Epitaxial wafer customization is rewriting margin distribution across the value chain. Shin-Etsu Chemical Co., Ltd. anchors high-purity monocrystalline ingot production through captive polysilicon refining. Siltronic AG specializes in 300mm prime wafers for logic foundries, sustaining qualification barriers at leading-edge nodes. SK Siltron Co., Ltd. dominates silicon carbide substrates for power electronics, extending its materials portfolio beyond traditional silicon.
A semiconductor silicon wafer is a thin, circular slice of single-crystal or engineered silicon, typically polished to surface roughness below 0.2 nanometers RMS, serving as the fundamental substrate for integrated circuit fabrication through photolithographic patterning and layer deposition. The 300mm diameter category captures the majority of advanced logic and memory production, where foundries prioritize defect density below 0.1 per square centimeter. Bulk silicon wafers maintain cost advantages in mature-node analog and power applications, while SOI substrates command premiums in radio-frequency and low-power designs where substrate isolation eliminates latch-up risks.
REACH restrictions on perfluorinated compounds constrain etching chemistries used in wafer surface preparation, compelling foundries to validate alternative cleaning protocols. Japan's METI enforces export controls on advanced materials and equipment, reshaping supply security calculations for Korean and Chinese fabs. China's GB standards and dual carbon goals from MEE impose energy-efficiency thresholds on polysilicon smelters, filtering upstream capacity additions. Stakeholders must track which regulatory jurisdictions capture next-generation fab investments, as local content requirements and subsidy eligibility rules will determine wafer procurement geography for the coming decade.
Market Dynamics
Foundry capex cycles and geopolitical subsidy competition are concentrating 300mm prime-grade wafer procurement around Taiwan Semiconductor Manufacturing Company, Samsung Foundry, and Intel's expanding European footprint.
Growth Catalysts
- EU Chips Act capital injections:Subsidy frameworks in Germany, France, and Italy are redirecting fabrication investment toward regional wafer demand, creating captive procurement pools for European polysilicon suppliers.
- Electric vehicle powertrain semiconductor load:Silicon carbide substrates for traction inverters and onboard chargers are expanding wafer area consumption per vehicle beyond legacy internal combustion architectures.
- Advanced node lithography requirements:EUV scanner deployment at 3nm and 2nm nodes demands defect densities below 0.03 per square centimeter, tightening qualification standards for prime-grade silicon suppliers.
Market Restraints
- Polysilicon input cost volatility:Metallurgical-grade silicon and chlorosilane precursor prices fluctuate with Chinese smelter energy rationing under MEE dual carbon enforcement.
- Geographic supply concentration:Over 80 percent of 300mm ingot pulling capacity resides in Japan, South Korea, and Taiwan, exposing procurement security to METI export control unpredictability.
- Perfluorinated compound substitution friction:REACH restrictions on PFC etching chemistries compel foundries to validate alternative surface preparation protocols without yield degradation.
Strategic Opportunities
- Indian fab incentive schemes:PLI scheme disbursements for semiconductor manufacturing are attracting wafer qualification programs from Gujarat and Tamil Nadu greenfield sites.
- Radio-frequency SOI substrate expansion:5G mmWave infrastructure and smartphone front-end modules are creating premium pricing tiers for high-resistivity silicon-on-insulator wafers.
- Photonics-electronics convergence:Silicon photonics transceivers for data center interconnects require specialized epitaxial stacks, opening customization contracts outside commodity memory pricing.
Industry Challenges
- Crystal growth technician scarcity:Czochralski process expertise for 300mm ingot diameter control is concentrated among retiring Japanese and German engineering cohorts.
- Multi-year qualification timelines:Leading-edge logic foundries impose 18-24 month certification cycles for new wafer suppliers, freezing out second-tier polysilicon integrated manufacturers.
- Legacy 200mm equipment obsolescence:Mature-node analog and power semiconductor fabs face spare part shortages for crystal pullers originally commissioned in the 1990s.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Silicon Wafer Market |
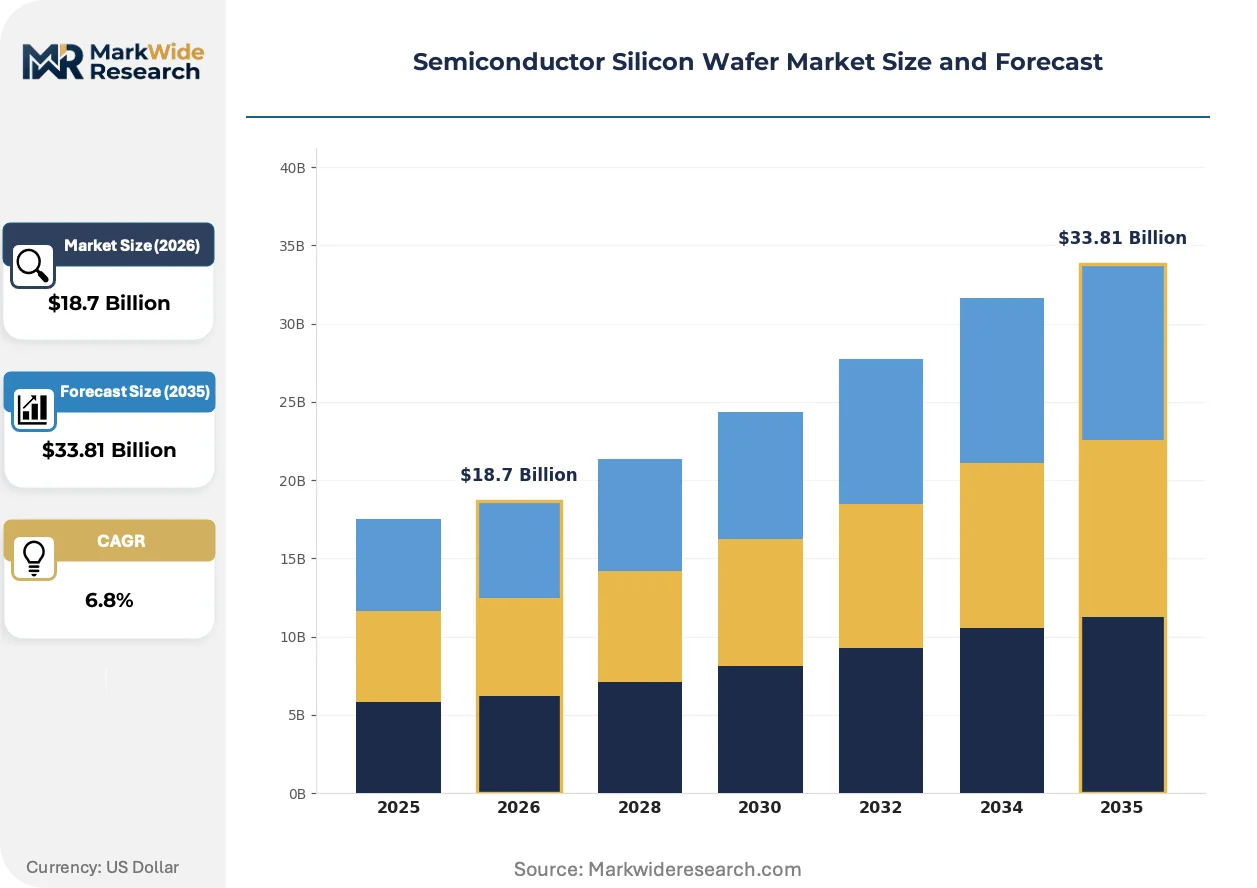
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SOI, Bulk, Epitaxial, Polycrystalline Application: Consumer Electronics, Automotive, Telecommunications, Industrial End User: Integrated Device Manufacturers, Foundries, Research Institutions, OEMs Thickness: 300mm, 200mm, 150mm, 100mm |
| Companies Covered | Siltronic AG, Soitec S.A., Shin-Etsu Chemical Co., Ltd., Wafer Works Corporation, Okmetic Oyj, SUMCO Corporation, SK Siltron Co., Ltd., Shanghai Simgui Technology Co., Ltd., GlobalWafers Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Silicon Wafer Market Strategic Shifts
Wafer surface engineering and substrate architecture diversification are fragmenting the historical commodity pricing model, creating technology-differentiated supply tiers.
Epitaxial deposition thickness control is migrating from homoepitaxial silicon layers toward strained silicon-germanium stacks for CMOS performance enhancement. Advanced logic foundries at 7nm and below are adopting these heterostructures to modulate carrier mobility without scaling gate oxide thickness. This materials shift is compressing margins for bulk silicon suppliers while elevating epitaxial service houses to strategic partnership status.
REACH F-Gas Regulation amendments are phasing down hydrofluorocarbon etchant use in wafer surface texturing and cleaning operations. European polysilicon smelters and wafer polishers must validate aqueous-based or plasma-assisted alternatives by 2027 to maintain CE marking eligibility. German and French chemical suppliers are accelerating fluorine-free precursor development, though Japanese equipment vendors retain process integration expertise.
Long-term supply agreements with prepayment structures are displacing spot-market wafer procurement for 300mm prime grades. Memory and logic foundries in Taiwan and South Korea are locking five-year contracts with Shin-Etsu and SUMCO to secure ingot allocation against geopolitical disruption. This contract densification is visible most acutely in Hsinchu and Pyeongtaek cluster procurement offices, where supplier finance teams now co-locate with customer sourcing departments.
Semiconductor Silicon Wafer Market Segmentation
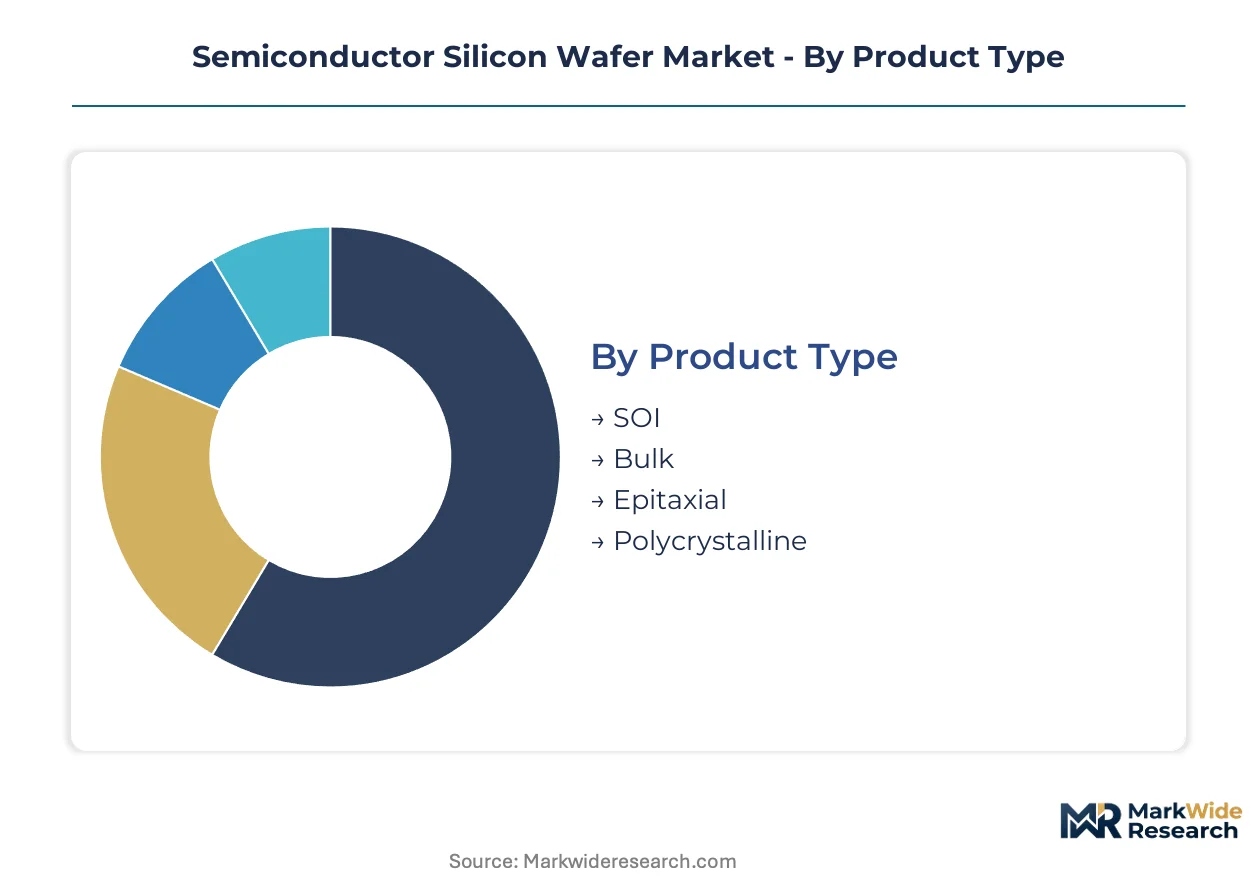
Wafer substrate architecture and diameter specifications fragment procurement patterns across logic foundries, memory fabs, and power semiconductor manufacturers. Each segmentation dimension carries distinct qualification barriers, pricing tiers, and supply security protocols that reshape vendor selection criteria.
Product Type:
Cost tier differentiation separates commodity bulk substrates from engineered variants commanding process-specific premiums.
- SOI:Silicon-on-insulator wafers embed a buried oxide layer beneath the active silicon film, eliminating substrate leakage in radio-frequency and low-power designs. Smartphone front-end modules and 5G base station transceivers in South Korea and Taiwan concentrate procurement of high-resistivity SOI for mmWave performance.
- Bulk:Monocrystalline silicon wafers without epitaxial or insulator layers serve mature-node analog, discrete power, and sensor applications where cost minimization dominates. German and Japanese automotive tier-one suppliers anchor demand for 200mm bulk wafers in traction inverter and battery management systems.
- Epitaxial:Thin crystalline silicon layers deposited on polished substrates enable precise dopant profiles for bipolar-CMOS-DMOS integration.
- Polycrystalline:Multi-grain silicon structures feed solar photovoltaic and thin-film transistor manufacturing outside leading-edge semiconductor flows.
Bulk silicon commands the established base. The steepest expansion runs through epitaxial stacks for heterogeneous integration.
Application:
End-use technology roadmaps dictate surface roughness specifications, defect density thresholds, and thermal budget compatibility.
- Consumer Electronics:Smartphone APs and tablet SoCs drive 300mm prime wafer consumption at sub-7nm nodes. Apple and Qualcomm foundry partners in Hsinchu and Pyeongtaek prioritize zero-defect surface preparation for EUV lithography yield protection.
- Automotive:Silicon carbide substrates for EV powertrains and advanced driver-assistance processors expand wafer area per vehicle. Tesla, BYD, and Volkswagen supply chains source 150mm and 200mm wafers for traction inverters with AEC-Q101 qualification requirements.
- Telecommunications:Base station ASICs and optical transceivers demand specialized substrates for high-frequency signal integrity.
- Industrial:Motor drives, PLCs, and power supplies consume mature-node wafers with extended temperature range specifications.
Consumer electronics absorbs the dominant volume share. Automotive applications are climbing the fastest as electrification multiplies semiconductor content per vehicle.
End User:
Customer type determines qualification timeline intensity, contract structure, and technical collaboration depth.
- Integrated Device Manufacturers:Captive fabrication facilities at Texas Instruments, Infineon, and STMicroelectronics blend internal wafer specification control with multi-source procurement policies. These IDMs maintain 18-24 month supplier qualification cycles for automotive-grade substrates.
- Foundries:Pure-play contract manufacturers including TSMC, Samsung Foundry, and GlobalFoundries concentrate 300mm prime wafer demand through consolidated procurement offices. Long-term supply agreements with prepayment structures displace spot-market transactions for leading-edge nodes.
- Research Institutions:IMEC, CEA-Leti, and academic fabs pilot novel substrate architectures before commercial scale-up.
- OEMs:System houses with captive fab operations source wafers for proprietary ASIC programs.
Foundries concentrate the steepest volume expansion. IDMs defend the most entrenched supplier relationships through backward integration into polysilicon refining.
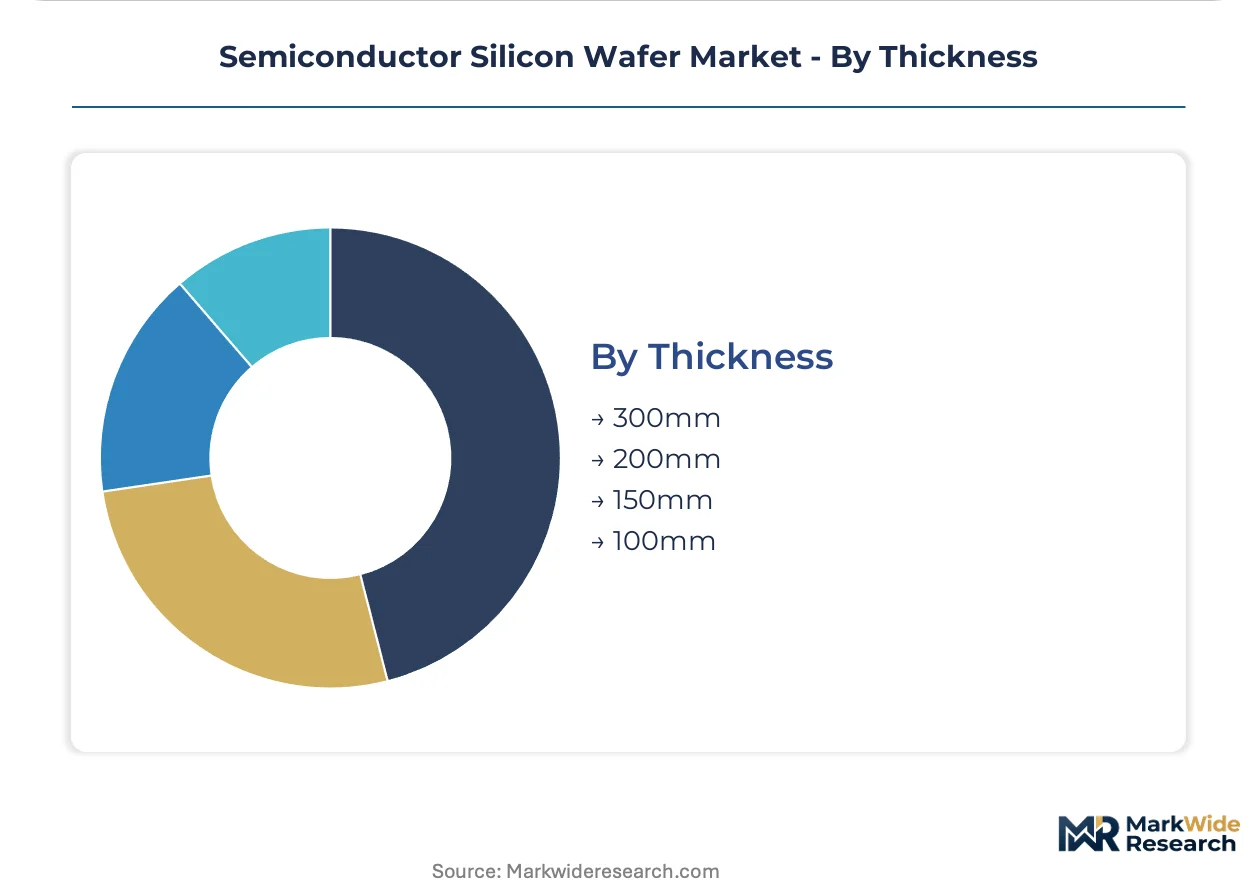
Thickness:
Wafer diameter correlates directly with fabrication efficiency, equipment compatibility, and ingot manufacturing complexity.
- 300mm:Twelve-inch wafers enable 2.25x die count multiplication versus 200mm equivalents, driving unit economics for advanced logic and memory. Taiwan, South Korea, and Arizona fab clusters absorb over 80 percent of global 300mm prime-grade output for EUV-capable production lines.
- 200mm:Eight-inch substrates persist in power semiconductors, analog ICs, and MEMS where equipment depreciation is complete and process maturity minimizes defect sensitivity. European and Japanese automotive semiconductor fabs face spare part shortages for 1990s-vintage crystal pullers.
- 150mm:Six-inch wafers serve silicon carbide substrate production and legacy discrete manufacturing.
- 100mm:Four-inch formats concentrate in compound semiconductor and research applications.
300mm formats dominate value capture. 200mm supply is tightening fastest as equipment obsolescence constrains capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over 80 percent of 300mm ingot pulling capacity concentrates in Japan, South Korea, and Taiwan, exposing procurement security to METI export control unpredictability. This geographic clustering shapes regional investment patterns and subsidy competition. Foundry capex cycles are redirecting wafer demand toward emerging fabrication clusters in Germany, India, and the southwestern United States.
Japan
Advanced crystal growth expertise for 300mm diameter control remains concentrated among retiring engineering cohorts in Tokyo and Osaka prefectures. METI export controls on advanced materials and equipment reshape supply security calculations for Korean and Chinese fabs. Hokkaido-based polysilicon smelters face energy-efficiency thresholds under dual carbon enforcement, filtering upstream capacity additions.
South Korea
Memory and logic foundries in Pyeongtaek and Yongin absorb substantial 300mm prime-grade output for EUV-capable production lines. Long-term supply agreements with prepayment structures displace spot-market transactions for leading-edge nodes. Busan-Ulsan cluster procurement offices now co-locate supplier finance teams with customer sourcing departments to secure ingot allocation.
Taiwan
TSMC and foundry partners in Hsinchu prioritize zero-defect surface preparation for EUV lithography yield protection at sub-7nm nodes. The concentration of advanced logic fabrication creates captive procurement pools for prime-grade silicon suppliers. Tainan and Taichung fab expansions are locking five-year contracts with Japanese ingot producers against geopolitical disruption.
Germany
EU Chips Act capital injections redirect fabrication investment toward regional wafer demand in Dresden and Munich clusters. REACH F-Gas Regulation amendments phase down hydrofluorocarbon etchant use in wafer surface texturing by 2027. Bavarian and Saxon polysilicon suppliers must validate fluorine-free precursor development to maintain CE marking eligibility.
United States
Intel's expanding Arizona and Ohio footprint concentrates 300mm prime-grade wafer procurement for advanced node production. CHIPS Act disbursements attract wafer qualification programs from greenfield sites in the Southwest and Midwest. Phoenix and Columbus metro areas are emerging as procurement hubs for domestic ingot allocation security.
Semiconductor Silicon Wafer Market Competitive Environment
Vertically integrated chemical conglomerates and specialized wafer fabricators split the market into distinct capability tiers. The vendor base organizes around three strategic archetypes: polysilicon-integrated ingot producers commanding upstream cost control, pure-play wafer specialists sustaining qualification barriers at leading-edge nodes, and compound semiconductor substrate diversifiers extending beyond traditional silicon. Dominant competitive moves include long-term supply agreements with prepayment structures and backward integration into captive polysilicon refining.
Among Japanese chemical conglomerates, Shin-Etsu Chemical Co., Ltd. and SUMCO Corporation exemplify the polysilicon-integrated archetype with upstream control over high-purity monocrystalline ingot production. Siltronic AG occupies a position within the European pure-play tier, representing specialized 300mm prime wafer qualification expertise for logic foundries. SK Siltron Co., Ltd. anchors the substrate diversification archetype, sitting within Korean materials portfolios that extend into silicon carbide for power electronics.
| Leading Market Players |
|---|
| Siltronic AG |
| Soitec S.A. |
| Shin-Etsu Chemical Co., Ltd. |
| Wafer Works Corporation |
| Okmetic Oyj |
| SUMCO Corporation |
| SK Siltron Co., Ltd. |
| Shanghai Simgui Technology Co., Ltd. |
| GlobalWafers Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Japanese ingot pulling capacity concentration in Tokyo and Osaka prefectures anchors margin capture at the polysilicon refining tier, forcing downstream foundries to absorb qualification premiums through long-term contract structures. This upstream clustering transfers pricing power from wafer polishers to chemical conglomerates with captive monocrystalline production.
Pricing Analysis
REACH F-Gas Regulation dictates the pricing tier structure across European supply pools, compelling fluorine-free precursor validation costs to embed in Bavarian and Saxon supplier quotes. Three-tier pricing structure across prime-grade, test-grade, and reclaim tiers separates EUV-capable 300mm wafers from mature-node 200mm equivalents, with defect density thresholds below 0.03 per square centimeter commanding substantial premiums. Cost compression in bulk silicon tiers is intensifying because Chinese smelter energy rationing under MEE dual carbon enforcement feeds metallurgical-grade silicon volatility. Memory foundries exhibit least price sensitivity due to prepayment-structured five-year contracts, while analog IDMs face acute margin pressure from legacy equipment obsolescence.
Supply Chain Analysis
TSMC, Samsung Foundry, and Intel's expanding Arizona footprint concentrate contract-manufacturing demand for 300mm prime-grade output. Ingot pulling capacity draws from Japan, South Korea, and Taiwan, with polysilicon refining anchored in Hokkaido and Ulsan. Single-source vulnerability permeates the Czochralski crystal growth equipment tier, where Japanese vendors retain process integration expertise for diameter control. Distribution runs through co-located procurement offices in Hsinchu and Pyeongtaek, where supplier finance teams secure allocation against geopolitical disruption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epitaxial deposition services and substrate customization layers expand faster than commodity wafer sales, creating attach-rate opportunities for process-specific engineering contracts. This service-attach dynamic rewards suppliers who migrate from transactional spot procurement to multi-year technical partnerships.
For Market Incumbents: Harden qualification barriers at sub-7nm nodes by embedding with EUV-capable foundry roadmaps before 18-24 month certification cycles freeze out challengers. Expand captive polysilicon refining in Hokkaido or Ulsan to offset METI export control unpredictability threatening Korean and Chinese fab security. Lock five-year prepayment structures with memory and logic foundries to defend margin position against spot-market volatility.
For New Entrants and Emerging Players: Indian fab incentive schemes in Gujarat and Tamil Nadu offer the most penetrable geographic entry point, with PLI disbursements attracting wafer qualification programs from greenfield sites lacking established supplier relationships. Target radio-frequency SOI substrate expansion for 5G mmWave infrastructure, where high-resistivity specifications command premiums outside commodity memory pricing. Lead with photonics-electronics convergence applications requiring specialized epitaxial stacks, bypassing entrenched competition in bulk silicon tiers.
For Investors and Strategic Acquirers: Capital is best deployed toward polysilicon-integrated ingot producers with upstream cost control and established foundry qualification relationships. Long-term viability across the analysis window favors suppliers with backward integration into high-purity monocrystalline production and technical collaboration depth at leading-edge nodes. Watch METI export control enforcement patterns as the critical inflection signal for regional procurement security recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement with Prepayment | Secures ingot allocation for TSMC and Samsung Foundry against geopolitical disruption in East Asian supply corridors. |
| Backward Integration into Polysilicon Refining | Shin-Etsu and SUMCO anchor cost control through captive Hokkaido smelter capacity under MEE dual carbon thresholds. |
| Fluorine-free Precursor Development | German and French chemical suppliers validate REACH F-Gas alternatives to maintain CE marking eligibility by 2027. |
| Silicon Carbide Substrate Diversification | SK Siltron extends materials portfolio beyond silicon into power electronics for EV traction inverter applications. |
| Crystal Growth Technician Training Program | Addresses Czochralski expertise scarcity among retiring Japanese and German engineering cohorts for 300mm diameter control. |
Study Parameters
Operator-level perspectives from crystal growth engineers, foundry procurement directors, polysilicon smelter managers, and epitaxial deposition specialists anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, METI trade statistics, EU Chips Act disbursement records, and REACH regulatory amendments. Bottom-up wafer demand modeling by diameter, substrate architecture, and end-use application triangulated against top-down foundry capex cycle analysis.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, application, end user, and thickness specifications. CAGRs derived from equipment installation timelines, node migration roadmaps, and electric vehicle semiconductor content trajectories. Forecast inputs incorporated EUV scanner deployment schedules, polysilicon smelter energy-efficiency thresholds, and automotive qualification cycle durations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed entrants or accelerated METI export control expansion would shift outcomes. Quarterly review of foundry equipment utilization rates, polysilicon spot pricing, and EU Chips Act disbursement velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Asia Pacific Graphene Market
Semiconductor Material
Europium Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
Semiconductor Glass Market
Semiconductor Material
Ultra High Purity Silicon Carbide Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Semiconductor Materials Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Silicon Carbide (Sic) Coating Market
Semiconductor Material
Yttrium Market
Semiconductor Material
Yttrium Oxide Market
Semiconductor Material
Silicon Dioxide Market