
 Trace Chemical Detector Market | 2026-2036
Trace Chemical Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Trace Chemical Detector Market Outlook
Asset-light leasing models for field-deployable detection units is reconfiguring capital requirements for security agencies and industrial buyers. Smiths Detection Group Ltd. leverages its airport screening installed base to extend service contracts into chemical threat monitoring. Bruker Corporation anchors its position through high-resolution mass spectrometry R&D intensity. Teledyne FLIR LLC competes by integrating thermal imaging with trace chemical sensing for layered threat assessment.
Trace chemical detectors are analytical instruments designed to identify and quantify substances at parts-per-billion concentrations, typically employing ion mobility spectrometry, surface acoustic wave sensors, or colorimetric reagent chemistry to trigger alarms within seconds of sample introduction. These systems serve critical functions in explosives ordnance disposal, clandestine laboratory interdiction, and industrial hygiene verification where human sensory detection fails. Portable detectors lead procurement volumes due to military dismounted operations and emergency responder mobility requirements, while benchtop systems command margin pools in forensic laboratory settings. Raman spectroscopy represents the fastest-expanding technology segment as laser stability improvements reduce false positive rates in complex matrices.
The US Transportation Security Administration and the European Civil Aviation Conference enforce performance standards that mandate detection sensitivity thresholds for passenger screening equipment, directly shaping manufacturer R&D priorities. The EPA and OSHA jointly regulate workplace exposure monitoring protocols that industrial facilities must satisfy through certified detection systems. Stakeholders must monitor how artificial intelligence integration into spectral interpretation algorithms reshapes competitive differentiation between hardware-centric and software-augmented platform strategies.
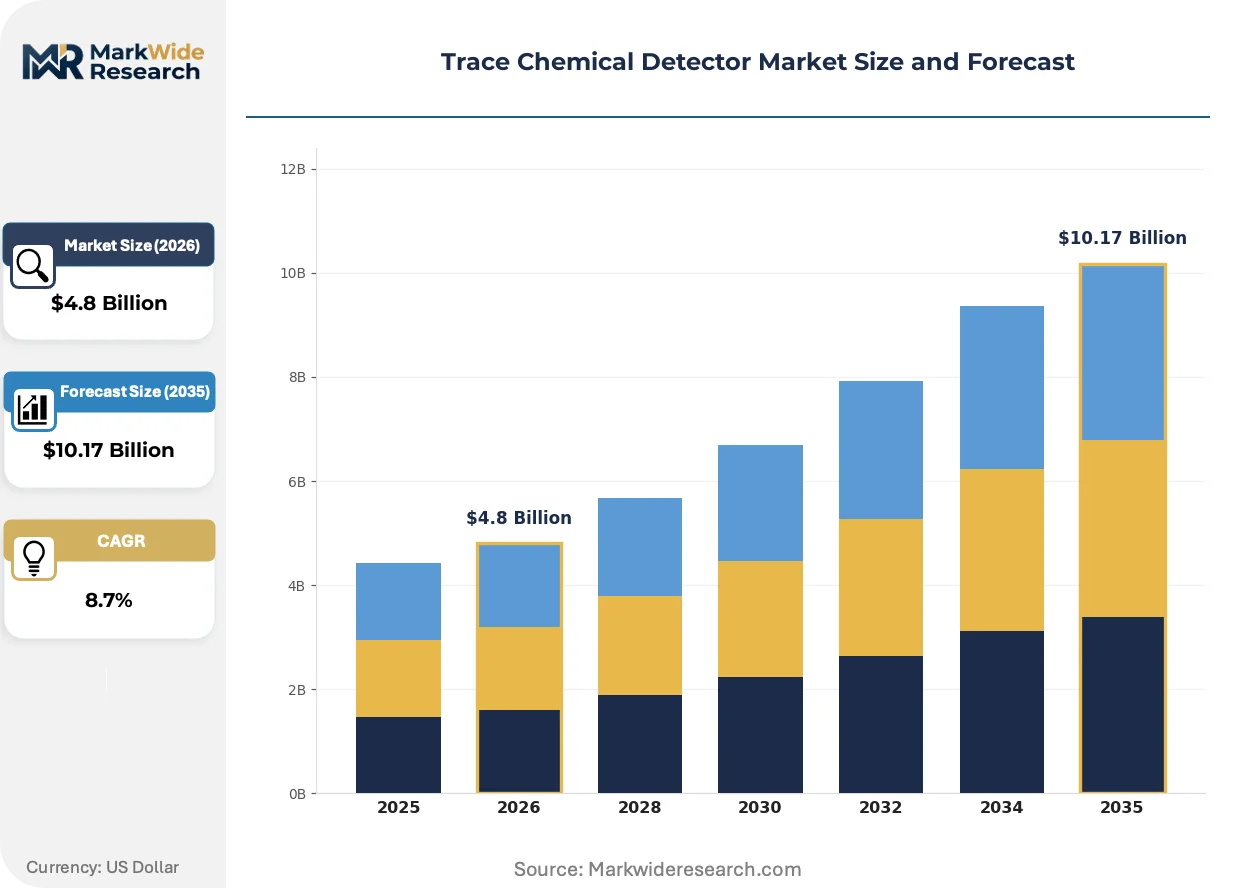
Market Dynamics
Miniaturization of ion mobility spectrometry modules is compressing unit economics and enabling first-responder agencies to triple fleet deployments without proportional budget expansion.
Growth Catalysts
- Counter-terrorism procurement mandates:NATO defense ministries are standardizing portable chemical detection for dismounted soldier programs, creating multi-year equipment refresh cycles.
- REACH chemical exposure monitoring:European industrial facilities must deploy certified trace detection for high-toxicity substance handling, mandating workplace verification protocols.
- Raman spectroscopy maturation:Laser stabilization advances are reducing false positive rates in complex environmental matrices, accelerating forensic laboratory adoption.
Market Restraints
- Sensor calibration drift:Surface acoustic wave devices require frequent recalibration against certified reference standards, elevating total cost of ownership.
- Semiconductor supply concentration:Specialty infrared detector arrays depend on limited foundry capacity in East Asia, creating procurement lead time volatility.
- Substitution by mass spectrometry:Benchtop high-resolution systems are displacing ion mobility units in forensic laboratories where judicial admissibility standards are tightening.
Strategic Opportunities
- India industrial safety enforcement:BIS certification requirements for hazardous chemical handling are expanding mandatory detection deployment across petrochemical and pharmaceutical manufacturing.
- Artificial intelligence spectral interpretation:Machine learning algorithm integration with portable hardware is creating differentiated software-augmented platform strategies.
- Leasing-based service models:Asset-light operational contracts are reconfiguring capital requirements for municipal emergency response departments and private security operators.
Industry Challenges
- Spectroscopy expertise scarcity:Qualified technicians capable of interpreting complex spectral signatures remain concentrated in national laboratory systems, constraining field deployment scaling.
- Multi-jurisdiction certification complexity:EPA, OSHA, and TSA maintain non-harmonized performance validation protocols, fragmenting product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trace Chemical Detector Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Handheld Detectors, Benchtop Detectors Technology: Mass Spectrometry, Gas Chromatography, Infrared Spectroscopy, Raman Spectroscopy End User: Government Agencies, Military, Environmental Testing Labs, Industrial Facilities Application: Hazardous Material Detection, Explosive Detection, Drug Testing, Air Quality Monitoring |
| Companies Covered | Smiths Detection Group Ltd., Teledyne FLIR LLC, Bruker Corporation, Analogic Corporation, OSI Systems, Inc., Leidos Holdings, Inc., Autoclear LLC, DetectaChem, L3Harris Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trace Chemical Detector Market Strategic Shifts
Detection hardware is converging with computational analytics, shifting competitive advantage from sensor purity to algorithmic interpretation speed and accuracy.
Hyperspectral imaging arrays paired with edge computing architectures are virtualizing traditional laboratory-grade chemical identification into handheld form factors. Military explosive ordnance disposal units and hazmat response teams are field-testing these systems for real-time threat classification. This convergence is virtualizing the boundary between field-deployable and benchtop analytical performance tiers.
The EPA and OSHA joint workplace exposure monitoring protocols are tightening detection sensitivity thresholds for industrial hygiene verification. Facilities handling acutely toxic substances must now deploy continuous monitoring rather than periodic spot-checking. Chemical manufacturing plants in Texas and Louisiana are retrofitting production lines with networked sensor arrays to satisfy these expanded obligations.
Security agencies are unbundling detection hardware from service contracts, treating analytical platforms as consumable infrastructure rather than capital assets. Municipal procurement departments are shifting toward operational expenditure models with guaranteed uptime clauses. This reconfiguration is most pronounced in Germany and Japan where counter-terrorism budgets face political pressure for efficiency demonstration.
Trace Chemical Detector Market Segmentation
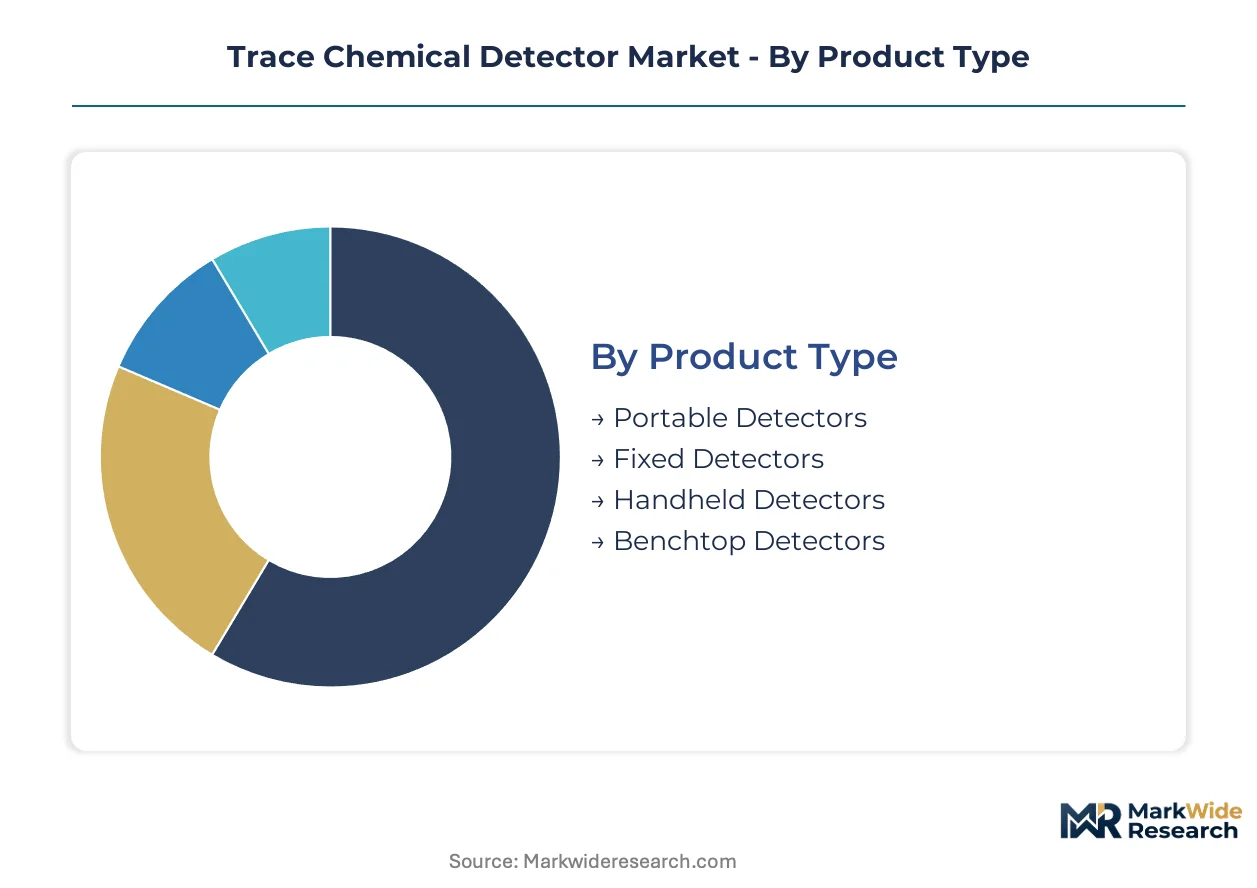
Segmentation in trace chemical detection reveals how procurement priorities diverge between mobile threat response and stationary compliance monitoring. Technology choices further stratify buyers across forensic precision requirements versus field durability demands.
Product Type:
Mature portable platforms dominate procurement volumes while emerging form factors reshape deployment economics across security and industrial verticals.
- Portable Detectors:Battery-powered units under 5 kg deploy ion mobility spectrometry or Raman modules for dismounted military operations and hazmat response. NATO standardization programs in Germany and the United States are tripling fleet purchases without proportional budget expansion through miniaturization gains.
- Handheld Detectors:Single-operator devices integrate surface acoustic wave sensors or colorimetric chemistry for rapid screening at checkpoints. Japanese counter-terrorism units and US Transportation Security Administration checkpoints drive replacement cycles as laser stabilization reduces false positive rates.
- Fixed Detectors:Permanently installed sensor arrays provide continuous perimeter monitoring for critical infrastructure and chemical manufacturing facilities.
- Benchtop Detectors:Laboratory-grade systems employ high-resolution mass spectrometry for forensic admissibility standards in judicial proceedings.
Portable detectors retain volume leadership; handheld variants hold the steepest expansion curve as sensitivity thresholds tighten at security checkpoints.
Technology:
Cost tiers separate mature detection methods from emerging spectroscopic platforms competing on interpretation speed and matrix complexity handling.
- Raman Spectroscopy:Laser-based molecular fingerprinting achieves non-contact identification through transparent containers and colored substrates. Forensic laboratories in Japan and industrial hygiene programs in Texas petrochemical clusters are accelerating procurement as algorithmic interpretation matures.
- Mass Spectrometry:High-resolution benchtop systems deliver judicial-grade specificity for explosive residue and clandestine laboratory evidence. EPA and OSHA joint workplace monitoring protocols in Louisiana chemical plants are displacing ion mobility units where certification standards tighten.
- Infrared Spectroscopy:Fourier-transform instruments provide rapid functional group identification for hazmat classification and unknown substance screening.
- Gas Chromatography:Separation-based detection achieves parts-per-trillion sensitivity for complex mixture analysis in environmental compliance testing.
Mass spectrometry commands premium pricing tiers; Raman platforms are climbing the fastest as portable laser stability improves.
End User:
Customer type determines procurement modality, with defense ministries favoring capital acquisition and municipal agencies shifting toward operational expenditure models.
- Military:Dismounted soldier programs and explosive ordnance disposal units require ruggedized portable units with sub-10-second alarm response. NATO members in Germany and the United States are executing multi-year equipment refresh cycles with standardized performance specifications.
- Industrial Facilities:Chemical manufacturing and pharmaceutical plants deploy continuous monitoring to satisfy REACH exposure verification and BIS certification requirements in India. Texas and Louisiana petrochemical corridors are retrofitting production lines with networked sensor arrays.
- Government Agencies:Federal emergency response departments and border security operations procure through leasing-based service contracts with guaranteed uptime clauses.
- Environmental Testing Labs:Commercial analytical services perform regulatory compliance screening for soil, water, and air matrices under EPA and state environmental agency protocols.
Military end users retain volume leadership; industrial facilities are gaining share fastest as workplace exposure monitoring mandates expand across jurisdictions.
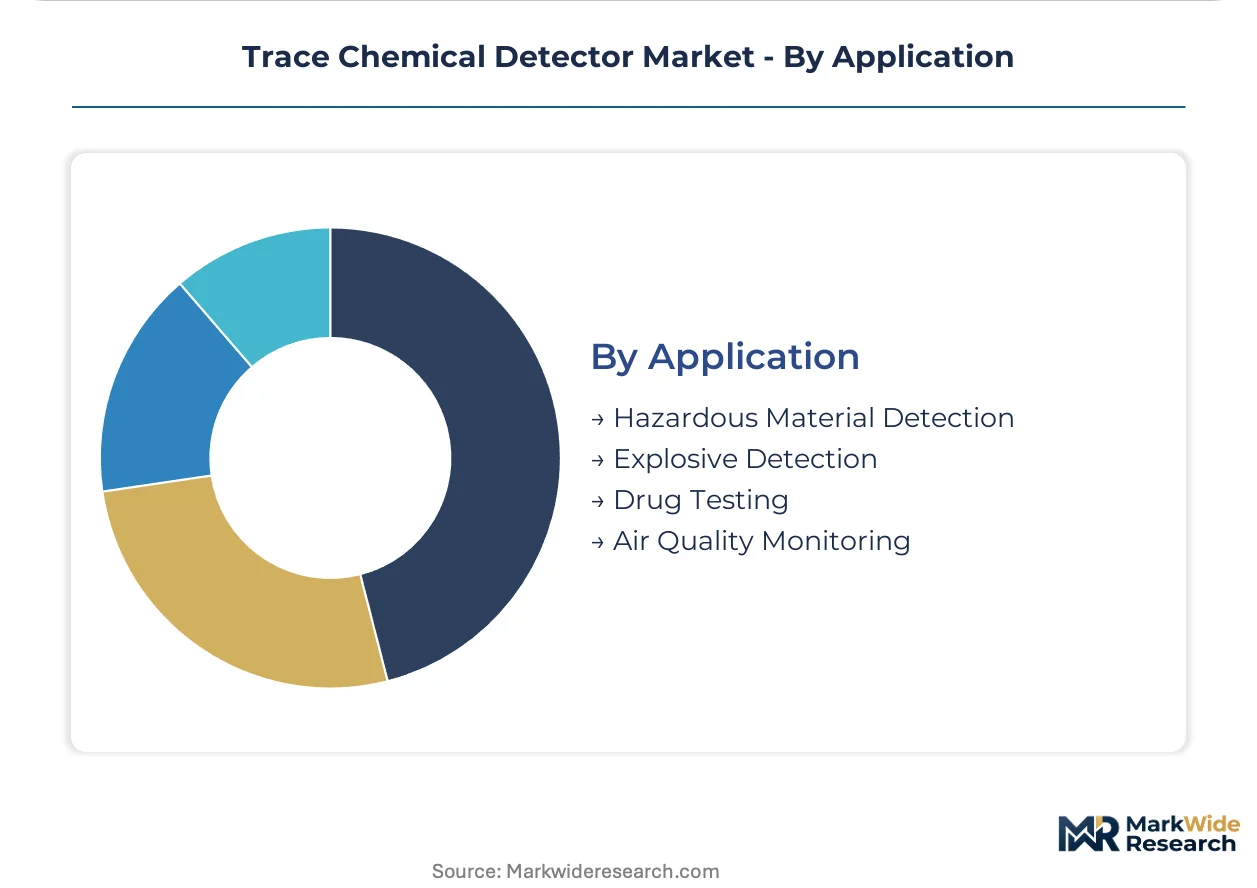
Application:
Application scope spans reactive threat response to proactive compliance verification, with divergent performance requirements shaping technology selection.
- Explosive Detection:Trace particle and vapor screening for aviation security, critical infrastructure protection, and military forward operating bases. TSA performance standards directly shape manufacturer sensitivity specifications for passenger checkpoint equipment.
- Hazardous Material Detection:Unknown substance identification for fire department hazmat teams and clandestine laboratory interdiction. First responder agencies in Germany and Japan are adopting asset-light leasing to demonstrate budget efficiency under political scrutiny.
- Drug Testing:Forensic identification of controlled substances and precursor chemicals for law enforcement evidence chains.
- Air Quality Monitoring:Continuous industrial emissions verification and workplace exposure assessment under EPA and OSHA joint protocols.
Explosive detection retains volume leadership; hazardous material applications are expanding most quickly as urban emergency response capabilities upgrade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Counter-terrorism procurement mandates and industrial safety enforcement are reshaping national deployment patterns for trace chemical detection systems. NATO defense ministries and national regulators are driving standardization while emerging economies introduce mandatory workplace monitoring protocols.
United States
The Transportation Security Administration mandates detection sensitivity thresholds for passenger screening equipment, directly shaping manufacturer R&D priorities. The EPA and OSHA jointly regulate workplace exposure monitoring protocols that industrial facilities must satisfy through certified detection systems. Chemical manufacturing plants in Texas and Louisiana are retrofitting production lines with networked sensor arrays to satisfy expanded obligations.
Germany
Counter-terrorism budgets face political pressure for efficiency demonstration, accelerating adoption of asset-light leasing models. REACH chemical exposure monitoring requirements mandate certified trace detection for high-toxicity substance handling in industrial facilities. Municipal emergency response departments in Bavaria and North Rhine-Westphalia are shifting toward operational expenditure models with guaranteed uptime clauses.
Japan
METI standards and counter-terrorism procurement programs drive replacement cycles for checkpoint screening equipment. Laser stabilization advances are reducing false positive rates, accelerating adoption by security agencies and forensic laboratories. Industrial hygiene programs in the Kanto and Kansai regions are deploying Raman spectroscopy for pharmaceutical manufacturing verification.
India
BIS certification requirements for hazardous chemical handling are expanding mandatory detection deployment across petrochemical and pharmaceutical manufacturing. The country's national industrial safety regulator enforces workplace verification protocols that mirror European REACH frameworks. Manufacturing clusters in Maharashtra and Gujarat are retrofitting facilities to satisfy expanded certification obligations for export market access.
United Kingdom
Border security operations and federal emergency response departments procure through leasing-based service contracts with guaranteed uptime clauses. The country's national security agency maintains performance validation protocols for explosive ordnance disposal equipment. Critical infrastructure protection programs in London and the Southeast are deploying continuous perimeter monitoring for chemical threat detection.
Trace Chemical Detector Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement verticals. The vendor base spans airport screening incumbents, defense contractors, and analytical instrumentation specialists with limited overlap in customer relationships. Three archetypes dominate: integrated security platforms leveraging installed bases, precision instrumentation specialists competing on resolution specifications, and ruggedized hardware suppliers serving military dismounted operations. Consolidation pressure is intensifying through strategic partnerships between sensor module suppliers and platform integrators, alongside geographic expansion into emerging industrial safety markets.
Within the integrated security platform tier, Smiths Detection Group Ltd. and Teledyne FLIR LLC exemplify channel-controlling strategies that leverage established screening infrastructure. Bruker Corporation occupies a position among precision instrumentation specialists competing on high-resolution mass spectrometry R&D intensity. These three entities represent distinct competitive vectors: installed base extension, thermal imaging convergence, and laboratory-grade specificity.
| Leading Market Players |
|---|
| Smiths Detection Group Ltd. |
| Teledyne FLIR LLC |
| Bruker Corporation |
| Analogic Corporation |
| OSI Systems, Inc. |
| Leidos Holdings, Inc. |
| Autoclear LLC |
| DetectaChem |
| L3Harris Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
East Asian foundry clusters in Taiwan and South Korea anchor infrared detector array production, concentrating upstream bargaining power among specialty semiconductor suppliers and compressing margins for downstream system integrators dependent on these components.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between premium laboratory systems and field-deployable units. Three-tier pricing structure across forensic-grade, industrial-certified, and rapid-screening levels segments buyers by judicial admissibility requirements. Cost compression in handheld ion mobility units is intensifying because miniaturization gains enable fleet tripling without proportional budget expansion. Municipal emergency response departments exhibit highest price sensitivity; defense ministries with NATO standardization mandates demonstrate lowest.
Supply Chain Analysis
Specialty EMS providers in Taiwan, Japan, and Germany hold concentrated capacity for surface acoustic wave sensor fabrication and laser stabilization module assembly. The supply chain draws from germanium substrates, quantum cascade laser diodes, and precision optical components as critical inputs. Single-source vulnerability in East Asian foundry capacity for infrared detector arrays creates procurement lead time volatility. Distribution runs through defense procurement channels, analytical instrumentation distributors, and direct service contracts with guaranteed uptime clauses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward municipal agencies consolidating procurement through leasing-based operational expenditure models, fragmenting the traditional capital-equipment vendor base.
For Market Incumbents: Harden installed base retention by extending service contracts into chemical threat monitoring, as Smiths Detection leverages airport screening infrastructure. Deepen backward integration into ion mobility spectrometry module production to offset semiconductor supply concentration. Prioritize AI-augmented spectral interpretation R&D to differentiate against mass spectrometry substitution in forensic laboratories. For New Entrants and Emerging Players: Pursue white-space opportunity in India's BIS-certified industrial safety enforcement, where petrochemical and pharmaceutical manufacturing clusters face mandatory retrofit obligations. Target asset-light leasing provision for municipal emergency response departments in Germany and Japan facing political efficiency pressure. Lead with software-augmented platform strategies integrating machine learning interpretation with portable hardware. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-mandate play because counter-terrorism procurement cycles and workplace exposure monitoring obligations create durable demand visibility. Target acquisition candidates with AI spectral interpretation capabilities and established service contract infrastructure. Monitor NATO defense ministry standardization program announcements as volume inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| AI Spectral Interpretation Integration | Machine learning algorithms differentiate portable platforms from benchtop precision in TSA-mandated checkpoints. |
| Backward Integration into Sensor Modules | In-house production of ion mobility spectrometry components reduces dependency on East Asian foundry capacity. |
| Leasing-Based Service Model Expansion | Operational expenditure contracts reconfigure municipal procurement away from capital asset ownership in Germany. |
| REACH Certification Pathway Investment | CE marking for high-toxicity substance handling unlocks mandatory deployment across European industrial facilities. |
| Joint Venture with Defense Contractors | NATO standardization programs require dismounted soldier program integration for multi-year equipment refresh cycles. |
Study Parameters
The analysis maps ion mobility spectrometry, Raman spectroscopy, mass spectrometry, and surface acoustic wave technology segments, each validated through defense procurement officers, hazmat response coordinators, forensic laboratory directors, and industrial hygiene managers. Primary interviews triangulate with secondary sources including EPA workplace monitoring protocols, TSA performance standards, NATO equipment specifications, and REACH enforcement guidance. Bottom-up unit deployment estimates cross-validate against top-down budget allocation analysis.
Forecast assumptions hold regulatory mandate timelines and semiconductor supply capacity fixed while varying counter-terrorism budget appropriations and industrial safety enforcement intensity across the projection horizon. Segmentation models incorporate product form factor, technology type, end-user procurement modality, and application-specific performance requirements. CAGRs derive from equipment refresh cycle analysis and fleet expansion elasticity to budget constraints, with sensitivity testing against ion mobility miniaturization adoption curves and mass spectrometry displacement rates in forensic settings.
Macroeconomic conditions sit as an overlay; deviation in defense spending trajectories or industrial capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding NATO standardization program continuity and REACH enforcement expansion. Quarterly review of defense ministry procurement announcements and BIS certification obligation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global Fixed Zirconia Oxygen Analyzer Market
Analytical Instruments
Electrochemistry Meters Market
Analytical Instruments
Microfluidic Devices Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Absorption Spectrometers Market
Analytical Instruments
Cleanroom Particle Counters Market
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
Electron Probe Microanalyzers (EPMA) Market
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Laser-Based Gas Analyzers Market
Analytical Instruments
Global Mass Spectrometry Market
Analytical Instruments
Flame Spectrometers Market
Analytical Instruments
Next Generation Mass Spectrometer Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Spatial Mass Spectrometry Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market