
 Global Semiconductor Microelectronics Materials Market | 2026-2036
Global Semiconductor Microelectronics Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Microelectronics Materials Market Outlook
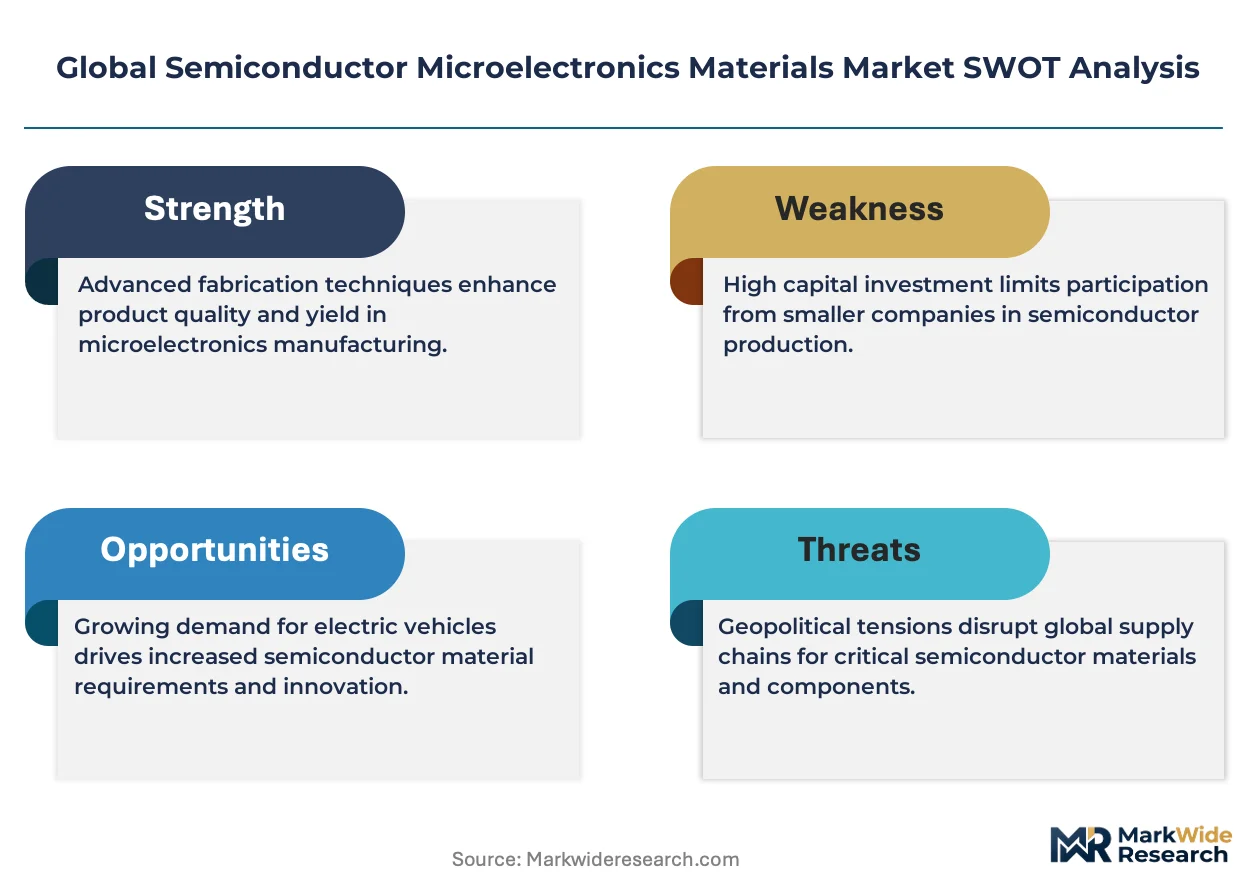
Capital-intensity divergence between integrated material suppliers and merchant specialists is bifurcating competitive dynamics in semiconductor microelectronics materials. Shin-Etsu Chemical Co., Ltd. leverages captive polysilicon refining and crystal growth to control silicon wafer purity grades. Dow Inc. anchors its position through advanced chemical mechanical planarization slurries and specialty gases for sub-7nm nodes. SK Siltron competes aggressively in silicon carbide substrates for power electronics, extending its footprint beyond traditional silicon.
Semiconductor microelectronics materials encompass engineered substances—silicon, gallium arsenide, indium phosphide, and silicon carbide—processed into wafers, substrates, films, or powders with atomic-level purity specifications, serving as the physical foundation for integrated circuit fabrication. These materials must meet defect densities below one per square centimeter at critical dimensions to enable functional yield in high-volume manufacturing. Silicon wafers in 300mm diameter remain the dominant revenue pool, though silicon carbide substrates command premium pricing due to supply scarcity and electric vehicle inverter demand. MEMS technology applications in automotive pressure sensors and consumer motion controllers represent the fastest-growing end-use trajectory within the technology segment.
REACH in Europe restricts perfluorinated compound emissions from etching processes, forcing material suppliers to reformulate cleaning chemistries and deposition precursors. The EPA in the United States enforces hazardous air pollutant standards that elevate compliance costs for domestic chemical suppliers serving fabs. Japan's METI coordinates supply security measures for silicon wafer and photoresist stockpiles, directly influencing procurement patterns among Japanese equipment and material houses. Stakeholders must monitor how export control expansions on deposition equipment redirect substrate sourcing strategies across foundry networks.
Market Dynamics
Advanced packaging architectures for artificial intelligence accelerators are compressing substrate qualification timelines while pulling silicon carbide and specialized wafer demand into uncharted volume territory. This structural force is rewiring procurement relationships between foundry operators and their material suppliers.
Growth Catalysts
- EU Chips Act capital redirection:Sovereign semiconductor programs across Europe are redirecting capital flows toward domestic wafer fabrication, creating captive demand for high-purity silicon and specialty gases.
- Electric vehicle inverter deployment:Silicon carbide substrates for power electronics are experiencing demand acceleration from automotive OEMs transitioning traction inverter architectures.
- Taiwan foundry cluster concentration:Leading-edge fabrication capacity concentration in Hsinchu and Tainan Science Parks sustains premium pricing for 300mm silicon wafers and advanced photoresists.
Market Restraints
- Silicon carbide substrate scarcity:Crystal growth yield limitations and boule processing bottlenecks constrain supply expansion despite electric vehicle pull.
- Perfluorinated compound restrictions:REACH regulations in Europe force reformulation of etching chemistries and deposition precursors, elevating R&D recovery timelines.
- Polysilicon input volatility:Energy-intensive metallurgical-grade silicon refining faces electricity cost swings that transmit directly to wafer substrate pricing.
Strategic Opportunities
- India semiconductor ecosystem emergence:PLI scheme incentives and Gujarat Dholera fabrication zone development create greenfield material supply opportunities.
- MEMS sensor proliferation:Automotive pressure sensing and consumer motion control applications represent underpenetrated volume expansion vectors.
- Photoresist stockpile coordination:Japan METI supply security measures open procurement partnership models for foreign material houses.
Industry Challenges
- Atomic-scale defect control:Sub-7nm node manufacturing requires defect densities below one per square centimeter, demanding capital-intensive cleanroom and metrology infrastructure.
- Export control navigation:Deposition equipment restrictions are forcing substrate sourcing strategy reconfigurations across multinational foundry networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Microelectronics Materials Market |
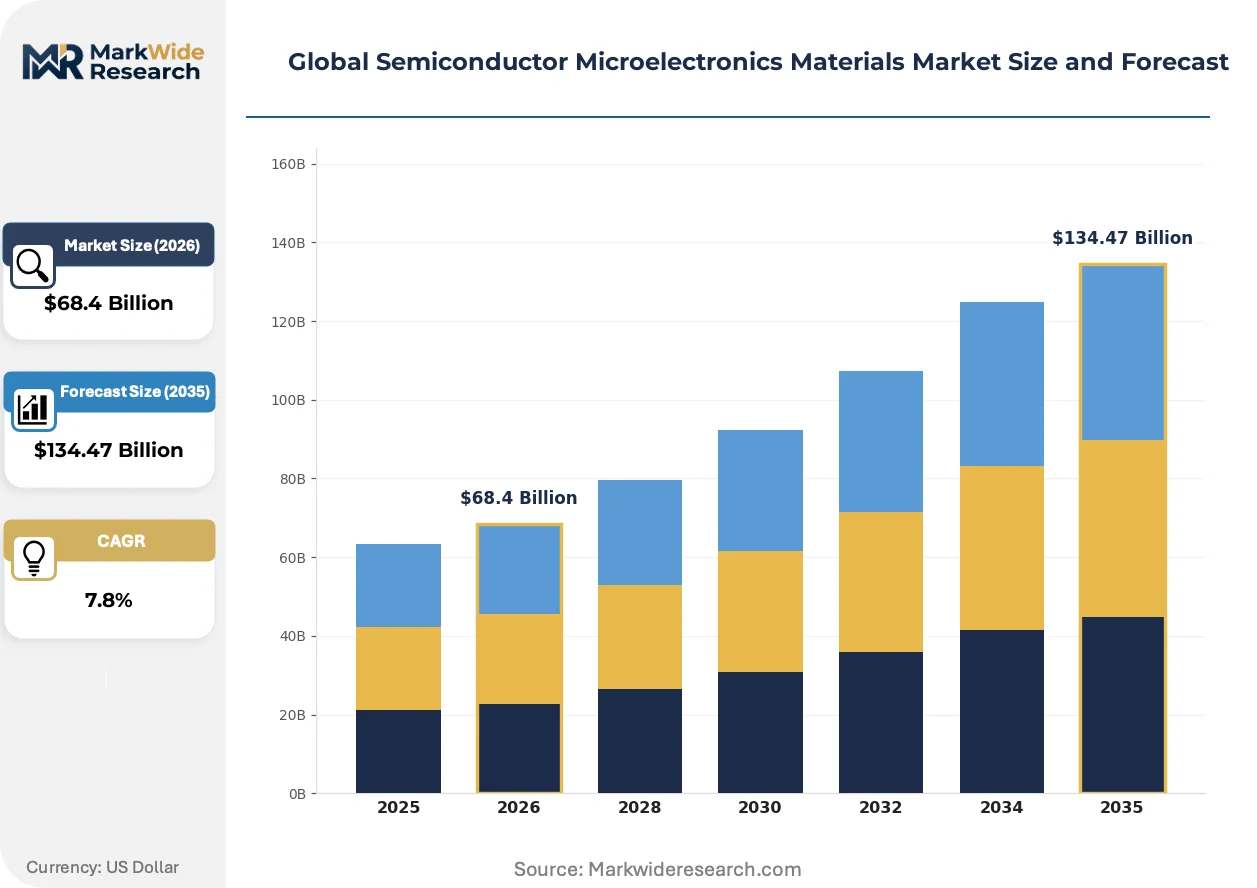
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $134.47 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Silicon, Gallium Arsenide, Indium Phosphide, Silicon Carbide Form Factor: Wafer, Substrate, Film, Powder End User Industry: Consumer Electronics, Telecommunications, Automotive, Industrial Automation Technology: MEMS, CMOS, BiCMOS, SOI |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Sumco Corporation, Dow Inc., Kyocera Corporation, Entegris, Applied Materials, Inc., SK Siltron, SUMITOMO CHEMICAL, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Microelectronics Materials Market Strategic Shifts
Wafer-level packaging and heterogeneous integration are dissolving traditional boundaries between front-end materials and back-end assembly processes. This convergence is spawning new material categories and qualification protocols.
Silicon carbide substrate technology serves high-voltage power switching applications with superior thermal conductivity and breakdown field strength compared to silicon. Automotive inverter manufacturers are adopting 150mm and 200mm SiC wafers at accelerating qualification pace. This adoption trajectory is bifurcating the merchant substrate market into automotive-qualified and industrial-grade supply tiers with diverging purity specifications.
REACH perfluorinated compound emission restrictions in Europe mandate reformulation of cleaning chemistries and deposition precursors by 2025 implementation deadlines. Chemical suppliers serving European fabs must redesign molecular architectures to maintain etch selectivity while eliminating persistent organic pollutants. Advanced node foundries in Ireland and Germany face the steepest compliance cost gradients.
Long-term supply agreements are displacing spot market purchasing for critical materials including silicon wafers, specialty gases, and photoresists. Foundry operators in Taiwan and South Korea are locking multi-year volume commitments directly with Shin-Etsu, SK Siltron, and JSR to secure allocation certainty. This contractual pivot is most visible in 300mm silicon wafer procurement where spot liquidity has contracted substantially.
Global Semiconductor Microelectronics Materials Market Segmentation
Material specifications cascade through form factors, end-use applications, and process technologies to create distinct procurement channels. Each segmentation axis governs qualification protocols, pricing tiers, and supplier relationships differently.
Material Type:
Channel distribution varies sharply by material chemistry, with silicon flowing through high-volume merchant distributors while compound semiconductors route through specialized substrate houses.
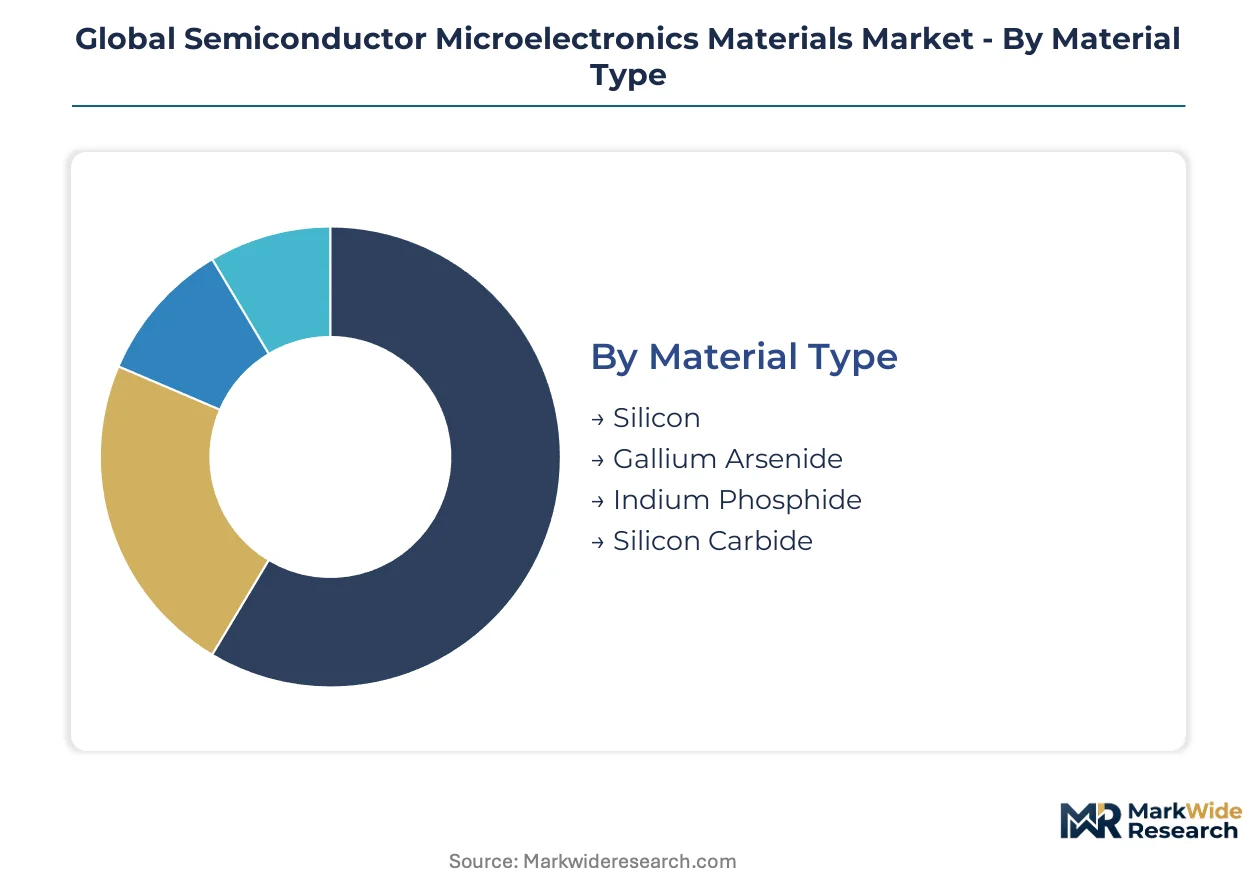
- Silicon:Metallurgical-grade polysilicon refined to 11N+ purity serves as the atomic foundation for 300mm logic and memory wafers. Taiwan foundry clusters in Hsinchu and Tainan absorb the majority of merchant supply under multi-year offtake agreements with Shin-Etsu and SUMCO.
- Silicon Carbide:Hexagonal polytype 4H-SiC boules sliced into 150mm and 200mm substrates command premium pricing due to crystal growth yield constraints. Automotive OEMs in Germany and the United States are qualifying SiC for traction inverters faster than substrate suppliers can expand furnace capacity.
- Gallium Arsenide:III-V compound substrates enable high-frequency RF amplification for 5G base station deployments.
- Indium Phosphide:Direct bandgap material supports photonic integrated circuits for datacenter interconnects.
Silicon dominates installed base. Silicon Carbide is where expansion concentrates.
Form Factor:
Cost tier stratification separates raw feedstock from qualified device-ready substrates, with each tier carrying exponentially higher value-add per kilogram.
- Wafer:Polished single-crystal discs in 200mm and 300mm diameters undergo epitaxial deposition and ion implantation to become active device layers. Leading-edge logic fabs in South Korea and the United States restrict procurement to a qualified vendor matrix of fewer than five suppliers per wafer specification.
- Substrate:Silicon carbide and sapphire substrates for power and optoelectronic applications require defect densities below 10^4 per square centimeter. Automotive-qualified SiC substrates trade at multiples of industrial-grade equivalents due to extended reliability testing protocols.
- Film:Sputtered or CVD-deposited thin films include barrier metals, dielectrics, and phase-change materials.
- Powder:High-purity ceramic and metal powders feed additive manufacturing and packaging applications.
Wafer commands margin concentration. Substrate is climbing the fastest in absolute dollar terms.
End User Industry:
Customer type determines volume scale and qualification velocity, with automotive imposing the longest certification timelines.
- Automotive:Functional safety requirements under ISO 26262 extend material qualification to 24-36 months for powertrain applications. German and Japanese OEMs are locking SiC substrate supply directly with SK Siltron and Wolfspeed to secure inverter ramp volumes.
- Consumer Electronics:Smartphone and wearable manufacturers drive 300mm silicon wafer consumption through foundry intermediaries. Apple and Samsung procurement teams coordinate quarterly volume forecasts with TSMC that transmit directly to Shin-Etsu and GlobalWafers.
- Telecommunications:5G infrastructure deployment sustains GaAs and InP substrate demand for millimeter-wave amplification.
- Industrial Automation:MEMS pressure and motion sensors penetrate factory automation and process control systems.
Consumer Electronics anchors volume scale. Automotive is gaining share fastest in value terms.
Technology:
Maturity curves separate legacy planar processes from advanced node architectures, with supply chains fragmenting accordingly.
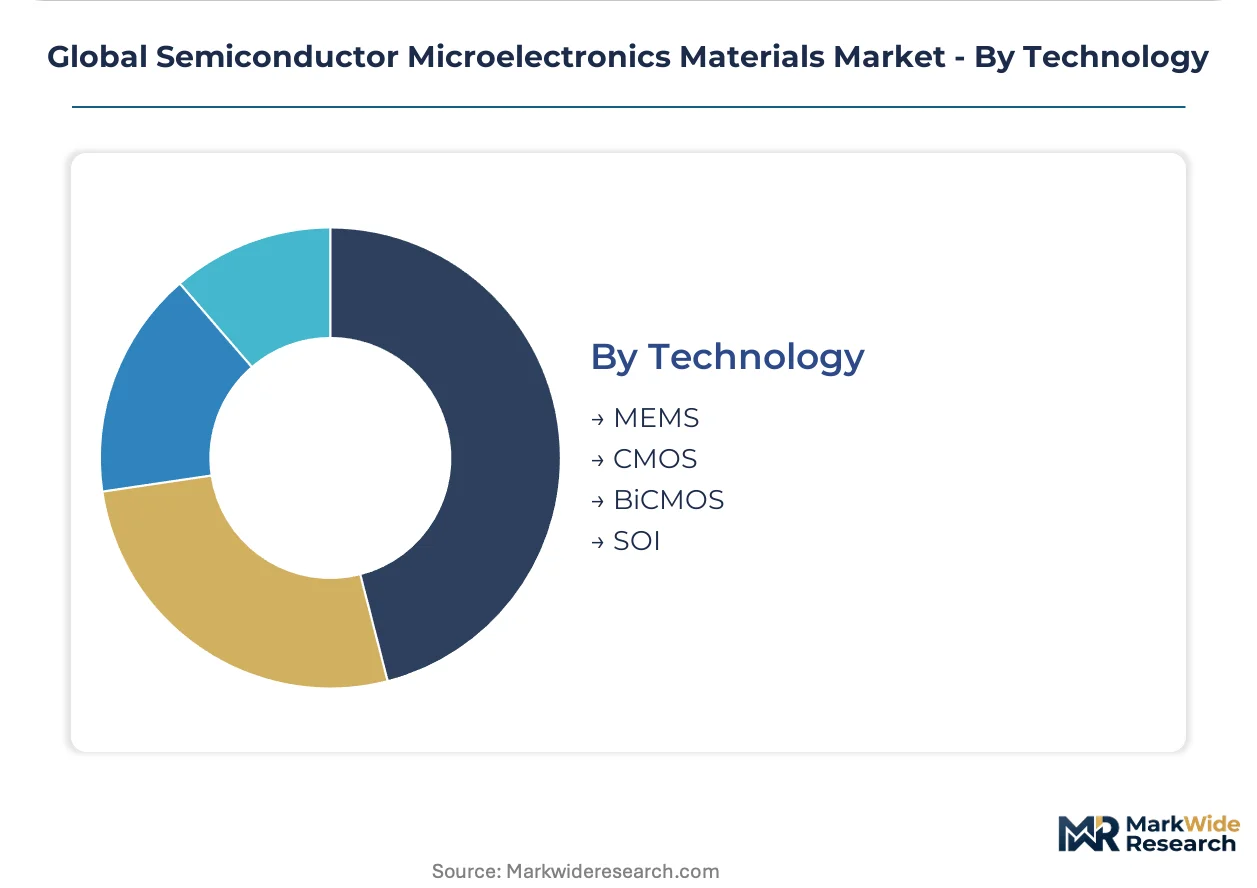
- CMOS:Complementary metal-oxide-semiconductor processing at 7nm and below requires extreme ultraviolet photoresists and atomic-layer deposition precursors with part-per-billion contamination control. Intel, Samsung, and TSMC operate captive supply qualification programs that exclude merchant generalists.
- MEMS:Microelectromechanical systems integrate mechanical structures with CMOS electronics for sensing and actuation. Bosch and STMicroelectronics dominate automotive pressure sensor production with in-house wafer fabrication.
- BiCMOS:Bipolar-CMOS integration serves mixed-signal applications in RF and power management.
- SOI:Silicon-on-insulator substrates reduce parasitic capacitance for RF and low-power logic.
CMOS dominates capital deployment. MEMS is where application expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Taiwan and South Korea absorb price premiums without volume elasticity, while European and North American purchasers negotiate harder on silicon carbide substrate costs amid supply scarcity.
United States
Intel's Arizona and Oregon fabrication complexes drive 300mm silicon wafer consumption at leading-edge nodes. EPA hazardous air pollutant standards elevate compliance costs for domestic chemical suppliers serving these fabs. Austin and Phoenix metro areas concentrate advanced packaging capacity for artificial intelligence accelerators.
Taiwan
TSMC's Hsinchu and Tainan Science Parks sustain premium pricing for extreme ultraviolet photoresists and atomic-layer deposition precursors. The island's national development fund coordinates strategic material stockpiles through direct procurement partnerships. Kaohsiung's emerging packaging cluster pulls silicon carbide demand from power electronics foundries.
South Korea
Samsung Electronics and SK Hynix operate captive qualification programs for sub-7nm materials that exclude merchant generalists. MFDS chemical safety regulations govern specialty gas handling protocols at Pyeongtaek and Icheon complexes. Yongin and Hwaseong city regions host the densest concentration of memory wafer fabrication globally.
Germany
Bosch and Infineon lock silicon carbide substrate supply directly for automotive inverter ramp volumes under ISO 26262 functional safety timelines. REACH perfluorinated compound restrictions force reformulation of etching chemistries at Dresden and Regensburg fabs. Saxony's Silicon Saxony cluster anchors European deposition equipment and specialty gas production.
Japan
Tokyo Electron and Shin-Etsu coordinate photoresist stockpile security measures through METI-directed supply allocation frameworks. JIS standards govern silicon wafer purity specifications for domestic logic and memory producers. Kyushu's Kumamoto and Oita prefectures concentrate 300mm epitaxial wafer and sputtering target manufacturing.
Global Semiconductor Microelectronics Materials Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in semiconductor microelectronics materials. Shin-Etsu Chemical and SUMCO control captive polysilicon refining through backward integration into crystal growth, while merchant specialists compete on formulation chemistry and regional proximity. Three archetypes dominate: integrated material suppliers with upstream feedstock control, process chemical specialists with node-specific formulation libraries, and compound semiconductor substrate houses with crystal growth yield expertise. Capacity expansion and long-term supply agreement locking represent the dominant competitive moves as foundry operators seek allocation certainty.
Within the integrated supplier tier, Shin-Etsu Chemical Co., Ltd. and Sumco Corporation exemplify the polysilicon-to-wafer control model that commands premium pricing in Taiwan and South Korea procurement channels. Among process chemical specialists, Dow Inc. and Entegris occupy positions defined by sub-7nm node formulation capabilities and hazardous materials handling compliance. SK Siltron represents the compound substrate archetype competing in silicon carbide boule growth where automotive qualification timelines create supply scarcity premiums.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Sumco Corporation |
| Dow Inc. |
| Kyocera Corporation |
| Entegris |
| Applied Materials, Inc. |
| SK Siltron |
| SUMITOMO CHEMICAL |
| BASF |
| Others |
Value Chain & Pricing Dynamics
ISO 26262 functional safety certification gates both silicon carbide substrate qualification and automotive-tier price premiums simultaneously, creating a bifurcated supply landscape where automotive-qualified material commands multiples over industrial-grade equivalents. Buyers in Taiwan and South Korea absorb price premiums without volume elasticity, while European and North American purchasers negotiate harder on substrate costs amid supply scarcity.
Pricing Analysis
Long-term supply agreements drive lifetime value more than spot transactions, with foundry operators locking multi-year volume commitments directly with Shin-Etsu and SK Siltron to secure allocation certainty. Contract-based long-term offtake dominates, with price differentiation resting on certification grade and volume scale. Cost compression in silicon carbide substrates is intensifying because crystal growth yield limitations constrain supply expansion despite electric vehicle pull. Automotive OEMs exhibit least price sensitivity due to ISO 26262 qualification timelines, while industrial-grade purchasers show highest elasticity.
Supply Chain Analysis
Boule processing bottlenecks in silicon carbide crystal growth tether supply expansion to furnace capacity additions in Taiwan, South Korea, and the United States. Polysilicon feedstock, high-purity gases, and photoresist chemistries draw from energy-intensive refining operations concentrated in East Asia. Single-source vulnerability runs through 300mm silicon wafer supply where fewer than five qualified vendors serve leading-edge logic fabs. Distribution runs through direct procurement partnerships between foundry operators and integrated material suppliers, bypassing merchant distributors for critical inputs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in switching costs: sub-7nm node qualification programs exclude merchant generalists and lock foundry operators into multi-year material supply relationships that resist displacement.
For Market Incumbents: Compound backward integration into polysilicon refining to defend margin position against energy cost volatility in metallurgical-grade silicon processing. Expand captive crystal growth capacity in Taiwan and South Korea to capture allocation certainty premiums from TSMC and Samsung. Lock extended photoresist supply agreements under Japan METI coordination frameworks before foreign material houses penetrate procurement partnerships.
For New Entrants and Emerging Players: Lead with silicon carbide substrate qualification for automotive inverter applications, where supply scarcity creates white-space entry opportunity despite extended ISO 26262 certification timelines. Target India's Gujarat Dholera fabrication zone development for greenfield material supply relationships under PLI scheme incentives. Pursue MEMS sensor material specialization as the fastest-growing technology segment with lower capital barriers than leading-edge CMOS.
For Investors and Strategic Acquirers: REACH perfluorinated compound emission deadlines reshape the acquisition landscape toward chemical specialists with reformulated etching chemistry libraries. Frame long-term viability around compound semiconductor substrate houses with demonstrated crystal growth yield expertise, as silicon carbide demand acceleration outpaces supply expansion across the projection horizon. Monitor Japan METI supply security measures as the signal for procurement partnership model shifts opening foreign material house access.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement Locking | TSMC and Samsung secure multi-year wafer allocation certainty from Shin-Etsu and SUMCO. |
| Backward Integration into Polysilicon | Shin-Etsu controls silicon wafer purity grades through captive metallurgical-grade refining. |
| Silicon Carbide Capacity Expansion | SK Siltron extends furnace capacity to meet automotive OEM inverter ramp volumes. |
| Photoresist Stockpile Coordination | Japan METI-directed allocation frameworks secure supply for Tokyo Electron and domestic fabs. |
| Green Chemistry Reformulation | Dow Inc. redesigns molecular architectures to meet REACH perfluorinated compound restrictions. |
Study Parameters
Cross-validation between primary interviews with fab procurement directors, R&D heads at material suppliers, and regulatory affairs leads anchors the qualitative findings. Secondary validation draws from SEC 10-K filings, Japan METI supply security reports, EU Chips Act implementation documents, and customs trade data for polysilicon and wafer flows. Bottom-up and top-down triangulation reconciles foundry capacity announcements with material supplier revenue disclosures.
Sensitivity analysis around crystal growth yield assumptions, electric vehicle inverter adoption curves, and sovereign semiconductor program capital deployment shapes the analytical framework. Segmentation dimensions span material chemistry, form factor, end-use industry, and process technology node across the analysis window. CAGRs derive from wafer shipment volumes, substrate pricing trajectories, and foundry capital expenditure cycles without explicit year anchoring.
Forecasts assume regulatory continuity in REACH perfluorinated compound implementation and Japan METI supply security coordination; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as export control expansions on deposition equipment and EU Chips Act capital redirection evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Polysilicon Market
Semiconductor Material
Germanium Market
Semiconductor Material
Tungsten Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Global Electronic Materials Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Indium Market
Semiconductor Material
Silicon Germanium Material Market