
 Silicon Carbide Ceramics Market | 2026-2036
Silicon Carbide Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Carbide Ceramics Market Outlook
The EU Green Deal is decoupling European industrial ceramic demand from legacy alumina-silicate supply chains by mandating lower process emissions in heavy manufacturing. Saint-Gobain leverages its vertically integrated raw material positions across France and Germany to sustain cost leadership in monolithic SiC components. Morgan Advanced Materials anchors its competitive position through specialized SiC-CMC formulations for aerospace turbine hot sections. CoorsTek differentiates via precision sintering capabilities that serve semiconductor equipment OEMs requiring sub-micron dimensional tolerances.
Silicon carbide ceramics are dense, covalently bonded ceramic materials produced through reaction bonding, sintering, or chemical vapor infiltration, typically achieving hardness values exceeding 25 GPa and thermal conductivity above 120 W/m·K, engineered for extreme-temperature structural, wear-resistant, and thermally conductive applications in hostile chemical environments. Monolithic SiC dominates current volume flows across refractory and mechanical seal applications where material homogeneity simplifies quality certification, while composite architectures, particularly SiC fiber-reinforced variants, represent the fastest-expanding margin pool as defense contractors qualify ceramic matrix composites for hypersonic leading edges and next-generation turbine vanes. Electronics applications are concentrating procurement around chemical vapor deposited SiC coatings for wafer handling components, where purity thresholds below 5 ppm metallic contamination command substantial price premiums over industrial-grade alternatives.
The EPA's National Emission Standards for Hazardous Air Pollutants constrain refractory manufacturing in the United States, pushing foundries toward longer-life SiC kiln furniture that reduces replacement frequency and associated downtime emissions. REACH registration requirements in Europe enforce full material disclosure across SiC precursor supply chains, elevating compliance costs for importers while advantaging producers with established substance dossiers. China's GB standards for advanced ceramics, administered by SAMR, mandate specific fracture toughness thresholds for structural SiC components used in nuclear and aerospace applications, creating a bifurcated certification landscape that stakeholders must navigate when qualifying suppliers across jurisdictions. Procurement teams should monitor evolving cross-border carbon border adjustment mechanisms, as embedded emissions in energy-intensive ceramic sintering processes will increasingly influence supplier selection and total cost of ownership calculations.
Market Dynamics
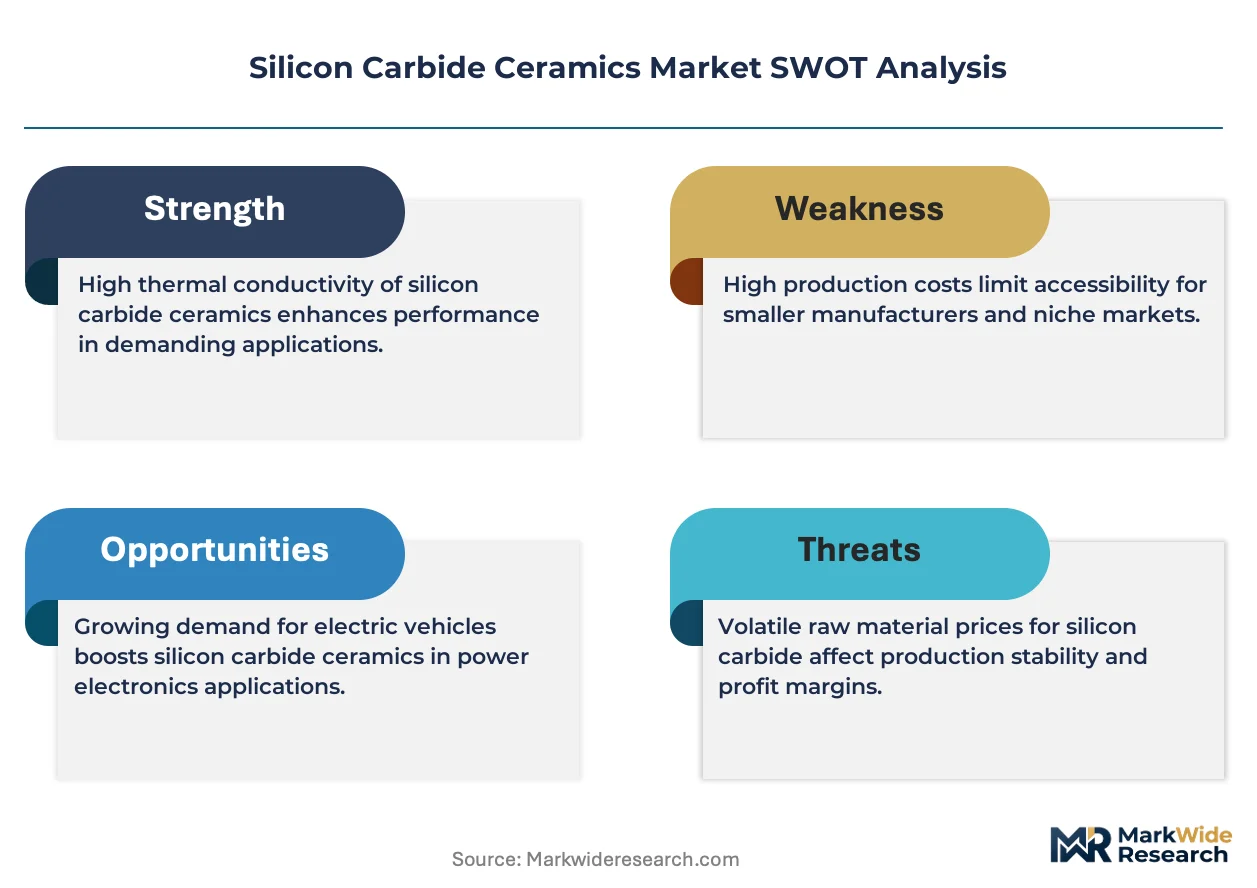
The central structural force reshaping silicon carbide ceramics is the voltage architecture transition in electric vehicle power electronics, which is concentrating procurement around 800V battery systems that demand thermally stable ceramic substrates capable of sustaining higher switching frequencies.
Growth Catalysts
- EU Green Deal industrial benchmarks:German and French steel foundries face mandated emissions reductions that accelerate substitution of alumina-silicate refractories with longer-life SiC kiln furniture.
- Semiconductor fabrication clustering:Domestic wafer processing equipment makers around Shanghai are qualifying local SiC ceramic supply chains to reduce import dependency.
- Hypersonic defense programs:SiC fiber-reinforced ceramic matrix composites are gaining qualification priority for leading edges and turbine vanes in next-generation aerospace applications.
Market Restraints
- Petroleum coke price volatility:High-purity carbon precursor costs fluctuate with oil refining economics, compressing margins for reaction-bonded SiC producers.
- Chinese supply concentration:Over 60% of metallurgical-grade silicon feedstock originates from specific industrial zones in Henan and Ningxia provinces, creating geographic single-point vulnerability.
- Energy-intensive sintering requirements:Achieving full density demands sustained temperatures above 2,000°C, exposing producers to electricity price spikes and carbon border adjustment exposure.
Strategic Opportunities
- India's PLI scheme for semiconductors:Domestic fab construction incentives create first-mover advantage for SiC ceramic component suppliers establishing local technical support.
- Fusion reactor first-wall applications:ITER and private fusion ventures are evaluating SiC-SiC composites for plasma-facing components requiring extreme thermal shock resistance.
- Direct-to-equipment OEM digital channels:Semiconductor capital equipment makers are consolidating vendor bases through integrated procurement platforms that bypass traditional distributor markups.
Industry Challenges
- Cross-jurisdictional certification complexity:China's GB standards for nuclear-grade SiC fracture toughness diverge from ASME Boiler and Pressure Vessel Code requirements, forcing dual qualification investments.
- Specialized sintering furnace scarcity:Hot isostatic pressing capacity for sub-micron tolerance components concentrates among a handful of European and Japanese equipment operators.
- Metallic contamination control:Semiconductor wafer handling applications demand purity below 5 ppm, requiring dedicated production lines isolated from industrial-grade ceramic manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Carbide Ceramics Market |
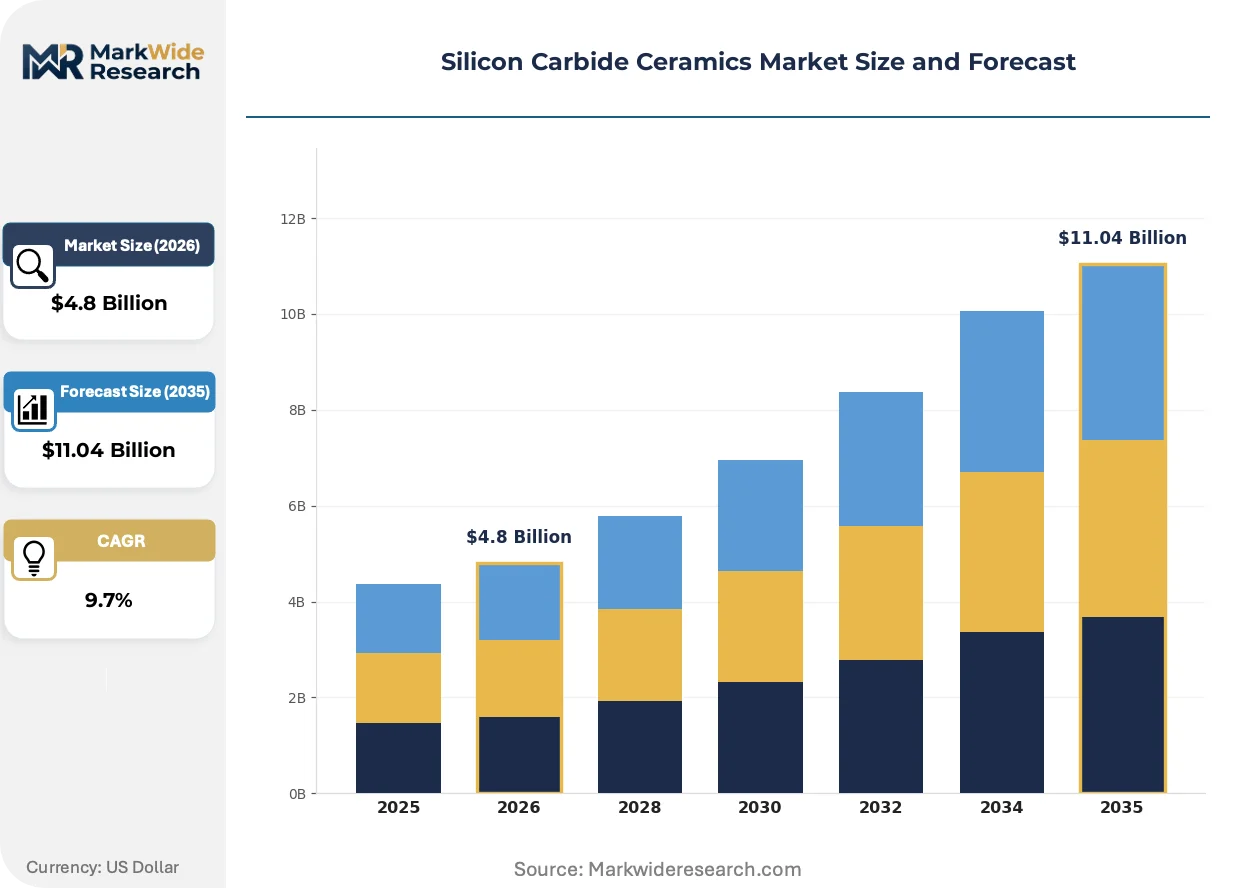
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monolithic, Composite, Coated, SiC-based Application: Aerospace, Defense, Automotive, Electronics End User: Manufacturers, Research Institutes, Defense Contractors, Suppliers Distribution Channel: Direct Sales, Online Retail, Distributors, Agents |
| Companies Covered | Saint-Gobain, Morgan Advanced Materials, CoorsTek, CeramTec GmbH, Schunk Ingenieurkeramik, Imerys, 3M Company, NGK Insulators, KYOCERA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Carbide Ceramics Market Strategic Shifts
Active transformation in silicon carbide ceramics centers on manufacturing precision upgrades, regulatory emissions frameworks, and procurement consolidation among semiconductor capital equipment buyers.
Chemical vapor infiltration is rewriting production economics for complex-shaped SiC components. This process deposits silicon carbide matrix material within fiber preforms at temperatures below conventional sintering thresholds. Aerospace contractors including turbine OEMs are adopting CVI-produced CMC shrouds at accelerating qualification cycles. The technology is compressing lead times for geometrically complex hot-section components from months to weeks.
REACH registration requirements enforce full material disclosure across SiC precursor supply chains throughout Europe. ECHA substance dossier obligations elevate compliance costs for importers lacking established registration histories. Industrial ceramic distributors serving German foundries are consolidating supplier bases toward producers with complete SVHC documentation, squeezing smaller trading operations.
Semiconductor equipment OEMs are unbundling after-sales service contracts from component supply agreements. Buyers now negotiate separate technical support and spare parts provisioning, forcing SiC ceramic suppliers to build direct field service capabilities. This pattern concentrates most visibly in South Korea, where Samsung and SK Hynix fab expansions demand localized technical response teams.
Silicon Carbide Ceramics Market Segmentation
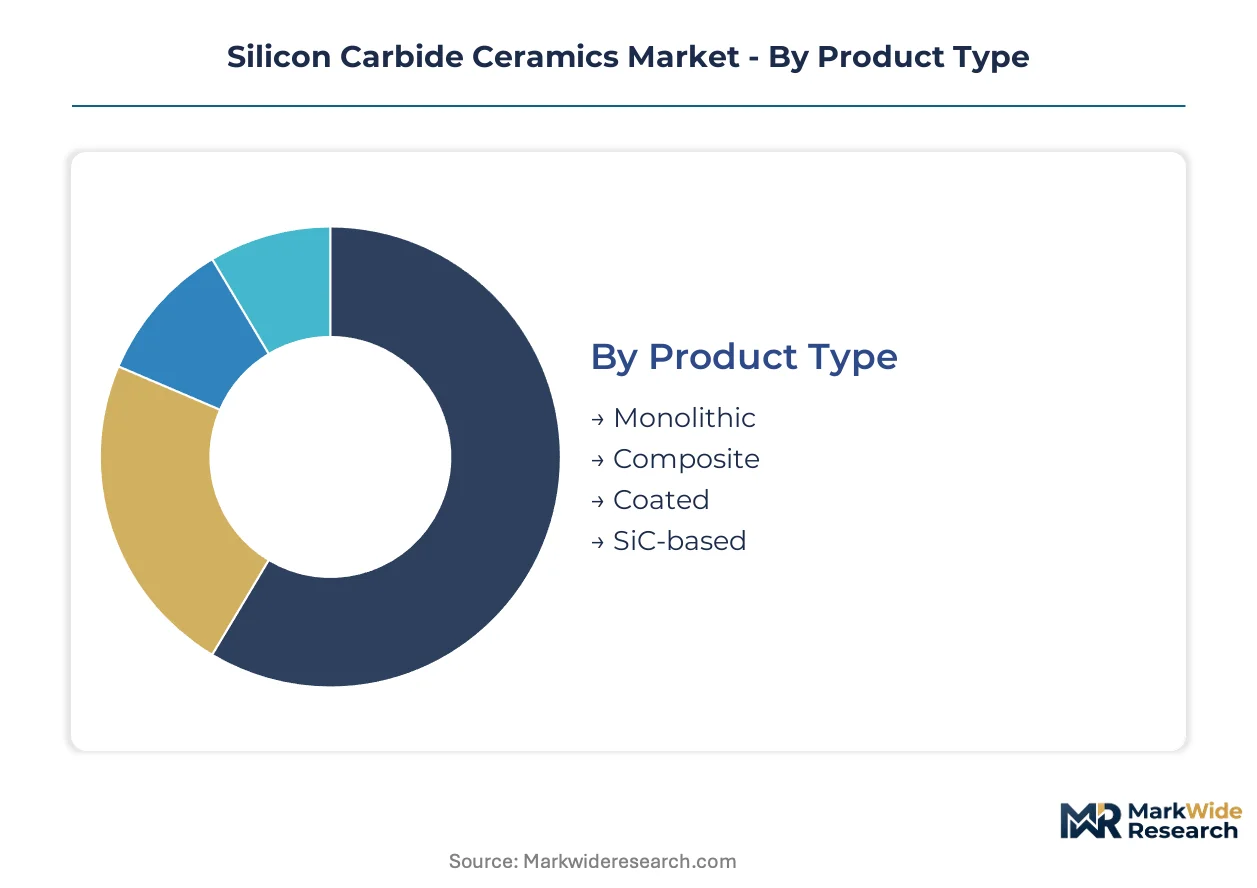
Silicon carbide ceramics serve divergent performance requirements across industrial refractories, semiconductor equipment, and aerospace propulsion. Procurement teams segment supply by material architecture, application severity, and certification grade to align supplier capabilities with end-use specifications.
Product Type:
Replacement cycles vary dramatically by material architecture, with monolithic components degrading predictably under thermal shock while composite structures demand condition-based monitoring.
- Monolithic:Homogeneous bulk SiC achieves hardness exceeding 25 GPa through pressureless sintering or reaction bonding. German steel foundries specify monolithic kiln furniture for blast furnace linings under EU Green Deal emissions benchmarks mandating longer service intervals.
- Composite:SiC fiber-reinforced ceramic matrix composites combine woven preforms with chemical vapor infiltrated matrices. Defense contractors in the United States and France qualify SiC-CMC turbine vanes and hypersonic leading edges where thermal shock resistance exceeds monolithic limits.
- Coated:Chemical vapor deposited SiC layers provide sub-micron purity surfaces for wafer handling components in semiconductor fabs around Shanghai.
- SiC-based:Blended formulations incorporating secondary phases like titanium diboride target specific electrical or tribological properties for mechanical seal faces.
Volume placements concentrate in Monolithic; the faster expansion belongs to Composite.
Application:
Application severity determines specification stringency, with semiconductor and aerospace buyers imposing purity and traceability requirements that industrial refractory customers rarely match.
- Aerospace:Turbine hot-section components operate above 1,200°C in oxidizing environments. GE Aviation and Rolls-Royce qualification programs for SiC-CMC shrouds drive process standardization across their supply bases.
- Defense:Hypersonic vehicle leading edges and rocket nozzle throats demand ablation-resistant ceramics. DARPA and French DGA programs accelerate fiber architecture development for Mach 5+ flight envelopes.
- Automotive:800V electric vehicle inverters require thermally stable ceramic substrates for power module packaging. BYD and Hyundai Motor Group procurement teams are qualifying domestic SiC ceramic suppliers to reduce lead times.
- Electronics:Wafer processing equipment uses high-purity SiC for susceptors, rings, and showerheads. Samsung and SK Hynix fab expansions in South Korea concentrate demand for metallic contamination below 5 ppm.
Procurement weight tilts toward Electronics for premium pricing; Defense applications show the steepest expansion trajectory as hypersonic programs mature.
End User:
End-user technical sophistication shapes supplier engagement models, with defense contractors and research institutes driving specification development that later diffuses to commercial manufacturers.
- Manufacturers:Industrial ceramic fabricators and OEM component shops purchase standard grades for mechanical seals, bearings, and refractory shapes. Chinese metallurgical-grade SiC feedstock from Henan and Ningxia provinces supplies this tier.
- Research Institutes:National laboratories and university consortia evaluate novel SiC fiber architectures and matrix densification methods. ITER and private fusion ventures assess SiC-SiC composites for plasma-facing first-wall applications.
- Defense Contractors:Prime aerospace and missile systems integrators impose AS9100 and ITAR compliance on ceramic suppliers. Raytheon and Northrop Grumman qualification cycles for CMC components run 18-36 months.
- Suppliers:Tier-2 material processors and specialty distributors serve fragmented demand from small-scale industrial users. REACH registration requirements in Europe force consolidation toward ECHA-compliant producers.
Transaction frequency peaks with Manufacturers; specification authority rests with Defense Contractors.
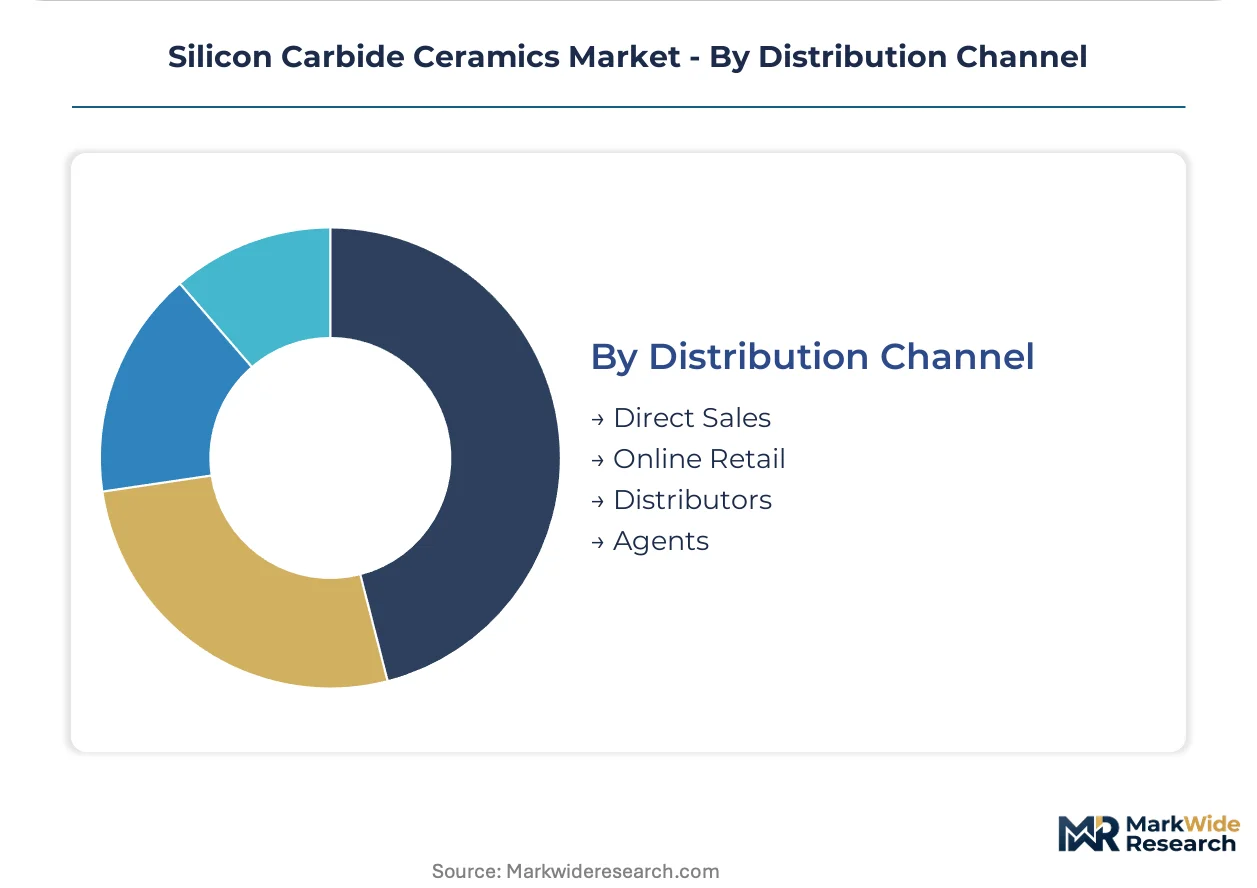
Distribution Channel:
Channel selection reflects buyer scale and technical support requirements, with large semiconductor and aerospace OEMs disintermediating traditional distributors.
- Direct Sales:Field application engineers negotiate specifications, qualification protocols, and long-term supply agreements. CoorsTek and Saint-Gobain maintain direct technical teams at major semiconductor capital equipment makers.
- Online Retail:Standard-grade powders, crucibles, and abrasive grains move through industrial e-commerce platforms. Small machine shops and academic researchers source prototype quantities without minimum order constraints.
- Distributors:Regional industrial ceramic specialists stock common refractory shapes and mechanical seal faces. German foundry suppliers consolidate toward distributors with complete SVHC documentation under REACH.
- Agents:Commissioned representatives bridge language and regulatory gaps for exporters entering unfamiliar jurisdictions. Japanese SiC ceramic producers rely on agents for initial penetration of Indian semiconductor fabrication projects.
Revenue concentration favors Direct Sales; Online Retail expands fastest for standard-grade consumables.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in China and Japan while consumption concentrates in German automotive and South Korean semiconductor fabs. This geographic split creates freight-heavy supply chains and tariff exposure for ceramic substrate shipments. Regional regulatory divergence on carbon emissions and material purity is fragmenting qualification standards.
China
Metallurgical-grade silicon feedstock originates from industrial zones in Henan and Ningxia provinces, supplying both domestic refractory makers and export markets. SAMR-administered GB standards mandate specific fracture toughness thresholds for nuclear and aerospace-grade SiC components. The semiconductor fabrication cluster around Shanghai is qualifying local SiC ceramic supply chains to reduce import dependency from Japanese and European suppliers.
Germany
Steel foundries in the Ruhr and Saar regions face EU Green Deal emissions benchmarks that accelerate substitution of alumina-silicate refractories with longer-life SiC kiln furniture. REACH registration requirements enforce full material disclosure across precursor supply chains, advantaging producers like Saint-Gobain with established ECHA substance dossiers. Bavarian precision ceramics specialists serve semiconductor capital equipment OEMs requiring sub-micron dimensional tolerances.
United States
EPA National Emission Standards for Hazardous Air Pollutants constrain refractory manufacturing, pushing foundries toward SiC kiln furniture that reduces replacement frequency and downtime emissions. Defense contractors in California and Virginia qualify SiC fiber-reinforced ceramic matrix composites for hypersonic leading edges under DARPA programs. The Department of Energy supports SiC-SiC composite evaluation for fusion reactor first-wall applications at national laboratories.
Japan
Hot isostatic pressing capacity for sub-micron tolerance components concentrates among specialized equipment operators serving semiconductor wafer handling applications. METI industrial policy supports domestic qualification of SiC ceramic substrates for 800V electric vehicle inverters. Kyushu-based producers supply high-purity CVD-SiC coatings for Samsung and SK Hynix fab expansions in South Korea.
South Korea
Samsung and SK Hynix fab expansions in the Seoul Capital Area and Busan-Ulsan corridor concentrate demand for metallic contamination below 5 ppm. Domestic procurement teams are qualifying local SiC ceramic suppliers to reduce lead times from Japanese sources. MFDS pharmaceutical-grade material standards indirectly elevate purity expectations for ceramic components used in advanced packaging equipment.
Silicon Carbide Ceramics Market Competitive Environment
The competitive structure tilts toward vertically integrated material specialists with captive raw material positions. Three tiers separate premium precision ceramics producers from industrial refractory suppliers and regional trading operations. Strategic moves concentrate on backward integration into high-purity silicon and carbon precursors, plus geographic co-location with semiconductor fabrication clusters to bypass distributor markups.
Among European integrated producers, Saint-Gobain and Morgan Advanced Materials occupy positions spanning monolithic refractories through fiber-reinforced composites. Saint-Gobain leverages its French and German raw material positions for cost leadership in kiln furniture, while Morgan Advanced Materials exemplifies the specialized CMC formulation archetype for aerospace turbine applications. Japanese precision ceramics producers including NGK Insulators and KYOCERA Corporation represent the contamination-controlled tier serving semiconductor equipment OEMs with dedicated production lines isolated from industrial-grade manufacturing.
| Leading Market Players |
|---|
| Saint-Gobain |
| Morgan Advanced Materials |
| CoorsTek |
| CeramTec GmbH |
| Schunk Ingenieurkeramik |
| Imerys |
| 3M Company |
| NGK Insulators |
| KYOCERA Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Germany and Japan anchor supply discipline through long-tenured technical management that resists commoditization pressure. Their captive sintering furnace positions translate into pricing power over semiconductor equipment buyers facing qualification delays from alternative sources.
Pricing Analysis
Cost-down pressure on industrial-grade monolithic SiC accelerates because Chinese metallurgical feedstock from Henan and Ningxia provinces floods standard refractory tiers. Three-tier pricing structure across semiconductor-grade, aerospace-certified, and industrial refractory levels separates contamination-controlled CVD coatings from reaction-bonded kiln furniture. Saint-Gobain and Morgan Advanced Materials defend premium positioning through ECHA-compliant REACH dossiers that smaller importers cannot replicate. Electronics buyers at Samsung and SK Hynix fabs show least price sensitivity, while German steel foundries under EU Green Deal emissions mandates drive hardest bargain on replacement-cycle extensions.
Supply Chain Analysis
China's GB standards for nuclear-grade SiC fracture toughness reshape sourcing toward domestic SAMR-certified producers in Shanghai fabrication clusters. Metallurgical-grade silicon concentrates in Henan and Ningxia provinces, while hot isostatic pressing capacity for sub-micron tolerance components clusters in Japan and Germany. Petroleum coke price volatility from oil refining economics creates margin compression risk for reaction-bonded SiC producers. Distribution runs through direct technical sales teams at CoorsTek and Saint-Gobain for semiconductor OEMs, with regional distributors serving fragmented foundry demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hot isostatic pressing furnace scarcity concentrates capability among European and Japanese operators, propping pricing for sub-micron tolerance components across the analysis window.
For Market Incumbents: Acquire specialized sintering furnace capacity in South Korea and Bavaria to anchor supply security for semiconductor equipment OEMs. Backward integration into high-purity carbon precursors defends margin position against petroleum coke volatility. Certification investment for China's GB nuclear-grade fracture toughness thresholds blocks emerging domestic competitors from aerospace qualification pipelines. For New Entrants and Emerging Players: Direct-to-equipment-OEM digital procurement platforms offer bypass routes around entrenched distributor relationships in Indian and Southeast Asian fab construction markets. India's PLI scheme for semiconductors presents the most penetrable entry point for technical ceramic suppliers establishing localized field service. Technical partnership with domestic wafer processing equipment makers accelerates qualification timelines versus direct OEM pursuit. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision ceramics specialists with existing ECHA REACH dossiers in German industrial corridors. Five-to-ten-year viability hinges on carbon border adjustment mechanism exposure in energy-intensive sintering operations. Watch EU Green Deal industrial emissions benchmark tightening as inflection signal for refractory substitution acceleration toward longer-life SiC kiln furniture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Precursors | Captive petroleum coke and silicon supply shields margins from oil refining volatility. |
| Hot Isostatic Pressing Capacity Expansion | Additional furnace installations in Kyushu and Bavaria relieve sub-micron component bottlenecks. |
| China GB Standards Certification | SAMR fracture toughness approval opens nuclear and aerospace procurement pipelines. |
| Direct Digital Procurement Channel | Equipment OEM platform integration bypasses distributor markups in semiconductor capital spending. |
| Localized Technical Service Buildout | Field engineering presence in Seoul Capital Area meets Samsung and SK Hynix response requirements. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs across the silicon carbide ceramics value chain. Primary interviews with sintering furnace operators, semiconductor equipment procurement managers, foundry maintenance directors, and aerospace CMC qualification engineers combined with ECHA substance dossier reviews and SAMR GB standard documentation. SEC 10-K disclosures from listed ceramic producers and METI industrial policy white papers provided additional validation. Bottom-up capacity estimates triangulated against top-down consumption models across refractory, electronics, and aerospace end-uses.
Data-stream reconciliation aligned production capacity surveys with import-export trade flows and OEM procurement disclosure patterns. Segmentation modeling spanned material architecture, application severity, certification grade, and regional regulatory cluster dimensions. CAGRs derived from regression analysis against electric vehicle inverter deployment trajectories and semiconductor fab construction pipelines. Fusion reactor first-wall evaluation timelines and hypersonic defense program qualification cycles supplied industry-specific scenario inputs.
Inputs from ECHA REACH registration databases and SAMR certification bulletins were available through the study window; gaps in private CMC process yield data introduce uncertainty bands around composite volume forecasts. Petroleum coke price volatility and cross-border carbon adjustment mechanism implementation timing represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Gallium Market
Semiconductor Material
Yttrium Oxide Market
Semiconductor Material
Europe Silicon Carbide Market
Semiconductor Material
Semiconductor Glass Wafer Market
Semiconductor Material
Global Electronic Materials Market
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Silicon Hydride Market
Semiconductor Material
Semiconductor Glass Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Yttrium Market
Semiconductor Material
Semiconductor Silicon Wafer Market