
 Germanium Market | 2026-2036
Germanium Market Size, Share, and Industry Trends Forecast 2026-2036
Germanium Market Analysis
Defense infrared system integrators is reorganizing procurement priorities toward high-purity germanium substrates for thermal imaging arrays. Teck Resources Limited leverages vertical integration from zinc smelting byproduct recovery through refined metal output. Umicore sustains European supply continuity via its Hoboken refining complex and electronics-grade purification lines. Yunnan Chihong Zinc & Germanium Co., Ltd. dominates mined concentrate output and controls access to China's largest primary germanium reserves.
Germanium is a lustrous, brittle metalloid extracted primarily as a byproduct of zinc ore processing, with electronic-grade material demanding purity levels exceeding 99.9999% for semiconductor and fiber-optic applications. Its primary industrial purpose centers on infrared transparency and efficient charge carrier mobility, making it irreplaceable in night-vision optics and high-speed electronics. High-purity germanium leads value capture due to exacting refining costs and defense certification requirements, while germanium dioxide grows fastest as submarine cable deployment accelerates across Pacific routes. Electronic grade commands the widest margin pool because telecommunications and aerospace buyers lock in long-term offtake at premium pricing.
China's MIIT governs export quota allocations and strategic stockpile releases, directly constraining non-Chinese buyers' access to raw concentrate. The EPA and OSHA in the United States enforce workplace exposure limits and waste discharge standards for germanium tetrachloride handling at refining and epitaxy facilities. REACH registration requirements in Europe compel importers to document full supply chain substance volumes and toxicity profiles. Stakeholders must monitor whether Beijing expands export licensing to germanium dioxide and tetrachloride derivatives, as this would force Western optics manufacturers to accelerate recycling partnerships or alternative material qualification programs.
Market Dynamics
China's MIIT export licensing regime is compressing spot availability for non-Chinese buyers while concentrating supply flows toward domestic solar and semiconductor foundries. This regulatory chokepoint is forcing Western defense contractors and fiber-optic cable builders to reconfigure procurement strategies around recycling partnerships and long-term offtake agreements.
Growth Catalysts
- Submarine cable deployment:Trans-Pacific fiber-optic route expansion is accelerating germanium tetrachloride consumption for erbium-doped fiber amplifiers. Installation contractors are locking in multi-year chemical supply contracts.
- Defense thermal imaging mandates:NATO member states are expanding infrared optics procurement for armored vehicle and airborne platforms. High-purity germanium substrates remain the only viable window material for long-wave detection arrays.
- REACH registration completion:ECHA substance dossier finalization has clarified import compliance pathways for European compound semiconductor foundries. Electronics-grade importers now operate under documented toxicity profiles.
Market Restraints
- Concentrate supply concentration:Over 80% of mined germanium originates as zinc smelting byproduct from Chinese state-controlled refiners. Spot market access for non-Chinese buyers remains subject to MIIT quota allocation.
- Refining energy intensity:Zone refining and Czochralski crystal growth consume substantial electricity inputs. European smelters face cost pressure from F-Gas Regulation compliance and carbon border adjustment exposure.
- Gallium arsenide substitution:III-V compound semiconductors are capturing share in certain high-frequency applications where germanium historically dominated. RF component designers are qualifying alternative substrate materials.
Strategic Opportunities
- Urban mining infrastructure:End-of-life fiber-optic cable and decommissioned infrared optics represent underexploited feedstock streams. Germanium recovery from manufacturing scrap currently yields sub-30% of theoretical recoverable metal.
- Space-based solar concentrators:Multi-junction photovoltaic arrays for satellite power systems specify germanium substrates for lattice-matched epitaxy. Launch schedule acceleration is creating new demand verticals.
- US IRA critical minerals designation:Defense Production Act invocation and Inflation Reduction Act tax credits are incentivizing domestic refining capacity construction. Project developers are securing offtake commitments from military system integrators.
Industry Challenges
- Zone refining technician scarcity:Operational expertise in high-purity metal purification is concentrated among retiring specialists at legacy refiners. Training pipelines for semiconductor-grade material processing remain underdeveloped.
- Dual-use export classification complexity:ITAR and EAR jurisdiction determinations for infrared optics create compliance timeline uncertainty. Defense contractors face extended qualification periods for international subsystem suppliers.
- Epitaxy reactor integration:Silicon-germanium device fabrication requires precise lattice matching and defect density control. Foundry engineers report yield compression during process node transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germanium Market |
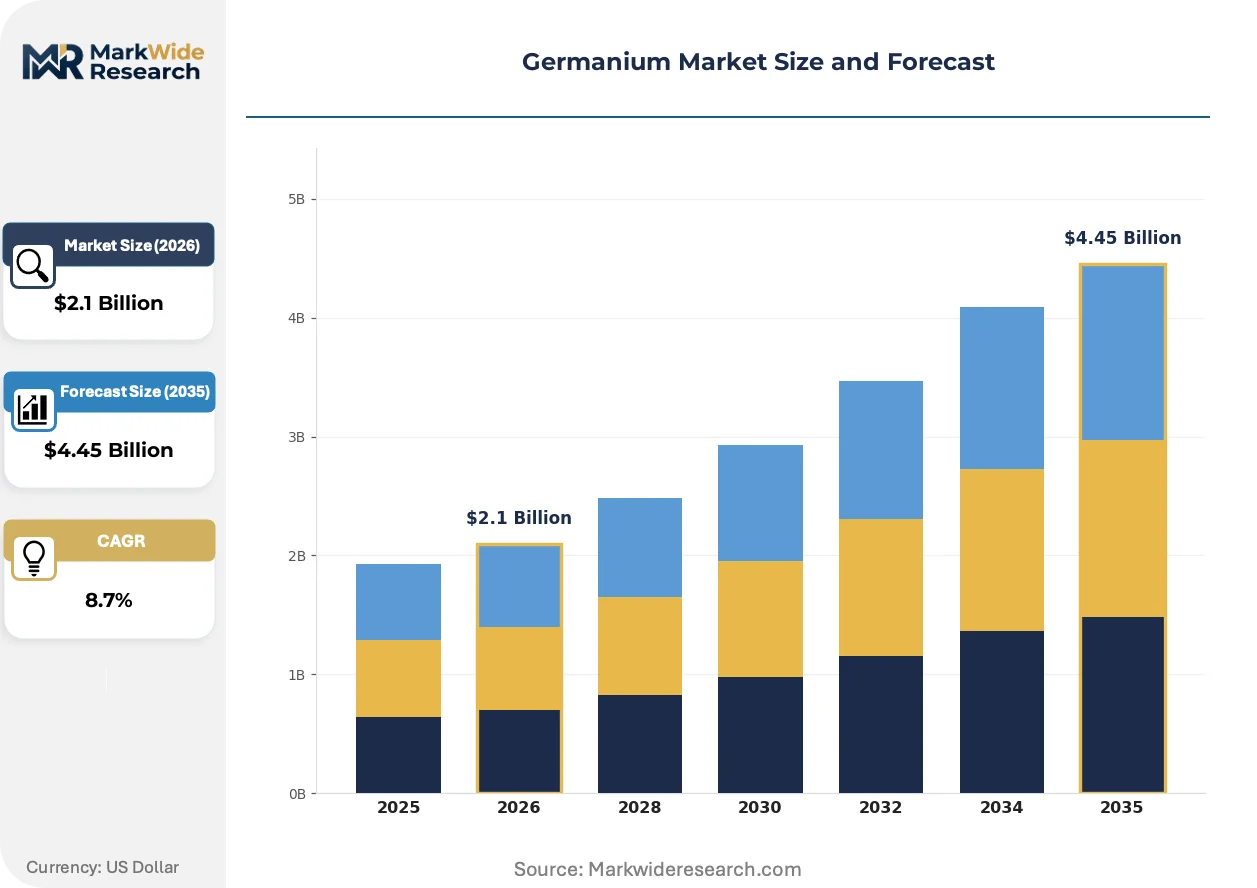
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Germanium Dioxide, Germanium Tetrafluoride, High-Purity Germanium, Germanium Alloys Application: Optical Fibers, Electronics, Solar Cells, Infrared Optics End User: Telecommunications, Aerospace, Defense, Consumer Electronics Grade: Electronic Grade, Reagent Grade, Metallurgical Grade, Others |
| Companies Covered | 5N Plus, Indium Corporation, Teck Resources Limited, American Elements, PPM Pure Metals GmbH, Umicore, China Germanium Co., Ltd., AXT, Inc., Yunnan Chihong Zinc & Germanium Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germanium Market Emerging Trajectories
Zone-refined single-crystal germanium is supplanting polycrystalline alternatives in demanding optical applications. Regulatory pressure on supply chain provenance is accelerating closed-loop material tracking. Procurement patterns are consolidating around vertically integrated compound semiconductor foundries with captive refining capabilities.
Zone-refined boules grown by the Czochralski method now dominate thermal imaging substrate procurement. Defense system integrators in the United States and Germany specify single-crystal material for night-vision goggle and targeting pod windows. This material upgrade is supplanting lower-grade feedstock in applications where optical transmission uniformity determines system performance.
REACH substance volume reporting requirements are forcing importers to document full supply chain provenance for germanium tetrachloride and dioxide derivatives. ECHA enforcement actions against undocumented shipments have prompted European optics manufacturers to establish certified recycling partnerships. Electronics-grade compounders now face mandatory toxicity profile disclosure that increases compliance overhead but reduces regulatory uncertainty.
Long-term offtake contracting is displacing spot market purchasing among major fiber-optic cable builders. Corning and Prysmian have secured multi-year chemical supply agreements directly with Chinese smelters and Western refiners. This procurement consolidation is most visible in trans-Pacific submarine cable projects where material availability risk outweighs price optimization incentives.
Germanium Market Segmentation

Germanium's value chain splits across chemical intermediates, refined metal, and engineered substrates, each flowing through distinct procurement channels. Defense contractors and fiber-optic cable builders source through divergent supply routes, creating segmentation logic that shapes pricing, lead times, and regulatory exposure.
Product Type:
Channel mix varies sharply: high-purity metal moves through direct mill contracts to defense primes, while chemical derivatives flow via distributors to fiber-optic compounders and solar cell manufacturers.
- Germanium Dioxide:White crystalline powder serving as precursor for germanium tetrachloride synthesis and direct feedstock for certain optical glass formulations. Demand concentrates with submarine cable deployment contractors across Pacific routes, where erbium-doped fiber amplifier production consumes bulk chemical volumes. REACH registration requirements in Europe constrain spot purchasing flexibility.
- High-Purity Germanium:Zone-refined metal exceeding 99.9999% purity, fabricated into single-crystal boules via Czochralski growth. Procurement locks into multi-year offtake agreements with aerospace and defense system integrators in the United States and Germany, where ITAR jurisdiction adds compliance overhead.
- Germanium Tetrafluoride:Gaseous compound employed in plasma etching processes and specialty optical fiber doping. Japanese semiconductor equipment manufacturers represent concentrated demand nodes.
- Germanium Alloys:Silicon-germanium mixtures and other metallurgical blends for lattice-matched epitaxy substrates. Compound semiconductor foundries in East Asia drive specification requirements.
By volume, Germanium Dioxide leads. By growth pace, High-Purity Germanium is climbing the fastest.
Application:
Cost tier stratification separates defense-certified infrared optics from commodity fiber-optic chemical consumption, with solar applications occupying a mid-tier position on purity requirements and pricing.
- Infrared Optics:Thermal imaging windows and lenses exploiting germanium's transparency to long-wave infrared radiation. NATO armored vehicle and airborne platform programs in the United States and Germany lock in premium-priced substrate supply. MIIT export licensing from China compresses non-Chinese buyer access.
- Optical Fibers:Erbium-doped fiber amplifiers for signal regeneration in trans-Pacific submarine cables. Installation contractors at Prysmian and Corning secure multi-year chemical supply contracts directly with Chinese smelters and Western refiners.
- Electronics:Silicon-germanium heterojunction bipolar transistors for high-frequency RF applications. 5G base station deployment and satellite communications drive specification evolution.
- Solar Cells:Multi-junction photovoltaic substrates for space-based power systems. Launch schedule acceleration at satellite manufacturers creates new demand verticals.
Defense procurement commands the widest margin pool. Fiber-optic chemical volumes are expanding most quickly.
End User:
Customer type determines contract structure: defense primes negotiate cost-plus long-term supply, while telecommunications carriers bid competitive tenders for cable project chemicals.
- Defense:Thermal imaging array integrators and night-vision goggle manufacturers specifying single-crystal germanium windows. United States and German system houses dominate procurement, with ITAR and EAR jurisdiction creating compliance timeline uncertainty for international subsystem suppliers.
- Telecommunications:Submarine cable installation consortia and terrestrial fiber network builders. Trans-Pacific route expansion accelerates germanium tetrachloride consumption, with procurement consolidating around vertically integrated compounders.
- Aerospace:Satellite power system manufacturers specifying germanium substrates for multi-junction photovoltaic arrays. Lattice-matched epitaxy requirements drive substrate qualification protocols.
- Consumer Electronics:Limited penetration in mainstream devices; niche applications in specialized imaging sensors.
Defense absorbs the highest-purity material volumes. Telecommunications chemical demand is gaining share fastest.
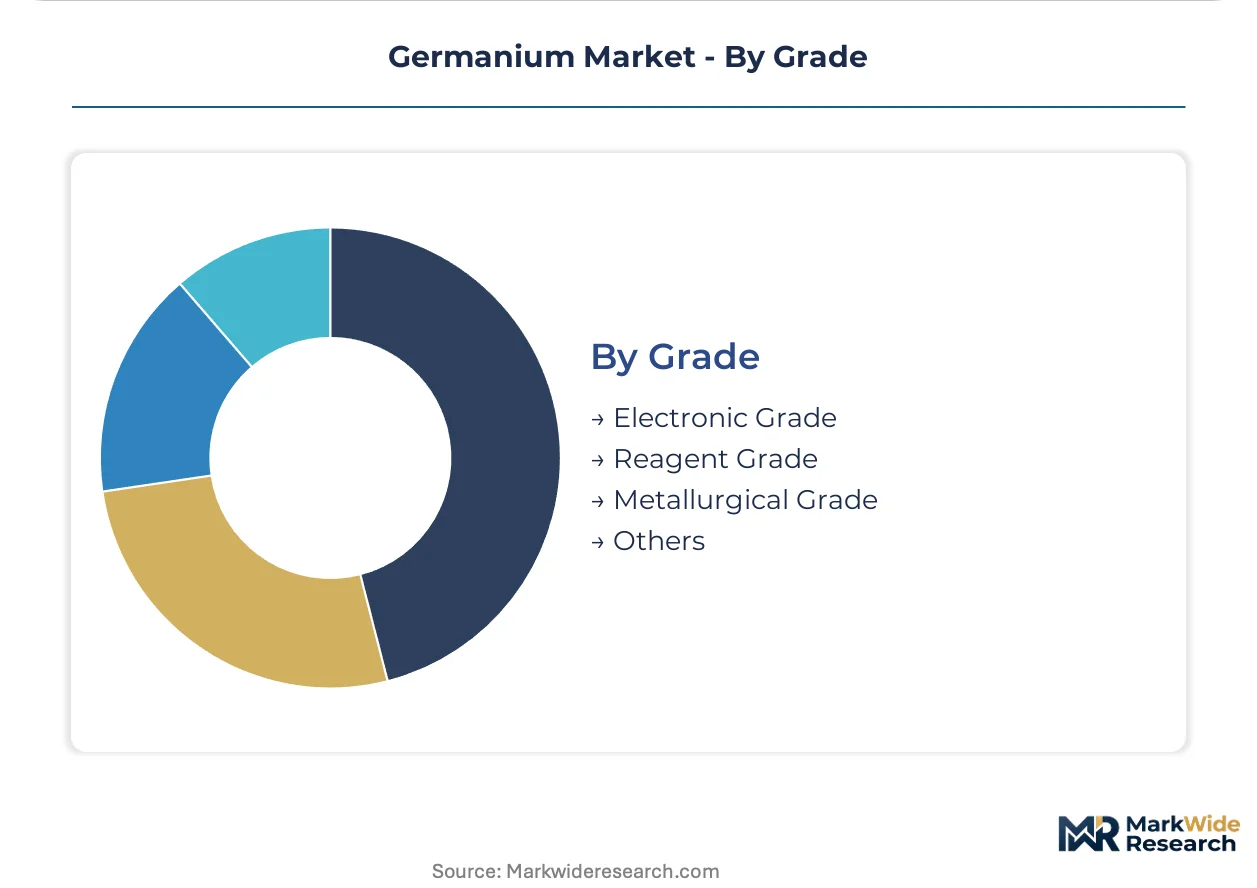
Grade:
Margin structure inverts across grades: electronic-grade purification costs dominate value capture, while metallurgical-grade material serves price-sensitive alloying applications.
- Electronic Grade:Purity levels exceeding 99.9999% for semiconductor and fiber-optic epitaxy applications. Hoboken refining complex in Belgium and Chinese state-controlled facilities supply European and Asian foundry clusters. Zone refining technician scarcity constrains capacity expansion.
- Metallurgical Grade:Lower-purity metal for alloying and chemical precursor production. Zinc smelting byproduct recovery at Teck Resources and Yunnan Chihong dominates feedstock origination.
- Reagent Grade:Laboratory and analytical chemistry applications with moderate volume requirements.
- Others:Specialty specifications for research and emerging applications.
Electronic Grade captures the widest margin pool. Metallurgical Grade supplies the largest volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese concentrate exports feed refining complexes in Belgium and North America, while Japanese equipment manufacturers source precursor chemicals for fiber-optic amplifier production. This tripartite trade corridor shapes procurement geography for defense and telecommunications end users.
China
MIIT export licensing governs concentrate allocation from Yunnan and Inner Mongolia mining clusters. Domestic solar cell manufacturers absorb rising volumes under strategic stockpile release programs. Shanghai and Suzhou foundry clusters concentrate germanium tetrachloride consumption for submarine cable precursor synthesis.
United States
Defense Production Act invocation funds refining capacity construction for thermal imaging substrate supply. EPA workplace exposure limits constrain tetrachloride handling at Texas and Arizona epitaxy facilities. Colorado and New Mexico host legacy zone refining operations serving aerospace prime contractors.
Belgium
REACH registration requirements at ECHA drive documented supply chain provenance for electronics-grade imports. The Hoboken refining complex anchors European high-purity metal output. Antwerp logistics corridors distribute precursor chemicals to German optics manufacturers.
Japan
METI critical minerals stockpiling secures tetrachloride reserves for trans-Pacific cable amplifier production. Osaka and Nagoya equipment manufacturers specify single-crystal substrates for satellite power systems. JIS standards govern purity certification for compound semiconductor foundries.
Germany
F-Gas Regulation compliance costs pressure refining energy intensity at European smelters. Bavaria and Baden-Württemberg defense integrators lock in multi-year substrate offtake for armored vehicle thermal arrays. KBA export classification reviews create compliance timeline uncertainty for infrared optics subsystem suppliers.
Germanium Market Vendor Landscape
Player mix skews toward state-controlled mining conglomerates and vertically integrated zinc smelters. Concentrate origination concentrates among Chinese refiners with MIIT quota allocation authority. Two strategic archetypes dominate: zinc byproduct recovery specialists with captive concentrate streams, and electronics-grade refiners with zone purification expertise. Competitive moves center on backward integration into mining assets and long-term offtake contracting with defense primes.
Among North American resource companies, Teck Resources Limited exemplifies the byproduct recovery archetype through zinc smelting operations. Umicore anchors European refining capacity through its Belgian complex. Yunnan Chihong Zinc & Germanium Co., Ltd. represents state-controlled concentrate dominance with access to China's largest primary reserves.
| Leading Market Players |
|---|
| 5N Plus |
| Indium Corporation |
| Teck Resources Limited |
| American Elements |
| PPM Pure Metals GmbH |
| Umicore |
| China Germanium Co., Ltd. |
| AXT, Inc. |
| Yunnan Chihong Zinc & Germanium Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Gallium arsenide substitution in RF applications is compressing pricing premiums for germanium substrates while simultaneously redirecting procurement toward higher-purity optical grades. This material displacement is reshaping supply geography toward East Asian compound semiconductor foundries and concentrating pricing power among zone-refining specialists with defense certification authority.
Pricing Analysis
Single-crystal Czochralski boules command substantial premiums over polycrystalline alternatives, while metallurgical-grade feedstock trades at depressed levels. Three-tier pricing structure across electronic, metallurgical, and reagent grades separates defense-certified material from commodity chemical derivatives. Pricing pressure stems from MIIT export licensing constraining spot availability for non-Chinese buyers. Telecommunications cable builders exhibit highest price sensitivity through competitive tender processes, whereas thermal imaging integrators lock in cost-plus contracts with minimal elasticity.
Supply Chain Analysis
Port congestion at Antwerp and Shanghai is elevating inbound logistics costs for germanium tetrachloride shipments bound for European fiber-optic compounders. Concentrate origination centers on China, with secondary refining capacity concentrated in Belgium and North America. The supply chain draws from zinc smelting byproduct streams, zone-refined boule production, and chemical precursor synthesis. Single-source vulnerability pervades the concentrate tier due to Yunnan Chihong's dominance over Chinese primary reserves. Distribution runs through direct mill contracts for defense primes and distributor networks for telecommunications chemical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated defense primes and submarine cable consortia capable of locking in multi-year offtake agreements, fragmenting spot market access for smaller compound semiconductor foundries.
For Market Incumbents: Fortify captive concentrate access through backward integration into zinc smelting assets or long-term tolling arrangements with Chinese state-controlled refiners. Expand zone-refining technician training pipelines to address operational expertise scarcity constraining capacity expansion. Prioritize ITAR certification maintenance as dual-use export classification complexity extends qualification timelines for international subsystem suppliers. For New Entrants and Emerging Players: Anchor in urban mining infrastructure for end-of-life fiber-optic cable and decommissioned infrared optics recovery, where germanium yields currently capture sub-30% of theoretical recoverable metal. Target European REACH-compliant recycling partnerships as ECHA enforcement actions against undocumented shipments create compliance-driven demand for certified feedstock streams. Pursue equipment-leasing models for zone-refining capacity rather than greenfield smelter construction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed zinc smelting conglomerates seeking to monetize byproduct recovery streams through downstream refining joint ventures. Long-term viability hinges on sustained defense thermal imaging procurement and submarine cable deployment acceleration across Pacific routes. Monitor Beijing's expansion of export licensing to germanium dioxide and tetrachloride derivatives as an inflection indicator forcing Western optics manufacturers toward alternative material qualification or accelerated recycling partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Smelting | Secures captive concentrate feedstock from Teck Resources-style byproduct recovery operations. |
| Zone-Refining Capacity Expansion | Addresses technician scarcity constraining high-purity metal output for defense substrate demand. |
| Urban Mining Infrastructure Development | Unlocks end-of-life fiber-optic cable and infrared optics as underexploited germanium recovery streams. |
| Long-Term Offtake Contracting | Mirrors Corning and Prysmian multi-year chemical supply agreements reducing material availability risk. |
| REACH-Compliant Recycling Partnerships | Responds to ECHA enforcement actions creating mandatory supply chain provenance documentation requirements. |
Methodological Framework
Two parallel data streams informed the analysis: primary engagement with zone-refining operations managers, defense procurement officers at thermal imaging integrators, fiber-optic cable project directors, and compound semiconductor foundry engineers; alongside secondary validation through customs trade data, SEC filings from zinc smelting conglomerates, ECHA substance volume registrations, and MIIT export licensing disclosures. Bottom-up triangulation across product-grade consumption estimates and top-down reconciliation against concentrate origination volumes anchored value and volume outputs.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, application, end user, and grade tier, with additional segmentation by regional regulatory cluster. CAGRs were derived from regression analysis of historical consumption patterns against submarine cable deployment schedules, defense procurement cycles, and satellite launch manifests. Zone-refining capacity utilization rates and MIIT quota allocation patterns served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained MIIT export licensing stringency and continued NATO defense thermal imaging procurement; material deviation would warrant model refresh. Specific risk factors include Beijing's potential expansion of licensing to chemical derivatives, gallium arsenide substitution acceleration in RF applications, and European F-Gas Regulation compliance cost escalation at smelters. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
Semiconductor Silicon Material Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Silicon Hydride Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Cadmium Market