
 Global Indium Tin Oxide (ITO) Market | 2026-2036
Global Indium Tin Oxide (ITO) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Indium Tin Oxide (ITO) Market Intelligence
A shift from single-source indium procurement toward multi-source supply agreements is recalibrating how manufacturers secure feedstock stability. Indium Corporation leverages its vertical integration from refining to target fabrication to sustain pricing leverage across volatile metal cycles. Mitsui Mining & Smelting Co., Ltd. anchors its position through captive zinc smelter outputs that yield indium as a byproduct. JX Nippon Mining & Metals competes on ultra-high-purity sputtering targets for advanced semiconductor nodes.
Indium tin oxide is a ternary oxide compound typically composed of 90% indium(III) oxide and 10% tin(IV) oxide by weight, deposited as a thin film with sheet resistances below 10 ohms per square to achieve both electrical conductivity and optical transparency in the visible spectrum. Sputtering targets dominate commercial volume due to their compatibility with roll-to-roll and flat-panel manufacturing lines, while thermal evaporation retains share in niche photovoltaics applications where film thickness uniformity requirements are less stringent. Transparent conductive films command premium positioning as OLED display makers specify tighter optical haze tolerances, whereas dispersion powder segments face margin compression from alternative conductive polymer development.
China's MEE enforces wastewater discharge limits on indium refining operations that elevate capital requirements for new smelter entrants, while REACH in Europe mandates full substance registration for ITO nanoparticle imports that complicate cross-border material flows. Japan's METI coordinates strategic stockpiling directives that buffer domestic manufacturers against supply disruptions from concentrated Chinese refining. Stakeholders must monitor substitution timelines for silver nanowire and metal mesh technologies that threaten ITO's cost-positioning in large-format touch applications.
Market Dynamics
Touchscreen manufacturers in consumer electronics are compressing specification cycles for transparent conductive films, forcing ITO suppliers to synchronize production cadences with display panel fabs in East Asian production clusters spanning China, South Korea, and Japan.
Growth Catalysts
- OLED display specification tightening:Panel makers in South Korea and Japan now mandate optical haze tolerances below 0.5%, elevating demand for ultra-high-purity sputtering targets.
- China's dual carbon goals:MEE enforcement of wastewater discharge limits on indium refining operations is accelerating consolidation toward technically proficient producers capable of compliance.
- Roll-to-roll manufacturing compatibility:Sputtering target formats optimized for continuous deposition lines are capturing volume from batch thermal evaporation in photovoltaic applications.
Market Restraints
- Indium supply concentration:Over 80% of global indium refining capacity resides in Chinese state-affiliated zinc smelter operations, creating single-source vulnerability for target fabricators.
- Silver nanowire substitution:Alternative transparent conductor technologies threaten ITO's cost-positioning in large-format touch applications exceeding 65 inches diagonal.
- REACH registration burden:ECHA mandates for full substance documentation on ITO nanoparticle imports complicate cross-border material flows into European display assembly plants.
Strategic Opportunities
- India electronics manufacturing:PLI scheme subsidies for semiconductor and display fabrication are attracting ITO target suppliers to establish localized sputtering operations near emerging panel fabs.
- Automotive display integration:Curved and flexible touchscreen specifications for electric vehicle infotainment systems are opening specification windows for ITO film variants with enhanced mechanical durability.
- Japan METI stockpiling coordination:Strategic reserve directives buffer domestic manufacturers against supply disruptions, creating preferential procurement relationships for qualified suppliers.
Industry Challenges
- High-purity indium sourcing:Target fabricators face 18-24 month qualification timelines with zinc smelter partners to secure 6N-grade feedstock suitable for semiconductor node applications.
- Sputtering equipment integration:Legacy flat-panel deposition lines require retrofitting to accommodate next-generation rotary target architectures, compressing capital recovery periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Indium Tin Oxide (ITO) Market |
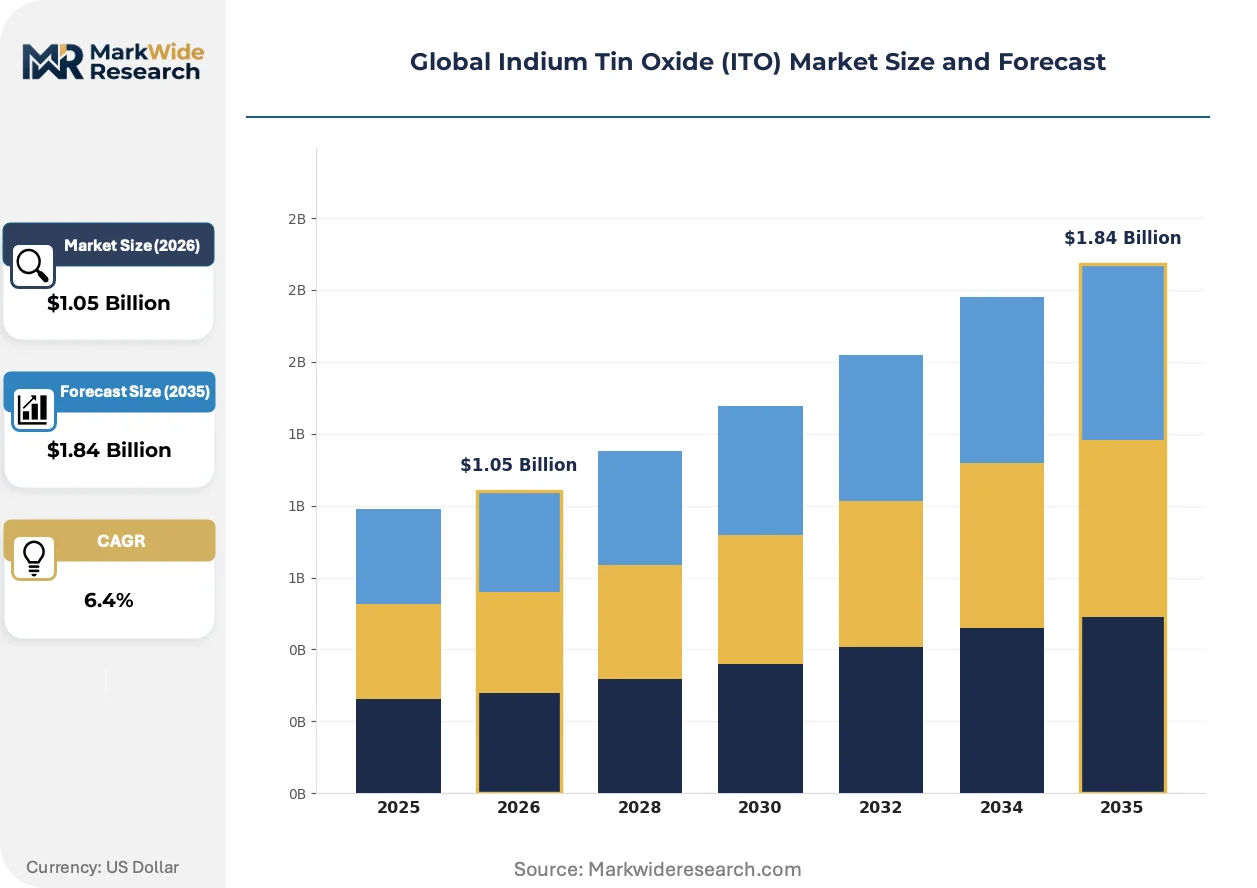
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targets, Pellets, Sputtering Targets, Dispersion Powder Technology: Sputtering, Thermal Evaporation, Chemical Vapor Deposition, Atomic Layer Deposition Application: Touchscreens, OLED Displays, Photovoltaics, Transparent Conductive Films End User Industry: Consumer Electronics, Solar Panel Manufacturing, Semiconductor Fabrication, Industrial Automation |
| Companies Covered | Nitto Denko Corporation, Samsung Corning Precision Material, Indium Corporation, JX Nippon Mining & Metals, Tosoh Corporation, Umicore, American Elements, ENAM Optoelectronic Material, Mitsui Mining & Smelting Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Indium Tin Oxide (ITO) Market Strategic Shifts & Innovations
Active developments across material purity, regulatory compliance architecture, and procurement contracting are restructuring how ITO value chains coordinate between indium refiners, target fabricators, and display panel manufacturers.
Ultra-high-purity ITO sputtering targets are unifying previously separate specification tiers for OLED and semiconductor applications. Display makers in South Korea now specify identical resistivity and particle count standards for both product categories, collapsing the premium segmentation that historically separated these segments. This unification is compressing margin differentiation across target grades and forcing suppliers to concentrate technical investment on a single purity platform.
REACH substance registration requirements from ECHA are fragmenting import pathways for ITO nanopowder into European manufacturing zones. German and Dutch customs authorities now enforce batch-level documentation that extends clearance timelines by 3-4 weeks, compelling display assemblers to shift toward pre-registered sputtering target formats rather than raw powder procurement. Small-format touch module producers in Eastern Europe face the most acute compliance cost escalation.
Multi-year offtake agreements are displacing spot market purchasing for indium feedstock among Japanese target fabricators. Mitsui Mining & Smelting and JX Nippon Mining & Metals have locked 5-7 year supply contracts with Chinese zinc smelters, securing volume commitments that insulate against price volatility but constrain operational flexibility. This contractual shift is most visible in the semiconductor sputtering target segment, where qualification timelines for alternative suppliers exceed 24 months.
Global Indium Tin Oxide (ITO) Market Segmentation
ITO market segmentation reflects distinct certification burdens across deposition technologies and end-use specifications. Display panel fabs in South Korea and Japan impose divergent purity protocols that reshape supplier qualification timelines.
Product Type:
Sputtering targets carry semiconductor-grade certification requirements from Japan's METI and South Korea's MFDS, while dispersion powders face REACH nanoparticle registration mandates from ECHA.
- Sputtering Targets:Rotary and planar formats deposited via magnetron sputtering achieve sheet resistances below 10 ohms per square. Demand concentrates in East Asian display clusters where OLED panel fabs specify 6N-grade indium feedstock for sub-0.5% optical haze tolerances.
- Targets:Solid ceramic discs and bonded assemblies serve batch deposition systems in legacy flat-panel lines. Japanese semiconductor fabricators drive specifications for ultra-high-purity variants with particle counts below 50 per square centimeter.
- Pellets:Compressed ITO granules for thermal evaporation crucibles in photovoltaic manufacturing.
- Dispersion Powder:Nanoparticle suspensions for printed electronics face ECHA registration delays extending European import clearance by 3-4 weeks.
Leading the category by volume: Sputtering Targets. Growing fastest: Dispersion Powder.
Technology:
Deposition method selection hinges on film thickness uniformity requirements and capital equipment compatibility with roll-to-roll manufacturing lines.
- Sputtering:Magnetron sputtering dominates commercial volume through compatibility with continuous deposition systems. South Korean display makers specify this technology for Gen 10.5 panel lines requiring uniform coating across 3-meter substrates.
- Thermal Evaporation:Resistive heating of ITO pellets retains share in photovoltaic applications where thickness tolerances of ±15% are acceptable. Chinese solar panel manufacturers favor this lower-capital approach for utility-scale installations.
- Chemical Vapor Deposition:CVD enables conformal coating on complex 3D surfaces for automotive display integration.
- Atomic Layer Deposition:ALD achieves sub-nanometer thickness control for advanced semiconductor nodes but faces throughput constraints.
Widest installed base: Sputtering. Steepest expansion trajectory: Atomic Layer Deposition.
Application:
Application segments stratify by optical performance thresholds and mechanical durability specifications for curved or flexible form factors.
- OLED Displays:Active-matrix OLED panels require ITO anode layers with transmittance exceeding 85% in the visible spectrum. Japanese and South Korean panel makers now unify specifications across smartphone and television formats, collapsing historical premium tiers.
- Touchscreens:Projected capacitive touch layers in consumer electronics face substitution pressure from silver nanowire technologies in formats exceeding 65 inches diagonal.
- Transparent Conductive Films:Flexible substrates for automotive and wearable applications specify enhanced crack resistance under bending stress.
- Photovoltaics:Thin-film solar cells utilize ITO front contacts where cost sensitivity favors thermal evaporation over sputtering.
Highest value concentration: OLED Displays. Climbing the fastest: Transparent Conductive Films.
End User Industry:
End-use sectors impose divergent procurement scales, with semiconductor fabrication requiring 18-24 month supplier qualification cycles versus solar panel manufacturing's spot-market purchasing.
- Consumer Electronics:Smartphone, tablet, and laptop manufacturers drive specification tightening for transparent conductors. East Asian production clusters in China, South Korea, and Japan compress product cycles to 12-18 months.
- Semiconductor Fabrication:Logic and memory chip foundries specify ITO sputtering targets for advanced packaging interconnects. Japan's METI stockpiling directives buffer domestic manufacturers against Chinese supply concentration.
- Solar Panel Manufacturing:Chinese utility-scale installers dominate volume demand with price-sensitive procurement.
- Industrial Automation:Human-machine interface panels and touch-enabled control systems specify enhanced durability for factory floor environments.
Dominant demand source: Consumer Electronics. Gaining share fastest: Semiconductor Fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zinc smelter byproduct recovery in Chinese state-affiliated operations anchors the upstream indium supply chain, while downstream fabrication clusters concentrate in East Asian display manufacturing corridors. This geographic configuration creates asymmetric dependencies between raw material extraction and high-value target production.
China
Dual carbon goals from Beijing are tightening MEE wastewater discharge limits on indium refining operations, accelerating consolidation toward technically proficient producers. The Yangtze River Delta hosts captive zinc smelter outputs that yield indium as a byproduct, with state-affiliated operations controlling over 80% of global refining capacity. Suzhou and Hefei panel fabs are compressing specification cycles for transparent conductive films to 12-18 months.
Japan
METI coordinates strategic stockpiling directives that buffer domestic manufacturers against supply disruptions from concentrated Chinese refining. The Kanto region around Tokyo anchors ultra-high-purity sputtering target fabrication for advanced semiconductor nodes. Osaka-based fabricators now specify identical resistivity standards for OLED and semiconductor applications, collapsing historical premium tiers.
South Korea
MFDS certification requirements for semiconductor-grade sputtering targets are unifying specification tiers across display and chip fabrication. The Seoul Capital Area drives Gen 10.5 panel line investments requiring uniform coating across 3-meter substrates. Samsung and LG Display operations in Gumi and Paju mandate optical haze tolerances below 0.5% for active-matrix OLED panels.
Germany
ECHA REACH mandates for full substance documentation on ITO nanoparticle imports are extending customs clearance timelines by 3-4 weeks at Hamburg and Rotterdam entry points. The Eindhoven Region display assembly plants are shifting toward pre-registered sputtering target formats rather than raw powder procurement. Dresden semiconductor foundries specify 6N-grade indium feedstock with particle counts below 50 per square centimeter.
United States
EPA enforcement of hazardous waste regulations on indium-containing manufacturing residues is elevating compliance costs for domestic target fabricators. The Pacific Northwest hosts specialty chemical operations supplying ITO precursor materials to East Asian panel makers. Arizona and Texas semiconductor packaging facilities are qualifying alternative feedstock suppliers to reduce single-source vulnerability from Chinese refining concentration.
Global Indium Tin Oxide (ITO) Market Key Industry Players
Multi-year offtake agreements dominate the current landscape as Japanese and Korean fabricators lock 5-7 year supply contracts with Chinese zinc smelters. The vendor base stratifies across three tiers: vertically integrated mining-to-target operations, captive byproduct refiners with dedicated fabrication arms, and specialist target fabricators dependent on merchant indium markets. Zinc smelter operators leverage captive indium outputs to secure downstream fabrication partnerships, while independent target makers concentrate technical investment on ultra-high-purity qualification protocols. Strategic partnerships and technology licensing are displacing pure merchant supply relationships as qualification timelines extend beyond 24 months.
Within the vertically integrated tier, Indium Corporation and Mitsui Mining & Smelting Co., Ltd. exemplify contrasting approaches to feedstock security. Indium Corporation leverages backward integration from refining to target fabrication to sustain pricing leverage across volatile metal cycles. Mitsui Mining & Smelting Co., Ltd. anchors its position through captive zinc smelter outputs that yield indium as a byproduct. JX Nippon Mining & Metals occupies a position competing on ultra-high-purity sputtering targets for advanced semiconductor nodes. These three fabricators represent the dominant competitive archetypes: full vertical integration, captive byproduct recovery, and premium-tier specialization.
| Leading Market Players |
|---|
| Nitto Denko Corporation |
| Samsung Corning Precision Material |
| Indium Corporation |
| JX Nippon Mining & Metals |
| Tosoh Corporation |
| Umicore |
| American Elements |
| ENAM Optoelectronic Material |
| Mitsui Mining & Smelting Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Indium metal price benchmarks cascade through zinc smelter byproduct credits into ITO sputtering target pricing tiers, with Chinese state-affiliated refiners leveraging captive indium outputs to extract premium terms from Japanese and Korean fabricators locked into long-term qualification protocols.
Pricing Analysis
Technical support and metallurgical consulting bundles separate premium Japanese suppliers from unbundled Chinese merchant offerings. Three-tier pricing structure across 6N-grade semiconductor targets, 5N-grade display targets, and 4N-grade photovoltaic pellets reflects certification investment differentials. Price compression runs through dispersion powder segments as REACH registration costs erode European margins. Solar panel manufacturers in China exhibit highest price sensitivity, while semiconductor foundries in Japan tolerate premium positioning for qualified supply security.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore buffer East Asian fabrication clusters against logistics volatility. Raw material flows draw from Chinese zinc smelter byproduct recovery, Korean zinc concentrate imports, and Japanese strategic stockpile releases. Single-source vulnerability concentrates in Yangtze River Delta refining operations controlling over four-fifths of global indium output. Distribution runs through bonded warehouse arrangements serving Gen 10.5 panel fabs in Gumi and Paju.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indium supply constraints from MEE wastewater enforcement prop 6N-grade pricing premiums, with Chinese smelter consolidation eliminating marginal refining capacity and tightening feedstock availability for unqualified target fabricators.
For Market Incumbents: Hedge silver nanowire substitution threats in large-format touch applications by accelerating sputtering target qualification for automotive curved displays. Secure backward integration into zinc smelter partnerships before 18-24 month qualification windows close to new entrants. Prioritize rotary target architecture R&D to capture retrofit demand from legacy flat-panel lines. For New Entrants and Emerging Players: Begin with India's PLI-subsidized display fabrication corridor, where localized sputtering operations face minimal incumbent qualification barriers. Target transparent conductive film segments for wearable and automotive applications where mechanical durability specifications favor ITO over emerging alternatives. Pursue joint development agreements with panel fabs rather than merchant supply positioning. For Investors and Strategic Acquirers: The window for entry favors captive byproduct refiners with existing zinc smelter infrastructure and technical proficiency for 6N-grade purification. Long-term viability hinges on qualification protocol completion before consolidation eliminates acquisition targets. Watch silver nanowire cost curves as the inflection signal for ITO displacement timelines in consumer electronics touch layers.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Japanese fabricators lock 5-7 year indium offtake with Chinese zinc smelters to insulate against price volatility. |
| Backward Integration | Target makers acquire stakes in zinc smelter operations to secure captive 6N-grade feedstock for semiconductor applications. |
| Green Manufacturing Transition | MEE wastewater compliance investments separate technically proficient refiners from marginal operators facing consolidation. |
| Capacity Expansion | Rotary target fabrication lines in India serve PLI-attracted display fabs with reduced logistics costs versus East Asian imports. |
| Joint Venture | Strategic partnerships between Korean panel makers and Japanese target fabricators unify OLED and semiconductor specification tiers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with zinc smelter operations managers, sputtering target procurement leads at display fabs, ITO R&D directors, and semiconductor packaging engineers. Bottom-up volume modeling triangulated against top-down value estimates derived from China Customs indium export statistics, Japan METI strategic stockpile reports, and ECHA REACH registration databases.
Data-stream reconciliation across supply-side capacity assessments and demand-side panel fab capex disclosures shaped the analytical framework. Segmentation dimensions spanned deposition technology, purity grade tier, end-use application, and regional production cluster. CAGRs emerged from fitted growth curves applied to indium consumption intensity metrics per square meter of display substrate, cross-referenced with OLED and LCD capacity expansion announcements.
Underlying measurement precision varies by segment; sputtering target volumes carry tighter precision than dispersion powder estimates due to consolidated supplier reporting. Forecasts reflect documented assumptions including sustained Chinese smelter concentration, silver nanowire substitution trajectories, and REACH enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Electronic Film Market
Semiconductor Material
Ultra High Purity Silicon Carbide Market
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
Electronic Ceramics Market
Semiconductor Material
Global Strontium Market
Semiconductor Material
Zinc Oxide Nanoparticles Market
Semiconductor Material
Global Electronic Materials Market
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
Gallium Market