
 South America Hemodynamic Monitoring Market | 2026-2036
South America Hemodynamic Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
South America Hemodynamic Monitoring Market Analytics
Minimally invasive hemodynamic monitoring is reshaping how cardiac output and fluid responsiveness are assessed in South American intensive care units. GE Healthcare leverages its installed base of patient monitoring platforms to sustain service revenue across Brazilian hospital networks. Edwards Lifesciences Corporation anchors premium positioning through specialized arterial pressure waveform analysis technology.
Hemodynamic monitoring encompasses the continuous or intermittent measurement of blood flow dynamics, cardiac function, and vascular tone using pressure transducers, thermistor sensors, and Doppler ultrasound probes operating at 2-5 MHz frequencies for transesophageal applications. Its primary purpose is to guide fluid therapy, vasoactive drug titration, and hemodynamic optimization during high-risk surgery and septic shock management. Non-invasive monitors represent the fastest-expanding product category as Brazilian clinics seek to reduce catheter-related bloodstream infections and procedural costs. Fluid responsiveness monitoring technology captures concentrated margin pools where LiDCO Group PLC and Cheetah Medical Inc compete on algorithmic differentiation for stroke volume variation assessment.
ANVISA governs medical device registration and post-market surveillance in Brazil, while Argentina's national pharmaceutical regulator enforces comparable technical standards for hemodynamic equipment importation. Both frameworks mandate clinical evidence packages and quality system certifications that extend product approval timelines and elevate barriers for non-established suppliers. Stakeholders must monitor evolving Mercosur harmonization initiatives and reimbursement pathway negotiations with Brazil's unified health system to anticipate access expansion or contraction across the region's largest addressable patient populations.
Market Dynamics
Non-invasive monitoring platforms are collapsing the traditional catheterization volume in Brazilian ICUs as hospitals prioritize infection control and procedural throughput over invasive precision.
Growth Catalysts
- ANVISA Accelerated Pathways:Brazil's streamlined medical device registration reduces clearance timelines for hemodynamic equipment, enabling faster commercialization of next-generation monitors.
- Catheter-Related Infection Prevention:Brazilian hospital networks are prioritizing non-invasive alternatives to reduce bloodstream infection rates and associated liability exposure in surgical wards.
- Southeastern Hospital Corridor Expansion:São Paulo and Rio de Janeiro health systems are modernizing ICU infrastructure, creating concentrated demand for advanced hemodynamic assessment tools.
Market Restraints
- Import Duty Structure:Brazilian tariff regimes on electronic medical components elevate landed costs for waveform analysis systems and pressure transducer assemblies.
- Clinical Evidence Requirements:ANVISA mandates extensive local validation studies that extend product approval cycles and strain R&D budgets for emerging suppliers.
- Specialized Training Bottlenecks:The region faces scarcity of perfusionists and critical care specialists capable of interpreting advanced hemodynamic parameters in real-time clinical settings.
Strategic Opportunities
- Argentine Market Underpenetration:Buenos Aires and Córdoba hospital networks remain underserved for advanced monitoring, presenting first-mover expansion potential for established Brazilian distributors.
- Tele-ICU Integration:Remote hemodynamic surveillance platforms enable specialist coverage across geographically dispersed critical care units in Brazil's northern and northeastern states.
- Mercosur Harmonization:Converging technical standards across member states promise simplified multi-country registration and reduced compliance fragmentation for device manufacturers.
Industry Challenges
- Legacy System Interoperability:Brazilian hospitals operate heterogeneous patient data architectures that complicate integration of new hemodynamic monitors with existing EMR workflows.
- Reimbursement Pathway Uncertainty:Negotiations with Brazil's unified health system regarding procedure codes for non-invasive monitoring create pricing visibility gaps for procurement planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Hemodynamic Monitoring Market |
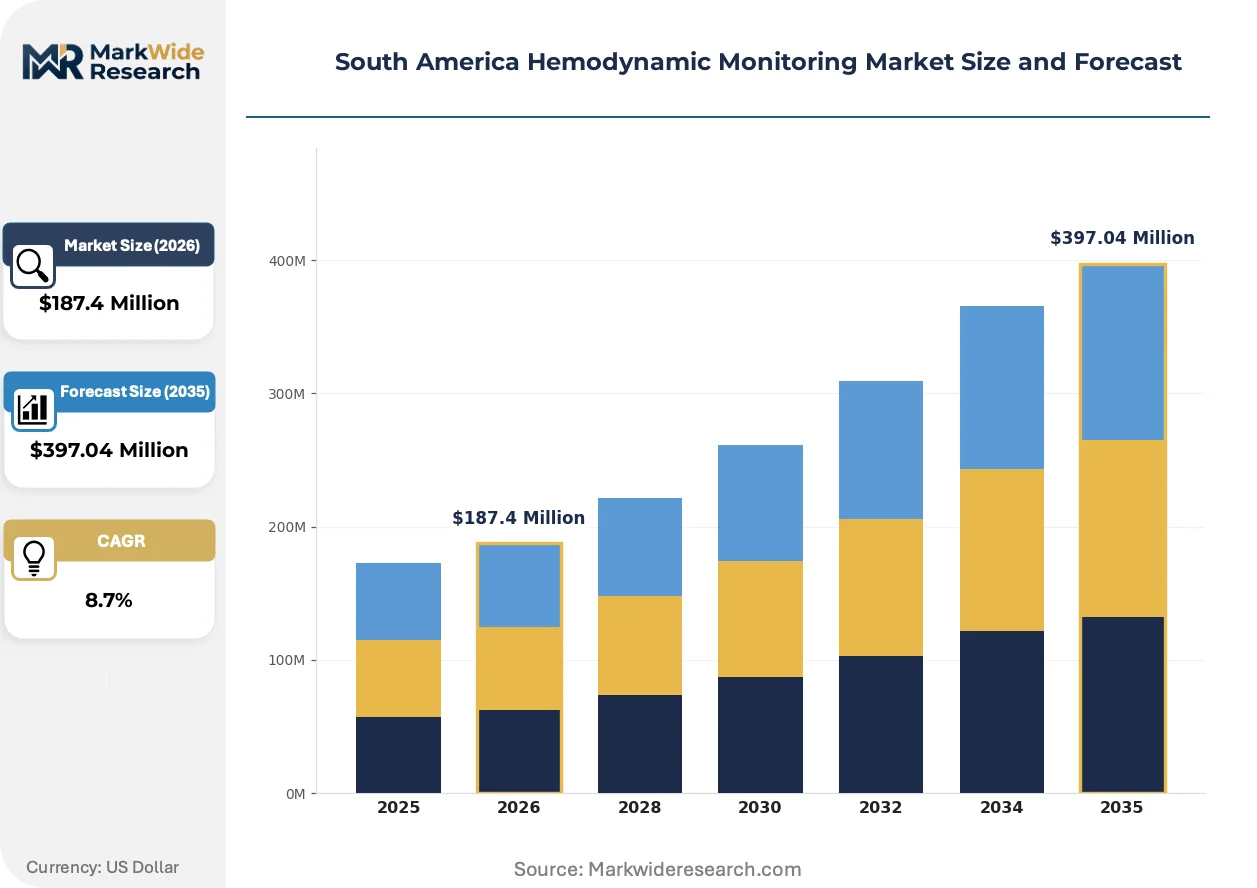
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Monitors, Non-Invasive Monitors, Continuous Monitors, Portable Monitors End User: Hospitals, Clinics, Emergency Care, Research Institutions Technology: Ultrasound, Electrical Impedance, Thermodilution, Fluid Responsiveness Monitoring Application: Cardiology, Critical Care, Surgery, Anesthesia |
| Companies Covered | GE Healthcare, Cheetah Medical Inc, Getinge Group, Draeger Medical, LiDCO Group PLC, Koninklijke Philips NV, ICU Medical Inc, Schwarzer Cardiotek GmbH, Edwards Lifesciences Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Hemodynamic Monitoring Market Evolving Landscape
Algorithmic fluid responsiveness assessment is displacing static pressure-based protocols across South American surgical suites, compressing decision cycles and reducing volume-loading complications.
Photoplethysmography-derived cardiac output monitoring is collapsing the cost barrier between invasive and non-invasive hemodynamic assessment. Outpatient surgical centers in São Paulo are adopting these platforms at twice the rate of traditional hospitals. The technology is collapsing the historical price-performance gap that protected catheter-based systems in lower-acuity settings.
ANVISA's updated post-market surveillance requirements now mandate real-time adverse event reporting for Class III hemodynamic devices. This regulatory tightening elevates compliance infrastructure costs but simultaneously rewards manufacturers with robust quality systems. High-complexity hospitals in Brazil's southeast are prioritizing suppliers with demonstrated surveillance capabilities.
Hospital purchasing consortia are consolidating procurement authority for hemodynamic equipment across multi-facility networks. Independent distributors in Argentina are losing direct access to ICU decision-makers as buying committees centralize vendor selection. This concentration is most pronounced among Catholic hospital networks operating across Brazil's southern states.
South America Hemodynamic Monitoring Market Segmentation
Segmentation in South American hemodynamic monitoring reveals how infection control priorities, ICU modernization budgets, and procedural throughput requirements reshape procurement patterns across Brazilian and Argentine health systems. Understanding these divides exposes where technology substitution accelerates and where legacy catheter-based systems retain defensive positions.
Product Type:
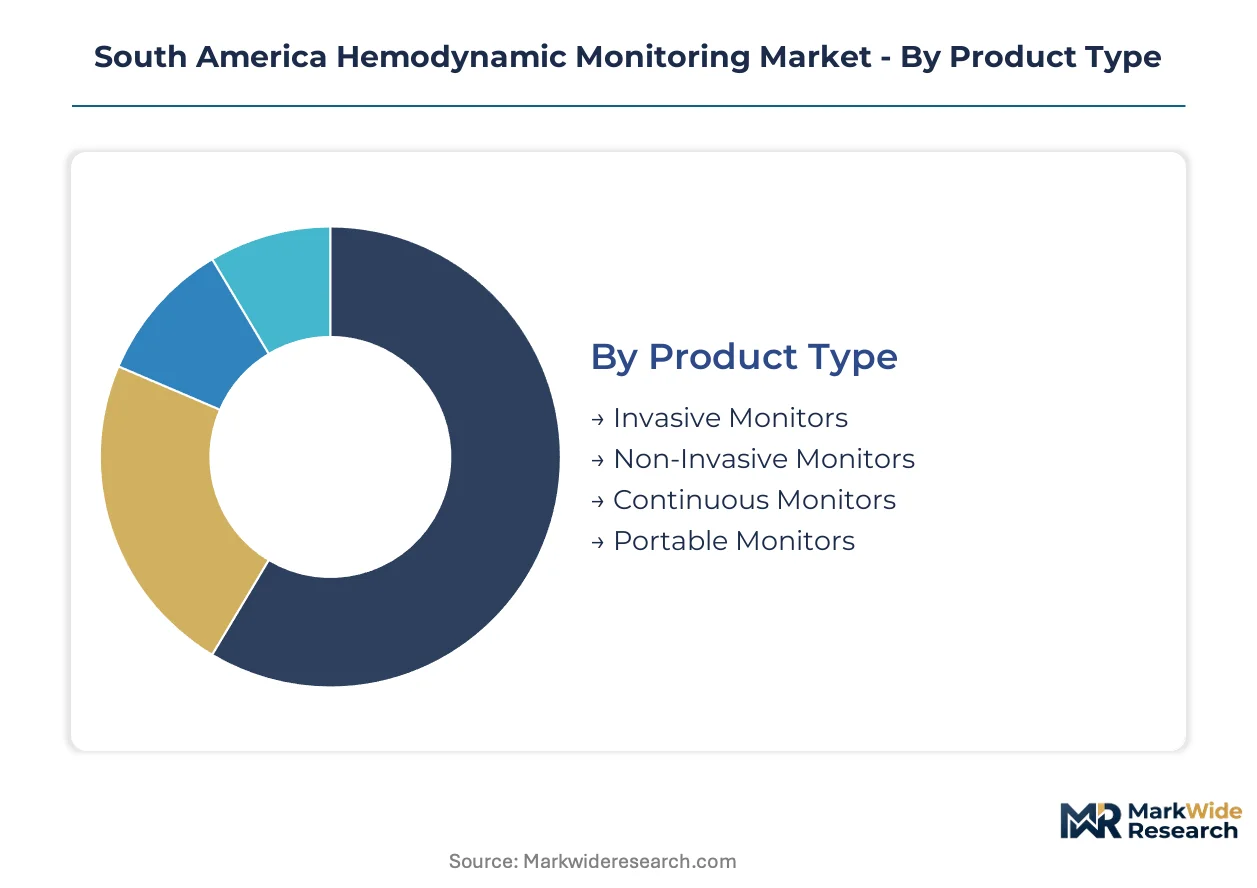
Mature invasive platforms anchor revenue while emerging non-invasive alternatives capture the fastest expansion trajectories in São Paulo surgical networks.
- Invasive Monitors:Pulmonary artery catheter systems with thermistor-equipped Swan-Ganz catheters deliver gold-standard cardiac output precision. São Paulo university hospitals maintain these platforms for complex cardiac surgery despite higher complication risks.
- Non-Invasive Monitors:Photoplethysmography and bioreactance-based systems eliminate catheter insertion risks. Brazilian outpatient surgical centers in Rio de Janeiro adopt these at accelerated rates to reduce bloodstream infection liability and turnover time between cases.
- Continuous Monitors:Real-time arterial waveform analysis systems enable uninterrupted hemodynamic tracking during lengthy procedures.
- Portable Monitors:Battery-operated compact units support inter-facility patient transport and emergency field deployment.
Invasive monitors handle the majority of throughput in high-complexity cardiac centers; non-invasive monitors are climbing the fastest on share as infection control mandates tighten.
End User:
Cost tier stratification separates capital-intensive hospital installations from budget-constrained clinic adoption across the southeastern corridor.
- Hospitals:Tertiary medical centers with dedicated ICU infrastructure deploy multi-parameter monitoring networks integrating hemodynamic modules with central nursing stations. São Paulo's Albert Einstein and Sírio-Libanês hospital networks standardize on platform ecosystems that lock in service contracts.
- Clinics:Ambulatory surgical facilities prioritize single-purpose monitors with simplified interfaces. Buenos Aires ophthalmology and orthopedic day-surgery centers drive demand for plug-and-play non-invasive cardiac output devices.
- Emergency Care:Pre-hospital and emergency department settings require rapid-deployment monitors for shock assessment.
- Research Institutions:Academic medical centers utilize research-grade hemodynamic platforms for clinical trial endpoints and algorithm validation.
Hospitals absorb the dominant capital expenditure volume; clinics represent the steepest expansion trajectory as outpatient surgery migrates from inpatient settings.
Technology:
Application intensity varies by procedural volume, with high-throughput surgical suites demanding real-time responsiveness assessment.
- Ultrasound:Transthoracic and transesophageal Doppler systems operating at 2-5 MHz frequencies measure blood flow velocity and cardiac output. Brazilian cardiac surgery programs in Rio de Janeiro rely on transesophageal echocardiography-integrated hemodynamic assessment for valve replacement procedures.
- Electrical Impedance:Thoracic bioreactance systems calculate stroke volume through chest wall impedance fluctuations. Argentine critical care units adopt these for non-invasive monitoring in sepsis management where serial assessments outpace invasive catheter tolerance.
- Thermodilution:Cold saline injectate methods through pulmonary artery catheters provide intermittent cardiac output reference standards.
- Fluid Responsiveness Monitoring:Algorithmic stroke volume variation analysis guides volume loading decisions. These platforms concentrate margin capture where LiDCO and Cheetah Medical compete on proprietary algorithm differentiation.
Ultrasound platforms command the installed base; fluid responsiveness monitoring technology is gaining share fastest as goal-directed therapy protocols standardize.
Application:
Customer workflow integration determines whether monitors serve dedicated specialists or cross-functional teams across surgical departments.
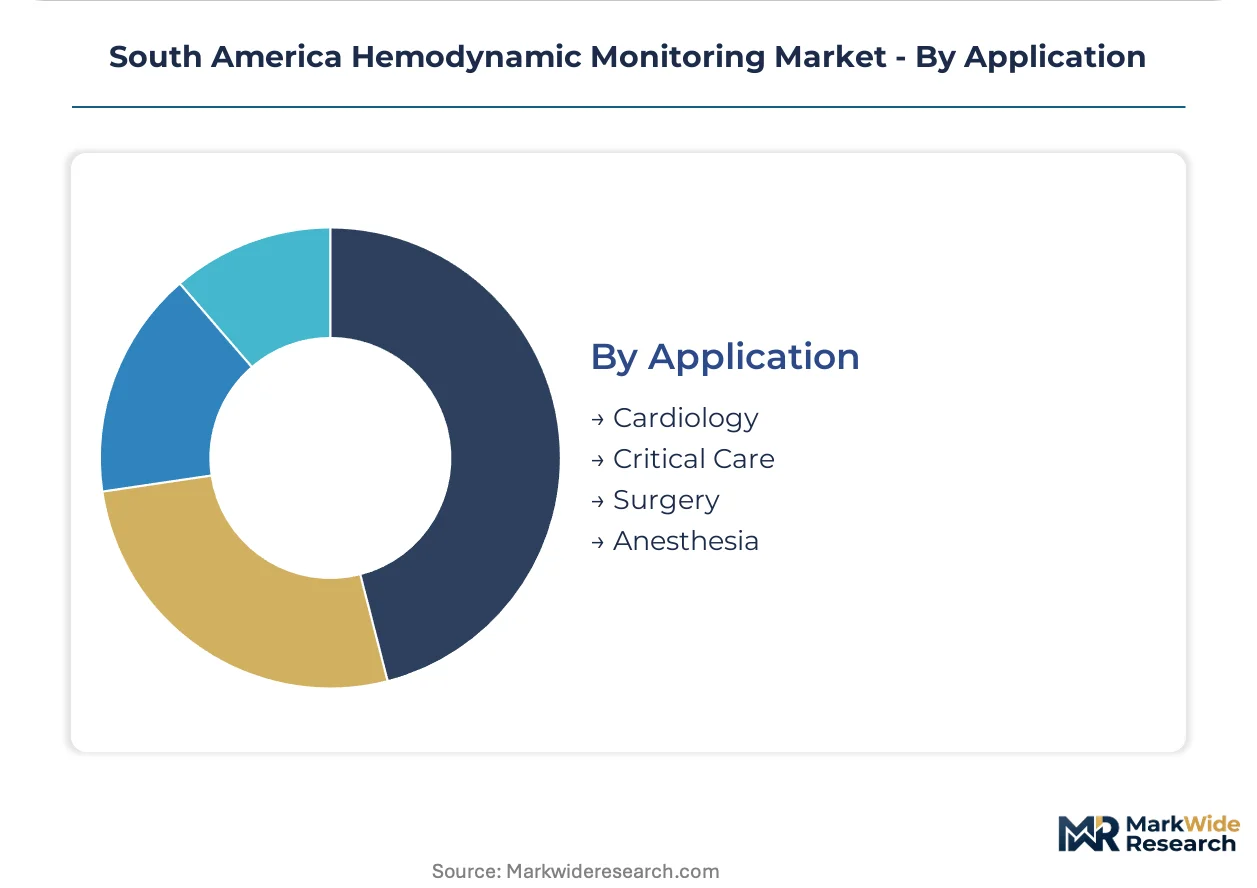
- Cardiology:Dedicated cardiac catheterization laboratories and electrophysiology suites require high-fidelity pressure and flow measurements. Interventional cardiologists in São Paulo's Dante Pazzanese Institute depend on precise cardiac output data for high-risk percutaneous coronary intervention hemodynamic support.
- Critical Care:Medical and surgical ICUs manage septic shock, acute respiratory distress syndrome, and multi-organ failure. Brazilian public hospital networks in Belo Horizonte expand monitoring capacity as ICU bed counts rise under federal infrastructure programs.
- Surgery:Operating rooms utilize hemodynamic optimization to reduce complications in major abdominal and vascular procedures.
- Anesthesia:Perioperative medicine teams employ goal-directed fluid therapy to shorten recovery and reduce postoperative morbidity.
Cardiology applications generate the highest equipment utilization rates; critical care is expanding most quickly as ICU capacity builds across Brazil's northern states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports hemodynamic monitoring systems across the Mercosur trade corridor, with Argentine hospitals representing the largest external demand cluster for Brazilian distributors.
Brazil
São Paulo and Rio de Janeiro university hospitals drive demand for multi-parameter monitoring networks. ANVISA's accelerated registration pathways compress product approval timelines for Class III hemodynamic devices. The southeastern hospital corridor spanning Albert Einstein and Sírio-Libanês networks standardizes on integrated platform ecosystems.
Argentina
Buenos Aires and Córdoba surgical centers seek plug-and-play non-invasive cardiac output monitors for ambulatory procedures. The national pharmaceutical regulator enforces technical standards for equipment importation that mirror Brazilian ANVISA requirements. Catholic hospital networks in Buenos Aires province centralize procurement authority through multi-facility buying committees.
Chile
Santiago's private clinic chains prioritize infection control through photoplethysmography-based monitoring systems. The country's medical device regulatory framework mandates quality system certifications for hemodynamic equipment commercialization. Metropolitan Santiago health systems modernize ICU infrastructure to support goal-directed fluid therapy protocols.
Colombia
Bogotá tertiary medical centers expand critical care capacity under national health infrastructure programs. The national food and drug surveillance institute oversees medical device registration with clinical evidence requirements. Antioquia and Valle del Cauca hospital networks adopt tele-ICU platforms to extend specialist coverage across mountainous terrain.
Peru
Lima public hospital networks face equipment procurement constraints amid budget allocation cycles. The national health authority coordinates with regional governments on medical device standardization initiatives. Coastal metropolitan clinics concentrate demand for portable hemodynamic monitors supporting inter-facility patient transport.
South America Hemodynamic Monitoring Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement hierarchies that fragment between hospital network consortia and independent distributor relationships. The market structure tiers into premium technology providers, mid-scale regional distributors, and emerging non-invasive platform developers. Two strategic archetypes dominate: integrated patient monitoring platform vendors leveraging installed base service contracts, and algorithm-focused fluid responsiveness specialists competing on proprietary analytics. M&A activity concentrates on acquiring algorithmic differentiation capabilities, while geographic expansion through Brazilian distributor partnerships captures Argentine and Chilean market entry.
Among diversified health technology conglomerates, GE Healthcare and Koninklijke Philips NV occupy positions anchored by broad patient monitoring platform ecosystems. Edwards Lifesciences Corporation exemplifies the premium-tier specialist archetype focused on arterial waveform analysis technology. These three entities represent contrasting competitive vectors: scale-driven platform integration versus precision-technology specialization.
| Leading Market Players |
|---|
| GE Healthcare |
| Cheetah Medical Inc |
| Getinge Group |
| Draeger Medical |
| LiDCO Group PLC |
| Koninklijke Philips NV |
| ICU Medical Inc |
| Schwarzer Cardiotek GmbH |
| Edwards Lifesciences Corporation |
| Others |
Value Network & Pricing Analysis
German and Japanese precision sensor manufacturers anchor the upstream component layer for South American hemodynamic monitors, concentrating margin capture in pressure transducer and thermistor assemblies before Brazilian assembly operations add modest value through regional calibration and ANVISA compliance packaging.
Pricing Analysis
Current-generation photoplethysmography systems command 40-60% price premiums over prior-generation catheter-based platforms, while next-generation AI-integrated fluid responsiveness monitors sit at the apex of hospital procurement budgets. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform ecosystems from standalone monitors and refurbished legacy units. Price differentiation hinges on ANVISA registration tier and after-sales service bundling. Cost compression in economy-tier portable monitors is intensifying because Argentine distributors are importing refurbished units from Chilean secondary markets. Outpatient surgical centers in Rio de Janeiro exhibit the highest price sensitivity; São Paulo's Albert Einstein and Sírio-Libanês networks demonstrate the lowest.
Supply Chain Analysis
Pressure transducer feedstock and thermistor sensor substrates flow predominantly from Germany, Japan, and the United States into Brazilian final assembly operations. Raw material dependencies center on medical-grade silicone for catheter coatings, precision-machined titanium for invasive probe housings, and semiconductor substrates for signal processing chips. Single-source vulnerability concentrates in German piezoelectric crystal suppliers for Doppler ultrasound transducers. Distribution runs through hospital purchasing consortia and Catholic network buying committees that have displaced independent Argentine distributors from direct ICU access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-invasive photoplethysmography platforms threaten to commoditize invasive catheter-based revenue streams unless incumbents construct defensive moats around algorithmic differentiation and service integration.
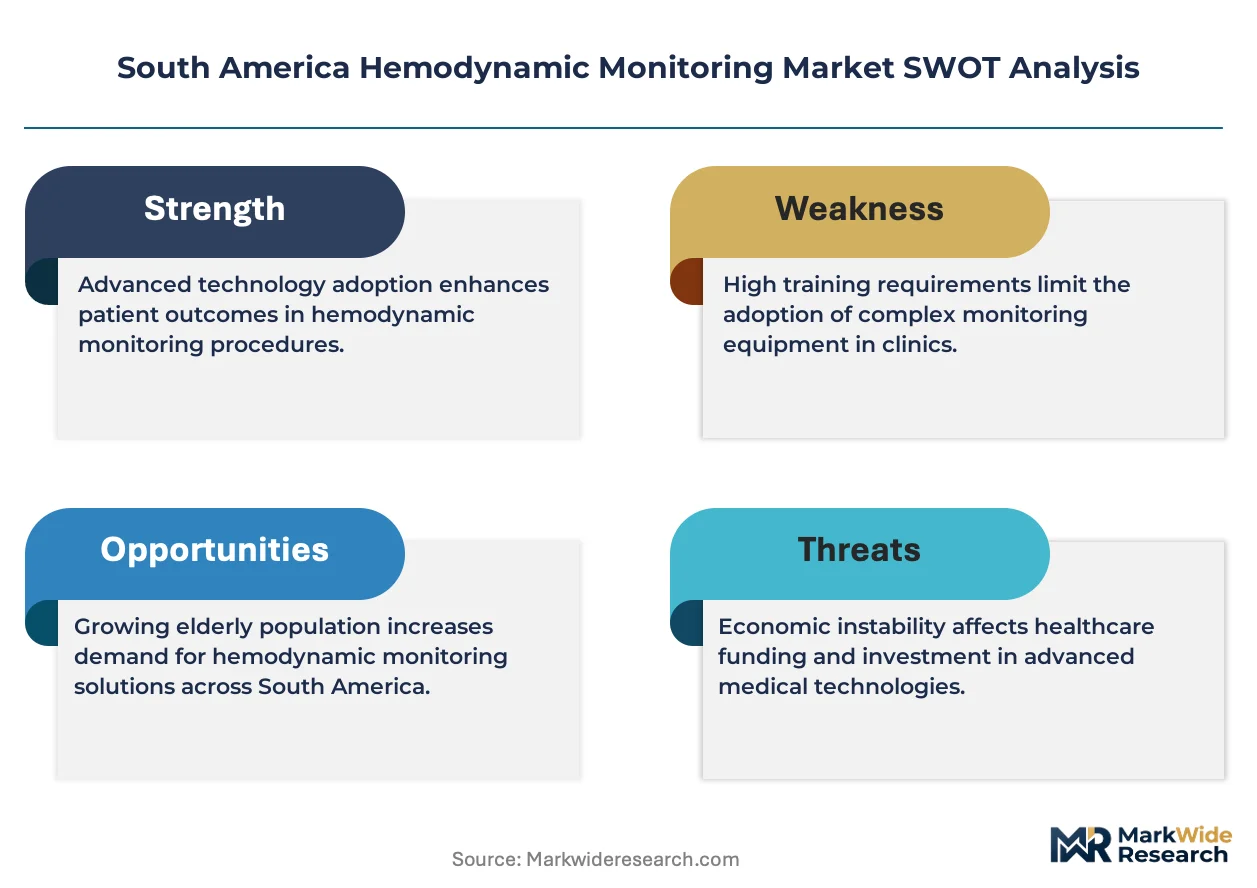
For Market Incumbents: Build switching-cost moats through deep software companion integration with Brazilian hospital EMR workflows and multi-year service contracts that embed biomedical engineers on-site. Incumbent device manufacturers must secure exclusive GPO contracts with São Paulo's southeastern hospital corridor before Cheetah Medical and LiDCO algorithm specialists capture fluid responsiveness market share. Backward integration into pressure transducer manufacturing reduces exposure to German supplier concentration. For New Entrants and Emerging Players: Mid-market ambulatory surgical centers in Buenos Aires and Córdoba represent the most penetrable entry point for plug-and-play non-invasive cardiac output devices where established Brazilian distributors lack direct relationships. Argentine Catholic hospital networks centralizing procurement through multi-facility buying committees create channel access vulnerability for incumbents. New entrants should partner with Chilean regulatory consultants to leverage Mercosur harmonization pathways for accelerated multi-country registration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors holding exclusive Brazilian state contracts that expire across the analysis window. Long-term viability in hemodynamic monitoring hinges on algorithmic IP portfolios rather than hardware manufacturing scale. Investors should monitor ANVISA reimbursement pathway negotiations for non-invasive monitoring procedure codes as the critical inflection signal for pricing power expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Accelerated Registration Pathway | Compressed approval timelines for Class III devices enable first-mover capture in Brazilian ICU modernization programs. |
| Hospital System Partnership | Exclusive service contracts with Albert Einstein and Sírio-Libanês networks lock out algorithm-specialist competitors. |
| Software Companion Development | EMR-integrated hemodynamic decision support tools embed proprietary algorithms into clinical workflow dependencies. |
| Reimbursement Strategy | Negotiated procedure codes with Brazil's unified health system determine pricing visibility for non-invasive monitoring adoption. |
| Geographic Expansion | Argentine and Chilean market entry through Brazilian distributor partnerships captures underpenetrated southern cone demand. |
Research Methodology
Cross-validation between primary interviews with ICU directors and biomedical engineers and secondary validation through ANVISA registration databases and hospital procurement records anchors the qualitative findings. Stakeholder engagement encompassed perfusionists, critical care specialists, GPO contracts managers, and medical device regulatory consultants across São Paulo, Rio de Janeiro, Buenos Aires, and Santiago. Secondary sources included ANVISA medical device registration filings, Brazilian unified health system reimbursement bulletins, Mercosur technical standard harmonization documents, and SEC 10-K disclosures from listed manufacturers. Bottom-up demand modeling from individual hospital procurement records triangulates against top-down market sizing from import duty statistics and distributor revenue estimates.
Calibration against historical ANVISA approval velocity and ICU bed expansion trajectories informs the projection framework across the analysis window. Segmentation dimensions encompass product type, end user tier, technology platform, and application intensity with geographic stratification by Brazilian state and Argentine province. CAGRs derive from fitted growth curves calibrated to documented hospital modernization budgets and infection control mandate implementation timelines. Forecast inputs incorporate photoplethysmography adoption curves and algorithmic fluid responsiveness protocol penetration rates.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Argentine import financing availability, or Mercosur tariff harmonization schedules would shift the trajectory. Forecasts reflect documented assumptions regarding ANVISA regulatory stability and hospital network consolidation velocity. Cross-checking against external hemodynamic device import statistics from Brazilian customs authorities is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Remote Electrocardiogram Monitoring Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
Asia-Pacific Patient Monitoring Market
Patient Monitoring
North America Respiratory Monitoring Market
Patient Monitoring
South America Remote Patient Monitoring Systems Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
South America Respiratory Monitoring Market