
 Global Multi-Parameter Patient Monitoring Equipment Market | 2026-2036
Global Multi-Parameter Patient Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multi-Parameter Patient Monitoring Equipment Market Foresight
Aftermarket service revenue is reconfiguring profit pools across the competitive landscape. GE HealthCare leverages its installed base of bedside monitors to secure long-term service contracts. Koninklijke Philips N.V. anchors its position through integrated central monitoring ecosystems that lock in hospital customers. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. competes aggressively on hardware cost while building out regional service networks.
Multi-parameter patient monitoring equipment comprises integrated physiological measurement systems that simultaneously track ECG, blood pressure, respiratory rate, oxygen saturation, and temperature through modular sensor arrays, typically displaying data on centralized screens or portable interfaces for clinical decision support. Portable monitors and wearable monitors are capturing accelerated demand as health systems decentralize care delivery from traditional ICU beds to emergency departments and home settings. Bedside monitors retain the largest installed base and sustain the deepest margin pools through consumables and maintenance attach rates, while central monitoring systems face consolidation pressure from software-defined platforms.
FDA clearance pathways and EU MDR conformity assessments shape product development timelines and market access costs for manufacturers targeting the United States and European Union. China's NMPA implements distinct clinical evidence requirements that delay entry for foreign device makers even as domestic champions accelerate approvals. Stakeholders must monitor how regulatory divergence between major jurisdictions affects platform standardization strategies and localization investment decisions.
Market Dynamics
The transition from hardware-centric bedside units to software-defined monitoring platforms is compressing equipment replacement cycles and forcing incumbents to rebuild revenue models around subscription-based data services rather than capital equipment sales.
Growth Catalysts
- FDA 510(k) clearance streamlining:Accelerated review pathways for predicate-device submissions reduce time-to-market for iterative monitor designs, enabling faster feature rollouts in US hospital systems.
- ICU infrastructure modernization:Health systems in Germany, the United States, and China are replacing legacy central stations with wireless-enabled distributed architectures.
- Remote patient monitoring reimbursement codes:CMS-established CPT billing categories for continuous physiological surveillance outside traditional inpatient settings create sustainable revenue streams for ambulatory monitor deployment.
Market Restraints
- EU MDR conformity assessment backlog:Notified body capacity constraints extend certification timelines for multi-parameter monitors, delaying product launches and freezing R&D budgets.
- Semiconductor supply concentration:Dependence on Taiwan and South Korea for specialized analog front-end chips creates vulnerability to geopolitical disruption and allocation rationing.
- Disposable sensor cost inflation:Single-use SpO2 probes and ECG electrodes face raw material price pressure from medical-grade polymer supply constraints.
Strategic Opportunities
- Home-based acute care expansion:CMS Hospital-at-Home waivers and comparable programs in England and Australia open addressable market for portable multi-parameter systems with cellular connectivity.
- AI-enabled early warning scoring:Integration of machine learning inference at the edge enables predictive deterioration alerts, differentiating premium monitor tiers.
- Direct-to-health-system distribution:Bypassing traditional Group Purchasing Organizations through manufacturer-owned service networks captures margin and deepens customer data access.
Industry Challenges
- Cybersecurity validation complexity:FDA premarket submission requirements for networked devices demand specialized firmware engineering talent that remains scarce.
- Legacy central station integration:Backward compatibility obligations with 1990s-era monitoring architectures consume engineering resources and delay cloud-native feature deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multi-Parameter Patient Monitoring Equipment Market |
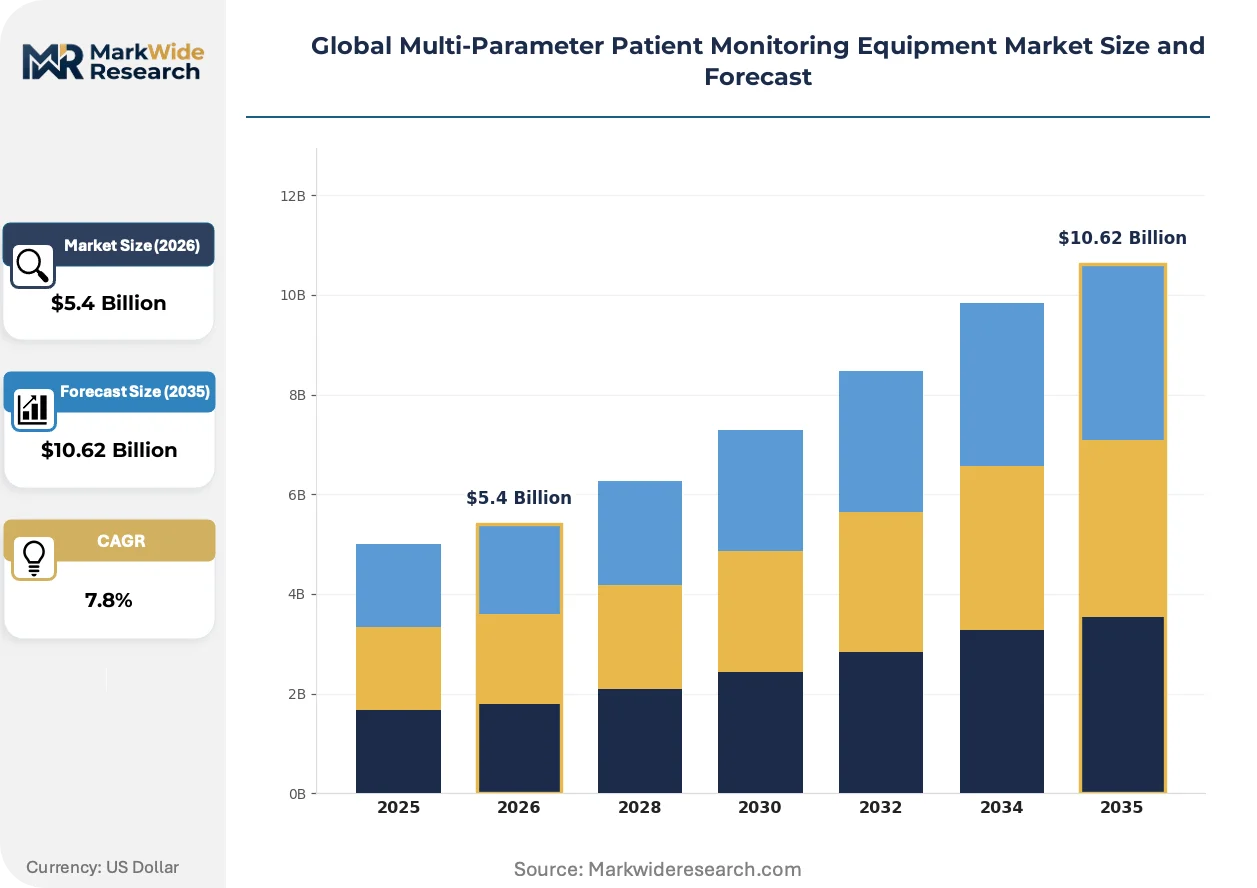
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $10.62 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedside Monitors, Portable Monitors, Central Monitoring Systems, Wearable Monitors Technology: Wireless, Wired, Bluetooth Enabled, Infrared, ECG Integrated, Respiratory Sensors Application: Critical Care, Postoperative Care, Ambulatory Monitoring, Emergency Care, Neonatal Care, Geriatric Monitoring End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Home Healthcare Providers |
| Companies Covered | GE HealthCare, Koninklijke Philips N.V., Medtronic, Nihon Kohden Corporation, Masimo Corporation, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Drägerwerk AG & Co. KGaA, Becton, Dickinson and Company, Spacelabs Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multi-Parameter Patient Monitoring Equipment Market Shifts & Advancements
Wireless sensor miniaturization and edge computing migration are dissolving the physical boundaries between traditional monitoring locations, enabling continuous surveillance across ambulatory, transport, and residential environments.
Disposable patch-based physiological sensors are collapsing the distinction between intermittent spot-checks and continuous monitoring in emergency departments. Hospital systems in the United States and Netherlands are deploying adhesive multi-parameter arrays for triage and boarding patient surveillance, eliminating cable management overhead and reducing skin integrity complications. This shift compresses capital expenditure for monitoring infrastructure while expanding addressable monitoring minutes per patient encounter.
The EU MDR's strengthened post-market surveillance requirements are extending clinical evidence obligations for legacy device families. Manufacturers must now maintain systematic literature reviews and PMCF studies for predicate devices, increasing regulatory affairs headcount and documentation burden. Class IIa multi-parameter monitors face particular scrutiny as notified bodies apply stricter benefit-risk thresholds to software-controlled diagnostic functions.
Health system procurement functions are consolidating vendor relationships through enterprise monitoring contracts that bundle hardware, software, and clinical decision support subscriptions. Large US IDNs and NHS trusts are favoring single-platform standardization over best-of-breed device selection, leveraging volume commitments for price concessions and interoperability guarantees. This concentration pressures mid-tier manufacturers without full-stack monitoring ecosystems.
Global Multi-Parameter Patient Monitoring Equipment Market Segmentation
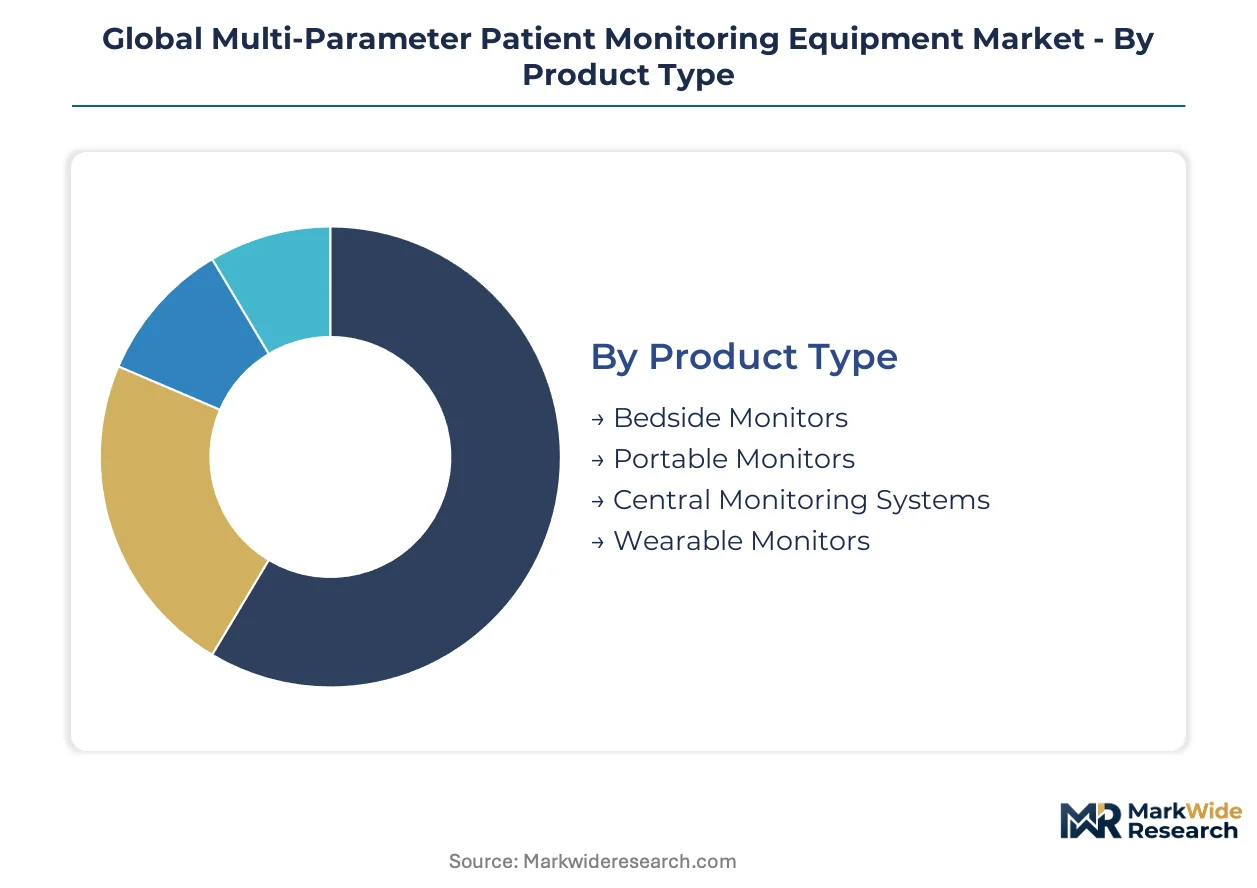
Multi-parameter patient monitoring equipment segments around care setting mobility, connectivity architecture, clinical acuity, and procurement authority. Each dimension shapes hardware specifications, software integration requirements, and service contract structures differently.
Product Type:
The use-case spectrum spans fixed ICU installations through ambulatory transport to continuous home surveillance, with each tier demanding distinct power management, display configuration, and data transmission protocols.
- Bedside Monitors:Stationary units integrate modular parameter modules with high-resolution displays for centralized nursing station visibility. Demand concentrates in Germany and the United States where ICU infrastructure modernization programs prioritize wireless-enabled bedside units with centralized alarm management and predictive analytics integration.
- Portable Monitors:Battery-powered devices with ruggedized enclosures support intra-hospital transport and emergency department flexibility. China and Australia are expanding procurement for portable systems as hospital-at-home programs and emergency medical services require continuous monitoring outside fixed installations.
- Central Monitoring Systems:Server-based architectures aggregate data from multiple bedside units onto centralized displays for surveillance economies of scale.
- Wearable Monitors:Adhesive patch and wrist-worn form factors enable unobtrusive longitudinal surveillance in ambulatory and residential settings.
Established volume favors bedside monitors; emerging adoption favors wearable monitors.
Technology:
Connectivity infrastructure determines installation cost, cybersecurity exposure, and interoperability with existing health information systems.
- Wireless:Wi-Fi and proprietary radio protocols eliminate cable management while enabling patient mobility within care facilities. United States health systems are prioritizing wireless architectures as FDA 510(k) pathways accelerate clearance for predicate wireless designs and CMS reimbursement codes support remote surveillance.
- Wired:Shielded copper connections deliver interference-resistant signal integrity for high-acuity measurements in electromagnetic-intensive environments like operating theaters.
- Bluetooth Enabled:Low-energy protocols support consumer-grade integration with smartphones and tablets for patient-facing applications.
- Infrared:Line-of-sight data transmission provides isolated connectivity in electromagnetic-sensitive zones like MRI suites.
- ECG Integrated:Dedicated analog front-end circuits with diagnostic-grade filtering for arrhythmia detection and ST-segment analysis.
- Respiratory Sensors:Impedance pneumography and capnography modules for apnea detection and ventilator synchronization.
Wireless architectures are climbing the fastest; wired installations retain dominance in surgical and high-interference zones.
Application:
Clinical acuity requirements drive sensor array complexity, alarm threshold granularity, and regulatory classification stringency.
- Critical Care:Full-parameter suites with invasive pressure monitoring and advanced arrhythmia detection for hemodynamic instability management. Demand concentrates in China and Germany where tertiary hospital expansion and ICU bed additions prioritize multi-parameter integration with ventilator and infusion pump networks.
- Postoperative Care:Automated early warning scoring and trending analytics for deterioration detection in step-down units. United States surgical centers are deploying postoperative monitoring with remote telemetry to reduce intensive care transfers and capture CMS-established reimbursement for continuous surveillance.
- Ambulatory Monitoring:Lightweight configurations for outpatient clinics and same-day surgery discharge protocols.
- Emergency Care:Rapid-deployment designs with simplified interfaces for triage throughput optimization.
- Neonatal Care:Specialized low-amplitude signal processing and apnea detection for preterm infant surveillance.
- Geriatric Monitoring:Fall-risk integration and simplified displays for cognitive accessibility in long-term care.
Critical care commands the deepest margin pools; postoperative care is gaining share fastest as step-down monitoring expands reimbursement eligibility.
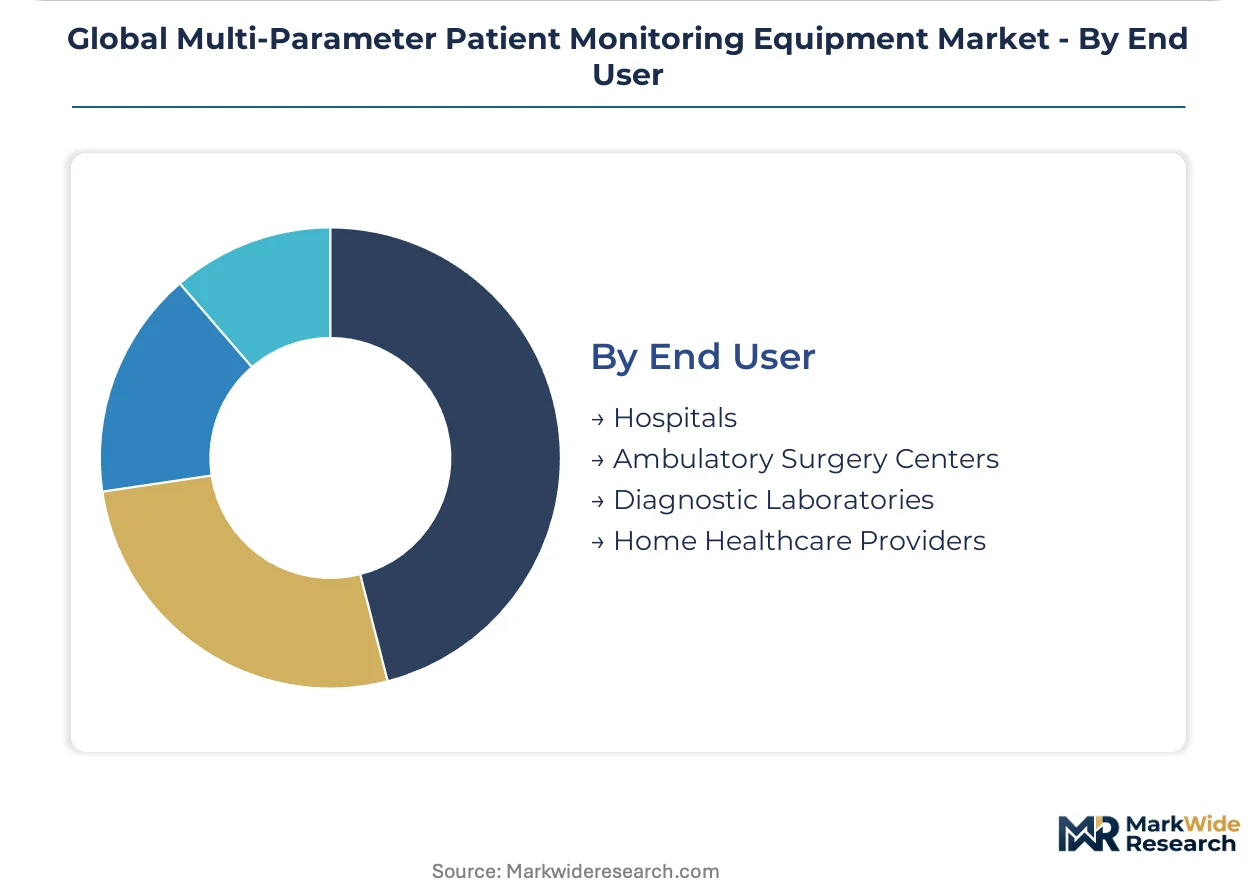
End User:
Procurement authority and capital allocation cycles segment around facility scale, reimbursement model, and regulatory oversight intensity.
- Hospitals:Enterprise-scale deployments with centralized purchasing, multi-year service contracts, and interoperability mandates. Germany and the United States anchor hospital procurement as IDN consolidation and NHS trust standardization favor single-vendor monitoring ecosystems with bundled software subscriptions.
- Ambulatory Surgery Centers:Cost-optimized configurations with streamlined parameter sets for procedural sedation and recovery monitoring. China and Australia are expanding ASC monitoring procurement as same-day surgery volume grows and regulatory frameworks align outpatient reimbursement with inpatient surveillance standards.
- Diagnostic Laboratories:Stress testing and procedure-specific monitoring for cardiac and pulmonary function assessment.
- Home Healthcare Providers:Cellular-connected portable systems for hospital-at-home and chronic disease management programs.
Hospital procurement dominates capital expenditure; home healthcare providers represent the steepest expansion trajectory as reimbursement codes mature for residential acute care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns diverge sharply across geographies. German health systems favor centralized long-term service contracts with integrated software ecosystems. Chinese hospitals prioritize hardware acquisition speed and modular upgrade paths. United States demand concentrates on wireless-enabled platforms that qualify for remote patient monitoring reimbursement codes.
United States
ICU infrastructure modernization and hospital-at-home program expansion drive procurement of wireless-enabled bedside and portable monitors. FDA 510(k) clearance pathways for predicate-device submissions accelerate time-to-market for iterative designs. The Texas Medical Center in Houston anchors enterprise-scale deployments with bundled hardware-software-service contracts.
Germany
Tertiary hospital consolidation and NHS trust standardization favor single-vendor monitoring ecosystems with predictive analytics integration. EU MDR conformity assessment requirements extend certification timelines for multi-parameter monitors. The Rhine-Ruhr metropolitan region concentrates procurement authority for university hospital networks replacing legacy central stations.
China
Domestic ICU bed expansion and emergency medical services modernization accelerate demand for portable and transport monitors. NMPA clinical evidence requirements delay foreign device entry while accelerating approvals for domestic champions. The Yangtze River Delta clusters manufacturing and R&D facilities for cost-optimized hardware production.
Australia
Hospital-at-home waivers and same-day surgery volume growth expand procurement for cellular-connected portable systems. TGA regulatory alignment with international standards facilitates faster device registration for remote surveillance platforms. Sydney and Melbourne anchor health system procurement for distributed monitoring architectures.
Netherlands
Emergency department throughput optimization and adhesive patch-based sensor deployment drive demand for disposable multi-parameter arrays. CE marking under EU MDR enables streamlined market access for wireless-enabled triage systems. The Eindhoven medical technology cluster concentrates development of miniaturized physiological sensors.
Global Multi-Parameter Patient Monitoring Equipment Market Competitive Landscape
Capability concentration sits with integrated ecosystem providers; scale advantage sits with hardware-optimized manufacturers. The market structures around three tiers: full-stack platform vendors with software-defined architectures, mid-tier specialists with regional service networks, and cost-optimized hardware fabricators. Strategic moves center on enterprise contract consolidation and backward integration into sensor manufacturing to secure supply chain control.
Among United States-based healthcare technology conglomerates, GE HealthCare and Medtronic exemplify the full-stack ecosystem archetype with installed base leverage for long-term service contracts. Koninklijke Philips N.V. anchors the integrated central monitoring tier through Dutch-origin healthcare technology consolidation. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. occupies the scale-driven hardware position with Chinese manufacturing concentration and aggressive regional expansion.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips N.V. |
| Medtronic |
| Nihon Kohden Corporation |
| Masimo Corporation |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Drägerwerk AG & Co. KGaA |
| Becton, Dickinson and Company |
| Spacelabs Healthcare |
| Others |
Supply & Pricing Matrix
Taiwan and South Korea's chokehold on analog front-end semiconductor fabrication concentrates margin capture upstream, while downstream pricing power accrues to hospital systems consolidating procurement through enterprise monitoring contracts. Disposable sensor polymer feedstock volatility transmits directly into hardware OEM margins, compressing the spread between component costs and bundled service pricing.
Pricing Analysis
Long-term service contracts with multi-year hardware refresh cycles dominate hospital procurement, displacing spot-market equipment purchases. Pricing stratifies across FDA-cleared premium tiers, CE-marked standard configurations, and economy-grade bedside units lacking predictive analytics integration. Cost compression in the economy tier is intensifying because Chinese hardware fabricators are flooding regional markets with modular upgrade-path designs. Ambulatory surgery centers exhibit highest price sensitivity; integrated delivery networks leveraging GPO-negotiated enterprise contracts show lowest.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries and supply-chain finance facilities secured by medical-grade polymer distributors are restructuring working capital requirements across the value chain. Component sourcing draws from Taiwan and South Korea for specialized chips, China for PCB fabrication and final assembly, and Germany for precision sensor modules. Single-source vulnerability concentrates in analog front-end semiconductor supply. Distribution runs through manufacturer-owned service networks and regional biomedical equipment distributors serving hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through health system consolidation, with United States IDNs and NHS trust standardization programs reducing vendor count per enterprise monitoring contract from six to two platform providers.
For Market Incumbents: Build installed-base moats through predictive analytics software lock-in and consumables attach-rate maximization. Deepen backward integration into SpO2 sensor manufacturing to offset polymer cost inflation. Defend against software-defined monitoring platforms by accelerating cloud-native feature deployment before legacy central station obligations consume R&D bandwidth. For New Entrants and Emerging Players: Pursue white-space penetration in hospital-at-home cellular-connected portable systems where reimbursement codes are maturing fastest. Target Australian and Dutch emergency department adhesive patch deployments where triage throughput optimization budgets remain less consolidated. Lead with direct-to-health-system distribution bypassing GPO intermediaries to capture margin and deepen clinical workflow data access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional service network operators holding long-term hospital contracts but lacking software-defined platform capabilities. Five-to-ten year viability hinges on successful subscription revenue model transition away from capital equipment sales. Monitor FDA 510(k) clearance velocity for predicate wireless designs as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment acceleration unlocks German and Dutch hospital procurement access. |
| Hospital System Partnership | Texas Medical Center-style bundled contracts secure multi-year service revenue and data exclusivity. |
| Software Companion Development | AI-enabled early warning scoring differentiates premium monitor tiers against hardware-optimized competitors. |
| Reimbursement Strategy | CMS remote patient monitoring CPT code qualification enables sustainable ambulatory monitor deployment economics. |
| FDA Submission | 510(k) predicate-device clearance streamlining accelerates iterative wireless design time-to-market. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital biomedical engineers, GPO contracts managers, ICU clinical directors, and aftermarket service heads. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, CMS reimbursement code filings, and hospital procurement database aggregators. Bottom-up equipment shipment modeling and top-down health system capital expenditure triangulation anchored volume estimates.
Calibration against historical wireless bedside monitor adoption curves and portable monitor deployment in hospital-at-home programs shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product mobility tier, connectivity architecture, clinical acuity application, and procurement authority level. CAGRs derived from equipment replacement cycle compression rates and software subscription revenue mix shifts. Forecast inputs incorporated ICU bed expansion trajectories in China and Germany alongside CMS reimbursement code eligibility expansion.
Macroeconomic conditions sit as an overlay; deviation in semiconductor allocation rationing, medical-grade polymer supply constraints, or health system capital expenditure freezes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory clearance velocity and reimbursement code maturation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
Global Vital Sign Monitoring Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
Medical Telemetry Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
Central Patient Monitoring System Market
Patient Monitoring
Transcutaneous Monitors Market
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
South Africa Patient Monitoring Market