
 North America Wearable Ambulatory Monitoring Devices Market | 2026-2036
North America Wearable Ambulatory Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wearable Ambulatory Monitoring Devices Market Insights
Canada's wearable device manufacturing corridor is narrowing as domestic assembly scales toward serving U.S. health system procurement. Medtronic leverages its cardiac rhythm management heritage to anchor hospital contracts across the Great Lakes region. iRhythm Technologies specializes in AI-enabled arrhythmia detection, sustaining premium positioning in cardiology service lines. Abbott Laboratories competes through glucose-sensor integration, extending its diabetes platform into ambulatory cardiac overlap.
Wearable ambulatory monitoring devices combine biosensors, wireless telemetry modules, and skin-adhesive substrates to capture electrophysiological signals during normal patient activity, transmitting data via Bluetooth or cellular protocols to cloud-based clinical platforms for remote diagnostic interpretation. Medical Monitors command the deepest margin pools due to reimbursement codes tied to diagnostic-grade data, while Smartwatches occupy the highest unit-volume tier through consumer-direct channels and employer wellness subsidies. Wearable Sensors represent the fastest-expanding technology layer as multi-modal arrays combining photoplethysmography, accelerometry, and galvanic skin response displace single-parameter legacy devices.
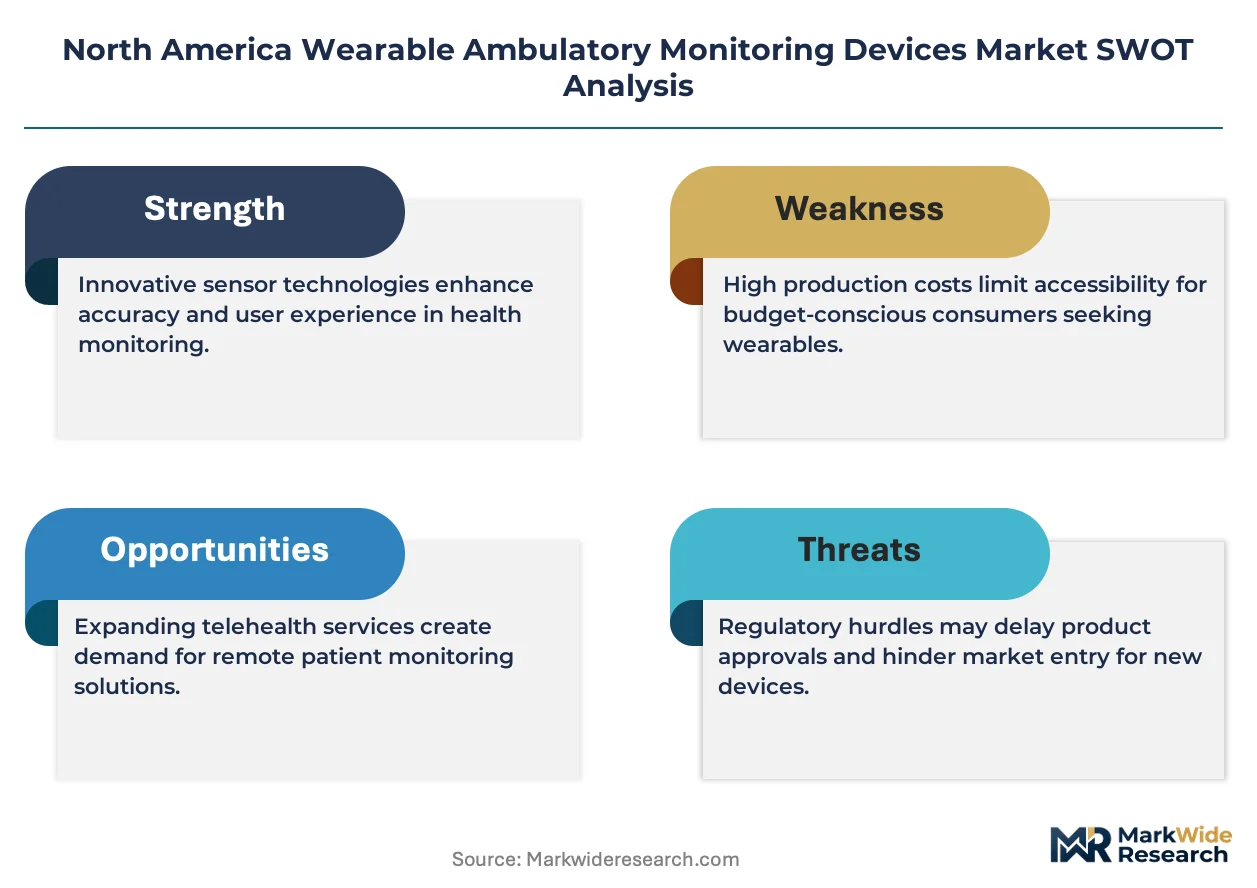
FDA Software as a Medical Device frameworks and HIPAA interoperability mandates shape product architecture, forcing manufacturers to embed 21 CFR Part 820 quality systems and encrypted data pipelines from initial design phases. The Federal Communications Commission regulates spectrum allocation for cellular-enabled monitors, directly constraining device connectivity options in rural coverage zones. Stakeholders must monitor pending CMS remote therapeutic monitoring reimbursement expansions to determine whether home-based chronic disease applications achieve payment parity with clinic-administered diagnostics.
Market Dynamics
Patch-based cardiac monitors are compressing diagnostic timelines from weeks to days, forcing outpatient cardiology departments to reconfigure staffing models around remote interpretation workflows rather than in-clinic telemetry.
Growth Catalysts
- FDA Software as a Medical Device frameworks:Pre-certification pathways compress commercialization timelines for algorithm-driven diagnostics. Manufacturers embed quality systems earlier in development cycles.
- Southeastern U.S. health system consolidation:Large-scale procurement contracts aggregate demand across multi-hospital networks, creating volume commitments that justify manufacturing scale.
- Photoplethysmography sensor miniaturization:Multi-modal biosensor arrays now fit adhesive patches smaller than conventional Holter monitors, expanding patient compliance in ambulatory settings.
Market Restraints
- Cellular coverage gaps:FCC spectrum allocation leaves rural zones with unreliable connectivity for real-time cardiac data transmission, limiting device functionality outside metropolitan corridors.
- Silicon wafer supply concentration:Advanced biosensor fabrication depends on concentrated Asian foundry capacity, exposing North American device makers to input bottlenecks.
- HIPAA interoperability mandates:Encrypted data pipeline requirements add architectural complexity that extends design verification timelines for smaller manufacturers.
Strategic Opportunities
- CMS remote therapeutic monitoring expansion:Pending reimbursement parity for home-based chronic disease applications would unlock diabetes-cardiac comorbidity monitoring at scale.
- Canada-U.S. manufacturing corridor integration:Ontario and Quebec assembly facilities position to serve cross-border procurement with tariff-advantaged production.
- AI-enabled arrhythmia detection:Machine learning classification of atrial fibrillation patterns converges with cloud-based clinical platforms to reduce specialist interpretation burden.
Industry Challenges
- 21 CFR Part 820 quality system implementation:Smaller device developers face capex burdens building compliant design controls and risk management documentation from inception.
- Bluetooth-cellular protocol integration:Dual-mode connectivity architectures require specialized firmware engineering talent that concentrates at established cardiac rhythm management firms.
- Legacy EHR interoperability:Cloud-based monitoring platforms encounter friction integrating diagnostic-grade data feeds into hospital information systems with outdated HL7 standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wearable Ambulatory Monitoring Devices Market |
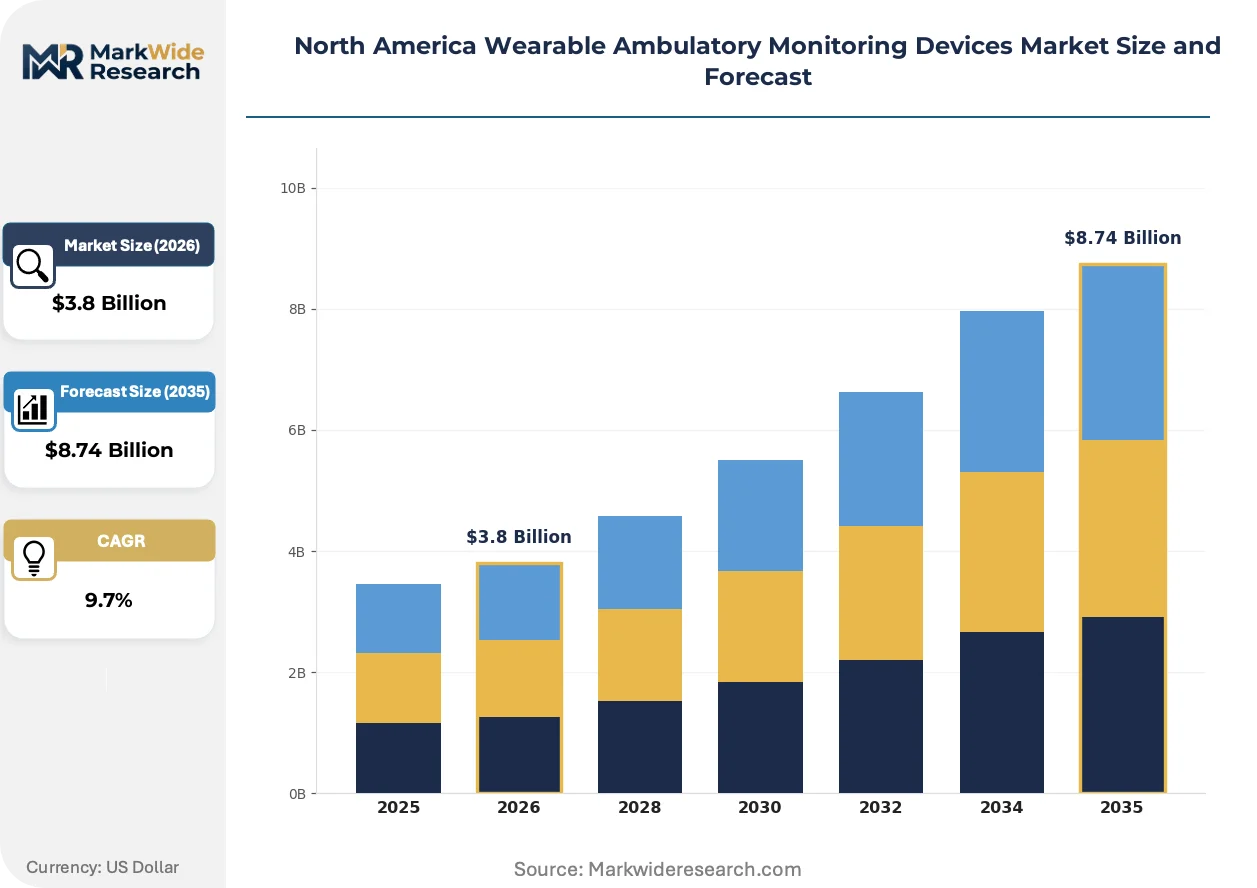
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Medical Monitors, Smart Clothing Technology: Bluetooth, Wi-Fi, NFC, Cellular, Wearable Sensors End User: Clinics, Hospitals, Home Care, Fitness Enthusiasts Application: Fitness Tracking, Heart Rate Monitoring, Sleep Analysis, Chronic Disease Management |
| Companies Covered | Koninklijke Philips NV, Boston Scientific, Medtronic, ZOLL Medical Corporation, iRhythm Technologies, GE Healthcare, BioTelemetry, Medicomp Inc, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wearable Ambulatory Monitoring Devices Market Trends and Innovations
Cardiac monitoring hardware is fragmenting into specialized form factors while software layers consolidate around platform-based interpretation services, compressing the value chain toward algorithmic diagnostics.
Multi-parameter biosensor arrays are migrating from single-purpose Holter replacements to continuous vital sign platforms capturing electrocardiography, photoplethysmography, and accelerometry in one adhesive substrate. Outpatient cardiology departments in the Great Lakes region adopt these devices fastest, driven by health system contracts demanding comprehensive ambulatory data. This convergence is compressing the market for standalone pulse oximeters and activity trackers as integrated patches displace multiple single-function wearables.
FDA pre-certification programs for Software as a Medical Device are accelerating algorithm updates without full 510(k) resubmissions, enabling faster clinical validation cycles for AI-driven arrhythmia classifiers. Manufacturers now architect products with modular software stacks separable from hardware submissions. Cardiac patch developers with established quality management systems capture disproportionate benefit, while newer entrants face documentation burdens that delay market entry.
Health system procurement departments are consolidating vendor relationships around integrated cardiac-diabetes monitoring platforms, unbundling device supply from interpretation service contracts. Large integrated delivery networks in Texas and Florida negotiate multi-year agreements covering hardware, cloud connectivity, and specialist overread services in single-source arrangements. This bundling concentrates purchasing power among three to four vendor ecosystems, marginalizing standalone device manufacturers without service-layer capabilities.
North America Wearable Ambulatory Monitoring Devices Market Segmentation
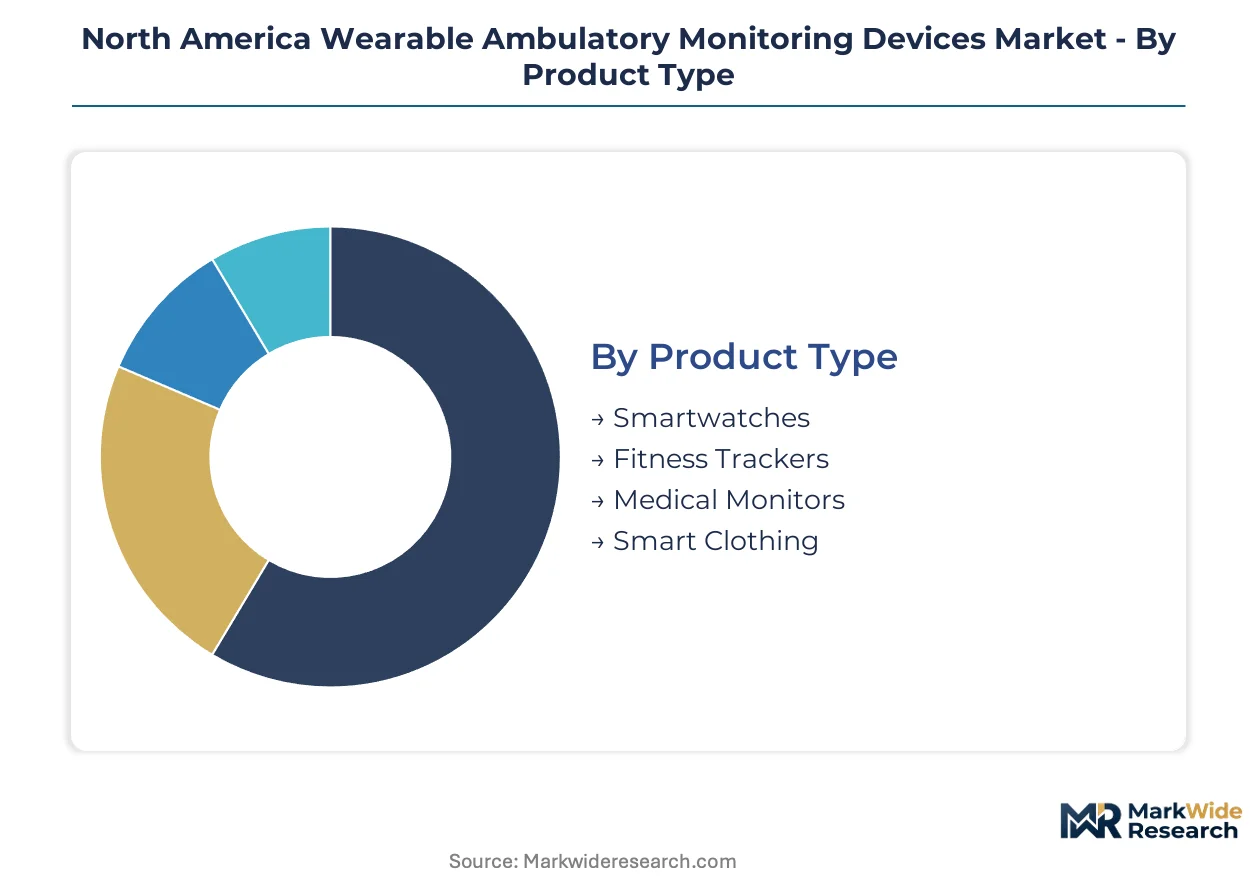
Segmentation in the North America Wearable Ambulatory Monitoring Devices Market reveals distinct margin pools and procurement channels. Product architecture diverges sharply between consumer-direct wellness devices and diagnostic-grade medical hardware governed by FDA pathways.
Product Type:
Cost tier stratification separates consumer wellness hardware from reimbursed medical equipment, with reimbursement eligibility determining margin structure and distribution channel.
- Smartwatches:Consumer-grade wrist-worn devices integrate photoplethysmography and accelerometry for activity and heart rate estimation. Demand concentrates through employer wellness subsidies in the southeastern United States, where self-insured employers aggregate volume commitments across multi-state workforces.
- Fitness Trackers:Simplified sensor arrays prioritize step counting and sleep staging over clinical-grade electrophysiology. The steepest expansion runs through direct-to-consumer channels, though HIPAA interoperability mandates constrain data portability into clinical workflows.
- Medical Monitors:FDA-cleared patch-based cardiac monitors capture diagnostic-grade electrocardiography with adhesive substrates. Reimbursement codes tied to arrhythmia detection sustain premium positioning in outpatient cardiology departments across the Great Lakes region.
- Smart Clothing:Textile-integrated conductive fibers embed biosensing into garments for continuous vital sign capture without skin-adhesive interfaces. Early adoption centers on research protocols and elite athletic programs pending clinical validation.
Medical Monitors capture the highest per-unit margins through diagnostic reimbursement. Smartwatches gain volume fastest through consumer-direct and employer channels.
Technology:
Connectivity architecture determines real-time capability versus store-and-forward limitations, with spectrum allocation and power constraints shaping hardware design tradeoffs.
- Bluetooth:Short-range wireless protocol dominates consumer wearables for smartphone-tethered data sync. Battery efficiency supports multi-day operation but requires patient proximity to relay devices, limiting rural ambulatory applications.
- Cellular:Embedded LTE/5G modules enable direct-to-cloud transmission without intermediary smartphones. FCC spectrum gaps in rural coverage zones constrain functionality outside metropolitan corridors despite superior patient mobility.
- Wi-Fi:Higher bandwidth supports firmware updates and bulk data offload in home or clinical settings. Power consumption relegates this protocol primarily to bedside or stationary monitoring configurations.
- NFC:Near-field communication facilitates device pairing and authentication with minimal power draw. Clinical deployment concentrates on medication adherence and patient identity verification rather than continuous physiological streaming.
- Wearable Sensors:Multi-modal biosensor arrays combining photoplethysmography, accelerometry, and galvanic skin response displace single-parameter legacy devices. Silicon wafer supply concentration in Asian foundries exposes North American manufacturers to input bottlenecks.
Bluetooth anchors the installed base across consumer applications. Wearable Sensors climb fastest as multi-parameter integration replaces discrete single-function hardware.
End User:
Customer type segmentation maps directly to procurement authority, with health system consolidation in the southeastern United States aggregating hospital and clinic demand into multi-year vendor contracts.
- Hospitals:Inpatient and emergency departments deploy ambulatory monitors for discharge planning and post-acute surveillance. Health system consolidation across Texas and Florida creates large-scale procurement contracts covering hardware, connectivity, and interpretation services.
- Clinics:Outpatient cardiology departments accelerate adoption of patch-based cardiac monitors for arrhythmia detection. Staffing models reconfigure around remote interpretation workflows rather than in-clinic telemetry.
- Home Care:Post-acute and chronic disease management applications await CMS reimbursement parity determination. Pending remote therapeutic monitoring expansions would unlock diabetes-cardiac comorbidity monitoring at scale.
- Fitness Enthusiasts:Consumer-direct purchasers drive unit volume through wellness-oriented feature sets. Data portability friction limits clinical utility despite hardware sophistication.
Hospitals command the concentrated procurement volume. Home Care presents the steepest expansion trajectory contingent on reimbursement policy evolution.
Application:
Use case maturity varies from established fitness tracking to emerging chronic disease management, with diagnostic-grade applications requiring FDA clearance and clinical workflow integration.
- Heart Rate Monitoring:Photoplethysmography-based pulse detection spans consumer smartwatches through FDA-cleared patch monitors. Algorithm-driven arrhythmia classification converges with cloud platforms to reduce specialist interpretation burden.
- Chronic Disease Management:Integrated glucose-cardiac monitoring platforms target diabetes-cardiovascular comorbidity populations. Abbott Laboratories extends its diabetes sensor platform into ambulatory cardiac overlap through multi-parameter biosensor convergence.
- Fitness Tracking:Activity quantification and caloric expenditure estimation dominate consumer wearable feature marketing. Employer wellness programs in the southeastern United States aggregate demand across self-insured populations.
- Sleep Analysis:Accelerometry and heart rate variability proxy sleep staging quality for consumer applications. Clinical validation gaps limit reimbursement eligibility despite consumer feature proliferation.
Heart Rate Monitoring holds the established clinical utility base. Chronic Disease Management shows the steepest expansion potential as multi-parameter platforms converge metabolic and cardiovascular surveillance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device assembly concentrates in Ontario and Quebec facilities serving cross-border procurement, while U.S. demand clusters in southeastern health systems and Great Lakes cardiology corridors.
United States
Patch-based cardiac monitors penetrate outpatient cardiology departments across Texas and Florida health systems. FDA Software as a Medical Device pre-certification pathways compress commercialization timelines for algorithm-driven diagnostics. The Great Lakes region anchors hospital contract aggregation through established cardiac rhythm management vendor relationships.
Canada
Ontario and Quebec manufacturing corridors scale toward tariff-advantaged production for U.S. procurement. Health Canada regulatory alignment with FDA frameworks facilitates cross-border device certification. Toronto-area assembly facilities capture contract manufacturing volume from consolidated North American health networks.
Mexico
Medical device maquiladoras in Baja California and Chihuahua supply component assembly for U.S.-bound cardiac monitors. COFEPRIS regulatory harmonization efforts with FDA standards streamline import documentation. Tijuana manufacturing clusters specialize in biosensor substrate fabrication and adhesive patch assembly.
North America Wearable Ambulatory Monitoring Devices Market Competitive Landscape
Diversified medical technology conglomerates and specialized cardiac monitoring firms split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: integrated health system contractors, AI-enabled diagnostic specialists, and multi-parameter biosensor platform builders. Consolidation pressures favor vendors with bundled hardware-connectivity-interpretation offerings. Competitive moves center on health system procurement contract capture and FDA pre-certification pathway navigation.
Among diversified medical technology conglomerates, Koninklijke Philips NV and GE Healthcare exemplify integrated health system contractors with broad diagnostic imaging heritage. Medtronic occupies a position within the cardiac rhythm management specialist tier, leveraging established hospital relationships. iRhythm Technologies represents the AI-enabled diagnostic archetype, anchoring cloud-based arrhythmia interpretation services. Abbott Laboratories sits within the multi-parameter biosensor platform tier, extending metabolic monitoring capabilities into cardiac overlap applications.
| Leading Market Players |
|---|
| Koninklijke Philips NV |
| Boston Scientific |
| Medtronic |
| ZOLL Medical Corporation |
| iRhythm Technologies |
| GE Healthcare |
| BioTelemetry |
| Medicomp Inc |
| Abbott Laboratories |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Ontario and Quebec assembly facilities is compressing contract manufacturing margins while simultaneously accelerating tariff-advantaged production bids for U.S. health system procurement, forcing suppliers to absorb input volatility to maintain volume commitments.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across diagnostic-grade wearable monitors. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected interpretation services from hardware-only transactions and consumer wellness devices. Cost compression in the standard tier is intensifying because health system procurement departments unbundle device supply from service contracts. Fitness enthusiasts exhibit the highest price sensitivity through direct-to-consumer channels, while hospital purchasing committees prioritize diagnostic reimbursement eligibility over unit cost.
Supply Chain Analysis
Silicon wafer fabrication feeds from concentrated foundry capacity in Taiwan, South Korea, and China, exposing North American device makers to input bottlenecks. Advanced biosensor arrays draw from photodiode substrates, flexible printed circuit boards, and medical-grade adhesive polymers. Single-source vulnerability concentrates in Asian semiconductor foundries serving multi-modal sensor integration. Distribution runs through integrated delivery networks and group purchasing organizations aggregating demand across multi-hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as CMS remote therapeutic monitoring reimbursement expansions unlock home-based chronic disease applications at scale, accelerating penetration beyond clinic-administered diagnostics.
For Market Incumbents: Build switching-cost moats through embedded cloud interpretation platforms that integrate diagnostic-grade data feeds directly into hospital EHR systems. Deepen backward integration into biosensor substrate fabrication to offset silicon wafer supply concentration. Defend against AI-enabled diagnostic specialists by accelerating FDA Software as a Medical Device pre-certification for algorithm updates.
For New Entrants and Emerging Players: Establish a beachhead in the home care segment pending reimbursement parity determination, where incumbent service-layer bundling remains weakest. Target fitness-to-clinical data portability as the most penetrable white space, addressing HIPAA interoperability friction that constrains consumer device clinical utility. Pursue direct partnerships with self-insured employers in the southeastern United States as a go-to-market angle bypassing health system procurement consolidation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-parameter biosensor platform development as FDA quality system requirements extend design verification timelines. Long-term viability favors vendors with bundled hardware-connectivity-interpretation capabilities serving consolidated health networks. Acquisition targets should demonstrate established 21 CFR Part 820 quality management systems. Monitor CMS remote therapeutic monitoring reimbursement determinations as the primary inflection signal for home care segment viability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Pre-certification | Accelerates algorithm update cycles without full 510(k) resubmissions for AI-driven arrhythmia classifiers. |
| Hospital System Partnership | Locks in multi-year procurement contracts covering hardware, connectivity, and specialist overread services. |
| Backward Integration into Biosensor Fabrication | Reduces exposure to Asian foundry concentration for silicon wafer and photodiode substrate supply. |
| Software Companion Development | Enables modular software stacks separable from hardware submissions under FDA quality frameworks. |
| Reimbursement Strategy | Positions home-based chronic disease applications for CMS remote therapeutic monitoring payment parity. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and outpatient cardiology department heads and refined through secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and SEC 10-K disclosures from diversified medical technology conglomerates. Bottom-up demand modeling across product type, technology, end user, and application segments was triangulated with top-down market sizing.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include device form factor, connectivity protocol, procurement channel authority, diagnostic versus wellness application, and regional health system consolidation pattern. CAGRs were derived from weighted average growth trajectories across these segments. Forecast inputs incorporated FDA clearance pipeline velocity and health system contract renewal cycles.
Macroeconomic conditions sit as an overlay; deviation in CMS reimbursement policy, cellular spectrum allocation decisions, or silicon wafer pricing would shift the trajectory substantially. Forecasts reflect documented assumptions regarding regulatory pathway timelines and procurement consolidation momentum. Cross-checking against hospital capital expenditure surveys and GPO contract announcement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Lung Monitoring Devices Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
Respiratory Monitoring Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Continuous Cardiac Monitoring Devices Market
Patient Monitoring
Italy Patient Monitoring Market
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
MRI Pulse Oximeters Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Patient Temperature Management Systems Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market