
 Cardiovascular Diagnostic and Monitoring Devices Market | 2026-2036
Cardiovascular Diagnostic and Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Diagnostic and Monitoring Devices Market Outlook
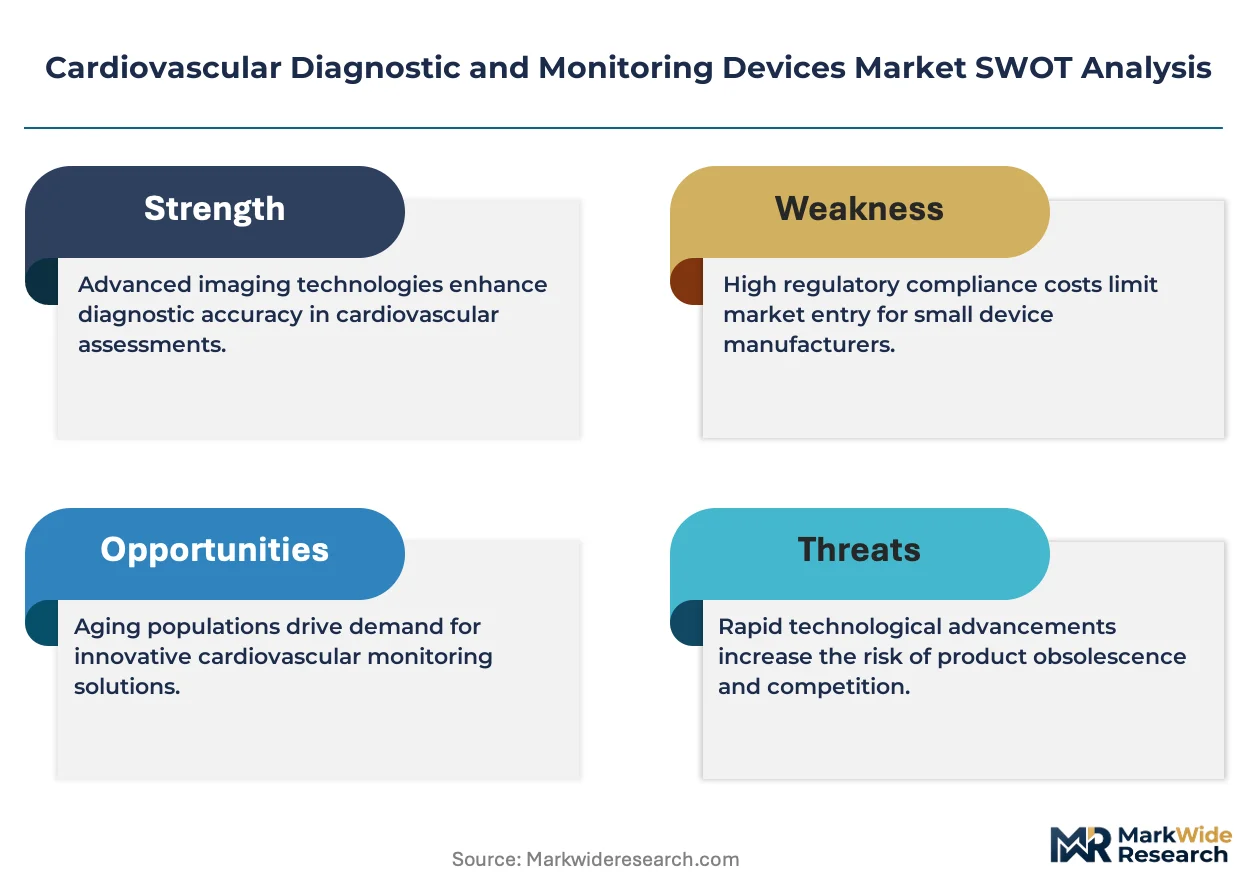
The EU Medical Device Regulation is rebalancing procurement criteria toward long-term clinical evidence and post-market surveillance for connected cardiac systems. GE HealthCare leverages its installed base of imaging platforms to cross-sell integrated monitoring workflows. Koninklijke Philips N.V. anchors its position through remote patient monitoring infrastructure that spans hospital and home settings. Medtronic differentiates via implantable loop recorders with extended battery longevity.
Cardiovascular diagnostic and monitoring devices encompass electrophysiological sensors, ultrasonic transducers, and wireless telemetry modules that capture cardiac electrical activity, structural function, and hemodynamic parameters for clinical decision-making. These systems process signals through analog-to-digital conversion at sampling rates exceeding 250 Hz to enable real-time arrhythmia detection and ischemia monitoring. Echocardiography devices command substantial margin pools due to capital intensity and proprietary probe technology. Wearable technology segments are expanding fastest as ambulatory electrocardiogram monitors gain prescription status for post-ablation surveillance. Home care settings represent an emerging channel where reimbursement codes are still crystallizing.
The FDA's premarket notification pathway and the EU MDR's clinical evaluation requirements shape product development timelines and market access costs for manufacturers. Japan's PMDA imposes additional quality system inspections that filter out smaller entrants from its cardiology device registry. China's NMPA has accelerated review timelines for innovative cardiac monitors under its priority review channel. Stakeholders must monitor evolving reimbursement frameworks for remote physiological monitoring as payer policies fragment across national health systems.
Market Dynamics
Ambulatory monitoring programs are restructuring hospital procurement toward subscription-based telemetry services that integrate electrophysiology data with electronic health records, compressing capital equipment cycles into recurring revenue arrangements.
Growth Catalysts
- EU MDR Clinical Evidence Mandate:Post-market surveillance requirements for connected cardiac systems are elevating barriers for non-compliant suppliers, concentrating procurement among established platform vendors with longitudinal data repositories.
- Remote Patient Monitoring Infrastructure:Reimbursement codes for home-based electrocardiogram surveillance are expanding prescription volumes for wearable loop recorders across cardiology clinic networks.
- Artificial Intelligence Arrhythmia Detection:Machine learning algorithms embedded in implantable devices are reducing false-positive alert rates, improving clinical workflow efficiency and device retention metrics.
Market Restraints
- Proprietary Probe Manufacturing Concentration:Echocardiography transducer production clusters in specialized German and Japanese component suppliers, creating single-source vulnerability for ultrasound system OEMs.
- EU MDR Technical Documentation Burden:Clinical evaluation report requirements for Class III cardiac monitors extend regulatory timelines by 18-24 months versus previous directives.
- Disposable Electrode Cost Volatility:Silver-silver chloride sensor material prices fluctuate with precious metals markets, compressing margins on high-volume Holter monitoring consumables.
Strategic Opportunities
- Underpenetrated Home Care Channel:Post-acute cardiac rehabilitation settings in the United States lack standardized remote monitoring protocols, creating first-mover advantage for integrated platform vendors.
- AI-ECG Convergence:Deep learning interpretation of single-lead ambulatory traces is enabling consumer-grade devices to achieve diagnostic parity with clinical Holter systems.
- Japan PMDA Priority Review:Accelerated approval pathways for innovative cardiac monitors reduce time-to-market for wireless patch technologies against domestic incumbents.
Industry Challenges
- Electrophysiology Data Scientist Scarcity:Signal processing expertise combining cardiac physiology with embedded systems engineering commands premium compensation, constraining R&D expansion at mid-tier manufacturers.
- Legacy EMR Integration Complexity:Hospital information systems built on HL7 v2 messaging require costly middleware development to ingest real-time telemetry streams from cloud-connected devices.
- ISO 13485 Certification Timeline:Quality management system audits for software-as-medical-device offerings average 14 months, delaying commercial launches for algorithm-dependent diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Diagnostic and Monitoring Devices Market |
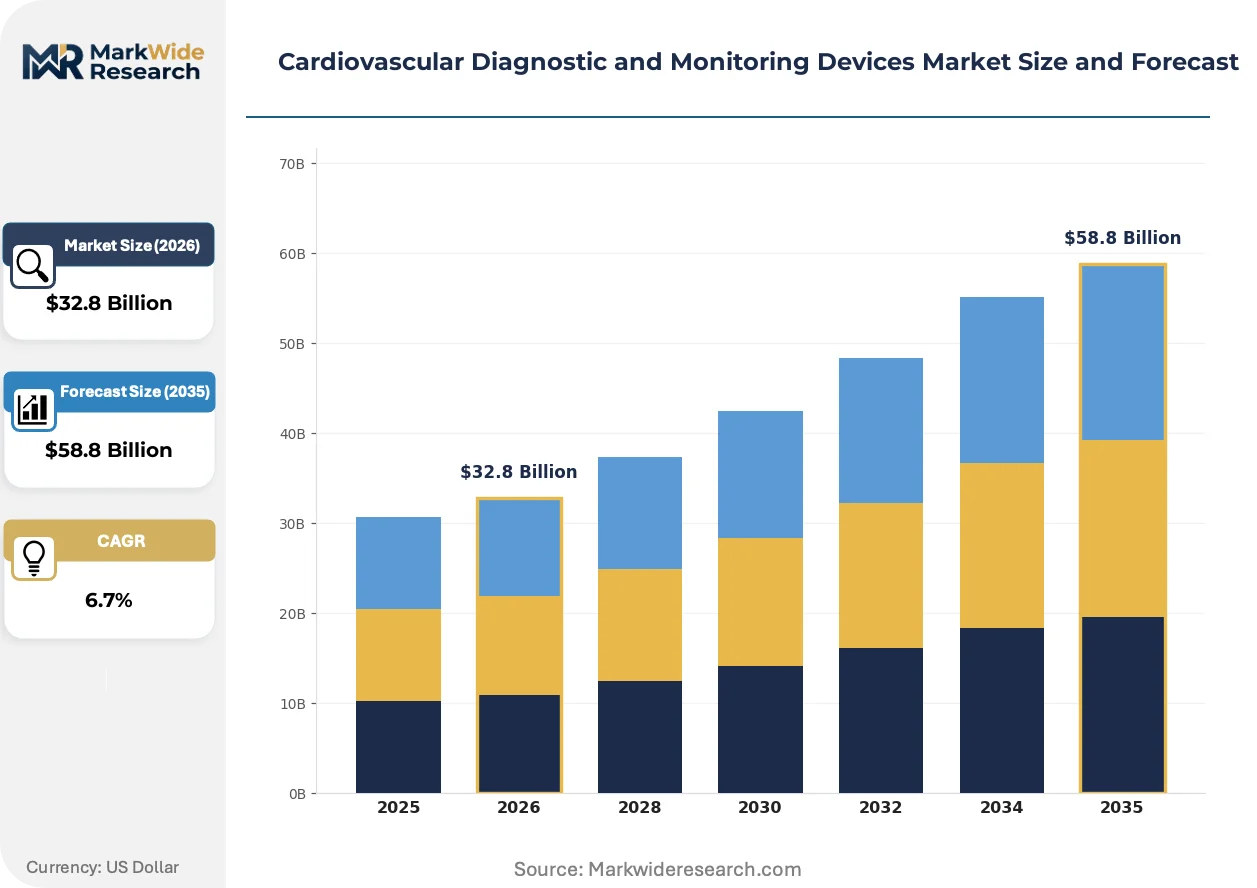
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $58.8 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Electrocardiogram Monitors, Echocardiography Devices, Holter Monitors, Implantable Loop Recorders Technology: Wearable Technology, Remote Patient Monitoring, Telehealth Systems, Digital Stethoscopes End User: Cardiology Clinics, Hospitals, Home Care Settings, Emergency Services Application: Heart Rate Monitoring, Arrhythmia Detection, Blood Pressure Measurement, Cardiovascular Risk Assessment |
| Companies Covered | GE HealthCare, Koninklijke Philips N.V., Medtronic, Abbott, Boston Scientific Corporation, Nihon Kohden Corporation, Biotronik, ZOLL Medical Corporation, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Diagnostic and Monitoring Devices Market Strategic Shifts
Digital biomarker extraction from continuous cardiac signals is displacing episodic testing paradigms, while regulatory frameworks scramble to validate software-driven diagnostic claims against traditional hardware-centric approval pathways.
Photoplethysmography-based blood pressure estimation is electrifying consumer wearable development, with optical sensors now achieving pulse waveform fidelity sufficient for hypertension screening. Apple and Samsung integrate these modules into smartwatch form factors, forcing traditional Holter manufacturers to defend clinical-grade accuracy as a differentiation anchor. The technology is compressing addressable market boundaries between wellness devices and prescription diagnostics.
China's NMPA priority review channel for innovative cardiac monitors is accelerating domestic approvals for patch-based electrocardiogram systems, compressing regulatory gaps with FDA and PMDA timelines. Domestic manufacturers leverage this tailwind to capture share in hospital procurement tenders that previously favored multinational incumbents. The policy shift is reshaping competitive positioning across Asia-Pacific distribution networks.
Hospital procurement committees now unbundle device acquisition from data analytics subscriptions, treating algorithm access as a separate line item negotiable across contract terms. Cardiology departments in Germany's university hospital networks pioneered this bifurcation, with purchasing autonomy shifting from biomedical engineering to chief medical information officers. The behavioral pivot is fragmenting vendor lock-in and elevating interoperability standards as primary selection criteria.
Cardiovascular Diagnostic and Monitoring Devices Market Segmentation
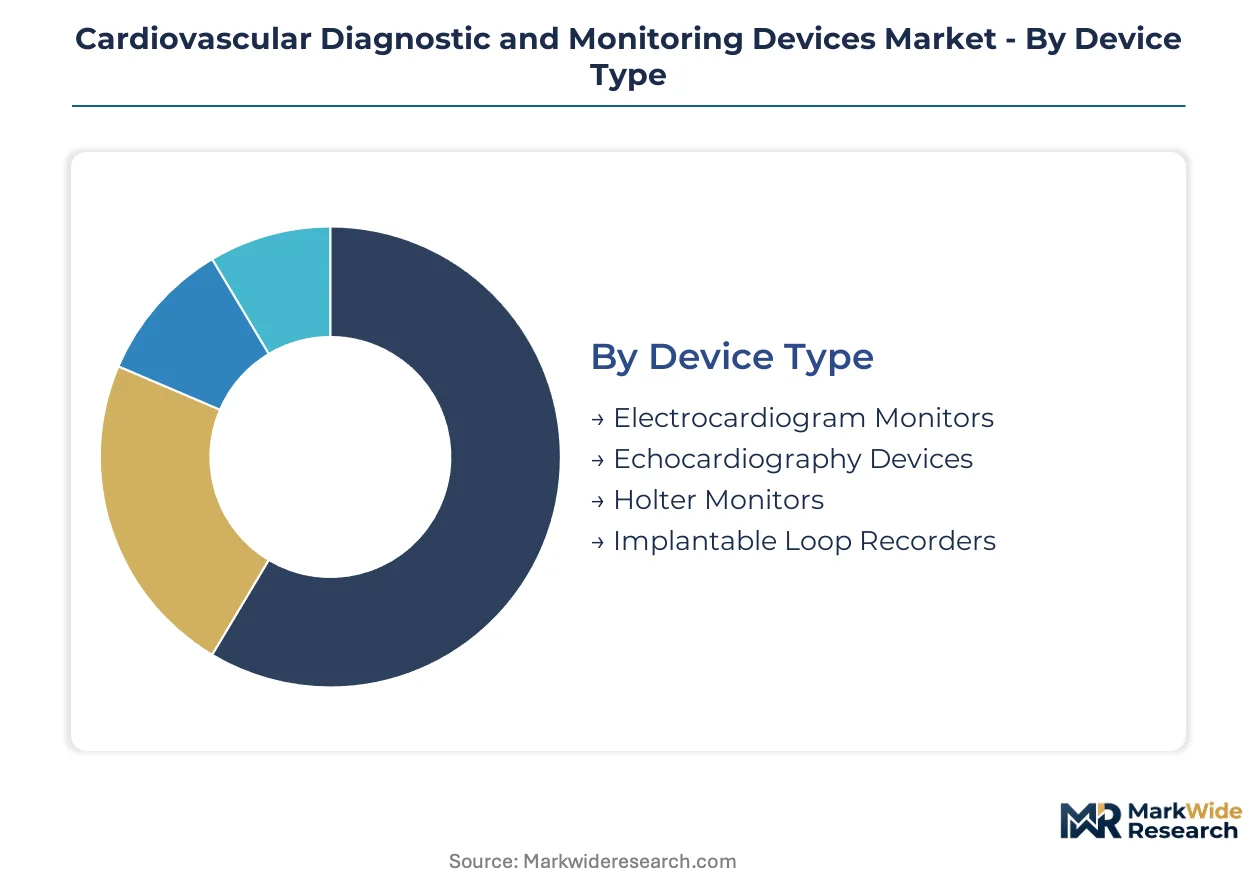
Segmentation in cardiovascular diagnostics reveals how device architectures align with care delivery models. Standalone hospital systems demand different integration depths than distributed home monitoring networks. Procurement committees weight capital intensity against recurring telemetry revenue when evaluating category mix.
Device Type:
Integration depth varies sharply—implantable systems require surgical workflow embedding while external monitors operate as modular peripherals.
- Electrocardiogram Monitors:Surface electrode arrays capture cardiac electrical activity through 3-12 lead configurations with sampling rates exceeding 250 Hz. Hospital telemetry units in Germany's university hospital networks are standardizing on wireless bedside monitors that stream to centralized nursing stations, driven by EU MDR post-market surveillance mandates for continuous data logging.
- Echocardiography Devices:Piezoelectric transducer assemblies generate ultrasonic waves at 2-15 MHz for structural and functional cardiac imaging. Cardiology clinics in the United States concentrate procurement in premium cart-based systems with 3D strain analysis, constrained by proprietary probe supply concentration among specialized German and Japanese component vendors.
- Holter Monitors:Ambulatory electrocardiogram recorders with 24-48 hour memory buffers.
- Implantable Loop Recorders:Subcutaneous devices with multi-year battery longevity for cryptogenic stroke evaluation.
Electrocardiogram monitors lead volumes today; implantable loop recorders are gaining share fastest.
Technology:
Cost tier stratification separates capital-intensive infrastructure from disposable consumer-grade peripherals.
- Wearable Technology:Photoplethysmography sensors and single-lead electrocardiogram electrodes embedded in wrist-worn or patch form factors. Home care settings in the United States are expanding prescription status for post-ablation surveillance wearables, supported by proliferating remote physiological monitoring reimbursement codes.
- Remote Patient Monitoring:Cloud-connected telemetry platforms integrating device data with electronic health records through HL7 FHIR interfaces. Hospital systems across North America are restructuring procurement toward subscription-based telemetry services that compress capital equipment cycles into recurring revenue arrangements.
- Telehealth Systems:Synchronous video consultation platforms with integrated biometric streaming.
- Digital Stethoscopes:Electronic auscultation devices with noise cancellation and spectral analysis.
Remote patient monitoring leads volumes today; wearable technology is climbing the fastest.
End User:
Customer type determines regulatory pathway complexity and reimbursement negotiation leverage.
- Cardiology Clinics:Specialized outpatient facilities with electrophysiology expertise and procedure volume concentration. Germany's cardiology clinic networks are driving demand concentration for connected monitoring platforms, responding to EU MDR clinical evidence requirements that favor established vendors with longitudinal data repositories.
- Hospitals:Acute care institutions with biomedical engineering departments and capital equipment procurement committees. Japan's PMDA quality system inspections filter device registry entrants, concentrating procurement among manufacturers with ISO 13485-certified quality management systems.
- Home Care Settings:Post-acute and residential environments with limited clinical oversight.
- Emergency Services:Pre-hospital transport and field response units requiring ruggedized portable devices.
Hospitals lead volumes today; home care settings are expanding most quickly.
Application:
Application maturity correlates with algorithm validation burden and diagnostic claim substantiation requirements.
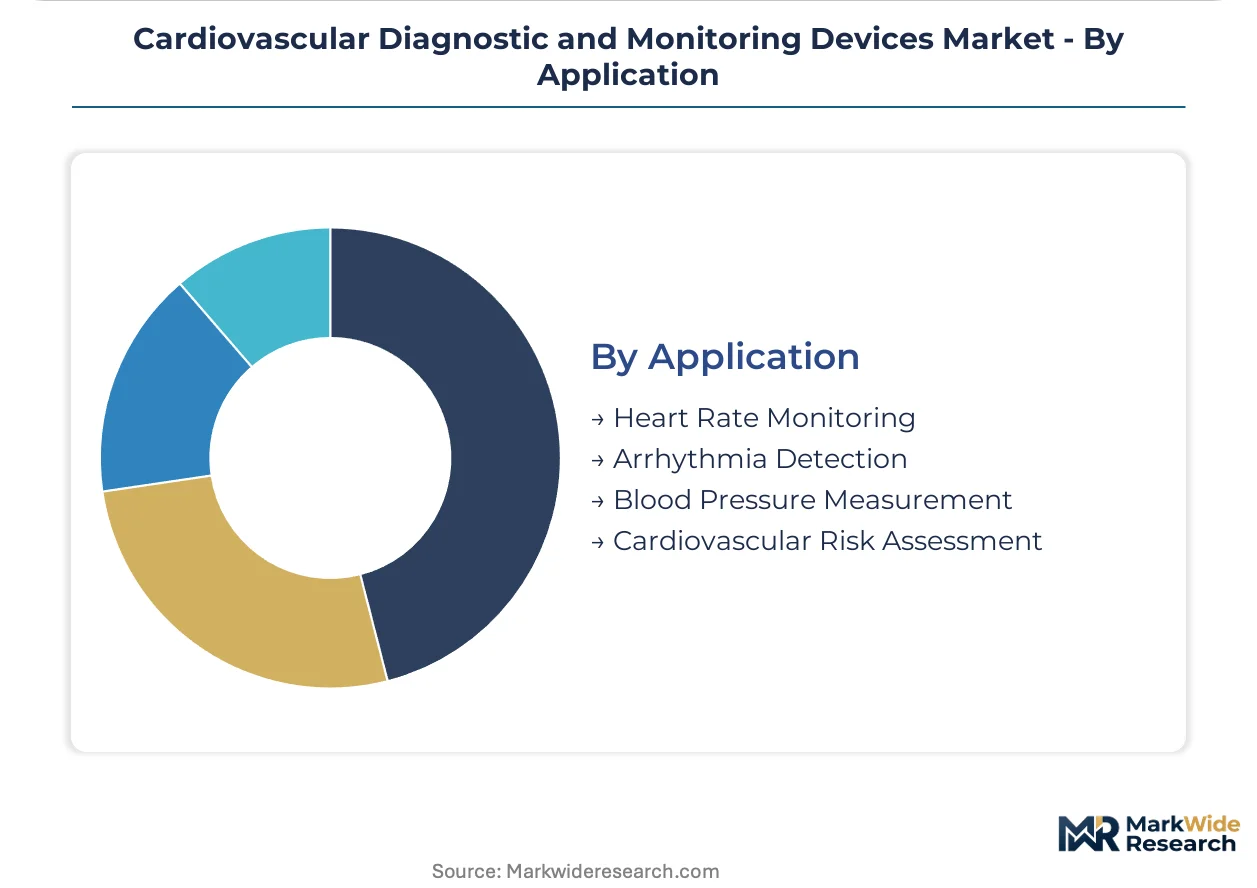
- Heart Rate Monitoring:Continuous pulse detection through photoplethysmography or electrocardiogram R-wave identification. Consumer wearable manufacturers in China leverage NMPA priority review channel acceleration to achieve diagnostic parity claims for optical pulse monitoring, pressuring traditional Holter manufacturers to defend clinical-grade accuracy.
- Arrhythmia Detection:Automated classification of atrial fibrillation, ventricular tachycardia, and conduction abnormalities through embedded machine learning algorithms. Implantable device OEMs are reducing false-positive alert rates through deep learning model refinement, improving clinical workflow efficiency and device retention metrics.
- Blood Pressure Measurement:Oscillometric cuff-based or pulse wave velocity estimation methods.
- Cardiovascular Risk Assessment:Composite scoring integrating multiple biomarkers for prognostic stratification.
Heart rate monitoring leads volumes today; arrhythmia detection is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophysiology specialists cluster in Germany's university hospital networks, Japan's precision manufacturing corridors, and the United States' ambulatory care expansion zones. These talent concentrations anchor regional procurement patterns and shape regulatory compliance investments.
United States
Ambulatory cardiac monitoring programs are expanding across hospital systems in Texas and the Southeast, driven by Medicare reimbursement codes for remote physiological monitoring. The FDA's premarket notification pathway shapes product development timelines for connected devices. Cardiology departments in Greater Boston pioneered subscription-based telemetry services that integrate electrophysiology data with electronic health records.
Germany
Cardiology clinic networks concentrate demand for connected monitoring platforms that satisfy EU MDR post-market surveillance mandates. REACH compliance requirements filter material sourcing for silver-silver chloride sensor electrodes. Industrial clusters in Baden-Württemberg host specialized piezoelectric transducer suppliers serving echocardiography OEMs.
Japan
PMDA quality system inspections concentrate procurement among manufacturers with ISO 13485-certified operations, filtering smaller entrants from the device registry. METI industrial policy supports domestic production of wireless patch technologies. The Kansai region anchors manufacturing of ultrasonic transducer assemblies for premium imaging systems.
China
NMPA's priority review channel accelerates approvals for innovative cardiac monitors, compressing regulatory gaps with FDA timelines. Domestic manufacturers leverage this tailwind to capture hospital procurement tenders in the Yangtze River Delta. Shanghai-based developers of photoplethysmography sensors achieve diagnostic parity claims for consumer-grade wearables.
India
CDSCO regulatory pathways for Class III cardiac devices extend timelines versus priority review jurisdictions, concentrating demand among established multinational suppliers. The PLI scheme for medical electronics attracts assembly investment to Karnataka and Tamil Nadu. Hyderabad's diagnostic equipment distributors report expanding volumes for Holter monitoring consumables.
Cardiovascular Diagnostic and Monitoring Devices Market Competitive Environment
Capital-heavy imaging platform producers compete with asset-light wearable designers across divergent margin structures. The vendor base stratifies into three tiers: diversified conglomerates with installed base leverage, specialized cardiac device pure-plays, and emerging sensor technology developers. Consolidation pressures concentrate procurement influence among health systems with subscription-based contracting power. Dominant competitive moves include cross-selling integrated monitoring workflows and restructuring capital equipment cycles into recurring telemetry revenue arrangements.
Within the diversified medical technology tier, GE HealthCare and Koninklijke Philips N.V. exemplify platform vendors leveraging imaging infrastructure to anchor monitoring ecosystem positions. Medtronic occupies a specialized position among implantable device developers, representing the pure-play archetype focused on extended battery longevity and ambulatory electrophysiology. These three companies illustrate how geographic origin and corporate structure correlate with strategic positioning: GE HealthCare and Philips operate as multinational conglomerates with broad portfolio reach, while Medtronic's focused structure enables concentrated R&D investment in implantable loop recorder technology.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips N.V. |
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| Nihon Kohden Corporation |
| Biotronik |
| ZOLL Medical Corporation |
| MicroPort Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive production of piezoelectric transducer assemblies anchors echocardiography OEMs' supply positions while licensing telemetry algorithms as separate subscription tiers secures recurring pricing power against hardware commoditization. Hospital procurement committees in Germany unbundle device acquisition from data analytics access, fragmenting vendor lock-in and elevating interoperability standards as primary selection criteria.
Pricing Analysis
Subscription-based telemetry services dominate procurement restructuring across North American hospital systems, compressing capital equipment cycles into recurring revenue arrangements. Three-tier pricing structure across premium imaging platforms, standard bedside monitors, and economy-grade Holter consumables reflects certification grade and after-sales service bundling. Cost compression in disposable electrode manufacturing intensifies because silver-silver chloride sensor material prices fluctuate with precious metals markets. Cardiology clinics exhibit highest price sensitivity due to reimbursement code crystallization, while university hospital networks prioritize integration depth over unit economics.
Supply Chain Analysis
Refurbishment flows for premium imaging systems create secondary market liquidity that constrains pricing power for new equipment sales in mature geographies. Piezoelectric transducer production clusters in Germany and Japan, while photoplethysmography sensor assembly concentrates in China's Yangtze River Delta. Raw material dependencies span rare earth elements for ultrasonic crystals, silver-silver chloride for electrodes, and lithium cells for implantable power systems. Single-source vulnerability in specialized German and Japanese component suppliers elevates supply risk for ultrasound system OEMs. Distribution runs through cardiology clinic networks and hospital procurement committees with GPO contracts managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by demand-shift toward AI-embedded arrhythmia detection algorithms that command premium positioning against commodity hardware.
For Market Incumbents: Deploy algorithm licensing as a defensive moat against wearable technology entrants achieving diagnostic parity through deep learning. Cross-sell integrated monitoring workflows from imaging installed bases to capture telemetry subscription revenue. Invest ISO 13485 certification resources to filter smaller competitors from Japan's PMDA device registry. Channel control through hospital system partnerships defends against unbundling pressures from chief medical information officers.
For New Entrants and Emerging Players: Post-acute cardiac rehabilitation settings in the United States represent the most penetrable buyer archetype lacking standardized remote monitoring protocols. Patch-based electrocardiogram systems targeting home care reimbursement code expansion offer white-space positioning against established platform vendors. Go-to-market through direct-to-clinic bypass of hospital procurement committees accelerates initial traction before GPO contract negotiations.
For Investors and Strategic Acquirers: Roll-up economics work for specialized sensor technology developers because EU MDR clinical evidence mandates concentrate procurement among vendors with longitudinal data repositories. Five-to-ten year viability hinges on software-as-medical-device revenue mix exceeding hardware dependency. Target acquisition profiles center on algorithm-dependent diagnostics with FDA premarket notification pathway progress. Monitor NMPA priority review channel acceleration for Chinese domestic manufacturers as inflection indicator for Asia-Pacific competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evaluation requirements extend timelines for Class III cardiac monitors by 18-24 months versus previous directives. |
| Hospital System Partnership | Germany's university hospital networks pioneered unbundling of device acquisition from data analytics subscription negotiations. |
| Software Companion Development | Machine learning algorithms embedded in implantable devices reduce false-positive alert rates and improve clinical workflow efficiency. |
| Reimbursement Strategy | Medicare remote physiological monitoring codes in the United States expand prescription volumes for wearable loop recorders. |
| FDA Submission | Premarket notification pathway shapes product development timelines and market access costs for connected monitoring platforms. |
Study Parameters
Bottom-up cardiology clinic and hospital system modeling reconciled against top-down component supplier tracking forms the analytical core of this study. Primary interviews with electrophysiologists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR clinical evaluation reports, CMS Medicare reimbursement databases, and hospital procurement tender records. Triangulation across stakeholder perspectives and regulatory documentation ensures segmentation integrity.
Input-output matrices map device unit shipments to telemetry subscription attach rates across the projection horizon. Segmentation dimensions modeled include device type, technology tier, end-user category, and application maturity. CAGRs derive from regression analysis of historical procurement patterns and forward-looking reimbursement trajectory assumptions. Industry-specific forecast inputs incorporate EU MDR implementation timelines and NMPA priority review channel throughput rates.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time telemetry subscription pricing transparency introduce uncertainty bands around recurring revenue projections. Forecasts reflect documented assumptions regarding reimbursement code crystallization and post-market surveillance compliance costs. Practitioners should monitor PMDA quality system inspection backlogs and silver-silver chloride commodity price volatility for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Pulmonary Stents Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Global Abdominal Aortic Aneurysm Treatment Market
Cardiovascular Devices
Congestive Heart Failure Treatment Devices Market
Cardiovascular Devices
Ischemic Stroke Aspiration Systems Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Global Ventricular Assist Device Market
Cardiovascular Devices
UAE Cardiovascular Devices Market
Cardiovascular Devices
Middle East and Africa Heart Valve Repair and Replacement Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Aortic Aneurysm Market