
 North America Self-Monitoring Blood Glucose Market | 2026-2036
North America Self-Monitoring Blood Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
North America Self-Monitoring Blood Glucose Market Analytics
Buyer concentration among home care settings and retail pharmacy chains is restructuring procurement dynamics across the North America Self-Monitoring Blood Glucose Market. Abbott Laboratories leverages its FreeStyle portfolio to dominate integrated continuous glucose monitoring systems. DexCom, Inc. competes through wireless-enabled platforms that extend real-time data connectivity. F. Hoffmann-La Roche Ltd. sustains brand strength in traditional blood glucose meters through precision-focused manufacturing scale.
Self-monitoring blood glucose encompasses portable electrochemical or optical devices that measure capillary blood glucose concentration via enzyme-mediated reactions, typically employing glucose oxidase or glucose dehydrogenase chemistry on disposable test strips for metabolic management. The primary commercial purpose centers on enabling diabetic patients to adjust insulin dosing, diet, and activity in real time outside clinical settings. Continuous glucose monitors represent the fastest-growing product category as wireless monitoring technology displaces conventional fingerstick protocols among Type 1 diabetic populations. Test strips still anchor the largest revenue pool due to recurring consumable demand across Medicare-reimbursed patient cohorts, though margin compression intensifies from generic competition.
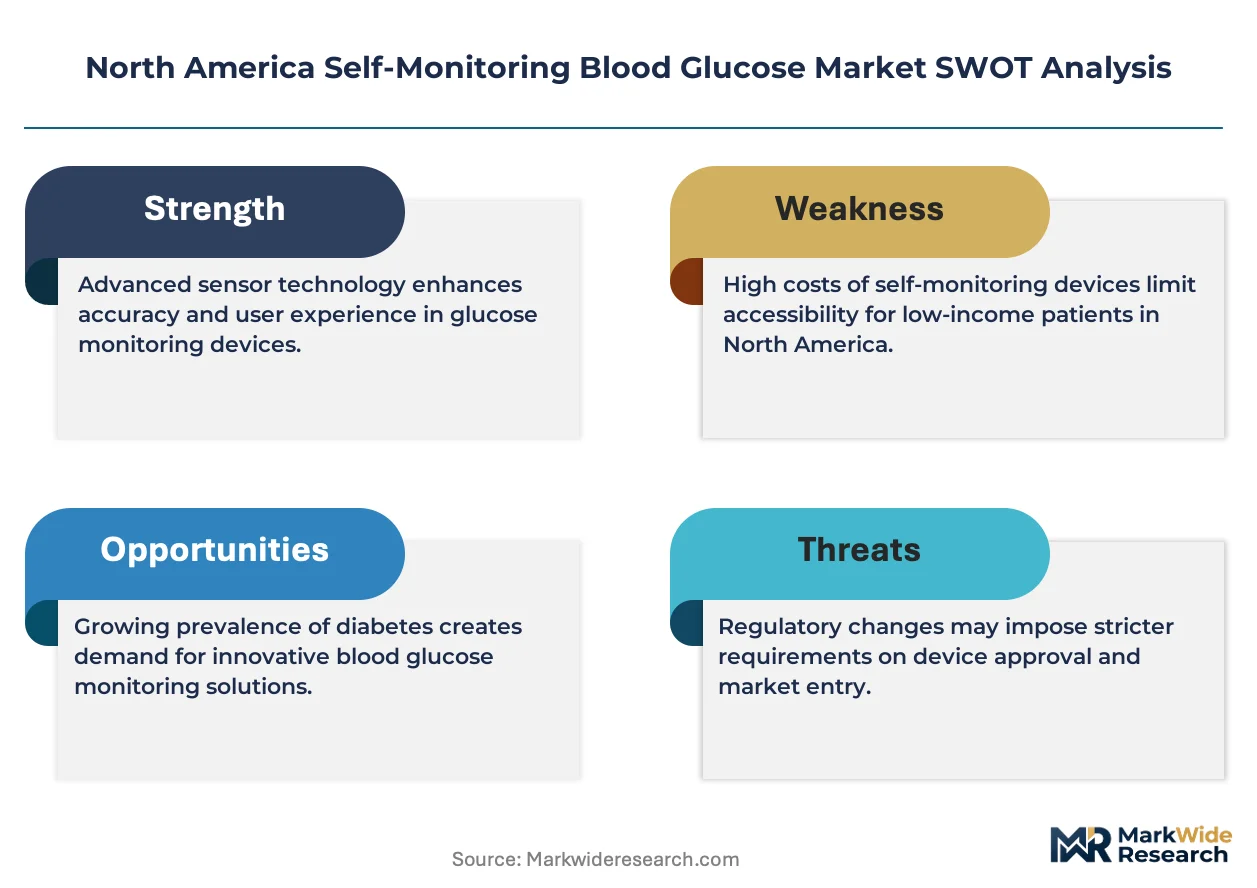
FDA 510(k) pathways and CLIA waiver standards govern device accuracy thresholds and over-the-counter access, directly shaping product development timelines and commercial launch feasibility for new entrants. Health Canada and Mexico's national health regulator enforce parallel but non-identical performance benchmarks that fragment cross-border harmonization efforts. Stakeholders must monitor evolving CMS reimbursement codes for non-invasive and integrated systems as coverage determinations will dictate which technology platforms achieve scalable patient access.
Market Dynamics
Wireless-enabled continuous glucose monitoring platforms are consolidating procurement power among integrated health systems and retail pharmacy chains, compressing margins for conventional test strip manufacturers while elevating data interoperability as a competitive gate.
Growth Catalysts
- Medicare Reimbursement Expansion:CMS coverage determinations for non-invasive and integrated glucose monitoring systems are accelerating patient access across home care settings in the United States.
- Enzymatic Biosensor Miniaturization:Advances in glucose oxidase and glucose dehydrogenase chemistry are enabling smaller, more accurate disposable test strips for point-of-care applications.
- Home Care Decentralization:Patient preference for remote diabetes management outside clinical facilities is driving device demand in residential settings across Canada and Mexico.
Market Restraints
- Generic Test Strip Competition:Unbranded consumables are eroding pricing power for established manufacturers in the recurring revenue pool.
- Cross-Border Regulatory Fragmentation:Divergent accuracy benchmarks between FDA 510(k) pathways and Health Canada requirements complicate product launch harmonization.
- Optical Sensing Limitations:Non-invasive glucose measurement technologies face persistent accuracy challenges in hypoglycemic range detection.
Strategic Opportunities
- Mexico Secondary Market Expansion:Underpenetrated patient populations and evolving national health regulator standards create whitespace for localized manufacturing partnerships.
- Artificial Intelligence Integration:Convergence of predictive analytics with real-time glucose data streams enables personalized insulin dosing recommendations.
- Direct-to-Consumer Channel Development:Subscription-based CGM delivery models bypass traditional pharmacy distribution in the United States.
Industry Challenges
- FDA 510(k) Timeline Compression:Expedited clearance pathways for integrated systems demand accelerated clinical validation without compromising accuracy thresholds.
- Interoperability Architecture Complexity:Legacy electronic health record systems resist seamless integration with wireless glucose data platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Self-Monitoring Blood Glucose Market |
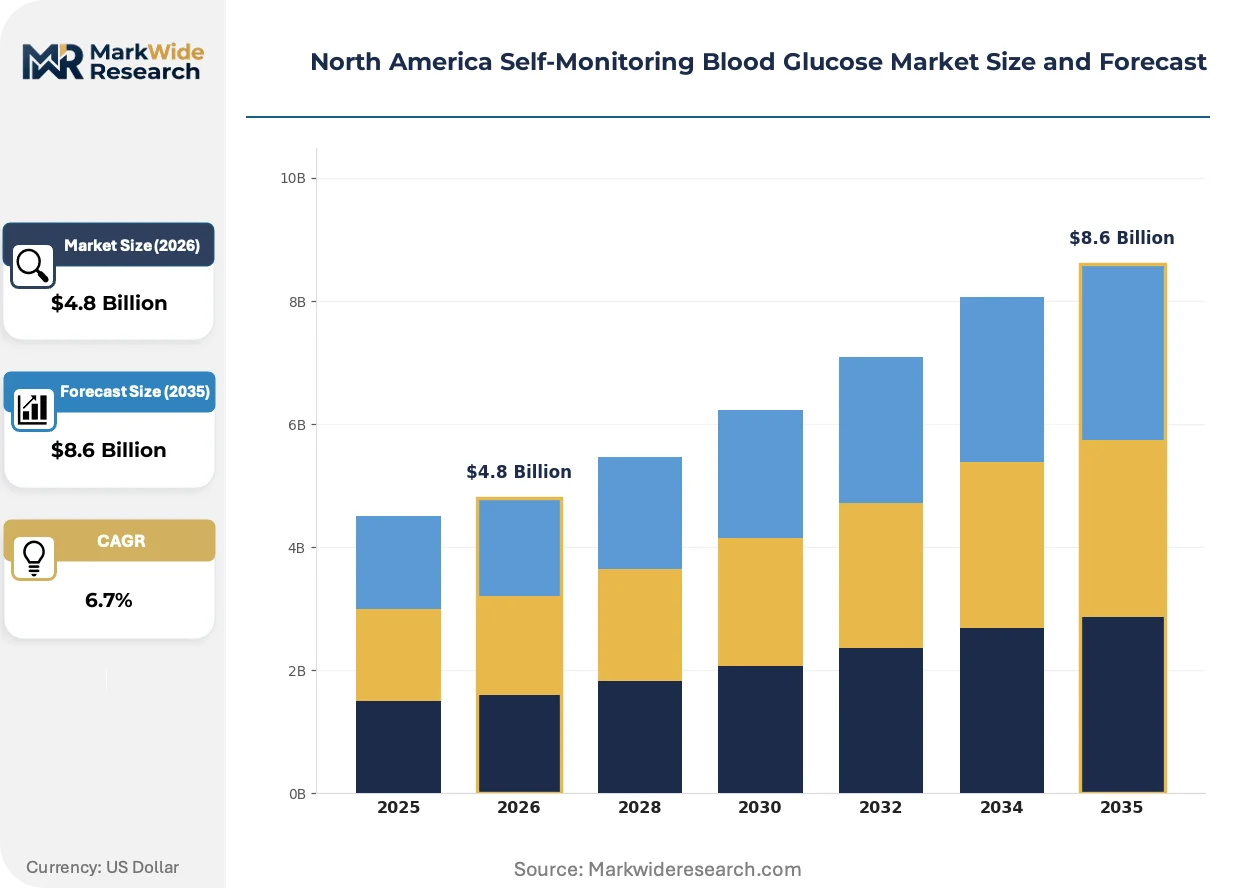
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Test Strips, Lancing Devices, Continuous Glucose Monitors End User: Diabetic Patients, Healthcare Providers, Home Care Settings, Pharmacies Technology: Self-Monitoring, Wireless Monitoring, Non-Invasive, Integrated Systems Distribution Channel: Retail Pharmacies, Online Stores, Hospitals, Wholesalers |
| Companies Covered | F. Hoffmann-La Roche Ltd., Arkray, Abbott Laboratories, B. Braun SE, Platinum Equity (LifeScan), DexCom, Inc., Ascensia Diabetes Care Holdings AG, Bionime Corporation, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Self-Monitoring Blood Glucose Market Evolving Landscape
Real-time metabolic data streams are redefining therapeutic decision-making, with sensor technology and reimbursement policy advancing in parallel across North American healthcare infrastructure.
Factory-calibrated continuous glucose monitors eliminate fingerstick calibration requirements through novel glucose sensing polymers and algorithmic drift compensation. Type 1 diabetic populations in the United States are adopting these systems at the fastest pace among all patient cohorts. This capability is rewriting the economics of diabetes management by collapsing the distinction between professional and personal monitoring environments.
FDA CLIA waiver standards for over-the-counter glucose devices are tightening accuracy thresholds while expanding retail access channels. Manufacturers must now validate performance across broader hematocrit ranges and environmental conditions prior to commercial launch. Home care settings and retail pharmacy chains bear the primary compliance burden as they transition inventory toward waived-certificate-of-waiver protocols.
Consolidated procurement by integrated delivery networks is compressing vendor margins while demanding value-added services beyond device supply. Group purchasing organizations are displacing individual clinic purchasing authority in the United States, with similar concentration emerging among provincial health authorities in Canada. This behavioral shift is most visible in the Midwest and Southeast United States, where hospital system mergers have reduced the number of independent purchasing decision points by half.
North America Self-Monitoring Blood Glucose Market Segmentation
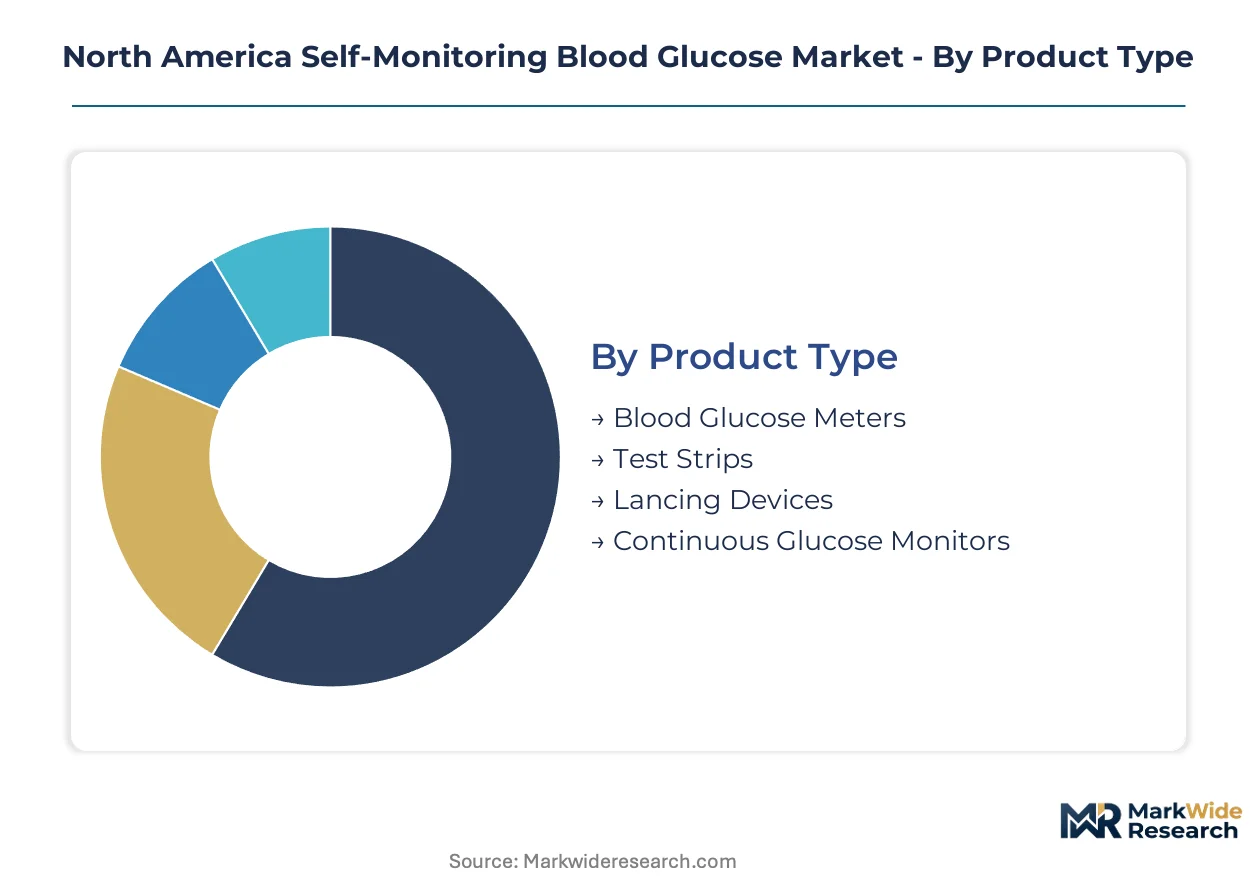
Self-monitoring blood glucose procurement decisions pivot on reimbursement eligibility, calibration requirements, and data interoperability needs. Each segment category reflects distinct buyer priorities across patient, provider, and payer stakeholders in the United States, Canada, and Mexico.
Product Type:
Reimbursement tier and consumable replenishment frequency drive purchasing authority within this category.
- Test Strips:Enzymatic disposable strips employing glucose oxidase or glucose dehydrogenase chemistry dominate recurring revenue pools through Medicare-reimbursed replenishment cycles. Demand concentrates among Type 2 diabetic populations in the United States seeking cost-capped monthly supplies under CMS coverage determinations.
- Continuous Glucose Monitors:Factory-calibrated sensors with algorithmic drift compensation eliminate fingerstick calibration requirements. Adoption accelerates fastest among Type 1 diabetic patients in the United States and Canada as integrated health systems negotiate volume-based procurement contracts.
- Blood Glucose Meters:Portable electrochemical devices with digital readouts serve as backup verification tools for CGM users and primary monitoring for cost-sensitive patients.
- Lancing Devices:Spring-loaded puncture mechanisms with adjustable depth settings accompany meter purchases as bundled accessories.
Test strips lead on scale through recurring consumable demand; continuous glucose monitors lead on momentum through wireless data integration.
End User:
Care setting determines device complexity requirements and regulatory compliance burdens.
- Home Care Settings:Residential diabetes management environments prioritize wireless-enabled devices with smartphone connectivity for remote monitoring. Patient preference for decentralized care drives demand across suburban United States and Canadian provincial health systems.
- Healthcare Providers:Clinical environments require CLIA-waived devices with documented accuracy across hematocrit ranges for point-of-care testing protocols.
- Diabetic Patients:Individual purchasers seek over-the-counter accessibility through retail pharmacy chains with prescription integration.
- Pharmacies:Inventory managers balance generic test strip margins against branded CGM subscription fulfillment.
Home care settings lead on scale through Medicare reimbursement expansion; healthcare providers lead on momentum through integrated delivery network consolidation.
Technology:
Data architecture sophistication separates premium positioning from commodity alternatives.
- Integrated Systems:CGM-insulin pump closed-loop platforms with predictive algorithm dosing represent the highest-value technology tier. FDA 510(k) clearance pathways govern commercial launch feasibility for new entrants in this segment.
- Wireless Monitoring:Bluetooth-enabled glucose meters transmitting real-time data to cloud platforms enable remote provider oversight. Demand concentrates among tech-enabled health systems in the United States Midwest and Southeast.
- Self-Monitoring:Conventional fingerstick protocols with manual logbook recording persist among Medicare cohorts with limited digital literacy.
- Non-Invasive:Optical sensing technologies face accuracy limitations in hypoglycemic detection ranges, constraining clinical adoption.
Self-monitoring leads on scale through established reimbursement codes; integrated systems lead on momentum through closed-loop therapeutic automation.
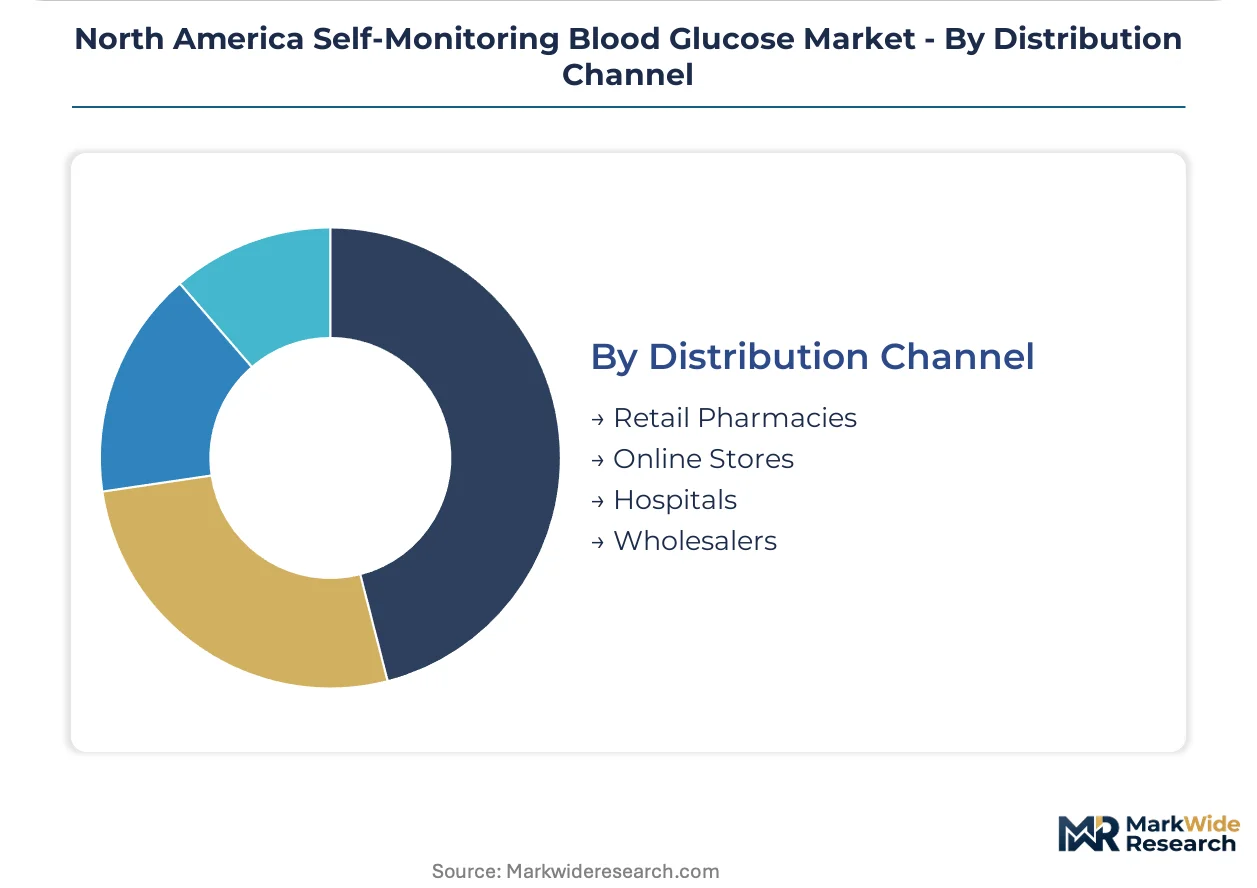
Distribution Channel:
Channel concentration is restructuring vendor margin structures across the region.
- Retail Pharmacies:CVS, Walgreens, and independent chains dominate test strip volume through prescription fulfillment and over-the-counter placement. Group purchasing organization consolidation compresses supplier pricing power in the United States.
- Online Stores:Direct-to-consumer CGM subscription models bypass traditional pharmacy distribution through automated sensor replenishment. Growth accelerates fastest among urban United States patients seeking price transparency.
- Hospitals:Integrated delivery networks negotiate enterprise contracts for inpatient glucose monitoring standardization.
- Wholesalers:McKesson and Cardinal Health distribute bulk test strip inventory to institutional purchasers.
Retail pharmacies lead on scale through Medicare Part B reimbursement access; online stores lead on momentum through subscription-based patient retention models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized endocrinology workforce clusters in the United States anchor regional innovation capacity, while Canadian and Mexican markets expand through decentralized care infrastructure.
United States
Medicare reimbursement expansion for continuous glucose monitors drives patient access across suburban home care settings. FDA 510(k) pathways and CLIA waiver standards govern device accuracy thresholds and over-the-counter commercialization. The Midwest and Southeast hospital system mergers have consolidated procurement decision points, compressing vendor margins while elevating data interoperability requirements.
Canada
Provincial health authority concentration is restructuring purchasing dynamics toward volume-based contracts for wireless-enabled monitoring platforms. Health Canada enforces parallel but non-identical performance benchmarks to FDA requirements, fragmenting cross-border product harmonization. Ontario and Quebec anchor device distribution infrastructure, with expanding secondary demand across Prairie Provinces.
Mexico
Underpenetrated Type 1 and Type 2 diabetic populations create whitespace for localized manufacturing partnerships and retail pharmacy chain expansion. The national health regulator evolves standards for point-of-care glucose testing accuracy, shaping import requirements for foreign device manufacturers. Mexico City Metro and Nuevo León concentrate private healthcare infrastructure investment, driving demand for CLIA-waived devices in outpatient settings.
North America Self-Monitoring Blood Glucose Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered technology segments. The vendor base stratifies between integrated continuous glucose monitoring platforms and conventional test strip manufacturers facing margin compression. Three archetypes dominate: diversified medical technology conglomerates with diabetes care divisions, pure-play glucose monitoring specialists, and private equity-backed portfolio companies consolidating legacy meter brands. Competitive moves center on strategic partnerships for data interoperability and vertical integration into sensor manufacturing.
Within the diversified conglomerate tier, Abbott Laboratories and F. Hoffmann-La Roche Ltd. exemplify scale-driven positioning across enzymatic biosensor and electrochemical device categories. DexCom, Inc. occupies the pure-play specialist position, representing wireless-enabled platform development. Among private equity-backed entities, Platinum Equity's LifeScan holding anchors traditional blood glucose meter consolidation. These three company groupings illustrate the structural tension between integrated system innovation and recurring consumable revenue defense.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Arkray |
| Abbott Laboratories |
| B. Braun SE |
| Platinum Equity (LifeScan) |
| DexCom, Inc. |
| Ascensia Diabetes Care Holdings AG |
| Bionime Corporation |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Enzymatic biosensor materials—glucose oxidase and glucose dehydrogenase chemistries—flow from specialized chemical manufacturers through contract converters to disposable test strip producers, with pricing power accumulating at the formulation layer where FDA 510(k) validation creates scarcity. This upstream concentration cascades into tiered downstream pricing, as Medicare-reimbursed consumable volumes in the United States subsidize lower-margin Canadian provincial contracts and emerging Mexican retail channels.
Pricing Analysis
Bundled sensor-plus-algorithm subscriptions versus unbundled test strip transactions split pricing architecture across patient segments. Three-tier pricing structure across premium, standard, and economy levels separates factory-calibrated CGM systems from CLIA-waived meters and generic strip alternatives. Price differentiation rests on FDA clearance tier and data interoperability certification, with integrated insulin pump compatibility commanding sustained premiums. Cost compression in the recurring consumable tier is intensifying because unbranded strip manufacturers exploit expired patent chemistry, while subscription-based CGM delivery models show least price sensitivity among Type 1 diabetic populations seeking automated dosing support.
Supply Chain Analysis
Regional distribution centers in Illinois, Ontario, and Nuevo León operate hub-and-spoke patterns radiating to retail pharmacy chains and integrated health system warehouses. Manufacturing concentration in the United States, Ireland, and Malaysia feeds from precision electrochemical sensor substrates and medical-grade polymer membranes. Single-source vulnerability in glucose sensing polymer supply creates exposure to formulation batch variability. Distribution runs through group purchasing organization contracts that consolidate formerly fragmented hospital procurement into enterprise-wide agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Self-Monitoring Blood Glucose Market functions as a stable compounder, with Medicare reimbursement expansion for continuous monitoring systems providing durable demand visibility across economic cycles.
For Market Incumbents: Cement data interoperability leadership by embedding CGM streams directly into Epic and Cerner electronic health record architectures before emerging platform competitors achieve integration certification. Prioritize backward integration into glucose sensing polymer production to defend margin position against raw material cost volatility and single-source supplier concentration.
For New Entrants and Emerging Players: Direct-to-consumer telehealth platforms offer the lowest-friction entry vector for algorithm-native companies lacking established GPO relationships. Target underpenetrated Type 2 diabetic populations in Mexican outpatient clinics where CLIA-waived device standards are still evolving and local manufacturing partnerships unlock import tariff advantages.
For Investors and Strategic Acquirers: Consolidation pressure builds where private equity-backed legacy meter portfolios face recurring revenue erosion from generic strip competition and CGM subscription displacement. Five-to-ten year viability favors pure-play wireless monitoring specialists with captive sensor manufacturing and FDA-cleared insulin pump integration. Watch CMS coverage determinations for non-invasive optical sensing as the inflection signal—approval would collapse the fingerstick-CGM distinction and reorder competitive tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS coverage expansion for integrated systems determines scalable patient access across Medicare cohorts. |
| Hospital System Partnership | Epic and Cerner EHR integration contracts lock in enterprise procurement decisions for CGM platforms. |
| Software Companion Development | Predictive insulin dosing algorithms differentiate premium CGM tiers from commodity sensor alternatives. |
| CE Marking Pathway | Health Canada parallel approval requirements fragment cross-border product harmonization for new entrants. |
| Backward Integration | In-house glucose sensing polymer production reduces exposure to single-source chemical supplier concentration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement committee members, GPO contracts managers, biomedical engineers, and endocrinology clinic directors with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and Health Canada device licensing data. Bottom-up patient population modeling and top-down revenue triangulation cross-checked segment-level estimates.
Segment-weighting approach distributed value and volume across product type, end user, technology tier, and distribution channel dimensions, with regional coefficients applied to United States, Canada, and Mexico sub-markets. CAGRs derived from fitted growth curves incorporating Medicare coverage trajectory assumptions, enzymatic biosensor cost decline rates, and wireless data platform adoption elasticities across Type 1 versus Type 2 diabetic populations.
The model assumes a particular technology adoption path; alternative pathways for non-invasive optical glucose sensing would alter the outlook if hypoglycemic range accuracy thresholds achieve clinical validation. Forecasts reflect documented assumptions on CMS reimbursement expansion timing and FDA clearance backlog resolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Asia-Pacific Respiratory Monitoring Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
Asia Pacific Wireless Healthcare Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Remote Patient Monitoring Devices Market