
 Portable Multi-Parameter Monitors Market | 2026-2036
Portable Multi-Parameter Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Multi-Parameter Monitors Market Analytics
China's medical device manufacturing corridor is rewriting supply dynamics for portable monitoring equipment. GE Healthcare leverages its established imaging ecosystem to cross-sell multi-parameter platforms into integrated hospital networks. Shenzhen Mindray Bio-Medical Electronics anchors its competitive stance through aggressive cost engineering and regulatory registrations across emerging markets. Nihon Kohden dominates specialized cardiac monitoring configurations with proprietary algorithm development and Japanese manufacturing precision.
Portable multi-parameter monitors are compact diagnostic instruments that simultaneously track electrocardiography, pulse oximetry, non-invasive blood pressure, respiratory rate, and temperature through integrated sensor arrays and signal processing firmware, designed for bedside, transport, and ambulatory patient surveillance across acute and sub-acute care settings. Handheld monitors sustain the largest revenue pool due to their deployment flexibility across emergency departments and aeromedical transport, while wearable devices represent the fastest structural expansion as health systems pursue continuous remote patient surveillance and reduced readmission penalties. Bluetooth-enabled connectivity leads technology adoption for its low-power interoperability with existing hospital IT infrastructure, though Wi-Fi configurations are gaining traction in telehealth deployments requiring higher bandwidth for real-time video-integrated consultations.
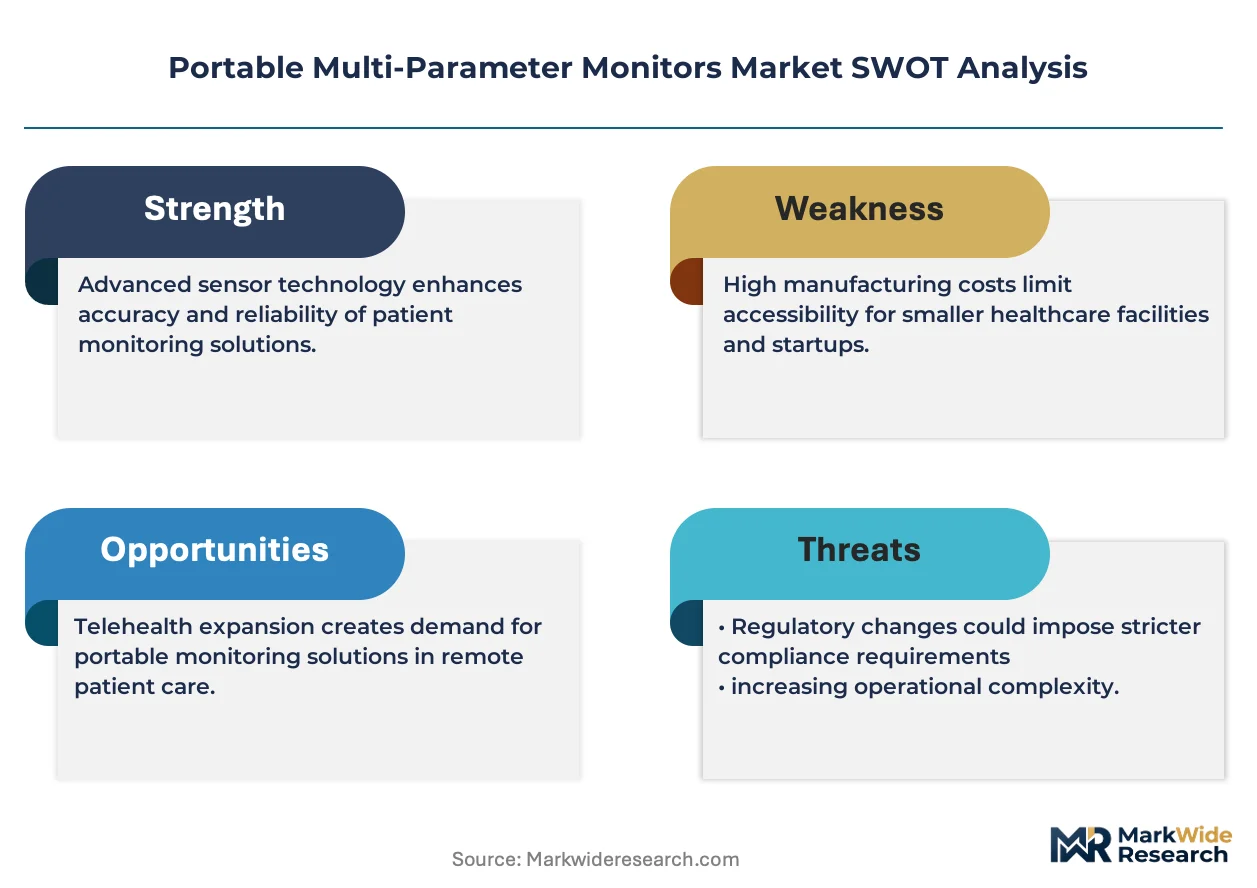
FDA 510(k) clearance pathways and IEC 60601-1-2 electromagnetic compatibility standards govern device commercialization in the United States, with the former dictating clinical validation requirements and the latter mandating immunity testing for increasingly wireless-intensive hospital environments. The EU Medical Device Regulation imposes stricter post-market surveillance and unique device identification requirements that extend compliance timelines for manufacturers seeking CE marking access. Stakeholders must monitor evolving cybersecurity guidance from FDA and comparable bodies, as network-connected monitors expand attack surfaces and attract heightened regulatory scrutiny across procurement specifications.
Market Dynamics
Wireless connectivity mandates from FDA and IEC are compressing development timelines while forcing simultaneous hardware and firmware redesigns across the portable monitor supply base.
Growth Catalysts
- Hospital emergency department modernization:US facilities under value-based care contracts deploy portable monitors for rapid triage workflows. CMS readmission penalties accelerate capital allocation toward continuous patient surveillance infrastructure.
- FDA 510(k) pathway streamlining:Predicate device referencing for software-only updates reduces regulatory burden for algorithm-enhanced monitors. Manufacturers exploit this to accelerate feature deployment cycles.
- Bluetooth Low Energy maturation:Interoperability with existing hospital IT architectures eliminates gateway hardware requirements. Engineering teams redirect resources toward sensor fusion rather than connectivity middleware.
Market Restraints
- Semiconductor supply concentration:Analog front-end chips and specialized ADCs source predominantly from Taiwan and South Korea foundries. Geographic concentration creates vulnerability to trade policy disruptions.
- IEC 60601-1-2 electromagnetic immunity testing:Wireless coexistence validation in dense RF hospital environments extends certification timelines. Small manufacturers lack anechoic chamber access for pre-submission testing.
- Disposable sensor cost structure:Single-use SpO2 probes and ECG electrodes constitute recurring operational expenditure that compounds total cost of ownership calculations against capital equipment.
Strategic Opportunities
- Rural health clinic penetration:Indian primary health centers under Ayushman Bharat lack continuous monitoring capability. Cost-engineered handheld units address this infrastructure gap without grid-dependent installation.
- Telehealth-integrated home discharge:Post-acute surveillance contracts bundle wearable monitors with remote nursing oversight. This shifts revenue from device sale to per-patient-month service fees.
- EU MDR unique device identification:Mandated traceability requirements favor manufacturers with integrated manufacturing execution systems. Early compliance creates procurement preference in German and French hospital tenders.
Industry Challenges
- Embedded cybersecurity engineering:FDA guidance on premarket submission of cybersecurity documentation demands specialized firmware architecture expertise. Talent scarcity in medical device security extends hiring timelines.
- Legacy bedside monitor integration:Proprietary data protocols from incumbent installed bases obstruct seamless data flow into hospital EMR systems. Middleware development consumes engineering bandwidth.
- Multi-jurisdiction registration synchronization:Divergent electromagnetic compatibility test methodologies between FDA, NMPA, and PMDA force redundant certification campaigns. Registration teams manage parallel submission tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Multi-Parameter Monitors Market |
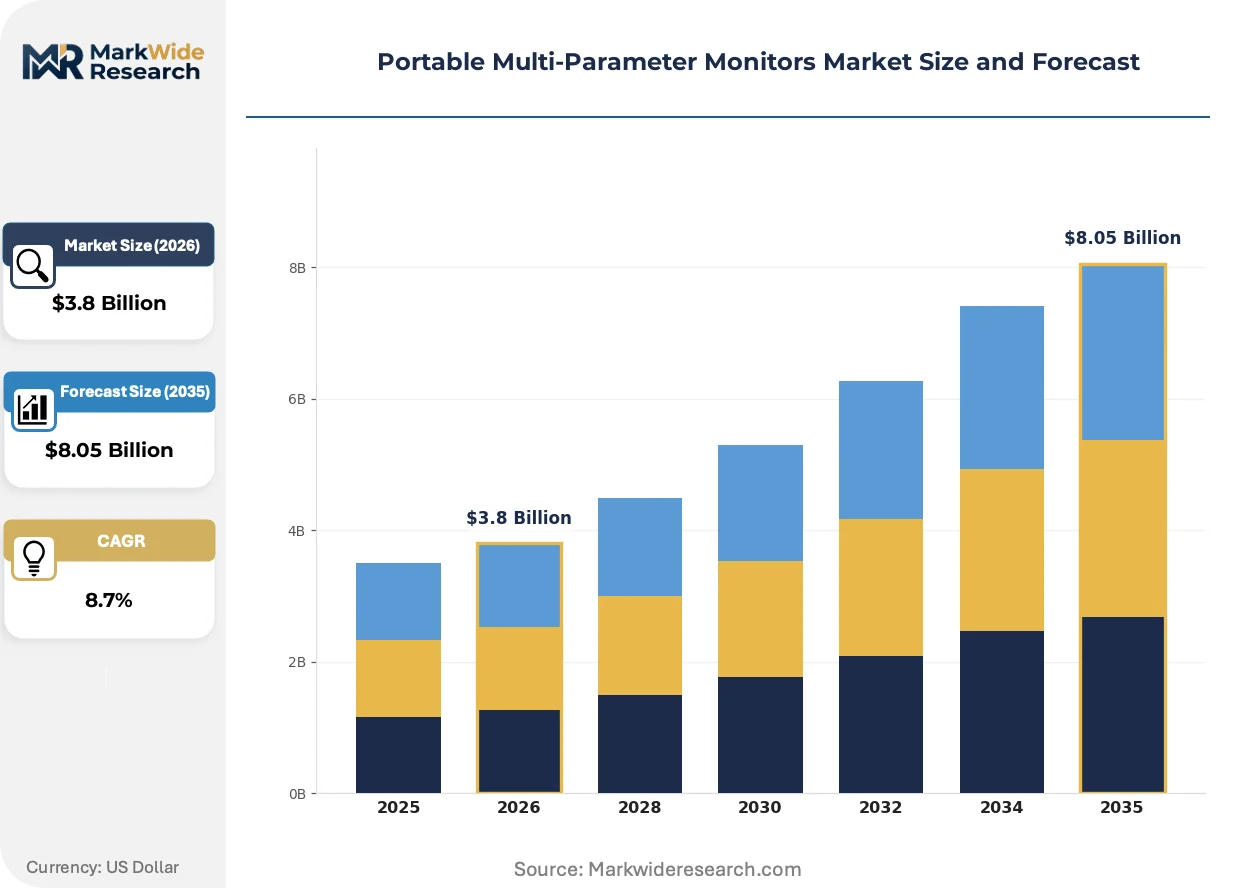
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Monitors, Wearable Devices, Stationary Monitors, Bedside Monitors Technology: Bluetooth, Wi-Fi, Infrared, USB End User: Hospitals, Home Care, Emergency Services, Clinics Application: Patient Monitoring, Vital Signs Monitoring, Telehealth, Research |
| Companies Covered | Koninklijke Philips N.V., GE Healthcare, Medtronic, Masimo Corporation, Shenzhen Mindray Bio-Medical Electronics, Nihon Kohden, Spacelabs Healthcare, ICU Medical, Inc., Drägerwerk AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Multi-Parameter Monitors Market Evolving Landscape
Artificial intelligence inference at the edge is compressing alarm fatigue while creating new regulatory validation requirements for algorithm-dependent diagnostic outputs.
Edge machine learning accelerators embedded in ARM-based system-on-chip architectures enable real-time arrhythmia detection without cloud latency. Cardiac care units at academic medical centers pilot these configurations for continuous telemetry substitution. The technology is digitizing alarm management from threshold-based triggering toward probability-weighted clinical alerts.
The EU Medical Device Regulation's post-market surveillance requirements impose systematic literature review obligations for legacy predicate devices. Manufacturers must maintain clinical evidence packages beyond initial CE marking. High-risk cardiac monitoring configurations face the steepest documentation burden, driving consolidation of regulatory affairs functions among mid-tier competitors.
Health system procurement committees now unbundle hardware acquisition from service contracts, separating device purchase from preventive maintenance and calibration scheduling. Integrated delivery networks in Texas and Florida pilot this model through third-party clinical engineering vendors. The shift transfers capital risk to equipment lessors while compressing manufacturer margin through transparent lifecycle cost benchmarking.
Portable Multi-Parameter Monitors Market Segmentation
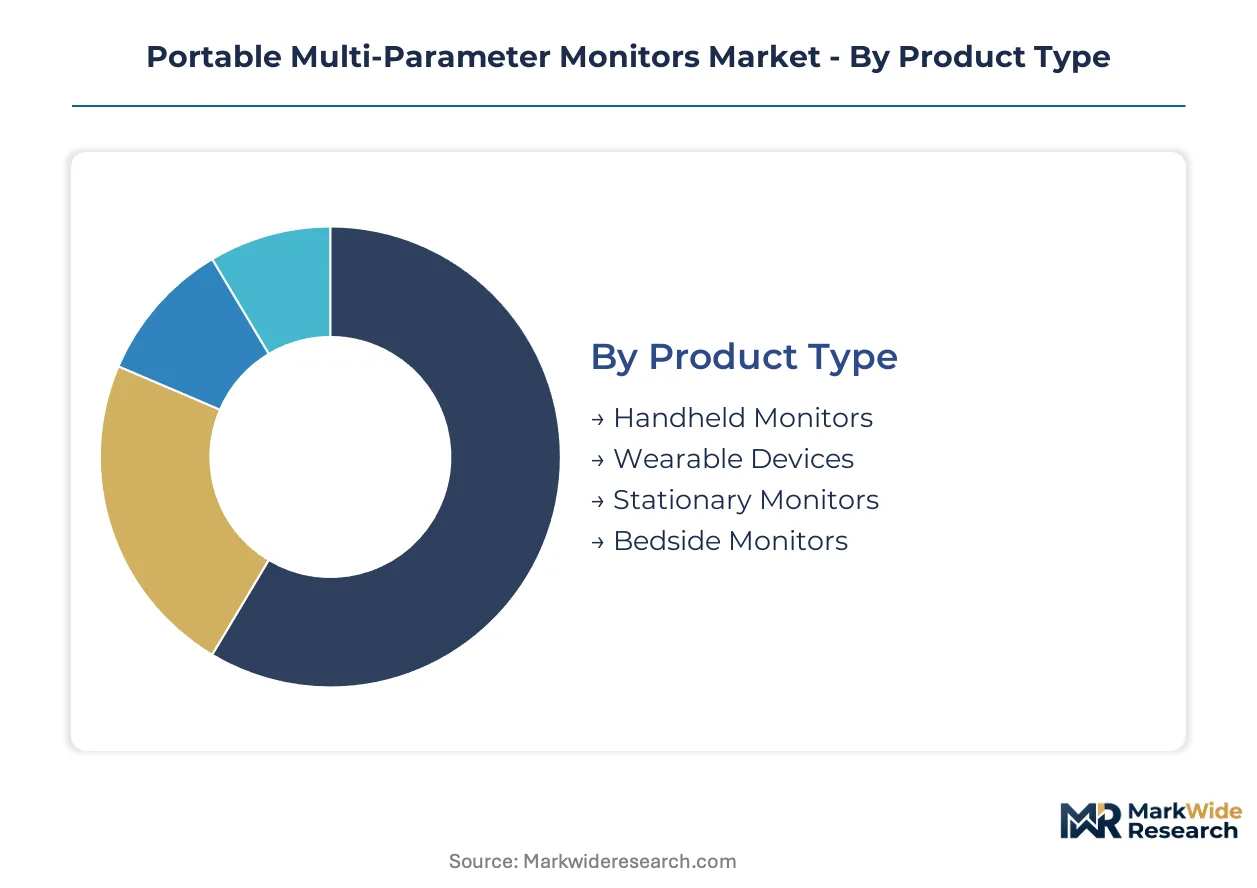
Segmentation in portable multi-parameter monitors reveals how hardware form factors, connectivity protocols, and care settings create distinct procurement patterns. Hospital capital committees evaluate segments through total cost of ownership lenses, while home care distributors prioritize patient adherence and reimbursement compatibility.
Product Type:
Mature bedside configurations dominate installed bases, while emerging wearable architectures are displacing traditional telemetry for ambulatory surveillance.
- Handheld Monitors:Battery-powered units integrate ECG, SpO2, NIBP, and temperature modules in sub-2kg enclosures. Emergency departments in US academic medical centers standardize on these for rapid triage protocols. Bluetooth Low Energy connectivity eliminates dedicated gateway hardware.
- Wearable Devices:Patch-based or wrist-worn sensors enable continuous multi-parameter streaming without tethering to bedside infrastructure. Medicare Advantage plans in Florida and Texas bundle these with remote patient monitoring programs to reduce 30-day readmission penalties.
- Stationary Monitors:AC-powered cart-mounted systems serve procedural suites and post-anesthesia care units.
- Bedside Monitors:Wall-mounted or rail-integrated displays anchor intensive care and step-down unit workflows.
Handheld monitors handle the majority of throughput; wearable devices are the fastest mover on share.
Technology:
Cost tier differentiation separates premium wireless implementations from economy wired alternatives, with interoperability premiums commanding hardware price multiples.
- Bluetooth:Bluetooth Low Energy 5.0 and 5.3 dominate hospital deployments for sub-10mW power consumption and native smartphone pairing. GE Healthcare and Philips leverage this for seamless EMR integration without IT infrastructure overhaul.
- Wi-Fi:802.11ac/ax configurations support higher bandwidth for video-integrated telehealth consultations and firmware over-the-air updates. Rural health clinics in India deploy these for specialist-backed remote diagnostics under Ayushman Bharat.
- Infrared:Line-of-sight data transmission persists in electromagnetic-sensitive environments like MRI suites.
- USB:Tethered connectivity remains standard for research applications requiring deterministic latency and raw signal export.
Bluetooth captures the volume base; Wi-Fi climbs the fastest on deployment share.
End User:
Application context separates acute care purchasers seeking alarm reliability from home care distributors prioritizing patient self-management.
- Hospitals:Integrated delivery networks procure through centralized clinical engineering contracts spanning preventive maintenance and calibration. Value-based care mandates in US markets accelerate replacement cycles for aging bedside infrastructure.
- Home Care:Durable medical equipment suppliers bundle monitors with remote nursing oversight, shifting revenue from capital sale to per-patient-month service fees. Medicare reimbursement codes determine device feature specifications.
- Emergency Services:Aeromedical and ground ambulance operators demand MIL-STD-810G shock resistance and extended temperature operating ranges.
- Clinics:Federally qualified health centers prioritize cost-engineered handheld units for episodic vital signs capture.
Hospitals absorb the dominant procurement volume; home care is expanding most quickly on addressable base.
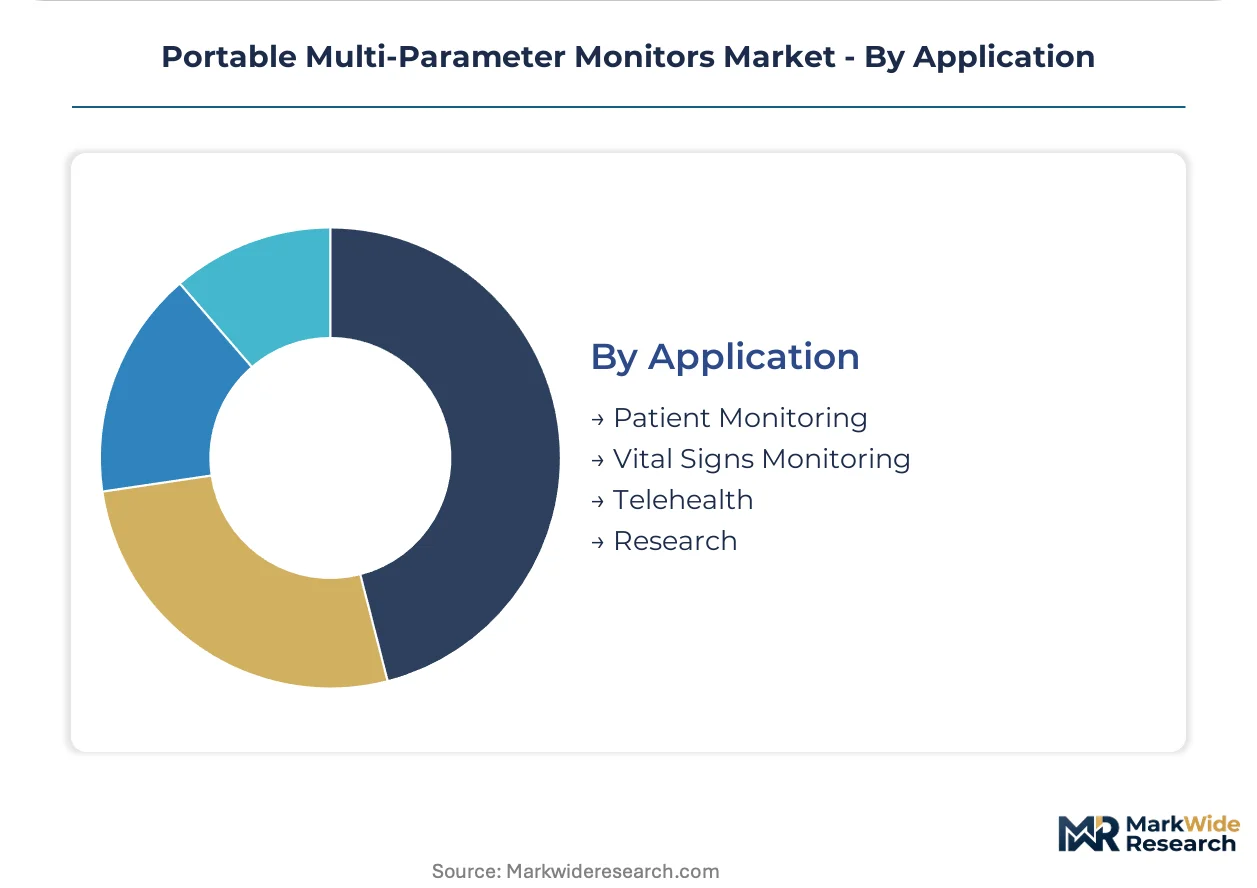
Application:
Customer type stratification separates institutional purchasers seeking workflow integration from research buyers demanding raw data access and protocol flexibility.
- Patient Monitoring:Continuous multi-parameter surveillance across cardiac care units, step-down beds, and transport corridors. FDA 510(k) clearance predicates drive feature standardization among top-tier manufacturers.
- Vital Signs Monitoring:Spot-check configurations for perioperative and general medical-surgical wards prioritize speed over trending analytics. Indian primary health centers under Ayushman Bharat deploy these for hypertension and diabetes screening.
- Telehealth:Cloud-connected platforms enable asynchronous specialist review and automated escalation protocols.
- Research:Investigational device exemptions support algorithm validation and novel biomarker discovery in academic medical centers.
Patient monitoring commands the installed base; telehealth is gaining share fastest on growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns diverge sharply by geography. US integrated delivery networks prioritize wireless interoperability and cybersecurity documentation, while Indian primary health centers under Ayushman Bharat demand cost-engineered handheld units for grid-independent deployment. Chinese manufacturing corridors supply both ends of this spectrum.
United States
Value-based care contracts from CMS accelerate replacement cycles for aging bedside infrastructure across Texas and Florida integrated delivery networks. FDA 510(k) clearance pathways and evolving premarket notification requirements for wireless medical devices compress development timelines while mandating rigorous electromagnetic compatibility testing. Academic medical centers in Boston and the Research Triangle pilot edge AI configurations for continuous telemetry substitution.
China
Shenzhen anchors the global supply base for cost-engineered multi-parameter platforms serving emerging market procurement. NMPA registration requirements and GB standards for medical electrical equipment govern domestic commercialization while export-oriented manufacturers pursue parallel FDA and CE marking tracks. The Yangtze River Delta manufacturing corridor concentrates analog front-end chip sourcing and final assembly capacity.
Germany
EU Medical Device Regulation post-market surveillance obligations and unique device identification requirements extend compliance timelines for manufacturers seeking CE marking access. German hospital tenders increasingly favor suppliers with integrated manufacturing execution systems for mandated traceability. The Baden-Württemberg and Bavaria industrial clusters host precision sensor component fabrication and clinical validation partnerships with university hospitals.
India
Ayushman Bharat primary health centers lack continuous monitoring capability, creating demand for handheld units that operate without grid-dependent installation. CDSCO medical device rules and BIS certification requirements govern import and domestic manufacturing. The Maharashtra and Gujarat pharmaceutical manufacturing corridors are diversifying into diagnostic device assembly for regional distribution.
Japan
PMDA regulatory pathways emphasize clinical evidence packages for high-risk cardiac monitoring configurations, driving consolidation of regulatory affairs functions. METI industrial policy supports domestic manufacturing precision for specialized algorithm development. The Kanto and Kansai metropolitan areas concentrate hospital procurement decision-making and clinical engineering vendor relationships.
Portable Multi-Parameter Monitors Market Competitive Landscape
Capability concentration sits with algorithm-specialist manufacturers; scale advantage sits with diversified health technology conglomerates. The market structures around three tiers: imaging ecosystem incumbents cross-selling monitoring platforms, dedicated cardiac monitoring specialists with proprietary firmware, and cost-engineered hardware fabricators serving price-sensitive procurement. Consolidation pressure intensifies as EU MDR documentation burdens favor integrated regulatory affairs functions. Dominant competitive moves include strategic partnerships for EMR interoperability and backward integration into sensor component sourcing.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and GE Healthcare occupy positions anchored by established imaging ecosystems that facilitate cross-selling into integrated hospital networks. Shenzhen Mindray Bio-Medical Electronics exemplifies the cost-engineered tier, with aggressive regulatory registrations across emerging markets supporting geographic expansion. Nihon Kohden represents the cardiac monitoring specialist archetype, with proprietary algorithm development and Japanese manufacturing precision distinguishing its positioning in high-acuity configurations.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| GE Healthcare |
| Medtronic |
| Masimo Corporation |
| Shenzhen Mindray Bio-Medical Electronics |
| Nihon Kohden |
| Spacelabs Healthcare |
| ICU Medical, Inc. |
| Drägerwerk AG & Co. KGaA |
| Others |
Value Network & Pricing Analysis
The Shenzhen-Dongguan logistics corridor anchors cost dynamics for portable multi-parameter monitors, with freight rate volatility from South China ports feeding directly into tiered pricing structures and procurement decisions across US hospital systems and Indian primary health centers.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated delivery networks and tier-one manufacturers, though spot purchasing persists for emergency department fleet refreshes. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared configurations with embedded AI from basic Bluetooth-enabled units and unlicensed emerging market variants. Cost compression in the economy tier is intensifying because Shenzhen-based fabricators are absorbing tariff exposure to maintain volume share. Federally qualified health centers exhibit the highest price sensitivity, while academic medical centers prioritize interoperability premiums over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessments for analog front-end chip sourcing. Taiwan, South Korea, and China concentrate semiconductor fabrication for specialized ADCs and sensor signal processors. Final assembly draws from the Yangtze River Delta and Pearl River Delta manufacturing corridors. Single-source vulnerability for Bluetooth Low Energy system-on-chip modules from Nordic Semiconductor and Texas Instruments creates procurement contingency planning. Distribution runs through regional clinical engineering vendors in the United States and government procurement consortia in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable multi-parameter monitors sit in early-cycle expansion as Medicare Advantage plans accelerate remote patient monitoring reimbursement and CMS readmission penalties institutionalize continuous surveillance infrastructure.
For Market Incumbents: Pre-empt algorithm commoditization by deepening proprietary arrhythmia detection firmware and securing exclusive EMR interoperability certifications with Epic and Cerner. Backward integration into SpO2 sensor manufacturing insulates margin from disposable probe cost inflation. Defensive patent filings around edge AI inference architectures block mid-tier competitors from feature parity. For New Entrants and Emerging Players: Pursue white-space penetration in Indian primary health centers under Ayushman Bharat, where cost-engineered handheld units face minimal incumbent lock-in. Telehealth-integrated home discharge bundles represent the most penetrable revenue model, shifting capital risk to equipment lessors. Direct distribution through durable medical equipment suppliers bypasses hospital GPO contract barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm-specialist manufacturers with FDA-cleared cardiac monitoring configurations over diversified hardware fabricators. Long-term viability hinges on regulatory affairs scale under EU MDR documentation burdens. Watch FDA cybersecurity guidance enforcement as the inflection signal for procurement specification tightening.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Predicate device referencing accelerates algorithm-enhanced feature deployment cycles. |
| CE Marking Pathway | EU MDR compliance creates procurement preference in German hospital tenders. |
| Hospital System Partnership | Integrated delivery network contracts bundle preventive maintenance with hardware acquisition. |
| Software Companion Development | Edge AI telemetry substitution displaces traditional cardiac monitoring installed bases. |
| Reimbursement Strategy | Medicare Advantage RPM coding determines wearable device feature specifications. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs directors converged on the working assumptions. Primary interviews with clinical engineering vendors and remote patient monitoring platform operators combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and IEC electromagnetic compatibility test registries. Bottom-up unit shipment estimates and top-down healthcare capital expenditure trends were triangulated to anchor market sizing.
Demand-supply balance framing shaped the analytical approach across the projection horizon. Segmentation modeling captured product type, connectivity protocol, end-user setting, and application context dimensions. CAGRs were derived from slope analysis of replacement cycle acceleration and penetration rate assumptions. Forecast inputs incorporated value-based care contract expansion trajectories and semiconductor foundry capacity allocation patterns.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles and trade policy enforcement would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline compression and wireless coexistence testing capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Global Fetal and Neonatal Monitoring Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Respiratory Monitoring Market
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Transcutaneous Monitors Market
Patient Monitoring
Asia Pacific Wireless Healthcare Market
Patient Monitoring
Multi-Parameter Patient Monitoring Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Continuous Cardiac Monitoring Devices Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
Global IOT Sensors in Healthcare Market
Patient Monitoring
Respiratory Monitoring Devices Market