
 Global Walking Assist Devices Market | 2026-2036
Global Walking Assist Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Walking Assist Devices Market Foresight
Modular kit configurations is pivoting buyer choice across the walking assist devices sector, enabling clinics to scale from basic mechanical walkers to sensor-equipped gait trainers without full system replacement. Ottobock leverages in-house orthotics expertise to bundle carbon-fiber crutches with custom bracing solutions. Honda Motor Co., Ltd. anchors its position through motorized drive systems originally developed for mobility robotics. GF Health Products, Inc. competes on manufacturing scale across North American distribution channels.
Walking assist devices encompass mechanical, sensor-based, motorized, hydraulic, and pneumatic apparatus engineered to redistribute body weight, stabilize gait patterns, or compensate for lower-extremity weakness through frame structures, wheel bases, or powered propulsion systems. Rollators with integrated seat-and-brake systems dominate hospital procurement due to reimbursement coding alignment, while sensor-based gait trainers command premium positioning in stroke rehabilitation protocols where real-time biofeedback accelerates neuroplastic recovery. Mechanical canes and crutches occupy the highest unit-volume tier, though margin pools concentrate in motorized segments where battery management systems and programmable speed controls differentiate clinical outcomes.
FDA 510(k) pathways govern sensor-based and motorized device introductions in the United States, while the EU Medical Device Regulation mandates clinical evidence thresholds for powered mobility aids sold under CE marking. Japan's Ministry of Economy, Trade and Industry (METI) coordinates with the Pharmaceuticals and Medical Devices Agency (PMDA) to align JIS safety standards with municipal long-term care insurance reimbursement schedules. Stakeholders must monitor how evolving software-as-medical-device classifications in major jurisdictions reshape regulatory obligations for connected walking aids.
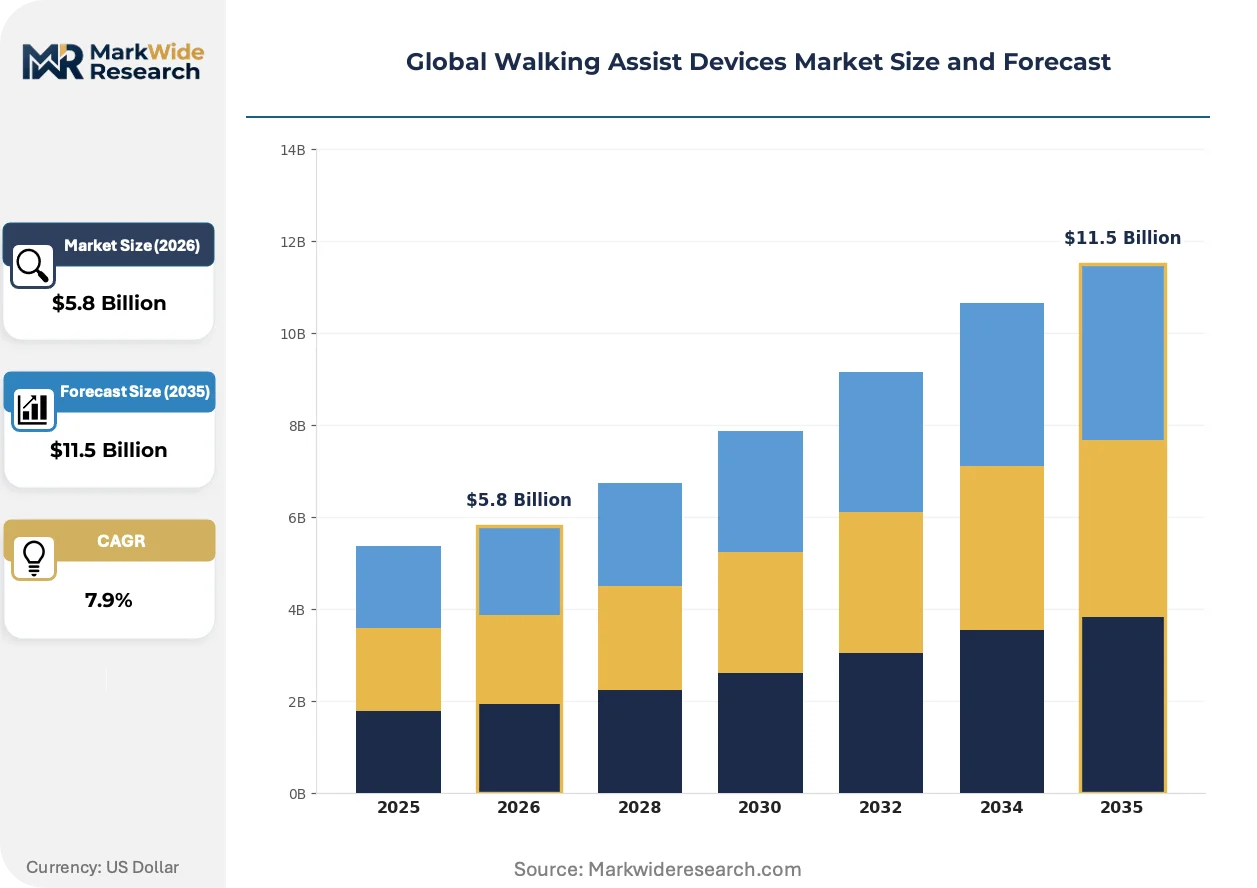
Market Dynamics
Modular kit configurations are compressing replacement cycles across clinical procurement, forcing manufacturers to architect backward-compatible sensor upgrades rather than complete system turnover.
Growth Catalysts
- Japan's long-term care insurance:Municipal subsidy frameworks under METI-PMDA coordination accelerate motorized rollator penetration in Tokyo and Osaka metropolitan networks.
- Sensor-based gait trainers:Real-time biofeedback protocols in stroke rehabilitation centers compress neuroplastic recovery timelines, expanding addressable patient populations.
- Germany's national health frameworks:Broadening reimbursement pathways for motorized mobility aids drive procurement volume in Bavarian and North Rhine-Westphalian rehabilitation networks.
Market Restraints
- Lithium-ion battery cost volatility:Supply concentration in East Asian cell manufacturers creates input price instability for motorized segment producers.
- FDA 510(k) predicate pathway maturity:Compressed clearance timelines paradoxically intensify competitive crowding in sensor-based device categories.
- Mechanical walker substitution:Low-code alternatives from Southeast Asian contract manufacturers pressure margin pools at the standard-tier price point.
Strategic Opportunities
- Software-as-medical-device classifications:Evolving FDA and EU MDR frameworks for connected walking aids create first-mover advantage in predictive gait analytics.
- Home-based rehabilitation:Post-acute care discharge protocols in the United States expand direct-to-patient channel potential for prescription-grade rollators.
- Carbon-fiber composite convergence:Lightweighting demand from geriatric user segments opens premium positioning for aerospace-derived material suppliers.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for real-time sensor fusion outpaces available talent pools in Midwestern US manufacturing corridors.
- CE marking clinical evidence thresholds:EU MDR requirements for powered mobility aids extend certification timelines by 8-14 months for novel gait trainer submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Walking Assist Devices Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canes, Crutches, Walkers, Gait Trainers, Rollators Technology: Mechanical, Sensor-Based, Motorized, Hydraulic, Pneumatic Application: Stroke Rehabilitation, Orthopedic Recovery, Pediatric Therapy, Geriatric Mobility, Neurological Disorder Support End User: Rehabilitation Centers, Home Care, Physiotherapy Clinics, Elderly Care Facilities, Pediatric Units |
| Companies Covered | Honda Motor Co., Ltd., Permobil Inc., GF Health Products, Inc., Invacare Corporation, Ottobock, Sunrise Medical, Pride Mobility Products Corp., Ossenberg GmbH, Drive DeVilbiss Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Walking Assist Devices Market Shifts & Advancements
Active sensor fusion and predictive analytics are redefining clinical value propositions, shifting competitive differentiation from mechanical stability to algorithmic gait optimization.
Machine learning-driven gait pattern recognition is converging with motorized propulsion systems to enable autonomous speed modulation based on real-time terrain assessment. Stroke rehabilitation centers in Germany and Japan are piloting these integrated platforms for hemiparetic patient cohorts. The technology is converging with traditional rollator architectures to compress the functional gap between assistive and rehabilitative device categories.
The EU Medical Device Regulation's clinical evidence requirements for powered mobility aids are forcing manufacturers to construct prospective registry studies rather than rely on predicate equivalence. This regulatory elevation disproportionately burdens mid-tier suppliers lacking dedicated clinical affairs infrastructure. German and French notified bodies are prioritizing review capacity for gait trainer submissions with embedded artificial intelligence components.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, creating standalone revenue streams for technical support and preventive maintenance. This disintermediation is most pronounced in United States academic medical centers with dedicated clinical engineering departments. Japanese municipal care networks retain bundled purchasing models, preserving traditional supplier relationships.
Global Walking Assist Devices Market Segmentation
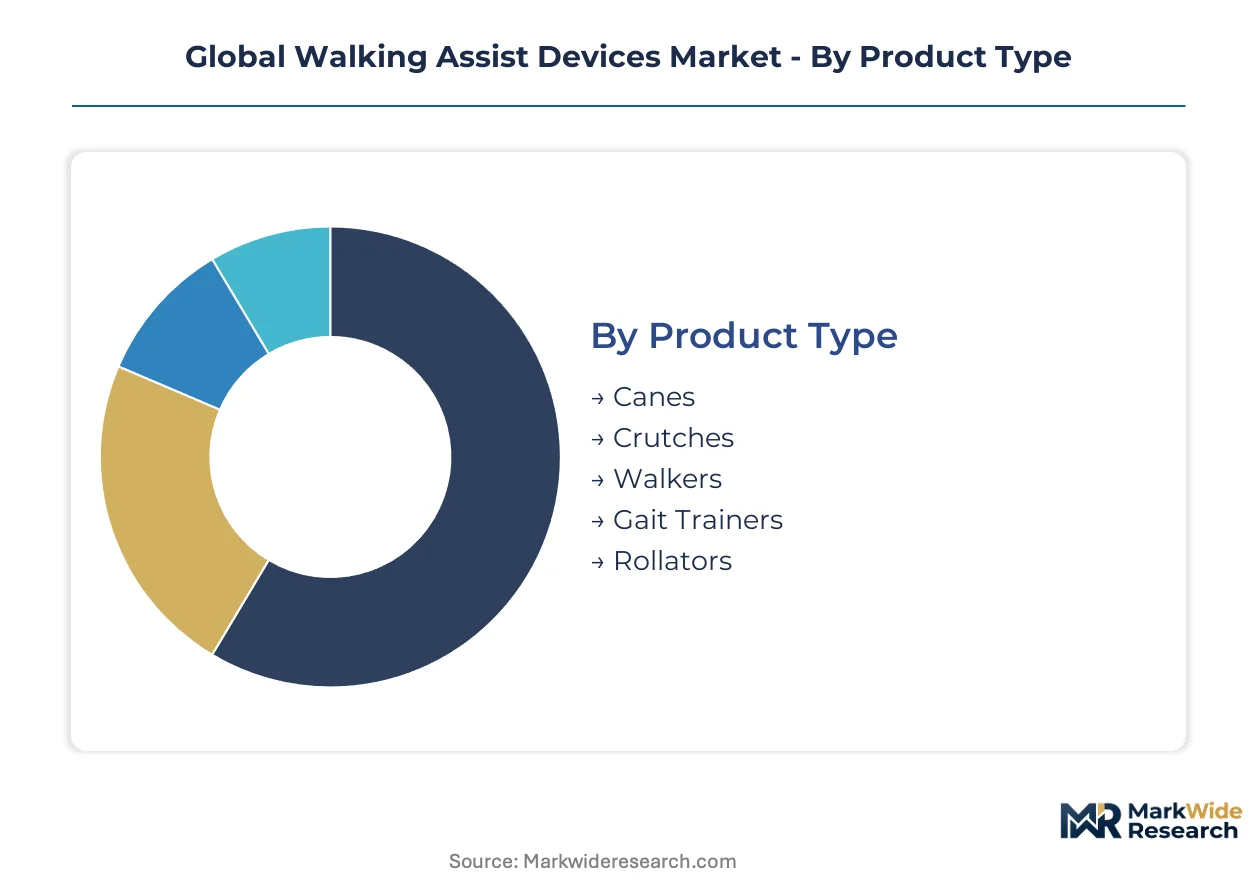
Walking assist devices fragment across four intersecting dimensions that reshape procurement economics and clinical utility. Technology tiers separate commodity mechanical aids from algorithmic gait optimization platforms. Application specificity determines reimbursement coding alignment and service intensity requirements.
Product Type:
Frame architecture and wheel configuration distinguish mobility outcomes across patient ambulation capacity.
- Canes:Single-point contact devices in aluminum, carbon-fiber, or quad-base configurations dominate geriatric outpatient dispensing. Demand concentrates in Japanese municipal long-term care networks where single-point aids qualify for streamlined insurance reimbursement.
- Crutches:Axillary and forearm variants redistribute weight through upper-extremity loading for temporary lower-limb offloading. Orthopedic recovery protocols in German rehabilitation centers drive volume for adjustable-height aluminum models with ergonomic grip systems.
- Walkers:Standard and wheeled frame structures provide anterior stability for moderate balance impairment. Pediatric therapy applications in United States early intervention programs favor lightweight folding designs for transportability between clinical and home environments.
- Gait Trainers:Posterior or anterior support frames with harness systems enable partial weight-bearing ambulation for neurological rehabilitation. Stroke rehabilitation centers in Japan and Germany pilot sensor-integrated variants with real-time biofeedback capabilities.
- Rollators:Four-wheeled frames with integrated hand brakes, seats, and storage baskets support community ambulation for chronic conditions. Bavarian and North Rhine-Westphalian rehabilitation networks expand procurement of motorized variants as national health frameworks broaden reimbursement pathways.
Mature deployment sits with rollators in elderly care facilities. Newer deployment is concentrated in sensor-equipped gait trainers.
Technology:
Actuation mechanisms separate passive assistance from active propulsion and intelligent adaptation.
- Mechanical:Passive frame structures rely on gravity and user-generated force without powered components. Southeast Asian contract manufacturers pressure margin pools through low-code production of standard walkers and canes for price-sensitive procurement channels.
- Sensor-Based:Inertial measurement units and pressure arrays capture gait kinematics for real-time feedback or remote monitoring. FDA 510(k) clearance timelines compress as predicate pathways mature, intensifying competitive crowding in stroke rehabilitation applications.
- Motorized:Battery-powered drive systems with programmable speed controls and terrain-adaptive algorithms assist users with severe lower-extremity weakness. Lithium-ion cell cost volatility from East Asian supply concentration creates input price instability for rollator and gait trainer producers.
- Hydraulic:Fluid-based resistance systems enable graded weight-bearing progression in clinical gait training. Physiotherapy clinics in Germany deploy these for controlled loading protocols in post-surgical orthopedic recovery.
- Pneumatic:Air-pressure actuation provides lightweight power assistance for pediatric and geriatric user segments with limited strength capacity. Japanese metropolitan elderly care networks evaluate these for indoor mobility where battery weight poses handling constraints.
Mechanical platforms retain volume leadership. Motorized systems are climbing the fastest on value concentration.
Application:
Clinical indication determines device specification, reimbursement tier, and outcome measurement protocol.
- Stroke Rehabilitation:Hemiparetic gait restoration requires asymmetric support with biofeedback-driven neuroplastic optimization. Sensor-based gait trainers with machine learning pattern recognition compress recovery timelines in German and Japanese pilot programs.
- Orthopedic Recovery:Post-fracture or joint replacement protocols demand graduated weight-bearing with load monitoring. Rehabilitation centers prioritize hydraulic and mechanical systems with adjustable resistance for controlled progression.
- Pediatric Therapy:Developmental delay and cerebral palsy applications require growth-adjustable frames with engaging interface design. Early intervention programs in United States school districts drive procurement of colorful, lightweight gait trainers with posterior support configurations.
- Geriatric Mobility:Chronic balance impairment and sarcopenia management favor stable, low-effort devices with rest capabilities. Elderly care facilities in Japan's metropolitan networks subsidize motorized rollator acquisition through municipal long-term care insurance.
- Neurological Disorder Support:Parkinson's disease, multiple sclerosis, and ALS progression demand adaptive devices for evolving symptom profiles. Home care channels in the United States expand for prescription-grade rollators with modular upgrade paths.
Geriatric mobility commands installed base dominance. Stroke rehabilitation is gaining share fastest on technology premiumization.
End User:
Care setting determines purchase authority, service integration requirements, and patient acuity profile.
- Rehabilitation Centers:Inpatient and outpatient facilities with multidisciplinary teams specify high-duty-cycle devices for intensive therapy protocols. German networks in Bavaria and North Rhine-Westphalia lead motorized rollator procurement volume.
- Home Care:Discharge-to-home pathways and aging-in-place preferences expand direct-to-patient channels for prescription-grade devices. United States post-acute care protocols drive demand for rollators with modular sensor upgrade compatibility.
- Physiotherapy Clinics:Private practice settings prioritize portable, multi-patient equipment with rapid adjustment capabilities. Hydraulic gait trainers with tool-free height modification dominate for orthopedic recovery patient throughput.
- Elderly Care Facilities:Residential and nursing home environments require durable, low-maintenance fleets with standardized training protocols. Japanese municipal networks retain bundled purchasing models preserving traditional supplier relationships.
- Pediatric Units:Hospital-based and outpatient pediatric services specify growth-accommodating designs with safety certification for vulnerable populations. Early intervention programs favor lightweight folding walkers for parent transportability.
Rehabilitation centers anchor premium technology adoption. Home care channels are expanding most quickly on reimbursement pathway evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters supply motorized drive systems to North American and European rehabilitation networks, while consumption concentrates in aging metropolitan corridors with mature reimbursement infrastructure.
United States
Post-acute care discharge protocols and Medicare Advantage expansion drive prescription-grade rollator procurement. FDA 510(k) predicate pathways compress clearance timelines for sensor-based gait trainers. Academic medical centers in Boston and Philadelphia unbundle after-sales service contracts from capital equipment purchases.
Germany
Bavarian and North Rhine-Westphalian rehabilitation networks expand motorized rollator acquisition as national health frameworks broaden reimbursement pathways. EU Medical Device Regulation clinical evidence thresholds extend certification timelines for novel gait trainer submissions. Physiotherapy clinics in Munich deploy hydraulic systems for controlled post-surgical loading protocols.
Japan
Metropolitan elderly care networks in Tokyo and Osaka subsidize device acquisition through municipal long-term care insurance coordinated by METI-PMDA. JIS safety standards align with reimbursement schedules for single-point canes and motorized rollators. Kansai region clinics pilot sensor-integrated gait trainers for hemiparetic stroke recovery.
China
Domestic production scales for mechanical walker export to Southeast Asian price-sensitive procurement channels. NMPA regulatory pathways mature for powered mobility aids targeting hospital rehabilitation departments. Yangtze River Delta manufacturing clusters supply lithium-ion battery management systems to motorized segment producers.
Global Walking Assist Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale-driven manufacturers face capability-intensive innovators. The vendor base organizes around three strategic archetypes: automotive-derived mobility technology diversifiers, orthotics-anchored rehabilitation specialists, and contract-manufacturing-scale distributors. Consolidation pressures intensify as modular kit configurations force backward compatibility investments, while M&A activity targets sensor fusion firmware capabilities and geographic expansion into municipal insurance networks.
Within the automotive-technology tier, Honda Motor Co., Ltd. exemplifies diversification into powered drive systems, while Ottobock represents orthotics-anchored bundling of carbon-fiber solutions with custom bracing. GF Health Products, Inc. occupies a position among North American distribution-scale competitors. These three entities anchor distinct competitive vectors: technology convergence, clinical integration, and manufacturing scale.
| Leading Market Players |
|---|
| Honda Motor Co., Ltd. |
| Permobil Inc. |
| GF Health Products, Inc. |
| Invacare Corporation |
| Ottobock |
| Sunrise Medical |
| Pride Mobility Products Corp. |
| Ossenberg GmbH |
| Drive DeVilbiss Healthcare |
| Others |
Supply & Pricing Matrix
Sensor fusion firmware migration from discrete components to integrated system-on-chip architectures simultaneously compresses per-unit electronics costs and concentrates procurement leverage among semiconductor foundries with medical-grade fabrication capacity. This dual compression reshapes margin economics for motorized rollator producers while amplifying dependency on East Asian battery management system suppliers.
Pricing Analysis
Margin tightening in the standard mechanical tier reflects Southeast Asian contract manufacturer scale expansion and direct-to-hospital procurement platform proliferation. Three-tier pricing structure across premium sensor-integrated, standard motorized, and economy mechanical levels separates reimbursement-coded rollators from cash-pay canes. Cost-down pressure on mechanical walkers accelerates because pediatric therapy programs prioritize transportability over durability. Geriatric care facilities exhibit lowest price sensitivity due to municipal insurance subsidy absorption, while physiotherapy clinics face acute margin compression from multi-patient equipment throughput demands.
Supply Chain Analysis
Japan's domestic-content alignment between METI safety standards and municipal procurement guidelines reshapes sourcing patterns for lithium-ion cell integration. Manufacturing gravity centers on China for mechanical frame stamping, South Korea for battery cell production, and Germany for hydraulic actuator precision machining. Raw material dependencies span aerospace-grade aluminum extrusions, medical-device-certified polymers, and rare-earth magnet assemblies for motorized drive systems. Single-source vulnerability concentrates in East Asian battery management system firmware where foundry capacity constraints create allocation risk. Distribution runs through rehabilitation center GPO contracts in the United States, direct municipal procurement in Japan, and specialized orthotics distributors in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems engineering scarcity props pricing power for motorized segment producers capable of in-house firmware development, creating durable margin premiums against mechanical commodity competitors.
For Market Incumbents: Anticipate sensor-based gait trainer category crowding as FDA 510(k) predicate pathways mature, and respond through backward integration into carbon-fiber composite production for lightweighting differentiation. Defensive consolidation should target firmware development teams in Midwestern US manufacturing corridors where talent pools are thinnest, while CE marking clinical evidence investments extend competitive moats against mid-tier European challengers. For New Entrants and Emerging Players: Enter via home care channel direct-to-patient models where post-acute care discharge protocols in the United States expand prescription-grade rollator access outside hospital procurement committees. White-space concentrates in pneumatic actuation for indoor geriatric mobility where battery weight constraints limit incumbent motorized solutions. Go-to-market positioning should emphasize modular upgrade compatibility with existing mechanical walker installed bases. For Investors and Strategic Acquirers: Re-rating potential sits with orthotics-anchored rehabilitation specialists given bundling synergies between carbon-fiber mobility aids and custom bracing solutions. Long-term viability over the five-to-ten year window favors manufacturers with captive clinical affairs infrastructure capable of navigating EU MDR evidence thresholds. Acquisition target archetype: mid-tier gait trainer developers with embedded AI components awaiting notified body prioritization. Signal to watch: German and French regulatory review queue depth for sensor-integrated submissions.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device Classification Investment | FDA and EU MDR framework alignment creates first-mover positioning in predictive gait analytics reimbursement. |
| Carbon-Fiber Composite Backward Integration | Aerospace material supplier partnerships enable premium positioning in lightweight geriatric rollator segments. |
| Municipal Insurance Network Partnership | Tokyo and Osaka metropolitan care coordination secures subsidized acquisition pathways for motorized variants. |
| Sensor Fusion Firmware Acquisition | Midwestern US engineering talent scarcity makes embedded systems capabilities strategic defensive assets. |
| CE Marking Clinical Registry Construction | Prospective evidence generation satisfies EU MDR powered mobility aid thresholds ahead of mid-tier competitors. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, METI-PMDA reimbursement schedule adjustments, and EU MDR notified body queue depths anchored the trend analysis, supplemented by interviews with rehabilitation center procurement directors, biomedical engineers, GPO contracts managers, and orthotics specialists. Secondary validation drew from FDA device listings, EUDAMED registration databases, Japanese municipal long-term care insurance expenditure reports, and hospital procurement database extracts. Bottom-up demand modeling across technology tiers triangulated against top-down national health framework expenditure projections.
Segment-weighting approaches distributed value estimates across mechanical, sensor-based, motorized, hydraulic, and pneumatic technology tiers, with further stratification by stroke rehabilitation, orthopedic recovery, pediatric therapy, geriatric mobility, and neurological disorder support applications. CAGRs derived from installed base replacement cycle compression, reimbursement pathway expansion velocity, and neuroplastic recovery protocol adoption curves. Forecast inputs incorporated lithium-ion cell cost trajectory assumptions and embedded systems engineering wage inflation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA software-as-medical-device reclassification scenarios or East Asian battery supply disruption events. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Global Microkeratome Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Electrophysiology Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
Superficial Radiation Therapy System Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Global Capnography Market
Medical Devices
Pedicle Screw Systems Market
Medical Devices
Global Microdermabrasion Devices Market