
 Cardiac Rhythm Remote Monitoring Devices Market | 2026-2036
Cardiac Rhythm Remote Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Rhythm Remote Monitoring Devices Market Outlook
Subscription-based remote monitoring software is hardening into the core revenue layer of cardiac rhythm management, shifting vendor economics from device sales toward recurring platform fees. Medtronic leverages its integrated CareLink network to sustain long-term patient relationships beyond the initial implant procedure. Abbott anchors its competitive stance through catheter-free rhythm monitoring systems that reduce clinic dependency. Boston Scientific Corporation differentiates via extended connectivity partnerships with electronic health record platforms.
Cardiac rhythm remote monitoring devices encompass implantable, wearable, and external systems that capture electrophysiological signals and transmit data through cellular, Bluetooth, or cloud-based infrastructure for clinician review, with typical sampling rates exceeding 256 Hz for diagnostic-grade arrhythmia detection. Mobile cardiac telemetry systems lead clinical adoption due to real-time alarm capabilities, while wearable monitors represent the fastest-expanding segment as consumer-grade form factors penetrate preventive cardiology programs. Cloud-based solutions concentrate margin pools through software licensing and data analytics services layered atop hardware deployments.
The FDA regulates these devices under 21 CFR Part 820 quality system requirements and increasingly enforces cybersecurity controls through premarket guidance, while HIPAA governs patient data transmission and storage protocols across connected care workflows. The Centers for Medicare & Medicaid Services shapes demand through reimbursement codes that determine whether remote monitoring services qualify for physician fee schedule payment. Stakeholders must monitor evolving cybersecurity validation requirements and reimbursement granularity as these twin forces determine which platform architectures achieve sustainable commercial traction.
Market Dynamics
The transition from episodic clinic visits to continuous cloud-based monitoring is restructuring cardiac rhythm management economics, with reimbursement codes now favoring remote physiologic monitoring over traditional in-person follow-up protocols.
Growth Catalysts
- CMS reimbursement expansion:Medicare physician fee schedule codes for remote cardiac monitoring services now cover implantable loop recorders and mobile cardiac telemetry, accelerating hospital outpatient department adoption across the United States.
- Wearable form factor maturation:Patch-based electrocardiogram monitors with 14-day wear durations achieve diagnostic-grade signal fidelity, penetrating preventive cardiology programs previously served by Holter monitors.
- FDA premarket cybersecurity guidance:The agency's 2023 guidance on post-market management of cybersecurity in medical devices establishes validation benchmarks that favor established platform vendors with mature quality systems.
Market Restraints
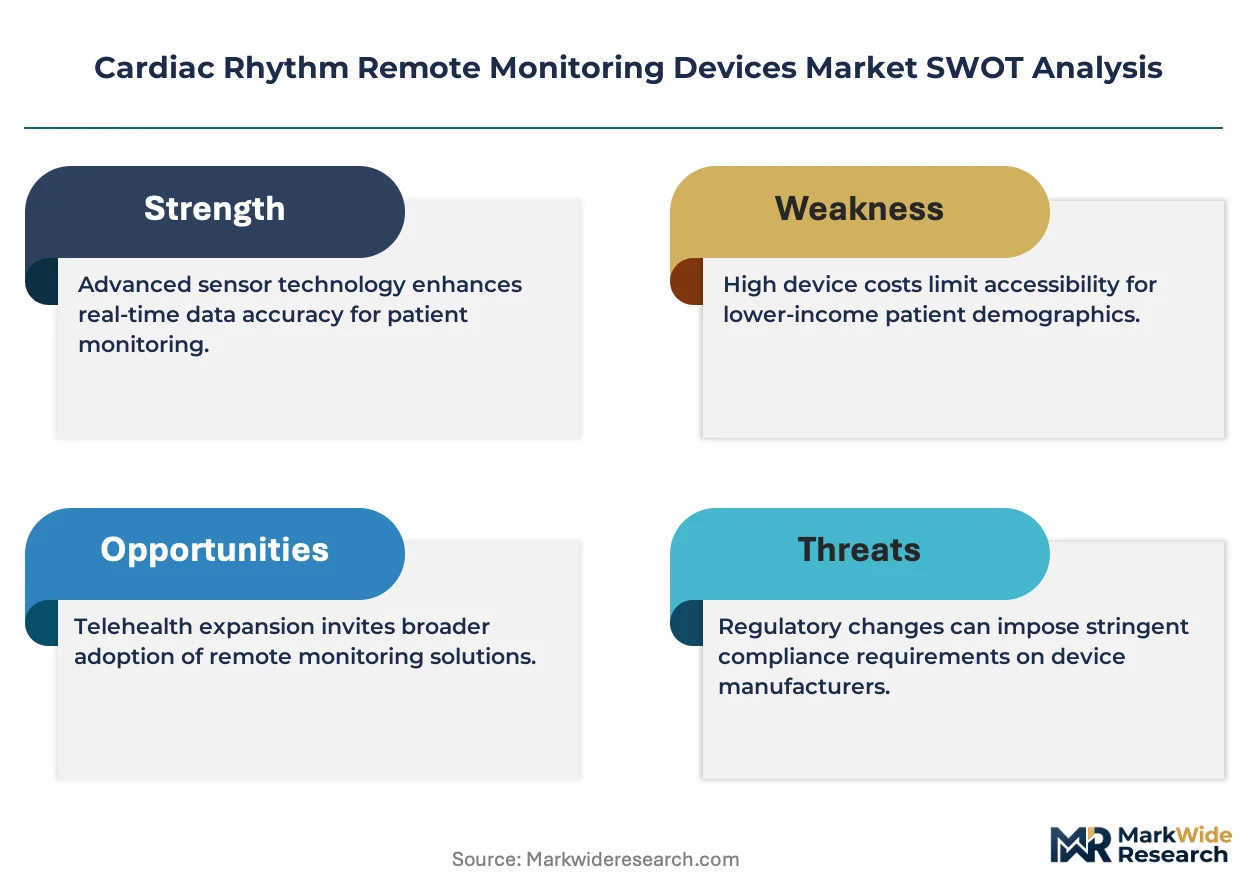
- Semiconductor supply concentration:Custom ASICs for ultra-low-power ECG signal processing depend on Taiwan-based foundry capacity, exposing device manufacturers to geopolitical supply disruptions.
- Cellular connectivity cost structure:Recurring data transmission fees for embedded SIM modules in implantable devices compress margins on hardware sales, particularly in price-sensitive ambulatory surgical center channels.
- Substitution by consumer wearables:Apple Watch irregular rhythm notification and similar consumer-grade atrial fibrillation detection functions satisfy low-acuity screening demand outside reimbursed clinical workflows.
Strategic Opportunities
- India cardiac center network expansion:Corporate hospital chains in Mumbai, Delhi, and Bangalore are building remote monitoring infrastructure for medical tourism patients requiring post-implant surveillance.
- Artificial intelligence-ECG convergence:Machine learning algorithms trained on cloud-aggregated rhythm databases enable automated preliminary interpretation, reducing cardiologist review burden and expanding panel capacity.
- Direct-to-patient subscription channels:Employer wellness programs and health plans are piloting standalone remote monitoring services that bypass traditional device-implant-referral pathways.
Industry Challenges
- Electrophysiologist workforce constraints:The specialized training pipeline for device interrogation and arrhythmia interpretation creates bottlenecks as monitoring panel volumes expand beyond tertiary academic centers.
- Legacy EHR integration complexity:Proprietary data formats from competing device platforms require costly middleware development to achieve seamless flow into Epic and Cerner electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Rhythm Remote Monitoring Devices Market |
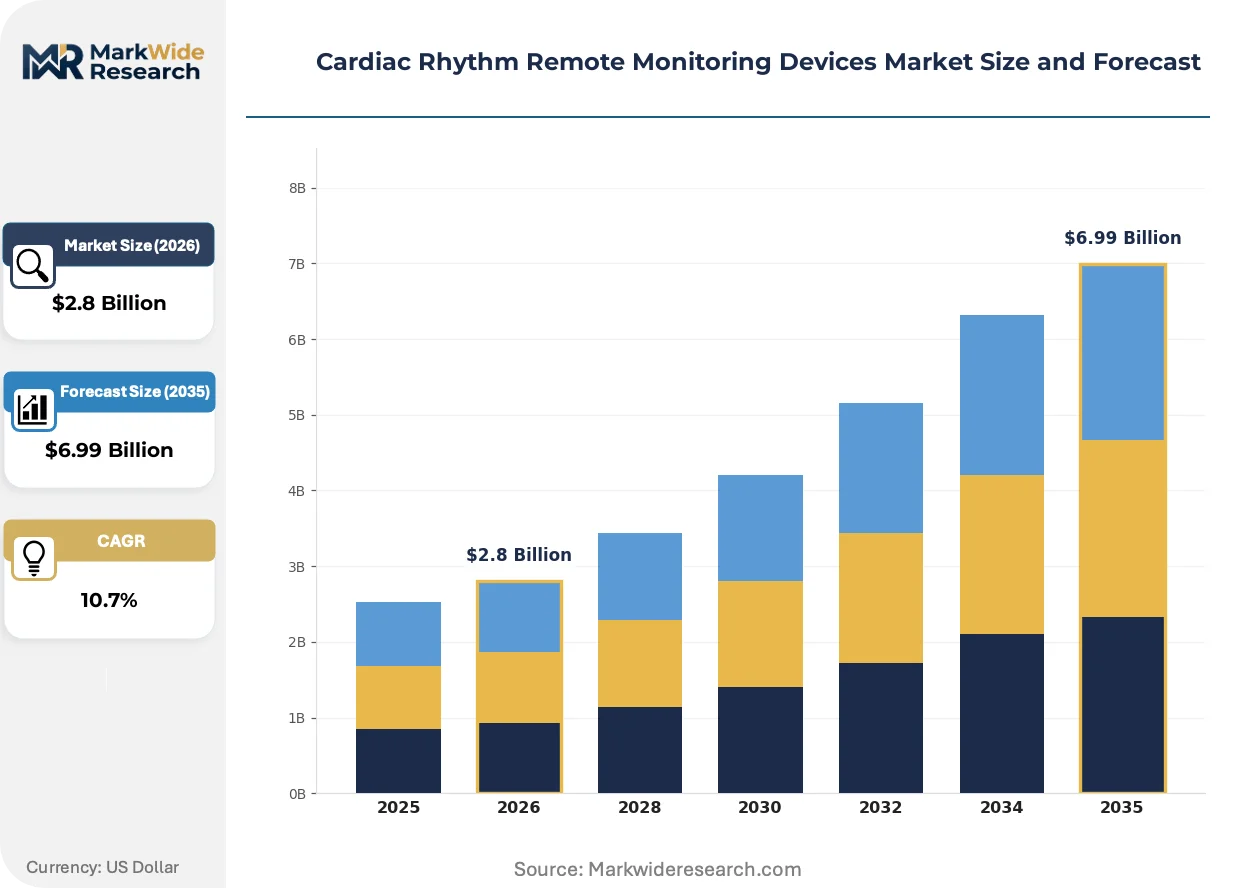
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.99 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Loop Recorders, Mobile Cardiac Telemetry, Wearable Monitors, External Holter Monitors Technology: Cloud-Based Solutions, Bluetooth Technology, Mobile Apps, Remote Patient Monitoring Systems End User: Healthcare Providers, Telehealth Services, Home Care Services, Clinical Research Organizations Application: Arrhythmia Monitoring, Patient Management, Data Collection, Clinical Trials |
| Companies Covered | Medtronic, Abbott, Boston Scientific Corporation, BIOTRONIK, iRhythm Technologies, Koninklijke Philips N.V., GE Healthcare, LivaNova, Zoll Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Rhythm Remote Monitoring Devices Market Strategic Shifts
Cardiac rhythm monitoring is fragmenting across multiple sensing modalities and care settings, with algorithmic interpretation and connectivity infrastructure now determining competitive position more than raw hardware specifications.
Bluetooth-enabled wearable patch monitors with dry electrode arrays is decentralizing arrhythmia detection from hospital-based telemetry units to home environments. Regional health systems in Texas and Florida are deploying these devices for post-discharge surveillance of heart failure patients. The shift compresses emergency department utilization for palpitation workups while expanding addressable patient populations beyond implant-eligible cohorts.
The FDA's 2024 update to cybersecurity premarket guidance requires threat modeling documentation and software bill of materials disclosure for all networked cardiac devices. Manufacturers must demonstrate secure update mechanisms and vulnerability disclosure programs prior to 510(k) clearance. Implantable cardioverter-defibrillator platforms face the steepest compliance burden given their life-sustaining function and long in-body residence.
Hospital procurement committees are unbundling device acquisition from monitoring service contracts, creating separate vendor relationships for hardware, connectivity, and clinical interpretation. This purchasing pattern fragmentation favors specialized software platforms that aggregate multi-manufacturer device data. The unbundling trend is most pronounced in United States integrated delivery networks with captive electrophysiology groups.
Cardiac Rhythm Remote Monitoring Devices Market Segmentation
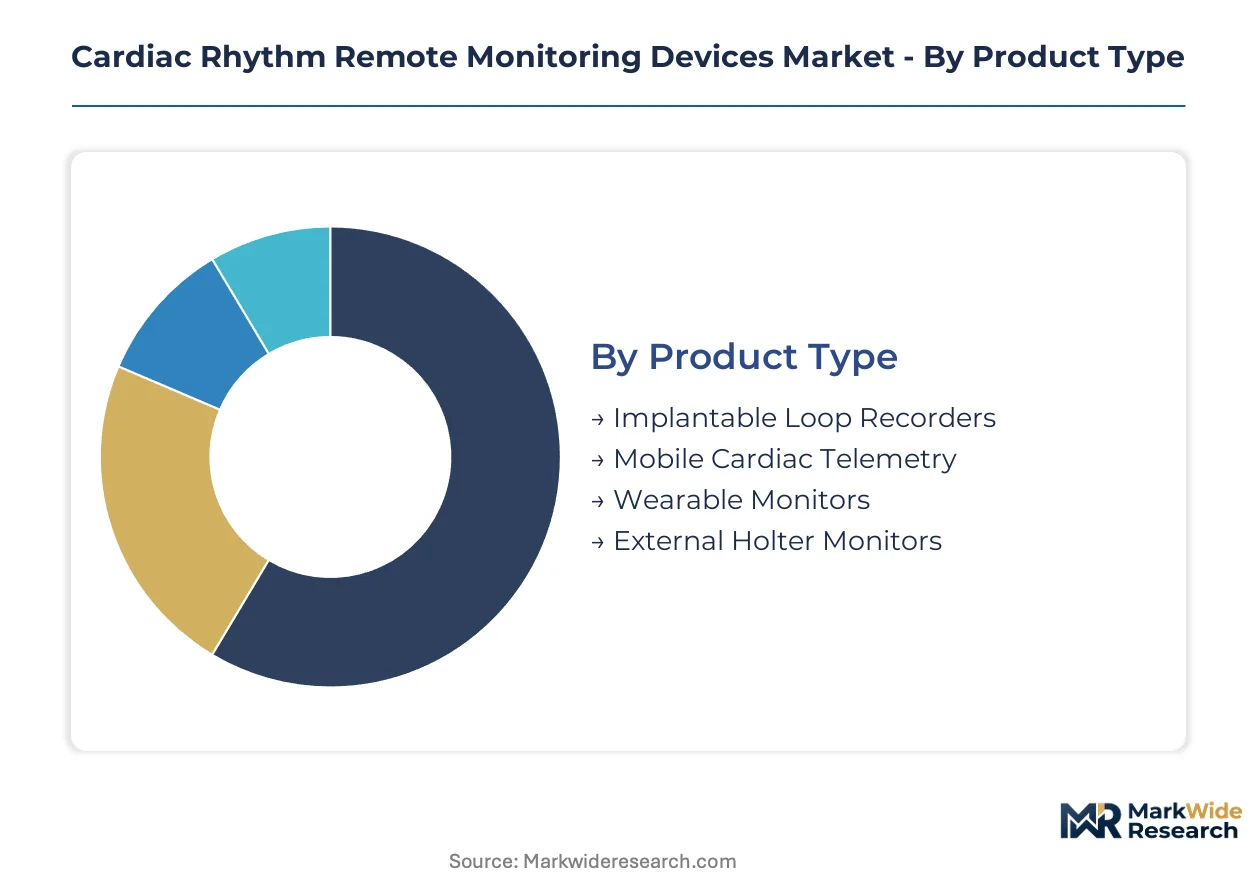
Device selection in cardiac rhythm remote monitoring pivots on the trade-off between diagnostic precision and patient mobility, with reimbursement codes increasingly favoring modalities that sustain continuous data capture outside institutional walls. Understanding how segments cluster across hardware form factors, connectivity architectures, and care settings clarifies where procurement budgets and platform investments are concentrating.
Product Type:
Upgrade cycles in this category accelerate where hardware obsolescence intersects with shifting reimbursement incentives, particularly as Medicare physician fee schedule revisions reward extended monitoring durations over episodic capture.
- Implantable Loop Recorders:Subcutaneous devices with multi-year battery life capture continuous ECG streams through leadless electrodes, transmitting via cellular modems to cloud repositories. Demand concentrates in United States electrophysiology practices managing cryptogenic stroke and unexplained syncope patients, where CMS reimbursement codes now cover automated alert triage services.
- Mobile Cardiac Telemetry:Real-time event-triggered systems with embedded cellular radios enable immediate clinician notification for ventricular arrhythmias and atrial fibrillation episodes. Hospital outpatient departments in Texas and Florida deploy these for post-discharge heart failure surveillance, compressing emergency department utilization.
- Wearable Monitors:Patch-based dry electrode arrays with 14-day wear durations achieve diagnostic-grade signal fidelity without clinic dependency.
- External Holter Monitors:Traditional multi-lead ambulatory systems retain position in price-sensitive health systems with limited remote monitoring infrastructure.
Volume placements concentrate in mobile cardiac telemetry systems; the faster expansion belongs to wearable monitors as preventive cardiology programs absorb consumer-grade form factors.
Technology:
Platform economics in this category hinge on recurring software licensing revenue layered atop hardware deployments, with margin pools migrating toward data analytics and connectivity infrastructure.
- Cloud-Based Solutions:Centralized data repositories aggregate rhythm streams from heterogeneous device fleets, enabling algorithmic triage and longitudinal trend analysis. United States integrated delivery networks with captive electrophysiology groups favor these platforms for unbundled procurement of monitoring services separate from device acquisition.
- Bluetooth Technology:Low-energy wireless protocols bridge wearable sensors to patient smartphones, reducing embedded cellular costs in external monitoring devices.
- Mobile Apps:Patient-facing interfaces deliver symptom correlation prompts and medication adherence nudges alongside rhythm data transmission.
- Remote Patient Monitoring Systems:Integrated platforms combining hardware, connectivity, and clinical interpretation services.
Revenue concentration sits with cloud-based solutions; Bluetooth-enabled architectures are climbing fastest as patch monitor form factors penetrate home-based surveillance.
End User:
Customer type fragmentation reflects the unbundling of device acquisition from clinical interpretation, creating distinct vendor relationships across hardware, software, and professional service layers.
- Healthcare Providers:Hospital-based electrophysiology groups and cardiology practices operate monitoring panels with dedicated device interrogation infrastructure. Tertiary academic centers in the United States maintain the deepest penetration of implantable device remote monitoring programs.
- Telehealth Services:Virtual-first cardiology platforms aggregate interpretation capacity across dispersed geographies, addressing electrophysiologist workforce constraints.
- Home Care Services:Post-acute monitoring for recently discharged cardiac patients.
- Clinical Research Organizations:Centralized rhythm adjudication for pharmaceutical trials.
Procurement volumes center on healthcare providers; telehealth services are expanding most quickly as virtual cardiology platforms address specialist scarcity.
Application:
Use case prioritization in this category tracks the migration from diagnostic confirmation toward longitudinal disease management, with algorithmic interpretation reducing cardiologist review burden.
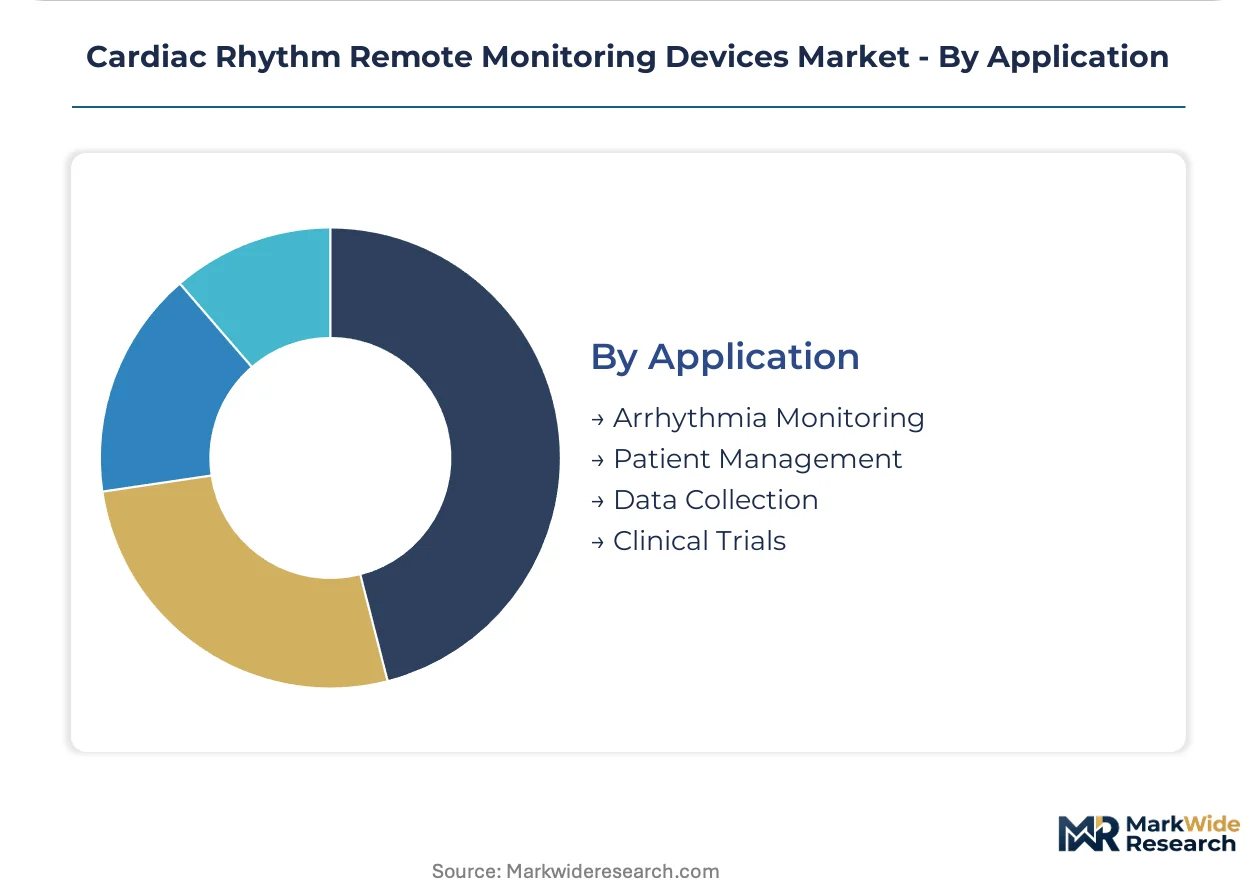
- Arrhythmia Monitoring:Detection and characterization of atrial fibrillation, ventricular tachycardia, and bradyarrhythmia episodes through automated algorithmic analysis. United States preventive cardiology programs deploy wearable monitors for population-scale AF screening.
- Patient Management:Coordinated care protocols integrating rhythm data with medication titration and lifestyle intervention.
- Data Collection:Structured repository building for quality improvement and research.
- Clinical Trials:Regulatory-grade endpoint adjudication for antiarrhythmic drug and device studies.
Deployment intensity clusters in arrhythmia monitoring; patient management applications are gaining share fastest as value-based contracts reward reduced hospitalization rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device production clusters in Minnesota, Massachusetts, and California supply cardiac rhythm monitoring hardware to electrophysiology practices worldwide. Consumption concentrates in United States hospital outpatient departments where Medicare reimbursement codes favor remote physiologic monitoring. Regulatory divergence across national health systems fragments platform deployment patterns.
United States
Hospital outpatient departments in Texas and Florida deploy mobile cardiac telemetry for post-discharge heart failure surveillance. The FDA's 2024 cybersecurity premarket guidance mandates threat modeling documentation for all networked cardiac devices. Minneapolis-St. Paul anchors implantable device manufacturing with integrated CareLink network infrastructure serving domestic electrophysiology practices.
Germany
Corporate hospital chains in Munich and Berlin build remote monitoring infrastructure for medical tourism patients requiring post-implant surveillance. The EU Medical Device Regulation (MDR) imposes enhanced clinical evidence requirements for Class III cardiac rhythm devices. Baden-Württemberg hosts precision electronics manufacturing supplying signal processing ASICs to European device vendors.
China
Domestic cardiac centers in Beijing and Shanghai expand remote monitoring programs for aging populations with atrial fibrillation burden. The National Medical Products Administration (NMPA) accelerates review pathways for innovative Class III cardiovascular devices under priority review channels. The Yangtze River Delta concentrates wearable monitor assembly operations serving price-sensitive hospital procurement committees.
India
Corporate hospital chains in Mumbai, Delhi, and Bangalore construct remote monitoring infrastructure for medical tourism patients requiring post-implant surveillance. The Central Drugs Standard Control Organization (CDSCO) harmonizes device registration requirements with IMDRF guidelines to accelerate market entry. Hyderabad's medical device cluster develops cloud-based aggregation platforms for multi-manufacturer device data integration.
Japan
Aging demographics drive ambulatory monitoring demand in Tokyo and Osaka metropolitan cardiology practices. The Pharmaceuticals and Medical Devices Agency (PMDA) enforces post-market surveillance requirements for implantable cardiac devices through mandatory adverse event reporting. The Kansai region hosts electronics manufacturing supplying Bluetooth-enabled wearable patch monitors for home-based surveillance programs.
Cardiac Rhythm Remote Monitoring Devices Market Competitive Environment
Top-tier vendors anchor integrated platform ecosystems, while mid-tier specialists compete on unbundled software and connectivity services. The vendor base stratifies across implantable device manufacturers, wearable monitor developers, and cloud-based aggregation platforms. Three archetypes dominate: vertically integrated implantable device vendors, catheter-free rhythm monitoring specialists, and multi-manufacturer data aggregation platforms. M&A activity concentrates on software capabilities and EHR integration assets; strategic partnerships target extended connectivity with electronic health record systems.
Among integrated implantable device vendors, Medtronic and Boston Scientific Corporation exemplify platform-centric positioning through recurring monitoring service revenue layered atop hardware deployments. Abbott occupies a distinct position within catheter-free monitoring through patch-based systems that reduce clinic dependency. These three entities represent the dominant competitive anchors shaping procurement patterns in United States integrated delivery networks.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| BIOTRONIK |
| iRhythm Technologies |
| Koninklijke Philips N.V. |
| GE Healthcare |
| LivaNova |
| Zoll Medical Corporation |
| Others |
Value Chain & Pricing Dynamics
Custom ASIC fabrication costs for ultra-low-power ECG signal processing trace from Taiwan-based foundry capacity through tiered hardware pricing to ambulatory surgical centers absorbing compressed margins on implantable cellular modules.
Pricing Analysis
Margin tightening in wearable patch monitors reflects embedded cellular cost compression as Bluetooth-enabled architectures displace real-time telemetry in preventive cardiology programs. Three-tier pricing structure across premium diagnostic-grade, standard clinical, and economy consumer-adjacent levels separates FDA-cleared implantable systems from patch-based external monitors and consumer-wearable screening tools. Cost-down pressure on hardware sales accelerates because hospital procurement committees unbundle device acquisition from monitoring service contracts. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with captive electrophysiology groups demonstrate lowest sensitivity due to recurring platform fee absorption.
Supply Chain Analysis
Electronics assembly workforce availability in Minnesota, Massachusetts, and California anchors implantable device manufacturing clusters serving domestic electrophysiology practices. Signal processing ASICs draw from Taiwan-based foundry capacity; dry electrode arrays source from precision manufacturing in Baden-Württemberg; cloud infrastructure rests on hyperscaler data center networks across the United States. Single-source vulnerability concentrates in Taiwan semiconductor fabrication for custom ultra-low-power chips. Distribution runs through hospital procurement committees and group purchasing organizations consolidating multi-manufacturer device acquisitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's evolving cybersecurity premarket guidance erects a compliance moat favoring established platform vendors with mature quality systems and documented secure update mechanisms.
For Market Incumbents: Acquire AI-ECG interpretation capabilities to automate preliminary rhythm analysis and expand electrophysiologist panel capacity beyond tertiary academic centers. Deepen backward integration into cloud infrastructure to capture software licensing margin pools migrating from hardware sales. Counter catheter-free monitoring specialists by embedding extended connectivity partnerships with Epic and Cerner electronic health record platforms.
For New Entrants and Emerging Players: Direct-to-patient subscription channels bypass traditional device-implant-referral pathways and unlock employer wellness program procurement. Target India corporate hospital chains in Mumbai, Delhi, and Bangalore constructing remote monitoring infrastructure for medical tourism patients. Lead with standalone monitoring services unbundled from hardware acquisition to penetrate price-sensitive ambulatory surgical center channels.
For Investors and Strategic Acquirers: FDA 510(k) clearance timelines extending for cybersecurity documentation is the leading indicator that platform consolidation will accelerate among compliant vendors. Five-to-ten year viability favors multi-manufacturer data aggregation platforms with established EHR integration assets. Monitor unbundled procurement patterns in United States integrated delivery networks as signal of software-centric margin capture displacing hardware-dependent revenue models.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Epic and Cerner EHR integration secures longitudinal patient data flow and panel retention. |
| Software Companion Development | AI-ECG algorithms trained on cloud-aggregated rhythm databases reduce cardiologist review burden. |
| Reimbursement Strategy | CMS physician fee schedule code capture determines whether remote monitoring services qualify for payment. |
| FDA Submission | Threat modeling documentation and software bill of materials disclosure satisfy 2024 cybersecurity guidance. |
| CE Marking Pathway | EU MDR clinical evidence requirements for Class III cardiac rhythm devices filter subscale competitors. |
Study Parameters
Independent corroboration across electrophysiologist interviews, hospital procurement manager discussions, and biomedical engineer consultations underwrites the qualitative findings. Primary fieldwork with GPO contracts managers and cloud platform engineering leads combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up device shipment modeling and top-down healthcare IT spending analysis triangulate market size estimates.
Comparable historical periods anchored the forecast window to pre-pandemic baseline utilization and post-2023 reimbursement expansion phases. Segmentation dimensions span hardware form factor, connectivity architecture, end-user setting, and application intensity across the projection horizon. CAGRs derived from logistic diffusion curves modeling wearable monitor penetration into preventive cardiology programs and implantable device replacement cycles. Forecast inputs incorporate electrophysiologist workforce pipeline constraints and cybersecurity validation timeline extensions.
The model holds under stable CMS reimbursement codes and Taiwan semiconductor supply continuity; deviation in FDA cybersecurity enforcement intensity or foundry capacity allocation would shift hardware availability timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Cerebral Oximetry Monitoring Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Global Heart Rate Monitor Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
Fetal and Neonatal Heart Monitor Market