
 North America Wearable Medical Devices Market | 2026-2036
North America Wearable Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wearable Medical Devices Market Intelligence
The FDA's evolving framework for Software as a Medical Device (SaMD) is expanding the compliance burden for new market entrants in North America. Apple Inc. leverages its vast consumer electronics ecosystem to integrate health monitoring features into its products. Dexcom, Inc. specializes in continuous glucose monitoring technology for diabetes patients. Abbott Laboratories competes across multiple therapeutic areas with its portfolio of wearable biosensors for cardiac and metabolic conditions.
Wearable medical devices are non-invasive electronic instruments worn on the body to collect physiological data continuously. These devices incorporate biosensors and often use Bluetooth connectivity to transmit data to a smartphone or a cloud-based platform. While smartwatches represent a high-volume segment, dedicated biosensors for cardiac monitoring and diabetes management are seeing rapid adoption within clinical settings. These specialized applications command higher value due to their clinical-grade accuracy and direct impact on patient outcomes.
The regulatory environment is primarily shaped by the FDA in the United States and Health Canada, which oversee device classification and market approval. Data privacy regulations, particularly HIPAA in the US, impose strict requirements on how patient information is handled. Navigating the distinction between consumer wellness gadgets and clinically validated medical devices remains a central strategic challenge for all market participants.
Market Dynamics
The central force shaping the North America wearable medical devices market is the strategic imperative among large integrated hospital systems to adopt remote patient monitoring technologies. This push aims to manage chronic conditions more effectively and reduce long-term healthcare costs.
Growth Catalysts
- Regulatory Streamlining:The FDA's Digital Health Center of Excellence initiative is accelerating market entry by providing clearer regulatory pathways for novel software-based medical devices and digital health technologies.
- Provider-Led Demand:Large hospital networks in the United States are actively deploying wearable sensors for remote patient monitoring programs, targeting conditions like diabetes and heart failure to improve outcomes.
- Technology Maturation:Advances in biosensor miniaturization and the widespread integration of low-energy Bluetooth connectivity enable the creation of more accurate, user-friendly devices for continuous data collection.
Market Restraints
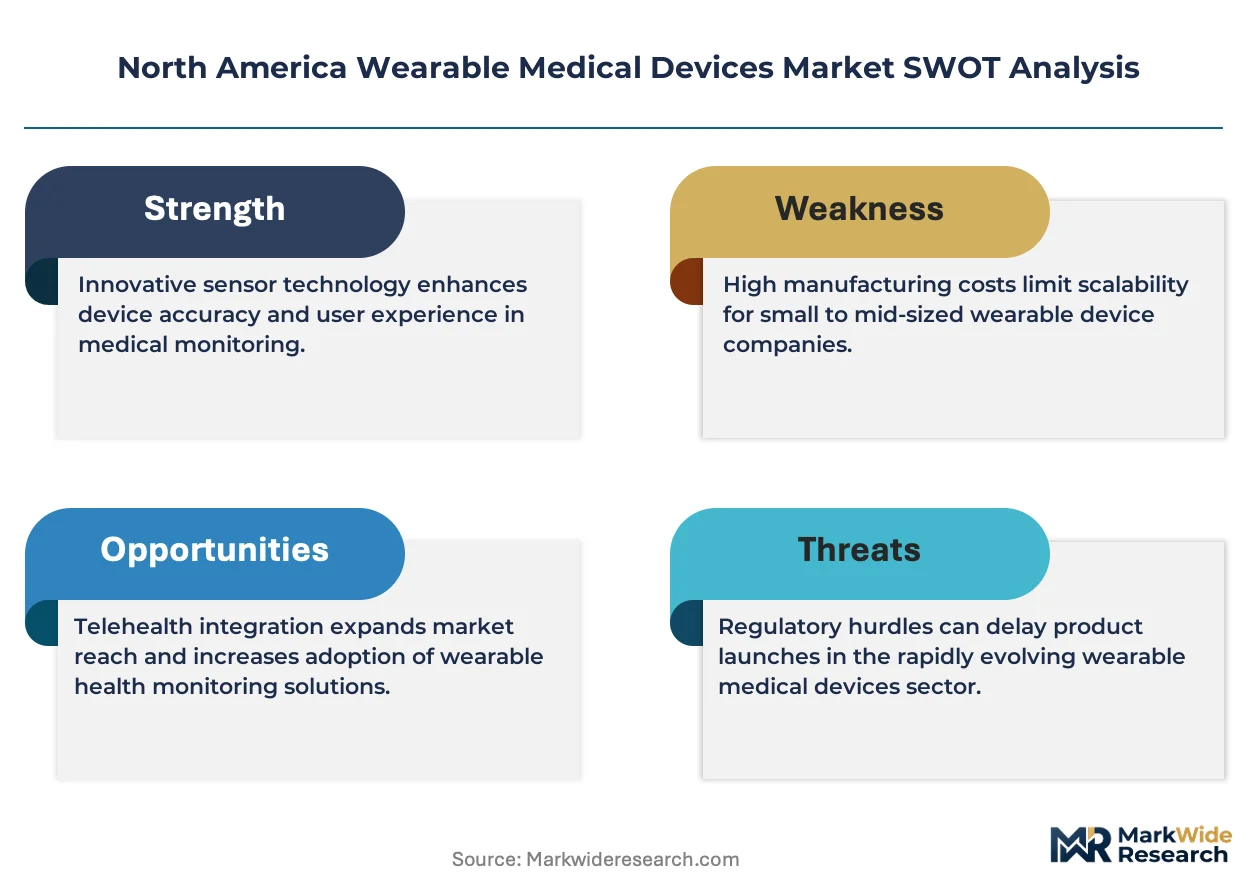
- Data Privacy Compliance:The strict requirements of HIPAA in the United States impose significant compliance costs and operational complexities on handling protected health information, acting as a barrier for new entrants.
- Clinical Validation Costs:The substantial financial investment and time required for clinical trials to achieve FDA clearance for a medical-grade device limits the number of products that can enter the clinical market.
- Market Definition Ambiguity:Persistent consumer and provider confusion between unregulated consumer wellness gadgets and clinically validated medical devices dilutes the value proposition of high-accuracy instruments.
Strategic Opportunities
- Expansion into New Therapeutic Areas:Significant opportunity exists to apply clinically validated wearable technology beyond diabetes and cardiac care into areas like chronic obstructive pulmonary disease (COPD), sleep apnea, and neurological disorders.
- AI-Powered Predictive Analytics:Integrating artificial intelligence and machine learning algorithms with continuous sensor data allows for the development of predictive platforms that can forecast adverse health events before they occur.
- Canadian Market Penetration:While the US market is advanced, there is considerable room for growth in Canada, where healthcare system adoption of clinical-grade wearables for chronic care is less mature.
Industry Challenges
- Software as a Medical Device (SaMD) Compliance:Navigating the FDA's evolving and increasingly stringent regulatory framework for SaMD creates a significant and continuous compliance burden, especially for software-focused innovators.
- EHR System Integration:A primary operational hurdle is the technical difficulty and cost associated with integrating data streams from diverse wearable devices into legacy Electronic Health Record (EHR) systems used by hospitals.
- Intellectual Property Complexity:The convergence of hardware, software, and data analytics leads to complex intellectual property disputes surrounding biosensor designs, data transmission protocols, and proprietary health algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wearable Medical Devices Market |
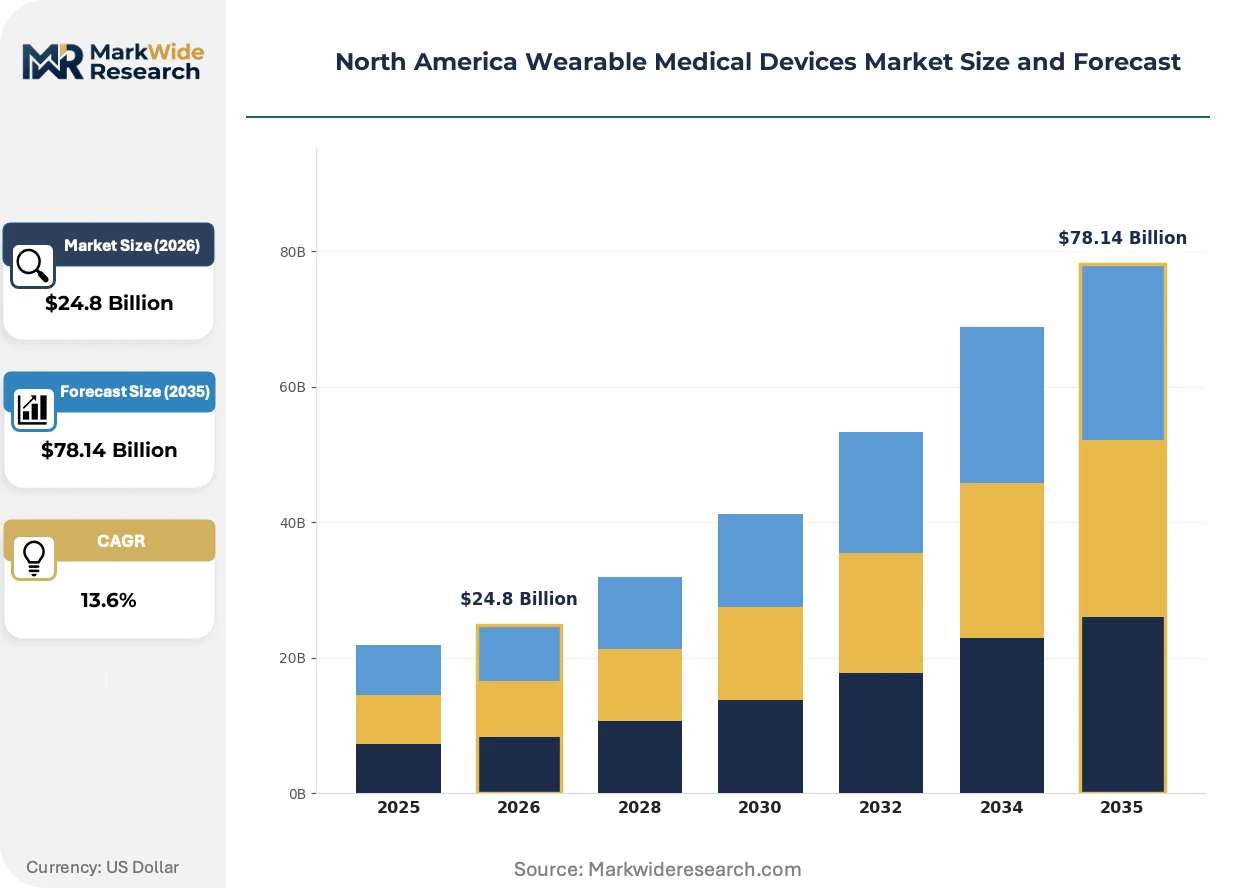
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $78.14 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartwatches, Fitness Trackers, Biosensors, Smart Clothing Technology: Bluetooth, NFC, Wi-Fi, RFID Application: Cardiac Monitoring, Diabetes Management, Sleep Tracking, Fitness Assessment End User: Healthcare Providers, Patients, Fitness Enthusiasts, Corporate Wellness Programs |
| Companies Covered | Apple Inc., Fitbit, Inc., Abbott Laboratories, Dexcom, Inc., Garmin Ltd., Samsung Electronics Co., Ltd., Masimo Corporation, BioTelemetry, Inc., ResMed Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wearable Medical Devices Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift from passive data collection toward the delivery of predictive, actionable health insights. This transformation is driven by advancements in sensor fusion, sophisticated software algorithms, and new service models aligned with healthcare system objectives in North America.
Continuous multi-parameter biosensors, which integrate monitoring for metrics like glucose, lactate, and electrolytes into a single patch, are a key innovation. Clinical research organizations and specialized hospital departments are adopting this technology for complex patient monitoring. This integrated data stream is rewriting chronic disease management protocols by providing a holistic, real-time physiological profile rather than siloed data points.
The FDA's regulatory approach to Software as a Medical Device (SaMD) is creating a new compliance paradigm. This framework prioritizes a manufacturer's internal quality processes and post-market data collection over a single pre-market hardware review. Software-centric innovators and new market entrants are most affected, as they must build capabilities for continuous monitoring and lifecycle management to secure and maintain market access.
A distinct behavioral shift is occurring as large US hospital systems move from one-time device purchases to subscription-based remote patient monitoring services. This transition away from a capital expenditure model disrupts the traditional sales cycle for device manufacturers. The trend is most prominent within accountable care organizations (ACOs) focused on managing high-risk patient populations to control costs and improve clinical outcomes.
North America Wearable Medical Devices Market Segmentation
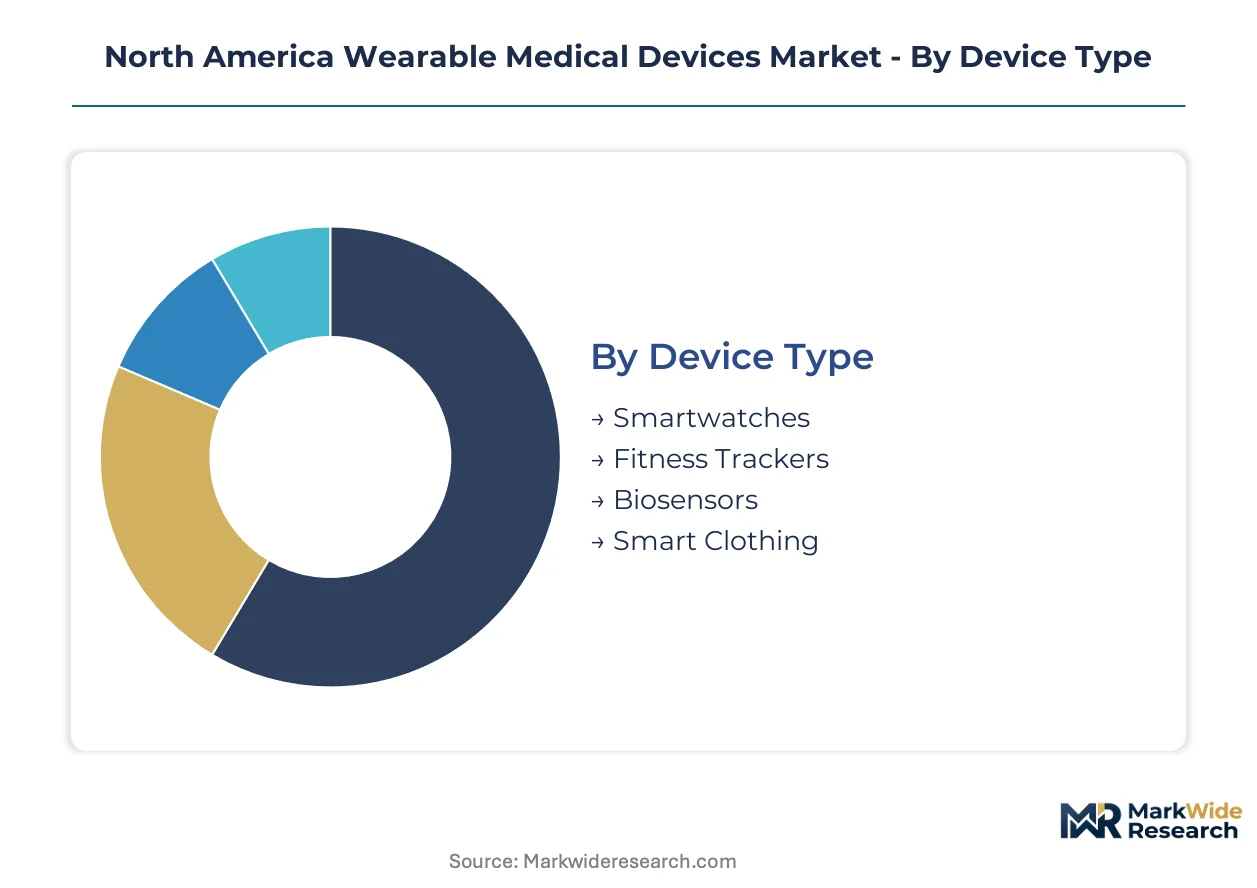
The North America wearable medical devices market exhibits distinct segments driven by diverse technological capabilities and end-user needs. Understanding these classifications provides clarity on where innovation is concentrated and how different device types serve specific clinical and wellness objectives. This granular view highlights key areas for investment and strategic development within the region.
Device Type:
The device type category spans a spectrum from highly standardized consumer electronics to specialized, clinically validated instruments requiring significant customization for specific health conditions. This differentiation influences regulatory pathways and market entry strategies for manufacturers.
- Biosensors:These devices continuously measure specific physiological parameters, such as glucose levels or cardiac activity, often directly on the skin. Demand concentrates within integrated hospital systems in the United States, driven by the need for precise, real-time data for chronic disease management.
- Smartwatches:Multifunctional wrist-worn devices offer a range of health monitoring features, including heart rate tracking and activity levels, integrated into a consumer electronics ecosystem. Demand remains high among general consumers across North America, seeking convenient wellness and basic health insights.
- Fitness Trackers:These dedicated devices primarily monitor physical activity, steps, calories burned, and basic sleep patterns.
- Smart Clothing:Garments embedded with sensors collect physiological data, offering discreet and comfortable monitoring solutions.
Most installed capacity flows through Smartwatches. Expansion is steepest in Biosensors.
Technology:
The underlying communication technologies determine how wearable medical devices transmit collected physiological data, impacting range, power consumption, and data transfer rates for various applications. Different technologies cater to distinct operational requirements and user environments.
- Bluetooth:This short-range wireless technology enables low-power data transmission between a wearable device and a nearby smartphone or hub. Widespread adoption in consumer and clinical devices across North America stems from its energy efficiency and ubiquitous smartphone integration.
- Wi-Fi:Providing higher bandwidth and longer range, Wi-Fi connects devices directly to local networks or the internet, facilitating real-time data uploads. Its use is growing in clinical settings within large hospital networks, supporting continuous, high-volume data streams for remote patient monitoring.
- NFC:Near Field Communication allows for very short-range, secure data exchange, primarily used for quick pairing or contactless payments in some devices.
- RFID:Radio-Frequency Identification tags are passive sensors used for identification and tracking, finding niche applications in inventory management of medical wearables.
Bluetooth technology currently underpins the majority of wearable medical device connections. Wi-Fi is climbing the fastest in terms of new clinical deployments.
Application:
The application segment delineates the primary health conditions or wellness goals that wearable medical devices are designed to address, ranging from critical disease management to general health maintenance. Each application demands specific sensor accuracy and data interpretation capabilities.
- Cardiac Monitoring:These applications involve continuous tracking of heart rate, ECG, and other cardiovascular metrics to detect arrhythmias or track post-surgical recovery. Demand within US hospital systems is significant for remote observation of patients with chronic heart conditions, aiming to prevent acute events.
- Diabetes Management:Devices in this category, primarily continuous glucose monitors, provide real-time blood sugar readings to assist patients and clinicians in managing diabetes. Adoption is robust among diabetes patients throughout North America, driven by improved glycemic control and reduced hypoglycemia incidents.
- Sleep Tracking:These applications monitor sleep patterns, duration, and quality, often identifying potential sleep disorders like apnea.
- Fitness Assessment:Focused on exercise performance, calorie expenditure, and activity levels, these applications cater to individuals pursuing physical wellness goals.
Fitness Assessment represents the largest volume of consumer-facing wearable applications. Cardiac Monitoring is gaining share fastest in clinical adoption.
End User:
The end-user segment distinguishes between the primary beneficiaries and purchasers of wearable medical devices, influencing product design, distribution channels, and pricing strategies. Different end-users prioritize varying levels of clinical accuracy, ease of use, and integration capabilities.
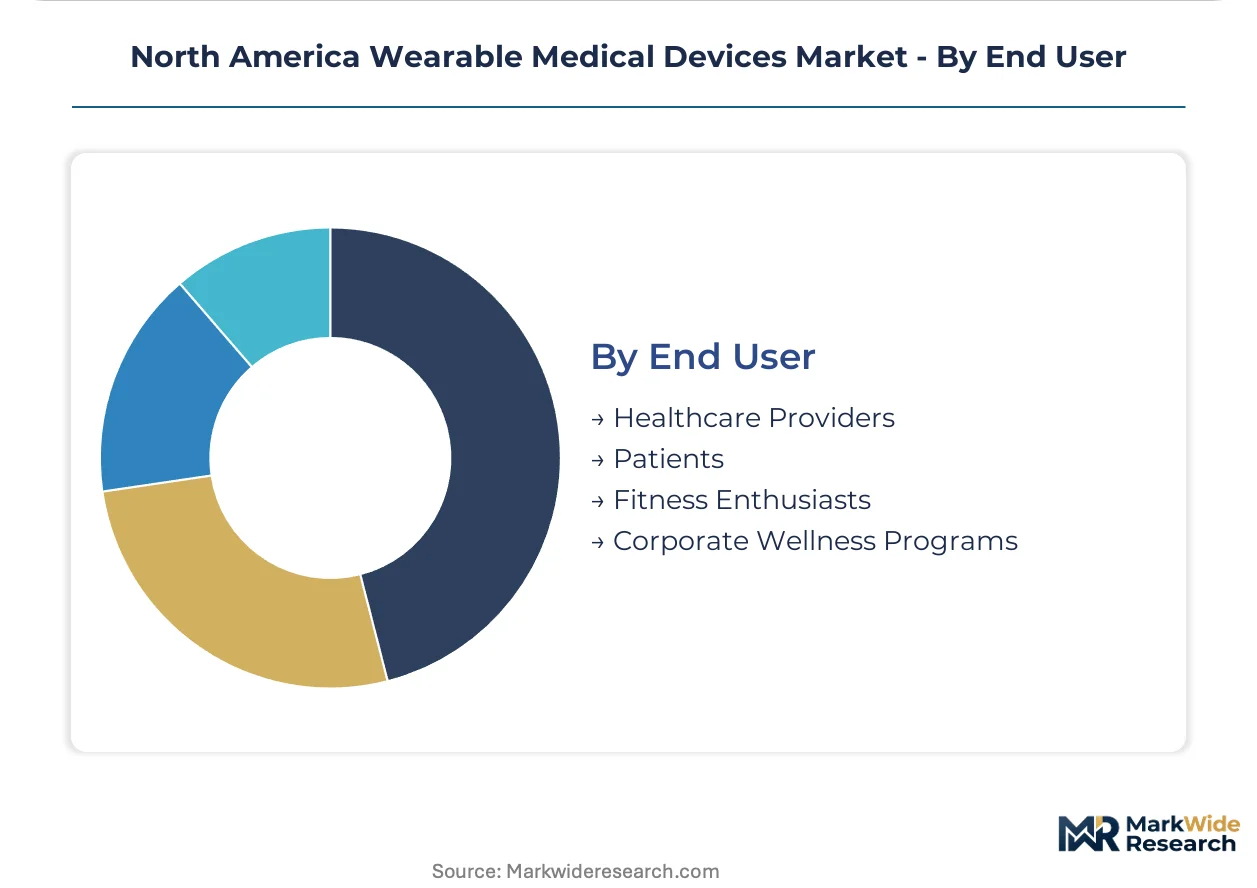
- Healthcare Providers:Hospitals, clinics, and physician groups utilize wearable devices for remote patient monitoring, diagnostics, and chronic disease management. Their procurement decisions in the United States are heavily influenced by clinical efficacy, EHR integration, and potential for cost reduction in long-term care.
- Patients:Individuals directly purchase and use wearable devices for personal health monitoring, condition management, or general wellness. Patient adoption across North America is driven by convenience, perceived health benefits, and increasing awareness of self-management tools for conditions like diabetes.
- Fitness Enthusiasts:This group primarily uses wearables to track exercise performance, activity levels, and basic physiological data for personal fitness goals.
- Corporate Wellness Programs:Employers deploy wearables to promote employee health, track activity, and potentially reduce healthcare costs through preventative initiatives.
Patients represent the largest end-user group by volume. Healthcare Providers exhibit the steepest growth trajectory in terms of clinical-grade device procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American region benefits from a highly skilled technology workforce and extensive research institutions, anchoring innovation in wearable medical devices. This talent pool drives advancements in biosensor development and data analytics for healthcare applications. Demand for these devices is concentrated in specific areas with advanced healthcare infrastructure.
United States
Integrated hospital systems in the United States drive demand for clinical-grade wearables, particularly for managing chronic conditions. The FDA's Digital Health Center of Excellence streamlines regulatory pathways for novel digital health technologies. Boston's vibrant MedTech hub fosters startups specializing in advanced biosensor development.
Canada
Canadian healthcare systems increasingly adopt clinical-grade wearables for chronic care management, aiming to improve patient outcomes. Health Canada oversees device classification and market approval, ensuring safety and efficacy. Toronto's MaRS Discovery District serves as a focal point for digital health innovation.
Mexico
Mexico's expanding healthcare infrastructure and rising prevalence of chronic diseases generate demand for accessible patient monitoring solutions. The country's national health regulator establishes clear guidelines for medical device development. Guadalajara's burgeoning tech ecosystem is becoming a key center for manufacturing and software development.
California
California's strong culture of technological innovation and abundant venture capital fuels development and early adoption of advanced wearable medical devices. Strict HIPAA regulations govern protected health information, influencing device design and data management. Silicon Valley remains an epicenter for health tech startups, driving breakthroughs in AI-powered diagnostics.
Northeast Corridor
The Northeast Corridor, with its concentration of academic medical centers and integrated hospital networks, exhibits strong demand for sophisticated remote patient monitoring tools. State-level data privacy initiatives complement federal regulations, influencing connected health device deployment. Philadelphia's growing bio-innovation cluster fosters collaboration between research institutions and device manufacturers.
North America Wearable Medical Devices Market Key Industry Players
The competitive structure tilts toward a blend of established medical device manufacturers and rapidly innovating consumer electronics giants. This market features specialized biosensor developers focusing on clinical accuracy alongside broad consumer brands integrating health features. Strategic archetypes include large technology conglomerates, dedicated MedTech innovators, and nimble software-as-a-medical-device (SaMD) startups. Companies are increasingly engaging in portfolio diversification and forming strategic partnerships to integrate data platforms.
Within the consumer electronics and health integration tier, Apple Inc. exemplifies the strategy of leveraging a vast ecosystem to embed health monitoring features into widely adopted products. Dexcom, Inc. represents a specialized medical device manufacturer, occupying a strong position in continuous glucose monitoring technology for diabetes patients. Abbott Laboratories sits within the established MedTech innovator archetype, anchoring its presence across multiple therapeutic areas with a portfolio of clinically validated wearable biosensors for cardiac and metabolic conditions.
| Leading Market Players |
|---|
| Apple Inc. |
| Fitbit, Inc. |
| Abbott Laboratories |
| Dexcom, Inc. |
| Garmin Ltd. |
| Samsung Electronics Co., Ltd. |
| Masimo Corporation |
| BioTelemetry, Inc. |
| ResMed Inc. |
| Others |
Cost & Logistics Intelligence
Vertical integration by large technology conglomerates and specialized MedTech innovators anchors both the supply position for critical components and the pricing power for advanced wearable medical devices. This integration ensures a controlled supply of biosensors and software, influencing market entry costs and the value proposition for clinically validated solutions across North America.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing for wearable medical devices, with subscription-based remote patient monitoring gaining traction among healthcare providers. Price differentiation stems from FDA clearance for clinical use and advanced data integration capabilities with Electronic Health Record (EHR) systems. Pricing softness reflects intense competition in the consumer wellness gadget segment. Patients purchasing basic fitness trackers exhibit the highest price sensitivity, while hospital systems prioritize clinical efficacy over cost for critical care applications.
Supply Chain Analysis
Domestic-content mandates for medical devices, particularly within government procurement, are subtly reshaping sourcing strategies for critical components. Geographic supply concentration for high-value biosensors and microcontrollers remains centered in the United States and East Asia, with assembly operations increasingly in Mexico. Raw material dependencies include medical-grade polymers, specialized sensor materials, and low-power communication modules. Single-source vulnerability for unique biosensor technologies presents a structural supply chain risk. Distribution runs through direct sales channels to healthcare providers and established consumer retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the shift towards high-value, clinically validated devices and subscription-based remote patient monitoring services. This premium-tier shift allows for higher revenue per patient and improved profitability.
For Market Incumbents:Hedge against the threat of software-centric innovators by strategically acquiring promising SaMD startups with novel algorithms or unique data analytics capabilities. Invest heavily in EHR integration platforms to solidify data flow and demonstrate clear return on investment for hospital systems. Focus R&D on multi-parameter biosensors and AI-powered predictive analytics to maintain a technological lead against emerging entrants.
For New Entrants and Emerging Players:Begin with a clear focus on underpenetrated therapeutic areas beyond diabetes and cardiac care, such as chronic obstructive pulmonary disease (COPD) or neurological disorders. Target the Canadian market, where clinical adoption of wearables is less mature, offering a significant white-space opportunity. Leverage a go-to-market strategy centered on demonstrating clinical efficacy through pilot programs with smaller hospital networks or specialized clinics to build credibility.
For Investors and Strategic Acquirers:Roll-up economics work for specialized MedTech innovators because structural fragmentation exists among software-as-a-medical-device (SaMD) startups. Long-term viability remains strong for companies offering clinically validated, integrated solutions that align with value-based care models. Identify acquisition target archetypes that possess proprietary biosensor technology or advanced AI platforms with existing FDA clearance. The signal to watch is increased reimbursement codes for remote patient monitoring services, indicating broader adoption and financial support.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-Powered Predictive Analytics | Enhances diagnostic capabilities and enables proactive patient interventions, improving clinical outcomes. |
| Secure FDA/Health Canada Clearance | Establishes clinical credibility and unlocks access to healthcare provider procurement channels. |
| Develop EHR Integration Solutions | Streamlines data flow into existing hospital systems, boosting operational efficiency for providers. |
| Expand into New Therapeutic Areas | Diversifies revenue streams and addresses unmet medical needs beyond current applications. |
| Form Hospital System Partnerships | Accelerates adoption of remote patient monitoring programs and validates device utility in clinical settings. |
Research Approach
Coverage spans North America, including the United States, Canada, and Mexico, with primary inputs from each region. The analytical approach combines extensive primary interviews with industry stakeholders and rigorous secondary validation. Interviewed roles include clinicians, hospital purchasing committee members, biomedical engineers, and regulatory affairs specialists. Secondary data sources encompass FDA filings, Health Canada documents, industry association reports, and healthcare provider financial statements, triangulated with bottom-up and top-down analyses.
Granularity was modeled across device type, technology, application, end-user, and regional regulatory clusters over the projection horizon. The quantitative model integrates historical trends with projected market dynamics to derive Compound Annual Growth Rates (CAGRs). Key industry-specific forecast inputs include the adoption rates of remote patient monitoring programs and the timelines for new regulatory approvals for novel devices.
Several conditions sit outside the modeled scope, including specific company-level financial performance and the impact of unregulated consumer wellness gadgets. Forecasts reflect assumptions regarding technological evolution and the stability of data privacy regulations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Surgical Polypropylene Mesh Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market
Medical Devices
Medical Connector Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Versatile Cryosurgical Devices Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market
Medical Devices
IoT Medical Devices Market
Medical Devices
Cervical Spacer Systems Market
Medical Devices
Low Vision Aids Market
Medical Devices
Incubator Devices Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Global Keratometers Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Prescription Goggles Market
Medical Devices
Digital Orthodontics Market
Medical Devices
Global Biopsy Punch Market