
 Fetal Heart Rate Monitoring Devices Market | 2026-2036
Fetal Heart Rate Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Fetal Heart Rate Monitoring Devices Market Analysis
ISO 13485 certification is rotating as the decisive qualification gate for manufacturers seeking entry into institutional procurement channels. GE Healthcare leverages its installed base of maternal-fetal medicine platforms to sustain service revenue streams across North American hospital networks. Koninklijke Philips N.V. anchors its position through integrated informatics that connect bedside monitors to electronic health record systems. Siemens Healthineers competes on imaging lineage, extending its cardiology expertise into fetal assessment workflows.
Fetal heart rate monitoring devices are electronic systems that detect, amplify, and display the fetal cardiac signal, typically operating via Doppler ultrasound at 1-2 MHz or through direct fetal electrocardiography with signal processing algorithms to isolate the fetal heart rate from maternal and ambient noise; their primary purpose is to enable clinicians to assess fetal well-being during pregnancy, labor, and delivery through continuous or intermittent surveillance of heart rate patterns and variability. Ultrasound Systems dominate capital expenditure budgets in hospital obstetric departments, while Wireless Monitors represent the fastest-expanding device category as facilities prioritize maternal mobility during labor. The End User dimension shows Hospitals capturing the largest volume commitment, though Home Care is gaining traction among health systems implementing remote patient monitoring programs for high-risk pregnancies.
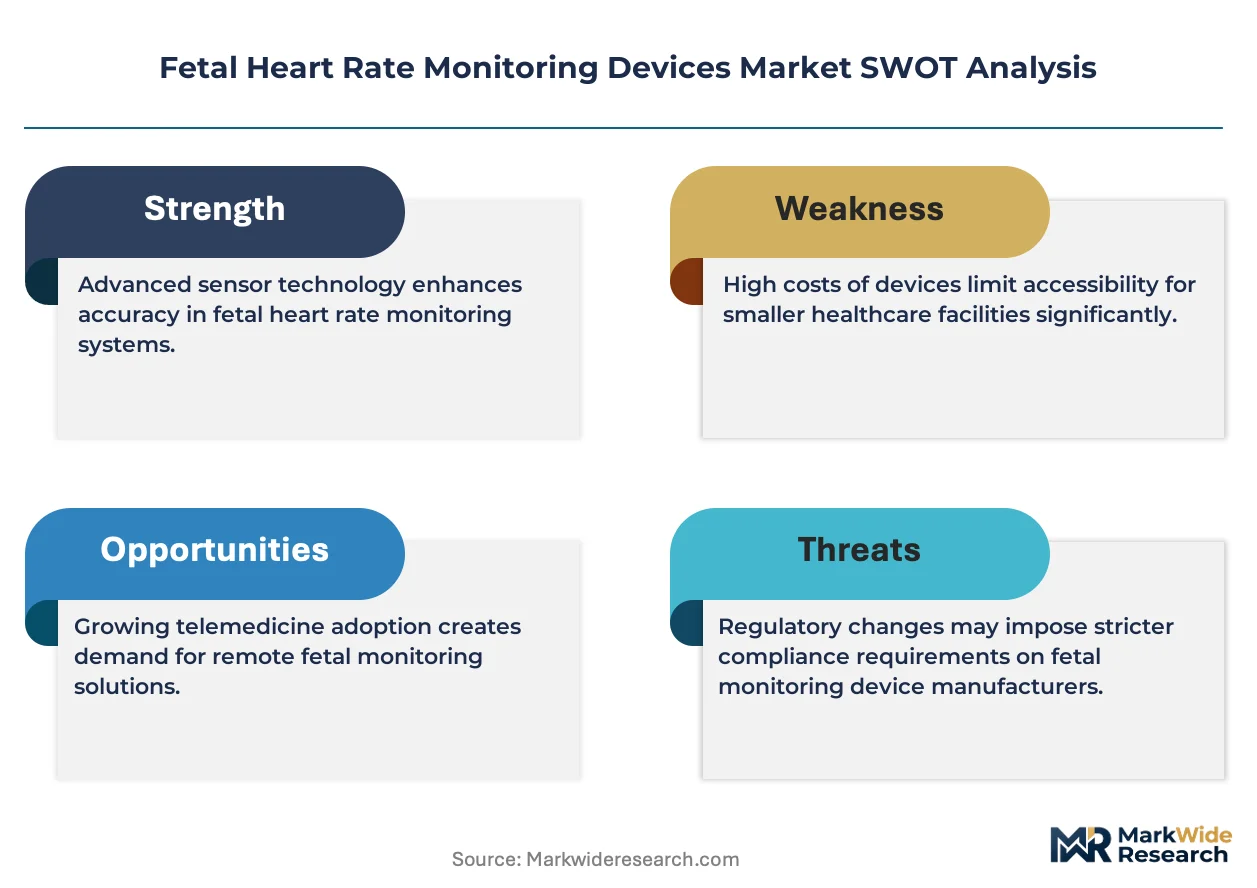
The FDA governs device safety and effectiveness through 510(k) clearance pathways for fetal monitors, while the International Electrotechnical Commission sets electrical safety and electromagnetic compatibility standards under IEC 60601-2-43 specific to fetal monitoring equipment; these frameworks elevate compliance costs for new entrants but also create structured procurement criteria that favor established manufacturers with regulatory infrastructure. Stakeholders must weigh the pace of wireless telemetry adoption against reimbursement uncertainties for remote monitoring services.
Market Dynamics
Hospital maternity wards are rotating their capital allocation toward wireless telemetry systems that enable ambulatory labor monitoring, compressing replacement cycles for legacy wired bedside units and redrawing procurement criteria around interoperability with electronic health record platforms.
Growth Catalysts
- Perinatal safety mandates:United States hospital systems face institutional pressure from Joint Commission accreditation standards to maintain continuous fetal surveillance capabilities, accelerating equipment refresh schedules.
- Remote patient monitoring reimbursement:CMS billing codes for maternal-fetal telehealth services create financial viability for home-based wireless monitor deployment among high-risk pregnancy populations.
- Doppler ultrasound miniaturization:Advances in low-power 1-2 MHz transducer design enable wearable form factors that expand addressable use cases beyond traditional obstetric department settings.
Market Restraints
- 510(k) clearance timelines:FDA premarket notification requirements for obstetric devices extend product development cycles by 12-18 months, elevating capital requirements for new entrants.
- Electromagnetic compatibility certification:IEC 60601-2-43 compliance testing costs disproportionately burden smaller manufacturers seeking institutional procurement eligibility.
- Disposable electrode supply concentration:Single-use fetal scalp electrode production concentrates among limited specialty contract manufacturers, creating input vulnerability.
Strategic Opportunities
- Home care channel expansion:Health system remote monitoring programs for gestational hypertension and diabetes comorbidities create demand for consumer-accessible fetal monitor interfaces.
- AI-assisted signal interpretation:Machine learning pattern recognition for fetal heart rate variability analysis converges with cloud-based telemetry to enable predictive alerting workflows.
- European MDR harmonization:Medical Device Regulation technical documentation standardization reduces fragmentation across Germany, France, and Netherlands national approval pathways.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in fetal electrocardiography signal processing algorithms remains concentrated among legacy device manufacturers, constraining R&D team scaling.
- Legacy system integration friction:Hospital information technology departments face technical debt from proprietary data formats in installed-base monitors, complicating interoperability upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fetal Heart Rate Monitoring Devices Market |
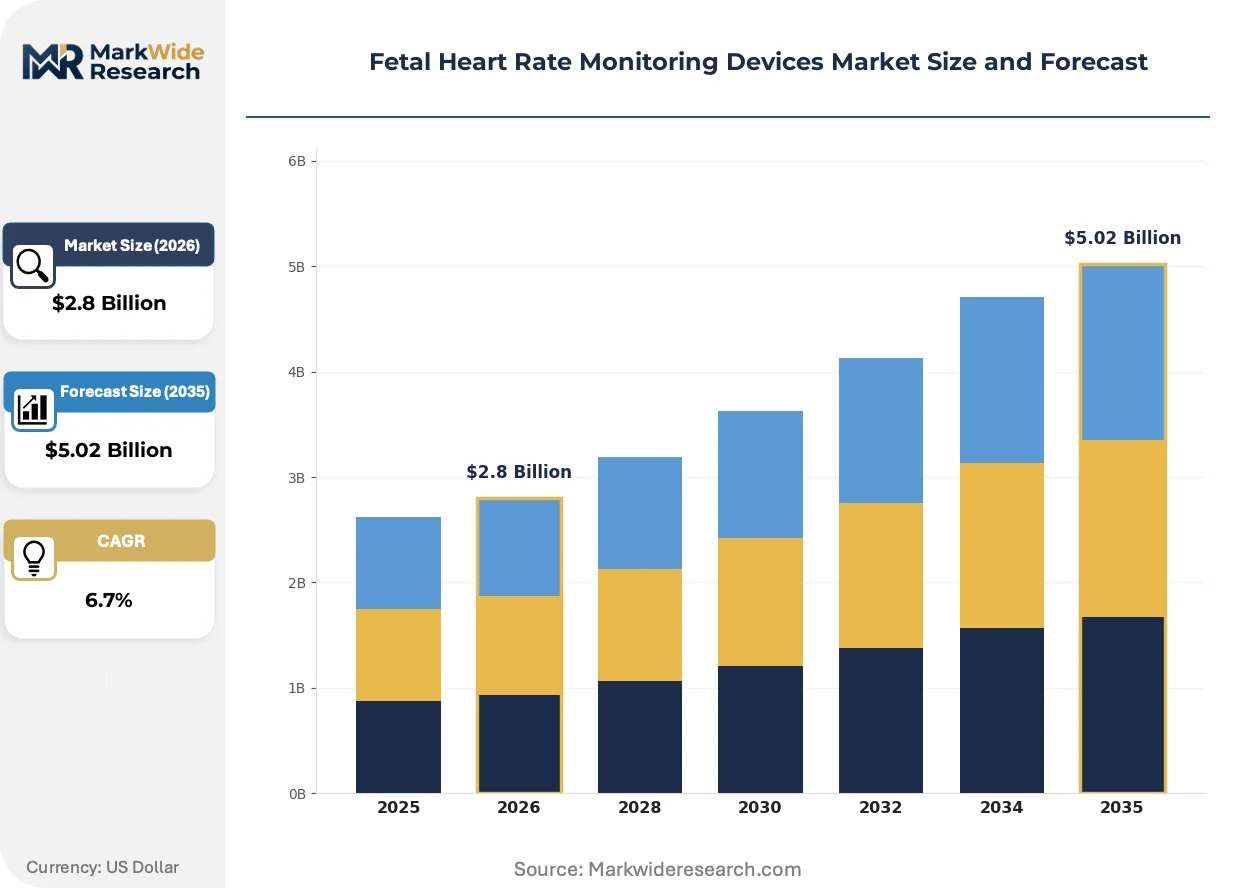
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Doppler Devices, EKG Monitors, Ultrasound Systems, Wireless Monitors End User: Hospitals, Clinics, Home Care, Diagnostic Centers Technology: Digital, Analog, Wireless, Telemetry Application: Routine Checkup, High-risk Monitoring, Labor Monitoring, Outpatient Care |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., MedGyn Products Inc., Cooper Companies Inc., Fujifilm Holdings Corporation, EDAN Instruments Inc., Mindray Medical, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fetal Heart Rate Monitoring Devices Market Emerging Trajectories
Wireless telemetry architectures are compressing the traditional boundary between acute care and ambulatory monitoring, forcing hardware manufacturers to reorient product roadmaps around software-defined functionality and cloud connectivity rather than standalone device sales.
Artificial intelligence-enhanced signal processing is bifurcating the competitive landscape between algorithm-native entrants and established manufacturers retrofitting pattern-recognition capabilities onto legacy hardware platforms. Venture-backed digital health firms are securing 510(k) clearances for cloud-based fetal heart rate interpretation tools at pace. This technology is bifurcating service delivery models, enabling remote obstetrician oversight of labor progression without continuous bedside presence.
The European Union's Medical Device Regulation (MDR) is elevating clinical evidence requirements for fetal monitoring equipment, compelling manufacturers to expand post-market surveillance infrastructure. Class IIa device reclassification under MDR Annex VIII imposes stricter conformity assessment procedures than predecessor directives. Wireless monitor vendors targeting Germany, France, and Netherlands markets are responding by consolidating notified body relationships and expanding clinical study commitments.
Hospital procurement committees are unbundling hardware acquisition from multi-year service contracts, compressing vendor switching costs and elevating price transparency. Group purchasing organizations are aggregating demand across health system networks, displacing individual hospital negotiations. This behavioral shift is most visible in United States integrated delivery networks, where standardization across multiple birth centers creates volume leverage for tender processes.
Fetal Heart Rate Monitoring Devices Market Segmentation
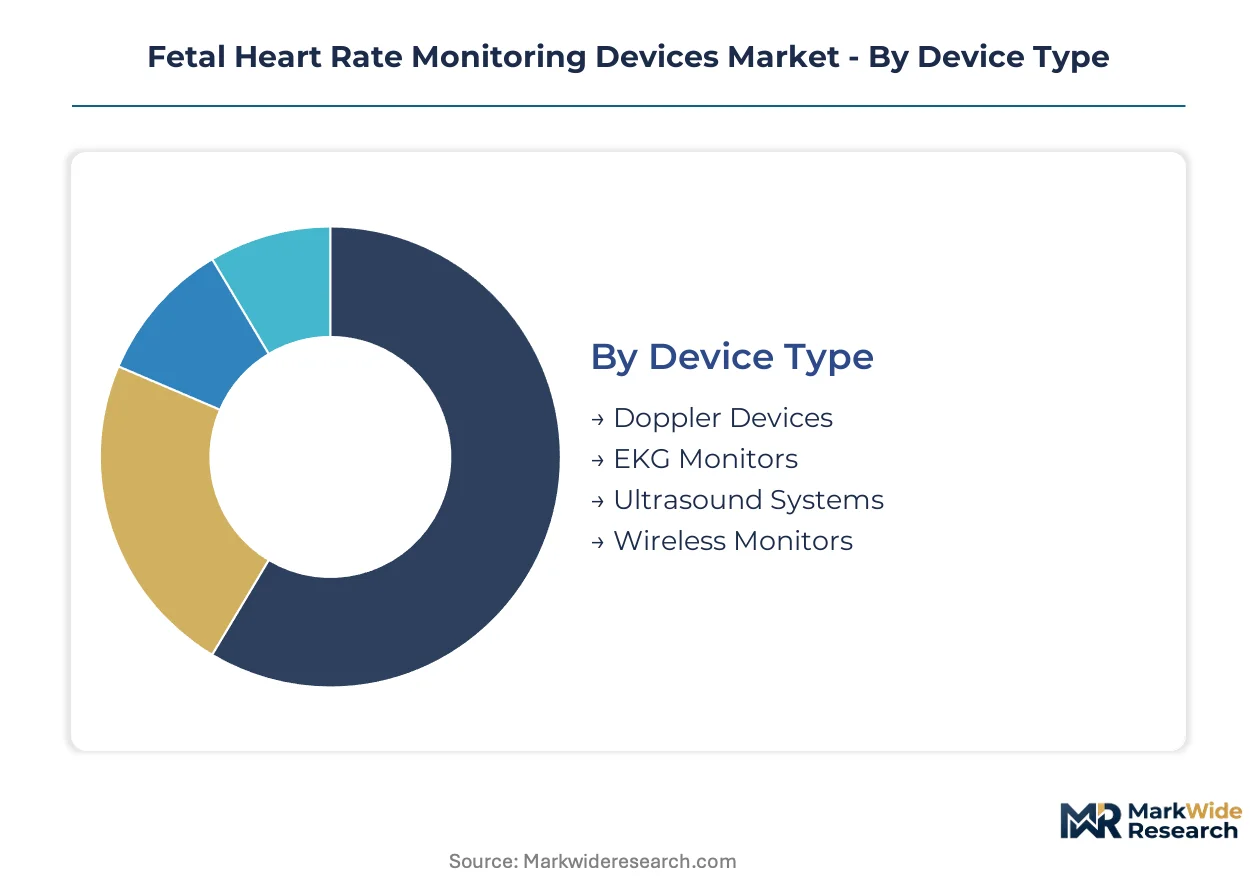
Device heterogeneity in fetal monitoring creates distinct procurement pathways, with capital-intensive systems flowing through hospital tender processes while portable units penetrate retail and direct-to-consumer channels. Understanding segment-channel alignment enables manufacturers to optimize distribution investment and service model design.
Device Type:
Channel mix varies sharply by device category, with wired bedside systems sold through capital equipment distributors and wireless monitors increasingly deployed via remote patient monitoring platform contracts.
- Ultrasound Systems:These capital-intensive imaging platforms integrate 1-2 MHz Doppler transducers with real-time display architecture for obstetric departments. United States hospital networks concentrate demand here, driven by Joint Commission accreditation requirements for continuous surveillance capabilities in maternity wards.
- Wireless Monitors:Telemetry-enabled wearable form factors transmit fetal cardiac signals to cloud-based dashboards, enabling ambulatory labor monitoring. Health system remote patient monitoring programs for high-risk pregnancies are where expansion concentrates fastest, supported by CMS reimbursement codes for maternal-fetal telehealth services.
- Doppler Devices:Handheld ultrasound units for intermittent auscultation serve clinic and home care channels with lower capital barriers.
- EKG Monitors:Direct fetal electrocardiography systems with scalp electrode interfaces remain concentrated in labor and delivery suites for high-acuity cases.
Ultrasound Systems dominate installed base. Wireless Monitors is where expansion concentrates.
End User:
Cost tier stratification separates institutional purchasers with multi-year service contracts from consumer-accessible segments where price sensitivity and ease-of-use dominate selection criteria.
- Hospitals:Acute care maternity wards drive volume commitment through centralized procurement committees, prioritizing interoperability with electronic health record systems and ISO 13485-certified manufacturer qualification. Group purchasing organizations aggregate demand across United States integrated delivery networks, compressing vendor switching costs.
- Home Care:Direct-to-patient distribution channels for high-risk pregnancy populations leverage cellular-connected monitors with simplified interfaces. Gestational hypertension and diabetes comorbidity management programs are where demand is concentrating, as health systems extend surveillance beyond facility walls.
- Clinics:Outpatient obstetric practices prioritize portable Doppler units for routine prenatal visits.
- Diagnostic Centers:Specialized fetal medicine facilities concentrate advanced ultrasound and echocardiography capabilities for complex case referral.
Hospitals dominate installed base. Home Care is where expansion concentrates.
Technology:
Application context determines technology selection, with digital signal processing required for AI-assisted interpretation workflows while analog architectures persist in cost-constrained settings.
- Digital:Microprocessor-based systems with algorithmic noise filtration enable machine learning pattern recognition for fetal heart rate variability analysis. Cloud-based telemetry integration is where demand concentrates, converging with predictive alerting workflows for remote obstetrician oversight.
- Wireless:Low-power radio frequency and cellular transmission protocols support ambulatory monitoring use cases. Maternal mobility prioritization during labor is driving replacement of wired bedside architectures in United States hospital maternity wards.
- Analog:Legacy amplifier-based systems persist in resource-limited settings with minimal maintenance infrastructure.
- Telemetry:Dedicated hospital network transmission systems enable centralized nursing station surveillance across multiple labor rooms.
Digital dominates installed base. Wireless is where expansion concentrates.
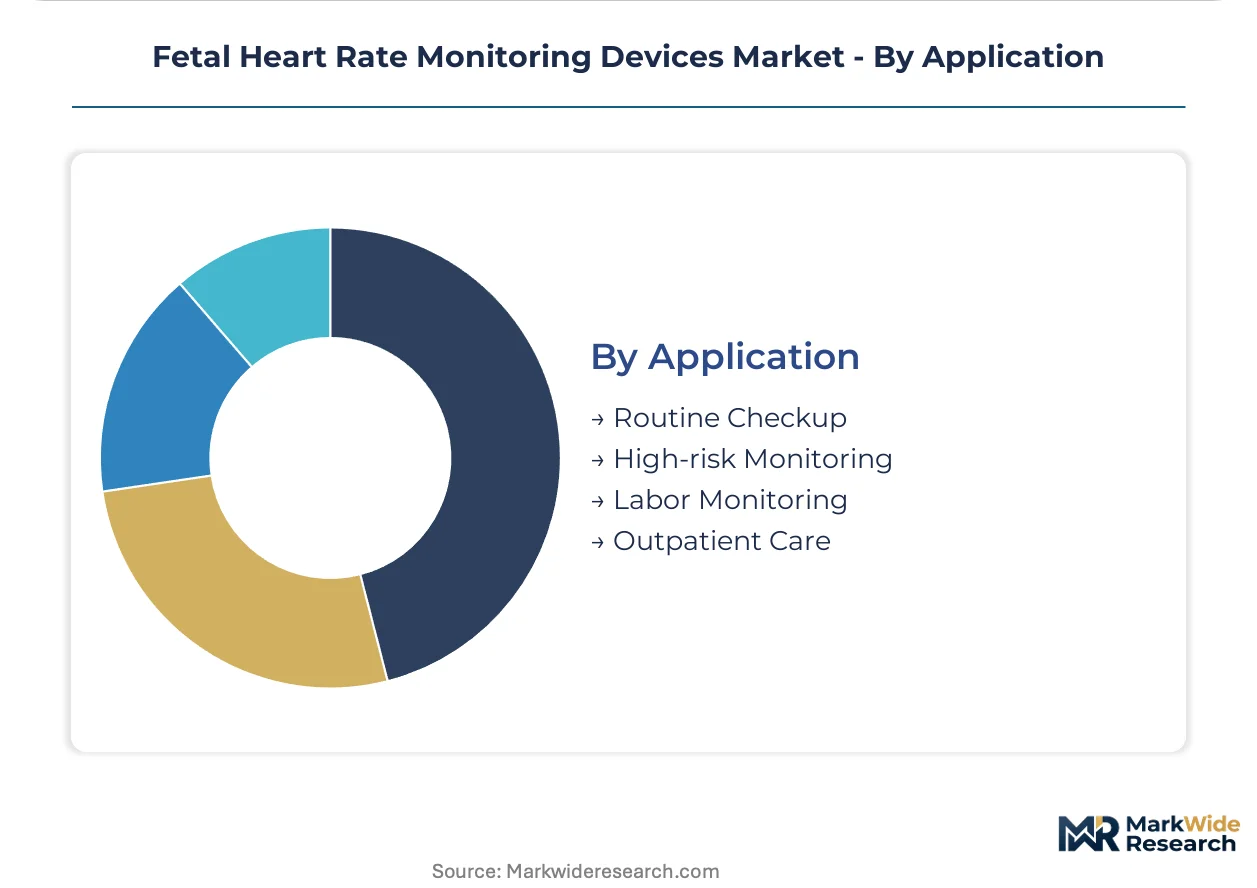
Application:
Volume-mix analysis reveals routine screening as the frequency anchor while high-acuity monitoring commands premium pricing and specialized device configurations.
- Labor Monitoring:Continuous surveillance during active labor requires bedside or wireless telemetry systems with real-time alerting for fetal distress patterns. United States perinatal safety mandates are where demand concentrates, accelerating equipment refresh schedules for legacy wired units.
- High-risk Monitoring:Surveillance of pregnancies complicated by maternal diabetes, hypertension, or fetal growth restriction demands intensive monitoring protocols. Remote patient monitoring program eligibility is driving home-based wireless deployment for this population.
- Routine Checkup:Intermittent Doppler assessment during scheduled prenatal visits represents the highest-frequency touchpoint.
- Outpatient Care:Non-hospital ambulatory settings concentrate surveillance for stable pregnancies with scheduled monitoring protocols.
Labor Monitoring dominates installed base. High-risk Monitoring is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States concentrate the largest capital commitments for continuous fetal surveillance systems. Group purchasing organizations aggregate tender volumes across integrated delivery networks. Wireless telemetry adoption accelerates equipment refresh cycles in maternity wards worldwide.
United States
Joint Commission perinatal safety mandates drive replacement schedules for legacy wired bedside monitors in hospital maternity wards. FDA 510(k) clearance pathways shape product development timelines for obstetric device manufacturers. The Boston-Cambridge corridor concentrates digital health venture activity around AI-assisted fetal signal interpretation tools.
Germany
University hospital networks prioritize interoperability with electronic health record systems in fetal monitor procurement criteria. EU Medical Device Regulation technical documentation requirements elevate post-market surveillance commitments for manufacturers. The Rhine-Ruhr metropolitan region anchors distribution infrastructure serving Central European obstetric departments.
China
Provincial maternal health initiatives expand ultrasound system deployment in county-level hospital obstetric departments. National Medical Products Administration standards govern electrical safety and electromagnetic compatibility for imported monitoring equipment. The Yangtze River Delta manufacturing cluster supplies transducer components and printed circuit assemblies to device assemblers.
Japan
Aging obstetrician workforce demographics accelerate remote monitoring program adoption for high-risk pregnancy surveillance. Ministry of Economy, Trade and Industry guidelines promote wireless medical device connectivity standards. The Osaka-Kobe industrial corridor hosts precision electronics fabricators serving fetal monitor original equipment manufacturers.
United Kingdom
National Health Service maternity transformation programs prioritize home-based monitoring for gestational hypertension and diabetes comorbidities. Medicines and Healthcare products Regulatory Agency conformity assessment procedures align with EU MDR technical documentation standards. London-based integrated care systems pilot remote patient monitoring platform contracts with wireless monitor vendors.
Fetal Heart Rate Monitoring Devices Market Vendor Landscape
Player mix skews toward diversified medical technology conglomerates with maternal-fetal medicine platform legacies. Consolidation around imaging and monitoring system portfolios characterizes the vendor landscape. Strategic archetypes include installed-base service revenue maximizers and algorithm-native digital health entrants. Competitive moves center on interoperability certification pursuits and cloud telemetry platform partnerships.
Within the conglomerate tier, GE Healthcare, Koninklijke Philips N.V., and Siemens Healthineers occupy positions anchored by hospital network relationships and regulatory infrastructure. These manufacturers exemplify the service-revenue maximizer archetype through multi-year maintenance contracts tied to electronic health record integration. EDAN Instruments Inc. represents the specialist fabricator segment with concentrated focus on obstetric monitoring equipment design.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| MedGyn Products Inc. |
| Cooper Companies Inc. |
| Fujifilm Holdings Corporation |
| EDAN Instruments Inc. |
| Mindray Medical |
| Cardinal Health |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for Doppler transducer assemblies concentrate procurement leverage among ISO 13485-certified contract manufacturers in the Yangtze River Delta, compressing margin capture for device assemblers while elevating pricing power for specialty component suppliers serving FDA-regulated obstetric equipment channels.
Pricing Analysis
Cost-plus contracts with quarterly electronics commodity indexation dominate hospital procurement agreements for capital-intensive ultrasound systems. Price differentiation rests on FDA 510(k) clearance tier and EHR interoperability certification, with premium tiers commanding service bundling premiums. Pricing pressure stems from GPO-aggregated tender volumes across United States integrated delivery networks. Home care channels exhibit highest price sensitivity due to direct-to-patient reimbursement gaps, while acute care hospitals prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Port congestion on the Shanghai-Los Angeles trade lane elevates inbound logistics costs for printed circuit assemblies and 1-2 MHz piezoelectric transducers. Manufacturing concentrates in China, Malaysia, and Mexico for final device assembly, with precision sensor fabrication anchored in Japan and Germany. Raw material dependencies include rare-earth elements for transducer ceramics, medical-grade silicones for wearable housings, and specialty alloys for scalp electrode conductors. Single-source vulnerability concentrates in disposable fetal scalp electrode production. Distribution runs through capital equipment distributors for hospital channels and direct-to-consumer platforms for home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device heterogeneity across wireless telemetry and traditional bedside systems fragments competitive space, creating niche entry points as health systems unbundle hardware from service contracts and prioritize ambulatory monitoring for high-risk pregnancy populations.
For Market Incumbents: Consolidate service revenue streams through multi-year EHR integration contracts that embed switching costs, while acquiring algorithm-native digital health firms to retrofit AI-assisted signal interpretation onto legacy hardware platforms. Defend against venture-backed entrants by accelerating FDA 510(k) clearance pipelines for cloud-based telemetry offerings. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks market entry for wireless monitors targeting gestational hypertension remote monitoring programs. White-space concentrates in home care channels for diabetes comorbidity management, where CMS reimbursement codes create financial viability. Go-to-market should prioritize health system RPM platform partnerships over direct hospital capital sales. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because maternal-fetal medicine platform synergies reward scale operators with installed-base service annuities. Acquisition targets should display ISO 13485 certification infrastructure and established notified body relationships for EU MDR compliance. The signal to watch is wireless telemetry reimbursement expansion beyond current maternal-fetal telehealth codes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Shortens product development cycles for wireless telemetry entrants competing against GE Healthcare and Philips installed bases. |
| Hospital System Partnership | Locks in multi-year service contracts through EHR interoperability commitments with Epic and Cerner networks. |
| Software Companion Development | Enables AI-assisted fetal heart rate variability analysis converging with cloud-based predictive alerting workflows. |
| Reimbursement Strategy | Secures CMS billing code expansion for home-based wireless monitoring of gestational hypertension populations. |
| CE Marking Pathway | Facilitates EU MDR compliance for wireless monitor vendors targeting Germany and Netherlands hospital networks. |
Methodological Framework
The analysis maps ultrasound systems, wireless monitors, Doppler devices, and EKG monitors, each validated through hospital procurement managers, biomedical engineers, GPO contracts specialists, and maternal-fetal medicine clinicians. Primary interviews with these stakeholders combined secondary validation from FDA 510(k) filings, CMS reimbursement code databases, hospital procurement records, and IEC 60601-2-43 certification registries. Bottom-up device shipment estimates triangulated against top-down health system capital expenditure surveys.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include device type, end user, technology architecture, and application context. CAGRs derived from equipment replacement cycle analysis, wireless telemetry adoption curves, and reimbursement policy trajectories. Forecast inputs incorporated Joint Commission accreditation mandate timelines and EU MDR reclassification implementation patterns.
Decision-makers should treat outputs as directional under stable regulatory reimbursement assumptions; material deviation in CMS telehealth policy or FDA clearance timelines would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Italy Patient Monitoring Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Asia Pacific Wireless Healthcare Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Telemonitoring Systems Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
B-Ketone Monitoring System Market
Patient Monitoring
Remote Home Monitoring Systems Market
Patient Monitoring
Holter Monitoring Systems Market