
 Global Veterinary Diagnostic Imaging Market | 2026-2036
Global Veterinary Diagnostic Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Diagnostic Imaging Market Foresight
Aftermarket service revenue is reconfiguring profit pools across the veterinary imaging value chain. IDEXX Laboratories sustains a dominant installed base through embedded software ecosystems and consumable-linked service contracts. Fujifilm Holdings Corporation leverages its film-to-digital transition heritage to control refurbishment and upgrade pathways for legacy X-ray systems. Siemens Healthineers anchors premium positioning through AI-augmented imaging workflows that reduce scan times in high-throughput specialty hospitals.
Veterinary diagnostic imaging encompasses non-invasive visualization systems engineered to anatomical scales from small exotics to equine patients, with spatial resolution requirements spanning 50-micron dental radiography to whole-body CT reconstruction. These systems enable early pathology detection, surgical planning, and treatment monitoring across species in clinical and research settings. Ultrasound devices lead volume deployment due to lower capital barriers and real-time guidance utility in companion animal practice, while MRI machines capture the fastest expansion as neurology and oncology referrals concentrate in tertiary centers. Digital Radiography within imaging technology segments now occupies the core replacement cycle as film-based systems face obsolescence across European and North American clinics.
The FDA Center for Veterinary Medicine and the EU Medical Device Regulation through notified bodies govern device safety and performance claims, while ISO 13485 quality management standards shape supplier qualification for international procurement. Japan's PMDA adds a third compliance layer for companies targeting METI-incentivized precision livestock farming programs. Stakeholders must monitor how AI-enabled diagnostic algorithms trigger new software-as-medical-device classifications across multiple jurisdictions.
Market Dynamics
AI-enabled diagnostic algorithms are forcing software-as-medical-device reclassifications across veterinary imaging, compressing product development timelines while expanding recurring revenue potential through algorithmic subscription layers.
Growth Catalysts
- EU MDR pathway acceleration:Streamlined CE marking for veterinary-specific devices reduces time-to-market for European manufacturers, incentivizing product portfolio expansion.
- Companion animal oncology:Rising referral volumes for cancer staging and treatment monitoring concentrate demand for MRI and CT capabilities in tertiary centers.
- Telemedicine integration:Cloud-based image transmission protocols enable remote specialist interpretation, extending diagnostic reach into rural and exurban practice settings.
Market Restraints
- Helium supply concentration:MRI magnet cooling depends on geographically concentrated helium extraction, exposing veterinary operators to price volatility and allocation disruptions.
- FDA Center for Veterinary Medicine review timelines:Novel imaging modalities face extended premarket notification periods, delaying commercialization of innovative hardware.
- Digital radiography substitution:Computed radiography systems face accelerated obsolescence as flat-panel detectors capture mid-market replacement cycles.
Strategic Opportunities
- India's PLI scheme extension:Production-linked incentives for medical device manufacturing create localized assembly pathways for cost-sensitive veterinary ultrasound systems.
- PET-CT convergence:Hybrid metabolic-anatomic imaging addresses unmet needs in equine sports medicine and exotic oncology, opening premium service tiers.
- Direct-to-clinic distribution:Manufacturer-bypass models for consumables and software licenses capture margin pools previously held by veterinary distributors.
Industry Challenges
- Veterinary radiologist credentialing:ACVR diplomate scarcity constrains throughput at high-volume specialty hospitals, capping equipment utilization rates.
- ISO 13485 compliance costs:Quality management system maintenance for multi-jurisdictional product lines elevates fixed overhead for mid-tier manufacturers.
- PACS integration complexity:Legacy hospital information system architectures resist seamless connectivity with modern imaging workstations, prolonging implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Diagnostic Imaging Market |
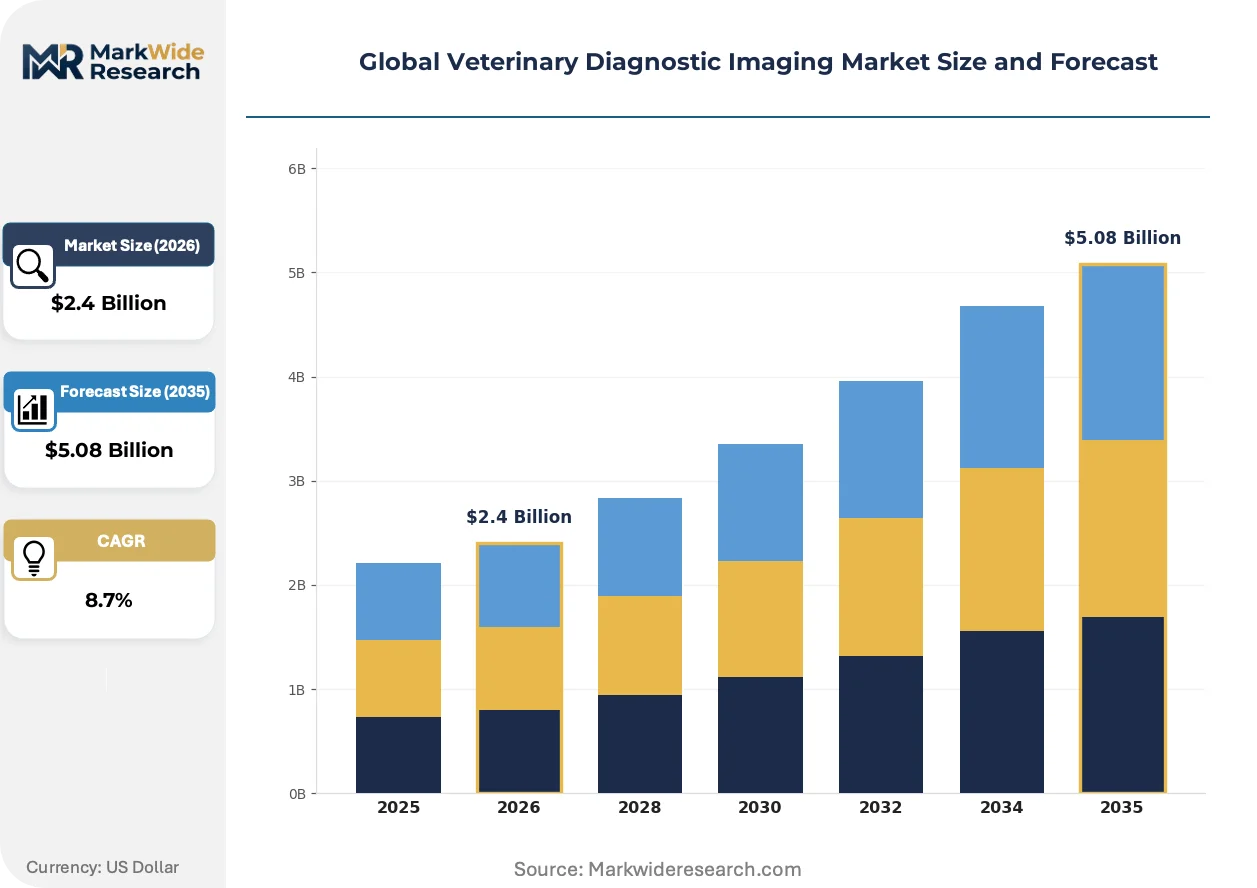
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Systems, Ultrasound Devices, MRI Machines, CT Scanners, Fluoroscopy Equipment Imaging Technology: Computed Radiography, Digital Radiography, Doppler Ultrasound, Nuclear Magnetic Resonance, Positron Emission Tomography Animal Species: Companion Animals, Livestock, Equines, Exotic Pets, Wildlife End User: Veterinary Clinics, Specialty Hospitals, Diagnostic Laboratories, Mobile Imaging Services, Research Institutions |
| Companies Covered | Fujifilm Holdings Corporation, Esaote SpA, IDEXX Laboratories, Inc., Mindray Medical International Ltd., Agfa-Gevaert Group, GE HealthCare, Siemens Healthineers AG, Hallmarq Veterinary Imaging Ltd., Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Diagnostic Imaging Market Shifts & Advancements
Workflow automation and point-of-care miniaturization are redrawing equipment deployment patterns across species and practice types, collapsing the distinction between referral-grade and generalist imaging capabilities.
Portable ultrasound systems are migrating from emergency and reproduction applications toward routine cardiac and abdominal screening in general companion animal practice. Mid-sized clinics in the United States and Germany now acquire wireless probe systems at replacement cycles shortened to 36-48 months. This diffusion is compressing the addressable market for cart-based systems below $15,000 while expanding subscription-based software attachment rates.
The EU AI Act's risk classification framework is imposing conformity assessment obligations on veterinary diagnostic algorithms marketed with clinical decision support claims. Manufacturers targeting European Economic Area deployment must now maintain post-market surveillance systems and algorithmic change control protocols. High-throughput specialty hospitals in France and the Netherlands are prioritizing vendors with established notified body relationships, creating procurement preference hierarchies.
Equipment-as-a-service contracting is displacing capital purchase models among independent practice groups facing liquidity constraints. Leasing structures bundling hardware, software, and preventive maintenance into per-scan or flat monthly fees now dominate ultrasound and digital radiography transactions in the United Kingdom and Australia. This shift concentrates credit risk with manufacturers while accelerating technology refresh cycles at the clinic level.
Global Veterinary Diagnostic Imaging Market Segmentation
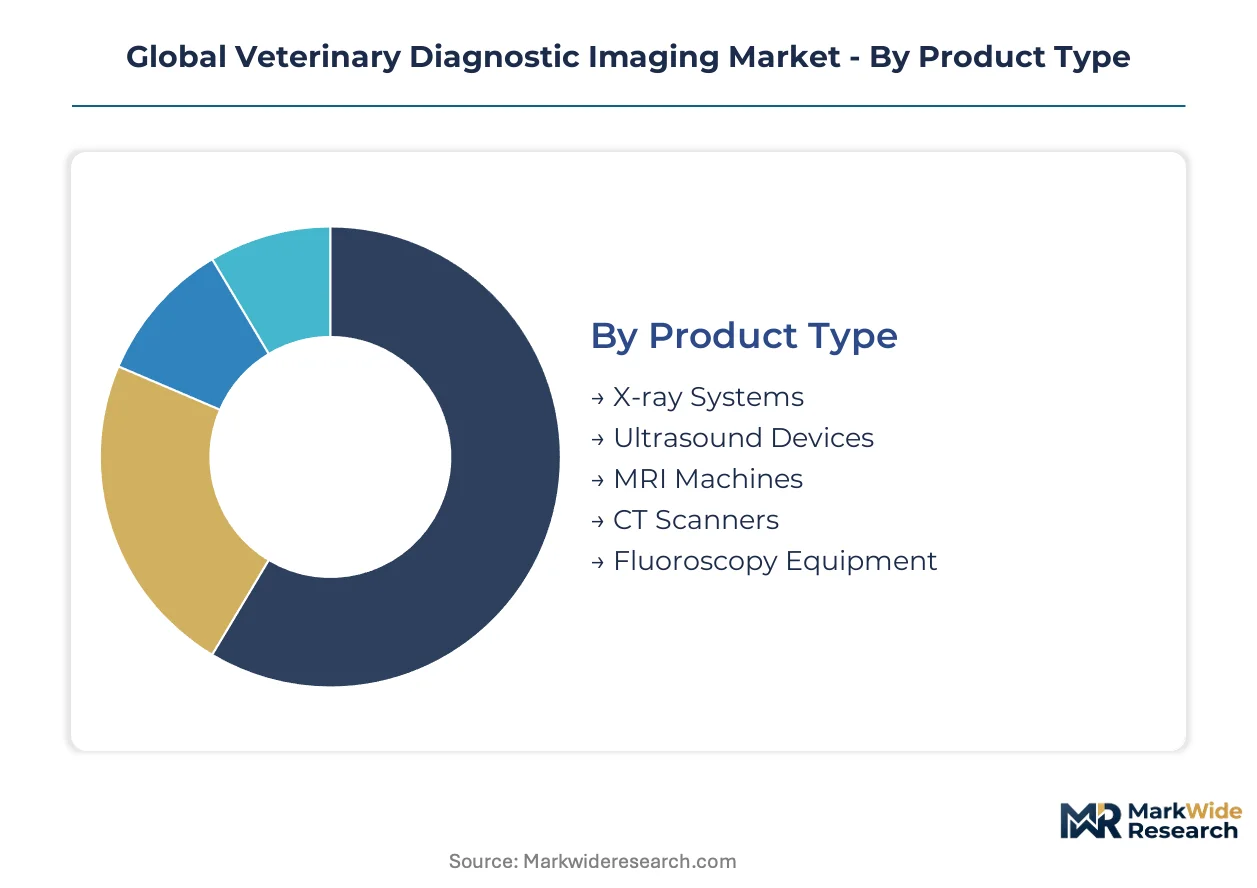
Segmentation in veterinary diagnostic imaging reveals how capital intensity, species physiology, and care delivery models fragment procurement patterns. Equipment specifications diverge sharply between high-throughput specialty hospitals and mobile rural services, while regulatory pathways vary by imaging modality and target species.
Product Type:
Cost tier stratification separates premium fixed installations from portable point-of-care systems across practice settings.
- X-ray Systems:Fixed and portable configurations using tungsten or molybdenum targets with kVp ranges optimized for species-specific tissue penetration. Demand clusters in United States companion animal clinics replacing film-based units, pressured by digital radiography substitution and shorter replacement cycles.
- Ultrasound Devices:Cart-based and handheld probes operating at 2-15 MHz with linear, convex, and phased array transducers for cardiac, abdominal, and reproductive imaging. Germany and United Kingdom independent practices drive wireless probe adoption, compressing addressable margins for cart systems below $15,000.
- MRI Machines:Superconducting and permanent magnet systems with field strengths from 0.2T to 3T adapted for veterinary patient positioning.
- CT Scanners:Multi-slice helical systems with sub-millimeter resolution for oncologic staging and orthopedic planning.
- Fluoroscopy Equipment:C-arm and fixed configurations enabling real-time guidance for interventional procedures and swallow studies.
X-ray Systems hold installed capacity. Ultrasound Devices are rotating up the share rankings.
Imaging Technology:
Application focus distinguishes legacy analog workflows from digital-native platforms and functional imaging capabilities.
- Computed Radiography:Photostimulable phosphor plate systems requiring laser scanning and chemical processing intermediates. European and North American clinics accelerate obsolescence as flat-panel detectors capture mid-market replacement demand.
- Digital Radiography:Direct and indirect conversion flat-panel detectors with immediate image acquisition and DICOM integration. United States specialty hospitals prioritize AI-augmented workflow integration, reducing scan times and radiologist interpretation bottlenecks.
- Doppler Ultrasound:Color and spectral Doppler modes assessing blood flow dynamics in cardiac and vascular applications.
- Nuclear Magnetic Resonance:Spectroscopic and diffusion-weighted sequences expanding beyond anatomic to metabolic tissue characterization.
- Positron Emission Tomography:Radiotracer-based metabolic imaging for oncology staging and neurology referrals.
Computed Radiography holds installed capacity. Digital Radiography is rotating up the share rankings.
Animal Species:
Volume concentration in companion animals contrasts with margin premiums in exotic and equine segments requiring specialized equipment configurations.
- Companion Animals:Canine and feline patients driving standardization in table dimensions, coil designs, and anesthesia protocols. United States pet insurance penetration and ACVR diplomate credentialing concentrate premium equipment procurement in tertiary referral centers.
- Livestock:Cattle, swine, and poultry applications emphasizing reproductive ultrasound and thoracic imaging for herd health management.
- Equines:Limb-focused imaging with weight-bearing CT and standing MRI configurations for sports medicine applications.
- Exotic Pets:Avian, reptilian, and small mammal species demanding specialized positioning devices and modified anesthesia systems.
- Wildlife:Field-deployable systems for conservation medicine and zoological institution applications.
Companion Animals hold installed capacity. Equines is rotating up the share rankings.
End User:
Customer type determines capital availability, utilization rates, and service contract structures across the value chain.
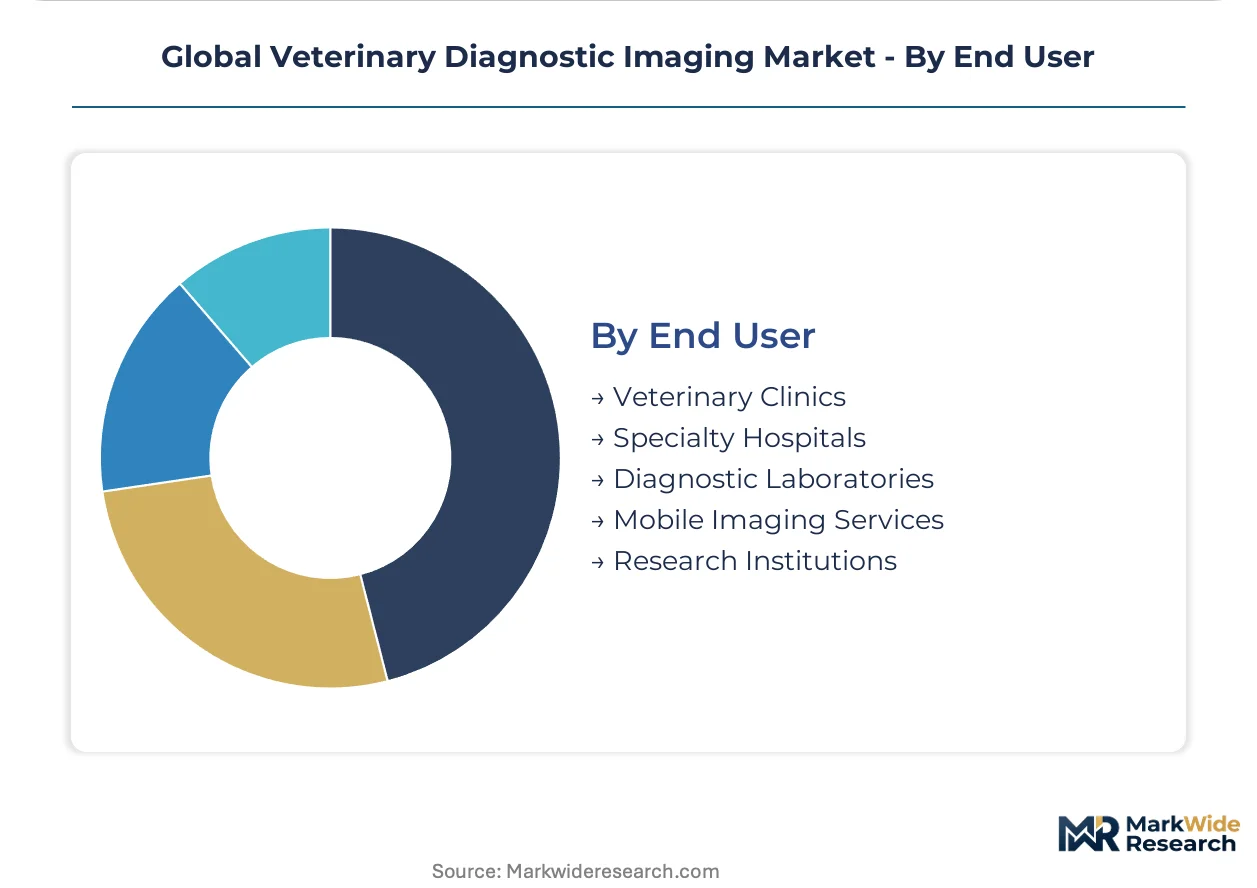
- Veterinary Clinics:General practice settings with mixed species caseloads prioritizing versatile, cost-contained imaging platforms. United Kingdom and Australia equipment-as-a-service contracting now dominates ultrasound and digital radiography transactions, bundling hardware, software, and preventive maintenance.
- Specialty Hospitals:Tertiary referral centers with ACVR board-certified radiologists and concentrated oncology, neurology, and orthopedic caseloads. France and Netherlands high-throughput institutions prioritize vendors with established EU notified body relationships for AI-enabled diagnostic algorithms.
- Diagnostic Laboratories:Centralized reference facilities processing outsourced imaging interpretations.
- Mobile Imaging Services:Trailer-mounted or van-based systems extending CT and MRI access to rural and exurban markets.
- Research Institutions:Preclinical imaging cores supporting pharmaceutical and veterinary medical device development.
Veterinary Clinics hold installed capacity. Specialty Hospitals is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across veterinary imaging procurement. United States buyers absorb premium equipment costs through pet insurance channels, while Indian and Southeast Asian markets prioritize cost-contained ultrasound systems for livestock applications.
United States
Specialty hospital expansion and ACVR diplomate credentialing concentrate demand for MRI and CT capabilities. FDA Center for Veterinary Medicine oversight shapes device safety standards for equipment deployed across tertiary referral networks. California and Texas metropolitan clusters anchor the highest concentration of PET-CT installations for companion animal oncology.
Germany
Independent practice consolidation and wireless probe adoption compress margins for cart-based ultrasound systems. EU Medical Device Regulation through notified bodies governs CE marking pathways for digital radiography platforms. Bavaria's veterinary clinic networks drive replacement cycles for AI-augmented imaging workstations.
China
Precision livestock farming programs under METI-equivalent agricultural modernization initiatives expand demand for portable ultrasound in swine and cattle operations. NMPA regulatory frameworks align with international quality standards for imported imaging equipment. Yangtze River Delta manufacturing clusters localize assembly of cost-sensitive veterinary diagnostic systems.
India
Production-linked incentive schemes for medical device manufacturing create localized assembly pathways for veterinary ultrasound systems. CDSCO quality management requirements shape supplier qualification for international procurement. Gujarat and Maharashtra industrial corridors concentrate contract manufacturing for export-oriented imaging equipment.
United Kingdom
Equipment-as-a-service contracting dominates transactions among liquidity-constrained independent practice groups. MHRA post-Brexit regulatory alignment maintains CE marking recognition for EU-sourced devices. London and Southeast England specialty hospitals prioritize vendors with established AI algorithm conformity assessment protocols.
Global Veterinary Diagnostic Imaging Market Competitive Landscape
Capability concentration sits with premium-tier imaging specialists; scale advantage sits with diversified healthcare conglomerates. The market structures around three tiers: integrated diagnostics platforms commanding installed base loyalty, precision imaging specialists anchoring tertiary hospital relationships, and cost-optimized manufacturers capturing emerging market volume. Strategic moves center on embedded software ecosystems that lock in consumable-linked service contracts, and AI-augmented workflow integration that reduces radiologist interpretation bottlenecks at high-throughput facilities.
Within the integrated diagnostics tier, IDEXX Laboratories exemplifies installed base dominance through embedded software ecosystems. Fujifilm Holdings Corporation occupies a position bridging film heritage to digital-native refurbishment pathways. Siemens Healthineers anchors premium positioning through AI-augmented imaging workflows. Among precision imaging specialists, Hallmarq Veterinary Imaging Ltd. represents veterinary-specific MRI configuration expertise.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| Esaote SpA |
| IDEXX Laboratories, Inc. |
| Mindray Medical International Ltd. |
| Agfa-Gevaert Group |
| GE HealthCare |
| Siemens Healthineers AG |
| Hallmarq Veterinary Imaging Ltd. |
| Canon Medical Systems Corporation |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp freight corridor's container cost dynamics compress margins for European veterinary imaging distributors while amplifying price differentiation between premium AI-augmented systems and cost-optimized portable units sourced from Asian manufacturing hubs.
Pricing Analysis
Aftermarket service contracts and algorithmic subscription tiers drive lifetime value capture across the veterinary imaging value chain. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated specialty hospital installations from mid-market digital radiography and entry-level handheld ultrasound. Cost compression in the wireless probe segment intensifies because German and United Kingdom independent practices now refresh equipment at 36-month cycles. General companion animal clinics exhibit highest price sensitivity, while United States tertiary referral centers with ACVR diplomate credentialing absorb premium equipment costs through pet insurance channels.
Supply Chain Analysis
Contract manufacturing concentration for veterinary ultrasound systems rests in Yangtze River Delta clusters, Gujarat pharmaceutical-industrial corridors, and Bavarian precision electronics hubs. Flat-panel detector arrays, superconducting magnet wire, and helium cryogenic systems anchor component dependencies. Single-source vulnerability in helium extraction from Qatar and Algeria exposes MRI manufacturers to allocation disruptions. Distribution runs through manufacturer-direct service contracts and veterinary distributor networks with embedded software ecosystem lock-in.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary diagnostic imaging market sits in early-cycle expansion as AI-enabled diagnostic algorithms penetrate beyond tertiary centers into general practice workflows, creating new recurring revenue architectures.
For Market Incumbents: Pre-empt obsolescence risk in computed radiography by accelerating flat-panel detector upgrade pathways and embedding predictive maintenance algorithms into service contracts. Defend installed base loyalty through consumable-linked software ecosystems that raise switching costs for IDEXX Laboratories-dominated reference laboratory networks. Prioritize ISO 13485 certification investments to qualify for EU MDR streamlined pathways and Japan PMDA precision livestock farming procurement. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme-extended veterinary ultrasound manufacturing by partnering with Gujarat and Maharashtra contract manufacturers for cost-sensitive livestock imaging systems. Target equine sports medicine and exotic pet oncology as white-space segments where standing MRI configurations and PET-CT hybrid systems face limited incumbent specialization. Pursue direct-to-clinic distribution models for wireless probe consumables and software licenses, bypassing traditional veterinary distributor margin pools. For Investors and Strategic Acquirers: Veterinary-specific AI algorithm developers with established EU notified body relationships and FDA Center for Veterinary Medicine premarket notification experience represent priority acquisition archetypes. Long-term viability hinges on software-as-medical-device classification navigation across multiple jurisdictions. Watch helium supply allocation disruptions and EU AI Act conformity assessment obligations as inflection indicators for MRI manufacturer margin compression and algorithm vendor procurement preference hierarchies.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Conformity Assessment | EU notified body relationships unlock procurement preference at France and Netherlands high-throughput specialty hospitals. |
| Helium Recovery System Investment | Closed-loop cryogenic cooling reduces MRI magnet operating cost exposure to Qatar-Algeria supply concentration. |
| Equipment-as-a-Service Contracting | Per-scan leasing structures dominate United Kingdom and Australia independent practice liquidity-constrained transactions. |
| Wireless Probe Miniaturization | Handheld cardiac and abdominal screening systems compress 36-48 month replacement cycles in German general practice. |
| Precision Livestock Farming Integration | METI-incentivized programs in Japan and China expand portable ultrasound demand for swine and cattle herd health management. |
Research Methodology
The analysis maps X-ray systems, ultrasound devices, MRI machines, CT scanners, and fluoroscopy equipment segments, each validated through biomedical engineers at specialty hospitals, veterinary distributor procurement managers, GPO contracts administrators, and ACVR diplomate radiologists. Primary interview findings triangulate against FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, ISO 13485 certification registries, and hospital equipment procurement databases. Bottom-up equipment shipment modeling and top-down veterinary practice spending allocation complete the validation architecture.
Assumptions held fixed include regulatory pathway timelines for software-as-medical-device classifications, helium supply allocation stability, and ACVR diplomate training pipeline throughput. Variables stress-tested across the analysis window encompass EU AI Act risk classification enforcement intensity, India's PLI scheme extension duration, and United States pet insurance penetration trajectories. Segmentation dimensions span product type, imaging technology, animal species, and end-user facility tier. CAGRs derive from equipment replacement cycle compression rates and algorithmic subscription attachment modeling.
Stress conditions across helium price volatility, FDA Center for Veterinary Medicine review timeline extensions, and wireless probe margin compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and variable sensitivities. Quarterly review of EU notified body AI algorithm backlog, India CDSCO medical device manufacturing license issuance, and United States specialty hospital ACVR staffing ratios is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
South Korea Computed Tomography Market
Medical Imaging
Argentina Diagnostic Imaging Equipment Market
Medical Imaging
Europe Intraoperative Imaging Market
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Functional Brain Imaging Systems Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
Medical Imaging Agent-Producing System Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
C-Arms Market
Medical Imaging
Italy Computed Tomography Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market