
 Contact-Free Sleep Monitoring Systems Market | 2026-2036
Contact-Free Sleep Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Contact-Free Sleep Monitoring Systems Market Outlook
Subscription-based sleep coaching and remote patient monitoring dashboards are expanding the recurring revenue profile of contact-free sleep monitoring platforms. ResMed leverages its established respiratory care infrastructure to anchor sleep data services within clinical workflows. Philips Healthcare sustains competitive positioning through hospital-grade sensor calibration and enterprise integration capabilities. SleepScore Labs specializes in consumer-facing sleep intelligence algorithms that differentiate its platform from hardware-centric rivals.
Contact-free sleep monitoring systems employ electromagnetic, optical, or acoustic sensing modalities to detect respiratory rate, heart rate variability, and body movement without physical skin contact, typically operating at distance ranges of 0.5 to 2 meters with millimeter-wave precision. These systems serve clinical screening, chronic disease management, and wellness optimization by converting biometric signatures into actionable sleep architecture metrics. Radar sensor technology leads commercial deployment due to its penetration through bedding materials and immunity to ambient light interference, while camera-based systems face structural constraints from privacy regulations that limit bedroom installation. Smart mattresses represent the fastest-growing product category as furniture manufacturers integrate silicon-layer sensing directly into consumer durables, shifting margin pools from discrete hardware toward embedded component supply.
The FDA software-as-a-medical-device framework and HIPAA interoperability standards shape product development roadmaps by mandating clinical validation thresholds and data governance architectures for systems targeting diagnostic use. The EU Medical Device Regulation imposes conformity assessment requirements on sleep apnea detection algorithms sold in European markets, creating divergent certification burdens for multi-territory vendors. Stakeholders must monitor evolving reimbursement codes for remote physiological monitoring to determine whether clinical-grade contact-free systems achieve sustainable payment parity with traditional polysomnography.
Market Dynamics
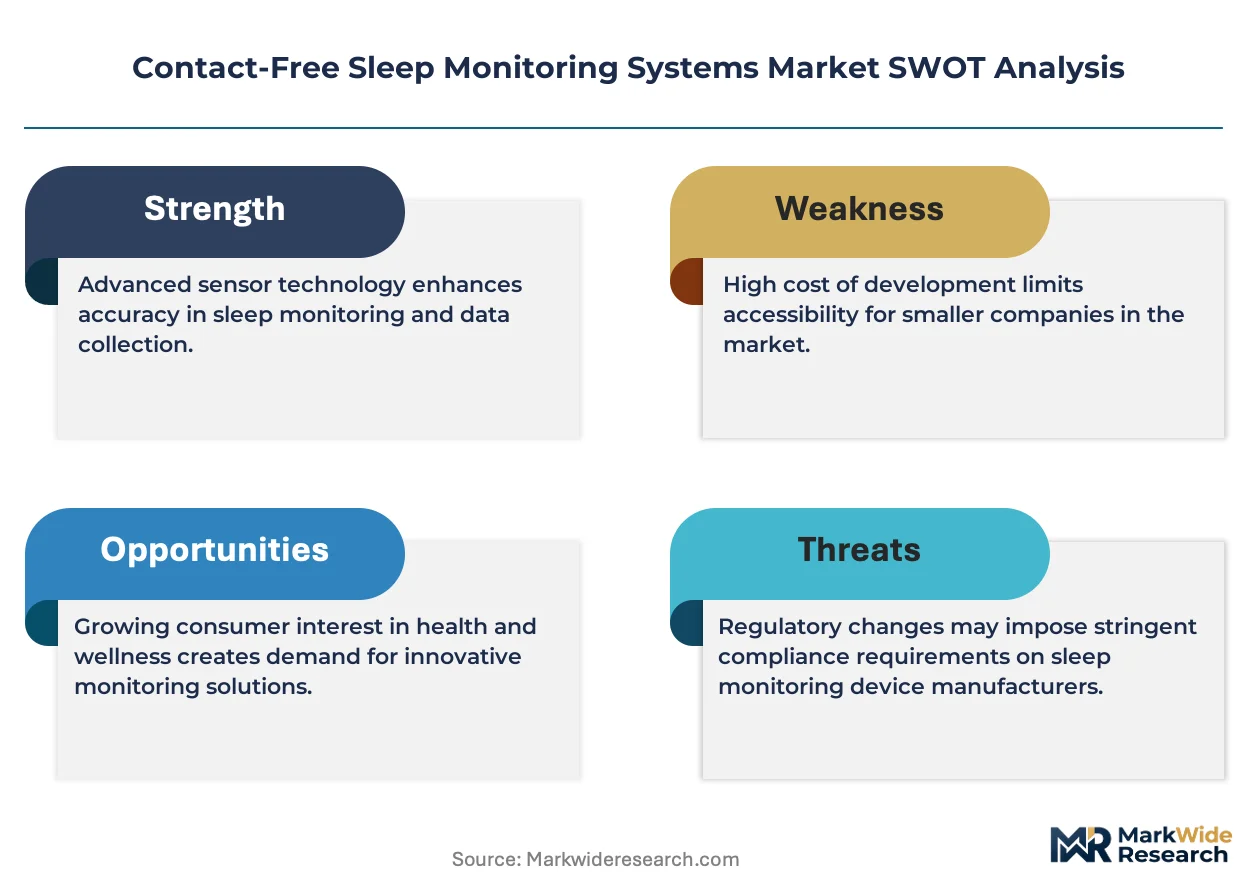
Radar-based biometric sensing is compressing hardware margins while elevating software valuation multiples across the contact-free sleep monitoring value chain. The FDA's software-as-a-medical-device framework is accelerating regulatory bifurcation between clinical-grade and wellness-oriented product tiers.
Growth Catalysts
- Hospital-to-home transition policies:United States aging-in-place initiatives and remote patient monitoring reimbursement codes are pulling clinical-grade systems into residential settings.
- Millimeter-wave radar maturation:Penetration through bedding materials and immunity to ambient light interference is expanding installation flexibility beyond camera-based alternatives.
- EU Medical Device Regulation:Conformity assessment requirements for sleep apnea detection algorithms are creating certification barriers that favor established vendors with clinical validation resources.
Market Restraints
- Silicon-layer sensor cost concentration:Advanced radar-on-chip components depend on concentrated semiconductor foundry capacity in East Asia, exposing margin structures to supply volatility.
- Privacy regulation friction:GDPR bedroom surveillance restrictions and state-level biometric privacy laws in Illinois and Texas constrain camera-based system deployment regardless of technical capability.
- Polysomnography substitution ceiling:Diagnostic-grade polysomnography retains reimbursement superiority for sleep disorder confirmation, limiting contact-free system penetration in clinical confirmation workflows.
Strategic Opportunities
- Smart mattress integration:Furniture manufacturers embedding silicon-layer sensing directly into consumer durables are shifting margin pools from discrete hardware toward embedded component supply.
- Subscription-based sleep coaching:Recurring revenue models combining biometric data with personalized intervention protocols are expanding lifetime value per installed device.
- India PLI scheme for electronics manufacturing:Production-linked incentives for medical device assembly are attracting contract manufacturers to establish radar sensor packaging capacity for regional supply.
Industry Challenges
- Algorithm validation timelines:FDA 510(k) clearance for respiratory event detection requires multi-site clinical trials extending product development cycles by 18-24 months.
- Interoperability architecture complexity:HIPAA-compliant data governance and EHR integration demand specialized health informatics talent scarce among consumer electronics firms.
- Calibration drift management:Sensor accuracy degradation over mattress lifecycle requires field recalibration infrastructure absent in traditional retail distribution channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact-Free Sleep Monitoring Systems Market |
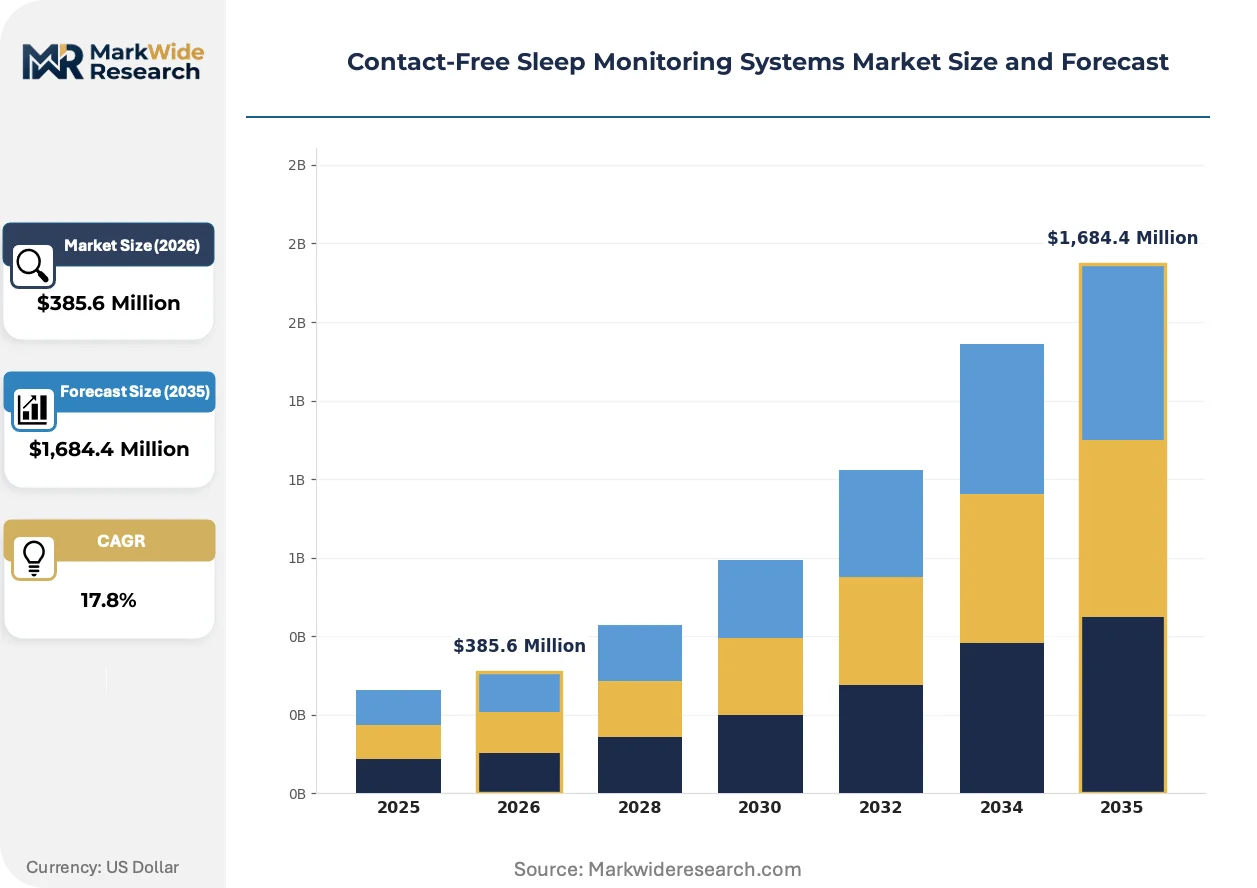
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,684.4 Million |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar Sensors, Infrared Sensors, Ultrasonic Sensors, Camera-Based Systems End User: Healthcare Providers, Research Institutions, Sleep Clinics, Home Users Product Type: Wearable Devices, Non-Wearable Devices, Smart Mattresses, Sleep Trackers Application: Sleep Quality Monitoring, Sleep Apnea Detection, Health Assessment, Sleep Research |
| Companies Covered | ResMed, Philips Healthcare, SleepScore Labs, Fitbit, Samsung Electronics, Apple, EarlySense, Withings, Sleepace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact-Free Sleep Monitoring Systems Market Strategic Shifts
Biometric sensing modalities are fragmenting into specialized form factors while regulatory frameworks force divergence between clinical and wellness product architectures. Software monetization is overtaking hardware shipment value as the primary revenue determinant.
Millimeter-wave radar arrays with sub-millimeter displacement resolution are overtaking piezoelectric and load-cell alternatives in mattress-embedded applications. Long-term care facilities in the United States are adopting these systems for fall-risk monitoring alongside sleep architecture assessment. The technology is compressing installation costs while expanding reimbursable monitoring endpoints beyond traditional sleep metrics.
The EU Medical Device Regulation's risk-classification hierarchy for diagnostic algorithms is forcing sleep apnea detection software into conformity assessment procedures previously reserved for physical devices. European vendors are restructuring quality management systems to accommodate notified body oversight of machine-learning model updates. This regulatory compression is advantaging firms with pre-existing ISO 13485 certification over consumer electronics entrants.
Direct-to-employer wellness contracts are displacing retail consumer acquisition as the dominant commercialization pathway for non-clinical sleep monitoring platforms. Self-insured employers in the United States are bundling sleep data services with chronic disease management programs to reduce cardiovascular risk pooling costs. This channel rotation is concentrating demand among occupational health vendors with enterprise sales infrastructure rather than consumer electronics distributors.
Contact-Free Sleep Monitoring Systems Market Segmentation
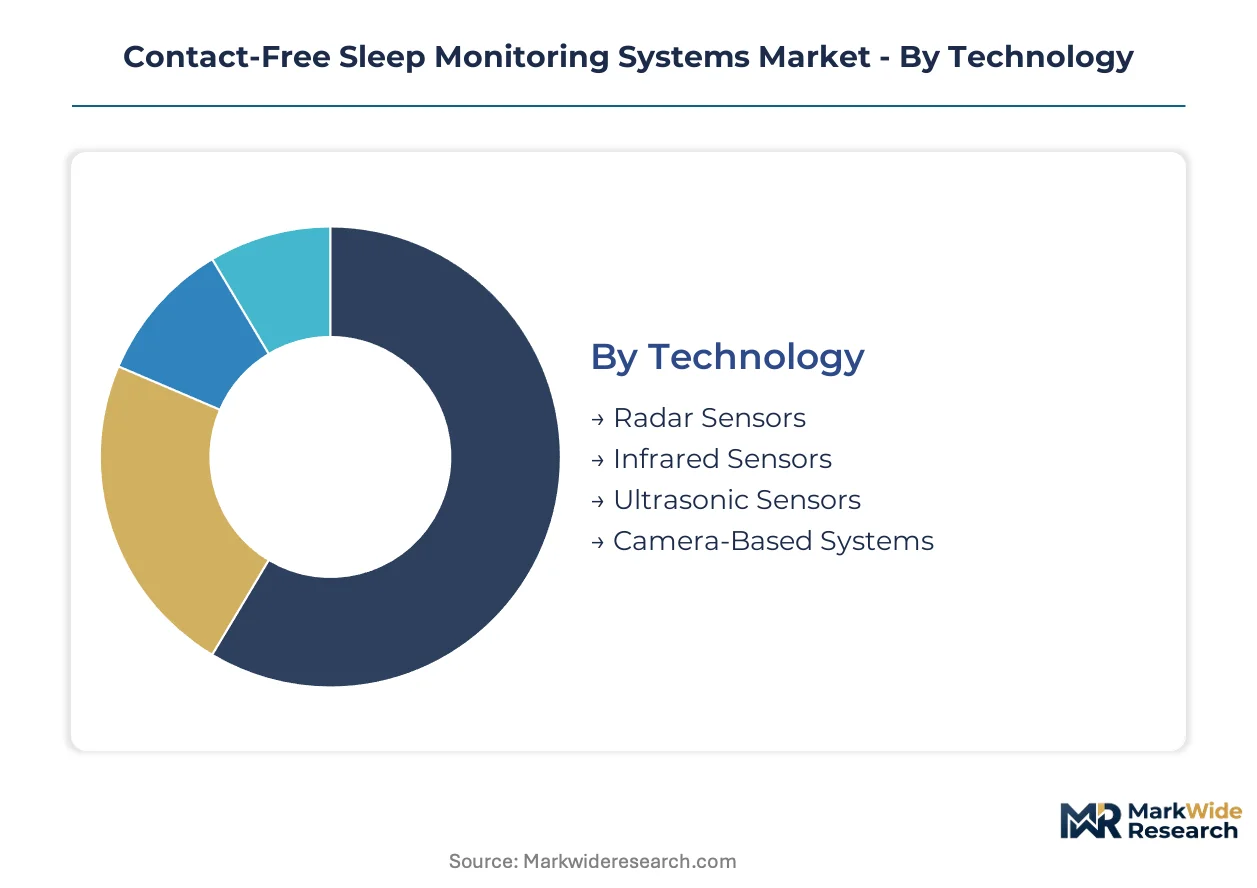
Technology choices in contact-free sleep monitoring determine installation flexibility, regulatory pathway, and reimbursement eligibility. Product architecture decisions cascade through hardware margins, software validation timelines, and end-user channel strategy.
Technology:
Upgrade cycles in sleep monitoring hardware favor sensing modalities with embedded software upgradeability over component replacement.
- Radar Sensors:Millimeter-wave arrays penetrate bedding materials and operate reliably across ambient light conditions. Demand concentrates in United States long-term care facilities where fall-risk monitoring expands reimbursable endpoints beyond sleep metrics alone.
- Infrared Sensors:Thermal detection of respiratory patterns requires line-of-sight positioning that constrains bedroom furniture placement. European home users drive procurement where GDPR restrictions on camera-based alternatives create regulatory preference for non-visual sensing.
- Ultrasonic Sensors:Acoustic displacement measurement offers lower hardware cost but reduced accuracy during deep sleep stages with minimal movement.
- Camera-Based Systems:Optical flow algorithms face structural deployment barriers from Illinois and Texas biometric privacy statutes regardless of technical capability.
Radar sensors sit at the top of the volume ranking, with infrared sensors climbing the fastest as privacy regulations harden against optical alternatives.
End User:
Customer type determines pricing architecture, with clinical validation requirements separating premium tiers from wellness-oriented offerings.
- Healthcare Providers:Hospital systems and integrated delivery networks require FDA 510(k) clearance for diagnostic claims. United States procurement concentrates in health systems pursuing hospital-to-home transitions under remote patient monitoring reimbursement codes.
- Sleep Clinics:Specialized diagnostic facilities balance polysomnography substitution against regulatory liability for missed apnea events.
- Research Institutions:Academic sleep laboratories prioritize raw data export and algorithm transparency over polished user interfaces.
- Home Users:Consumer procurement channels through direct-to-employer wellness contracts rather than retail electronics distributors.
Healthcare providers command the highest average selling prices, while home users deliver the steepest expansion trajectory through employer-sponsored program enrollment.
Product Type:
Form factor decisions determine whether margin pools accumulate in discrete hardware, embedded components, or recurring software services.
- Smart Mattresses:Silicon-layer sensing integrated directly into furniture shifts supply relationships toward mattress manufacturers and away from standalone device vendors. United States furniture brands are embedding radar-on-chip components at factory assembly.
- Non-Wearable Devices:Bedside and under-mattress sensors require minimal user behavior change, supporting elderly patient compliance in aging-in-place programs.
- Wearable Devices:Contact-free claims for wrist and chest-worn products face technical scrutiny where skin proximity blurs category boundaries.
- Sleep Trackers:Consumer-grade devices without clinical validation occupy wellness-tier pricing with limited reimbursement access.
Smart mattresses lead volume rankings, with non-wearable devices gaining share fastest as long-term care procurement accelerates.
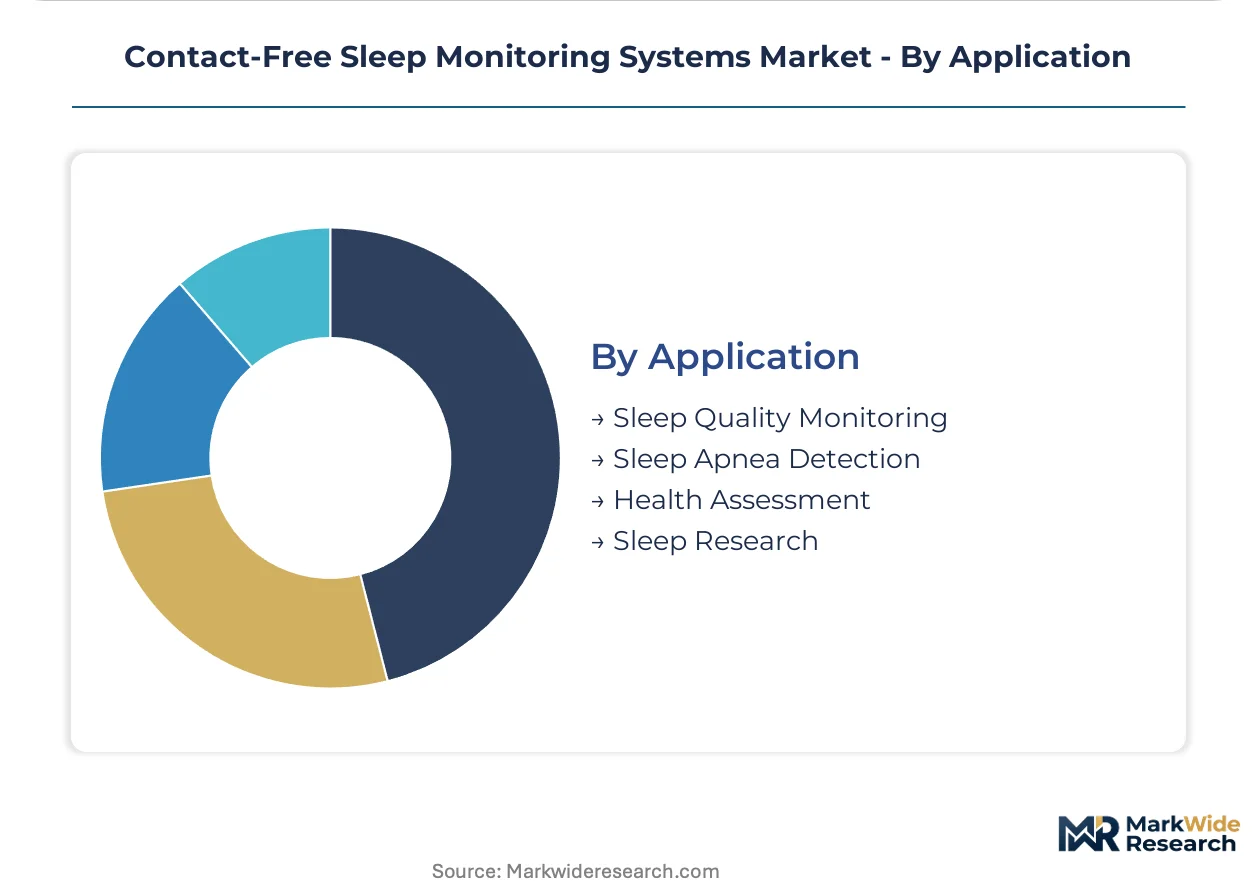
Application:
Use case specificity determines regulatory classification, with diagnostic claims triggering medical device pathways that wellness monitoring avoids.
- Sleep Apnea Detection:Algorithmic screening for respiratory events requires multi-site clinical trials extending FDA clearance timelines. United States vendors pursue 510(k) pathways to access remote physiological monitoring reimbursement.
- Sleep Quality Monitoring:Architecture and duration metrics face lower validation burdens, enabling faster commercialization for wellness-oriented positioning.
- Health Assessment:Cardiovascular risk indicators derived from nocturnal heart rate variability attract employer wellness program procurement.
- Sleep Research:Academic applications demand epoch-level data granularity and open API access that consumer platforms rarely provide.
Sleep quality monitoring holds the broadest installed base, with sleep apnea detection expanding most quickly as reimbursement codes mature for contact-free alternatives to polysomnography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands reimbursement infrastructure for remote patient monitoring that Germany lacks, while Japan's aging demographics outpace clinical capacity expansion in comparable economies.
United States
Hospital-to-home transition policies and aging-in-place Medicaid waivers drive procurement of radar-based systems for elderly residential monitoring. The FDA's software-as-a-medical-device framework accelerates 510(k) clearance pathways for sleep apnea detection algorithms. Long-term care facilities in Florida and Arizona embed millimeter-wave sensors into fall-risk monitoring protocols alongside sleep architecture assessment.
Germany
Integrated care contracts and disease management programs for chronic heart failure create reimbursement access for nocturnal cardiovascular monitoring. The EU Medical Device Regulation imposes notified body oversight on diagnostic algorithm updates, extending validation timelines. Medical technology clusters in Baden-Württemberg concentrate radar-on-chip packaging capacity for regional hospital system supply.
Japan
Super-aging municipality initiatives and shortage of sleep laboratory technicians push demand for automated sleep screening in rural prefectures. The PMDA's guidance on software medical devices requires clinical validation datasets exceeding wellness-tier offerings. Tokyo-based electronics firms partner with mattress manufacturers in Osaka-Kobe industrial corridors to integrate silicon-layer sensing into furniture exports.
China
Hospital construction in tier-two cities and chronic disease management pilots under Healthy China 2030 expand clinical-grade installation bases. NMPA's medical device classification rules for AI-assisted diagnostic software create regulatory friction for algorithm updates. Shenzhen hardware accelerators prototype radar sensor modules for smart home OEMs targeting domestic aged care facilities.
India
Production-linked incentive schemes for electronics manufacturing attract contract assemblers to establish radar sensor packaging lines for regional medical device supply. CDSCO's streamlined registration for Class A and B software medical devices reduces entry barriers for wellness-tier platforms. Bengaluru health technology clusters develop sleep coaching applications targeting corporate wellness programs in information technology campuses.
Contact-Free Sleep Monitoring Systems Market Competitive Environment
Top-tier vendors anchor clinical validation infrastructure and FDA clearance pathways, while mid-tier wellness platforms compete on consumer acquisition cost and employer channel access. The vendor base stratifies across respiratory care incumbents, consumer electronics conglomerates, and sleep-specialized algorithm developers. Three archetypes dominate: established medical device manufacturers with polysomnography heritage, technology platforms leveraging existing hardware ecosystems, and pure-play sleep intelligence specialists. Competitive moves concentrate on strategic partnerships with mattress manufacturers and portfolio diversification into remote patient monitoring reimbursement codes.
Among respiratory care specialists, ResMed exemplifies the clinical-tier archetype through its established reimbursement relationships and hospital system integration capabilities. Philips Healthcare occupies a position bridging medical device certification and consumer electronics scale, reflecting its diversified health technology portfolio. SleepScore Labs represents the pure-play algorithm specialist tier, differentiating through sleep intelligence software rather than hardware manufacturing ownership. These three anchors illustrate the strategic divergence between clinical validation depth and consumer platform reach that defines competitive positioning in contact-free sleep monitoring.
| Leading Market Players |
|---|
| ResMed |
| Philips Healthcare |
| SleepScore Labs |
| Fitbit |
| Samsung Electronics |
| Apple |
| EarlySense |
| Withings |
| Sleepace |
| Others |
Value Chain & Pricing Dynamics
Captive radar-on-chip production in Taiwan and South Korea anchors both component availability and pricing power for clinical-grade system vendors, while wellness-tier competitors remain exposed to spot-market silicon sourcing. This integration choice separates FDA-cleared manufacturers from consumer electronics entrants competing on procurement cost alone.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for millimeter-wave sensor modules, compressing hardware margins while elevating software valuation multiples. Three-tier pricing structure across FDA-cleared clinical, CE-marked wellness, and unvalidated consumer tiers reflects certification investment recovery timelines. Cost compression in the wellness segment is intensifying because Shenzhen-based OEMs are flooding direct-to-consumer channels with undifferentiated radar modules. Home users in employer-sponsored programs show lowest price sensitivity, while independent elderly consumers in aging-in-place programs exhibit highest elasticity.
Supply Chain Analysis
FDA 510(k) clearance and ISO 13485 certification gating restrict qualified component sourcing to semiconductor foundries with medical-grade quality management systems, concentrating supply relationships. Taiwan, South Korea, and the United States dominate radar-on-chip fabrication, with backend packaging spreading to Malaysia and Vietnam. Raw material dependencies include gallium arsenide substrates, advanced packaging resins, and precision antenna substrates. Single-source vulnerability runs through TSMC's specialty process nodes for sub-6GHz radar integration. Distribution runs through hospital GPO contracts and direct-to-employer wellness platform aggregators rather than retail electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between United States reimbursement infrastructure and Asian manufacturing cost bases, with the 17.80% CAGR differential reflecting regulatory premium capture against component sourcing savings.
For Market Incumbents: To counter algorithm commoditization from consumer electronics entrants, ResMed and Philips Healthcare should deepen backward integration into radar sensor packaging through captive facilities in Malaysia's medical device zones. Channel control through exclusive GPO contracts with United States health systems remains the priority defensive lever.
For New Entrants and Emerging Players: Direct-to-employer wellness platform partnerships offer the lowest customer acquisition cost route for algorithm-only vendors lacking hardware manufacturing assets. The most penetrable white-space sits in India's corporate wellness programs, where CDSCO's streamlined Class A/B software registration reduces entry barriers. A sleep-coaching subscription bundled with biometric hardware financing attacks the compliance gap in employer chronic disease management.
For Investors and Strategic Acquirers: Roll-up economics work for clinical-validation specialists because FDA 510(k) clearance timelines create scarcity value for pre-cleared algorithm platforms. Five-to-ten year viability hinges on reimbursement code expansion for remote physiological monitoring. The signal to watch is CMS's creation of discrete billing codes for contact-free sleep apnea screening, which would trigger hospital system procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Unlocks remote patient monitoring reimbursement codes for United States hospital system procurement. |
| CE Marking Pathway | Enables EU Medical Device Regulation compliance for sleep apnea detection algorithm sales. |
| Hospital System Partnership | Secures GPO contract access and anchors clinical validation within integrated delivery networks. |
| Software Companion Development | Expands recurring revenue through subscription-based sleep coaching and remote monitoring dashboards. |
| Reimbursement Strategy | Positions contact-free systems for payment parity with traditional polysomnography in CMS coding. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with sleep technology executives, FDA regulatory consultants, hospital biomedical engineers, and GPO contracts managers with secondary validation. Secondary sources included FDA 510(k) clearance databases, CMS Medicare reimbursement filings, EU MDR notified body registries, and hospital procurement contract disclosures. Bottom-up sensor shipment modeling and top-down sleep monitoring service revenue estimates were triangulated against installed base calculations.
Segment-weighting across technology modality, end-user archetype, product form factor, and application use case drove volume and value allocation throughout the projection horizon. CAGRs were derived from logistic diffusion curves fitted to reimbursement code adoption timelines and hospital-to-home transition policy implementation. Forecast inputs included radar sensor cost decline curves, FDA software-as-a-medical-device framework evolution, and employer wellness program penetration rates.
Regulatory clearance delays, reimbursement code non-creation, and semiconductor supply disruption are the dominant revision risks to the outlook. Deviation in CMS reimbursement policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Asia Pacific Wireless Healthcare Market
Patient Monitoring
Remote Electrocardiogram Monitoring Market
Patient Monitoring
Global Fetal and Neonatal Monitoring Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Heart Monitoring Devices Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
Global Hemodynamic Monitoring System Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
Patient Monitoring Devices Market
Patient Monitoring
Germany Blood Glucose Monitoring Market