
 Global Smart Pulse Oximeters Market | 2026-2036
Global Smart Pulse Oximeters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Pulse Oximeters Market Foresight
The capability gap between capital-heavy sensor manufacturers and software-centric entrants is rotating competitive advantage toward integrated platform providers. Masimo Corporation leverages its hospital-grade signal processing heritage to dominate clinical channels. Medtronic plc anchors its position through backward integration into cardiac care ecosystems. Koninklijke Philips N.V. extends consumer reach via sleep and respiratory product adjacencies.
Smart pulse oximeters are non-invasive photoplethysmography devices that measure arterial oxygen saturation and pulse rate through light absorption at red and infrared wavelengths, typically operating at 660 nm and 940 nm with accuracy within 2% for SpO2 readings above 70%. These instruments serve continuous physiological monitoring across clinical triage, chronic disease surveillance, and athletic performance optimization. Fingertip devices lead unit volume due to low cost and pharmacy accessibility, while wrist-worn formats capture expanding margin pools through multi-parameter biosensor fusion. Remote patient monitoring applications are outpacing fitness tracking as reimbursement codes for connected diagnostics mature across health systems.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development timelines and market access barriers for connected diagnostic devices. ISO 80601-2-61 standards govern pulse oximeter accuracy and alarm performance, compelling manufacturers to maintain rigorous calibration protocols. Stakeholders must monitor evolving data localization mandates from China's NMPA and India's CDSCO as these jurisdictions tighten oversight of cross-border health data transmission from consumer-grade monitoring devices.
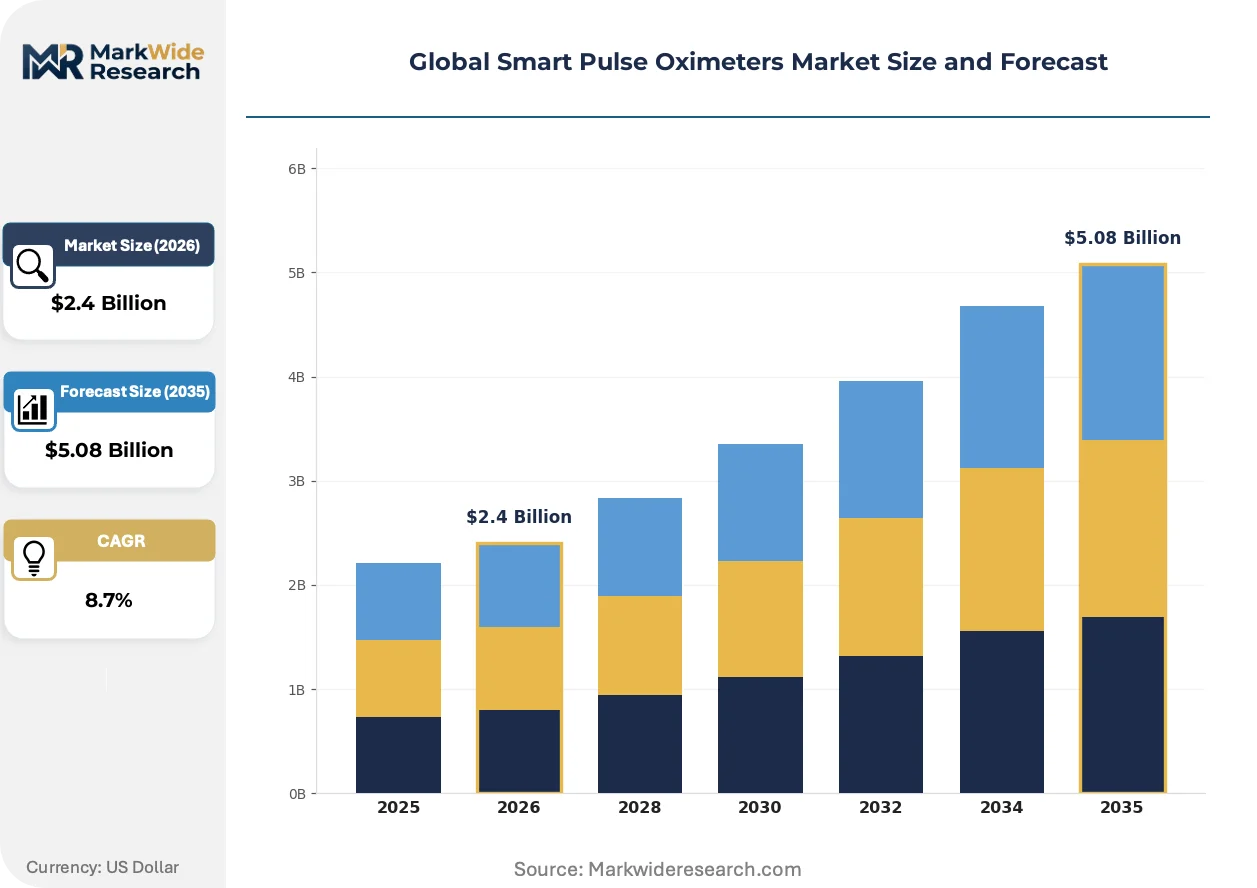
Market Dynamics
Remote patient monitoring reimbursement codes are consolidating clinical demand around connected diagnostic platforms, forcing hardware manufacturers to absorb software development costs and recurring cloud infrastructure investments previously externalized to health systems.
Growth Catalysts
- FDA 510(k) pathway maturation:Streamlined clearance for predicate devices with established photoplethysmography algorithms accelerates time-to-market for iterative sensor improvements.
- Home care provider consolidation:Large hospital-at-home networks in the United States are standardizing on interoperable pulse oximeter fleets to reduce training overhead across distributed nursing staff.
- Photoplethysmography fusion with accelerometry:Wrist-worn devices combining SpO2 with motion artifact rejection are displacing fingertip units in sleep apnea screening workflows.
Market Restraints
- Indium gallium arsenide photodiode supply concentration:Near-infrared sensor substrate fabrication concentrates among three East Asian foundries, exposing manufacturers to input cost volatility.
- EU MDR technical documentation burden:Conformity assessment timelines for Class IIa connected devices have extended from 6 to 14 months, freezing product pipeline velocity.
- Smartwatch SpO2 substitution:Consumer electronics OEMs are bundling oximetry into multi-function wearables at marginal hardware cost, compressing standalone device addressable market.
Strategic Opportunities
- Chronic obstructive pulmonary disease surveillance in Germany:Disease management contracts between statutory health insurers and pulmonology networks create procurement pull for continuous remote monitoring.
- China NMPA data localization mandate:Domestic cloud infrastructure requirements for health data transmission favor local platform partnerships over direct foreign market entry.
- Peripheral artery disease screening convergence:Integration of SpO2 with ankle-brachial index measurement is opening vascular surgery clinic adoption.
Industry Challenges
- ISO 80601-2-61 calibration technician scarcity:Validated phantom testing for accuracy verification requires specialized biomedical engineering expertise concentrated among legacy hospital device service organizations.
- Legacy electronic health record integration friction:HL7 FHIR connectivity requirements demand middleware development that stretches thinly capitalized entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Pulse Oximeters Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fingertip, Wrist-worn, Tabletop, Portable Technology: Bluetooth, Wi-Fi, Infrared, Optical Sensors, Photoplethysmography Application: Chronic Disease Management, Fitness Monitoring, Sleep Apnea Detection, Emergency Care, Remote Patient Monitoring End User: Home Care Providers, Ambulatory Centers, Diagnostic Laboratories, Telehealth Services, Sports Training Facilities |
| Companies Covered | Masimo Corporation, Medtronic plc, Koninklijke Philips N.V., Nonin Medical, Inc., Nihon Kohden Corporation, GE Healthcare, Contec Medical Systems Co., Ltd., Smiths Medical, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Pulse Oximeters Market Shifts & Advancements
Multi-parameter biosensor fusion is collapsing the boundary between consumer wellness and clinical-grade monitoring, with algorithmic signal processing now the primary differentiator rather than optical hardware performance alone.
Reflectance-mode photoplethysmography is fragmenting form factor assumptions that previously constrained pulse oximetry to fingertip placement. Wrist and ear canal sensors using green and infrared LED arrays are achieving SpO2 correlation coefficients above 0.92 against transmittance benchmarks in controlled studies. Cardiology outpatient clinics are piloting these alternatives for 24-hour ambulatory monitoring where finger probe compliance fails.
EU MDR post-market surveillance requirements are mandating systematic collection of real-world performance data from deployed devices. Manufacturers must now maintain periodic safety update reports and trend analysis of adverse events across their entire installed base. This obligation favors platform-centric vendors with cloud-connected fleets over disconnected point-of-sale distribution models.
Hospital procurement committees are unbundling device acquisition from data analytics subscriptions, treating pulse oximeter hardware as commoditized infrastructure while negotiating separately for predictive algorithm access. This bifurcation is visible in United States health system RFP structures that separate capital equipment line items from multi-year software licensing agreements.
Global Smart Pulse Oximeters Market Segmentation
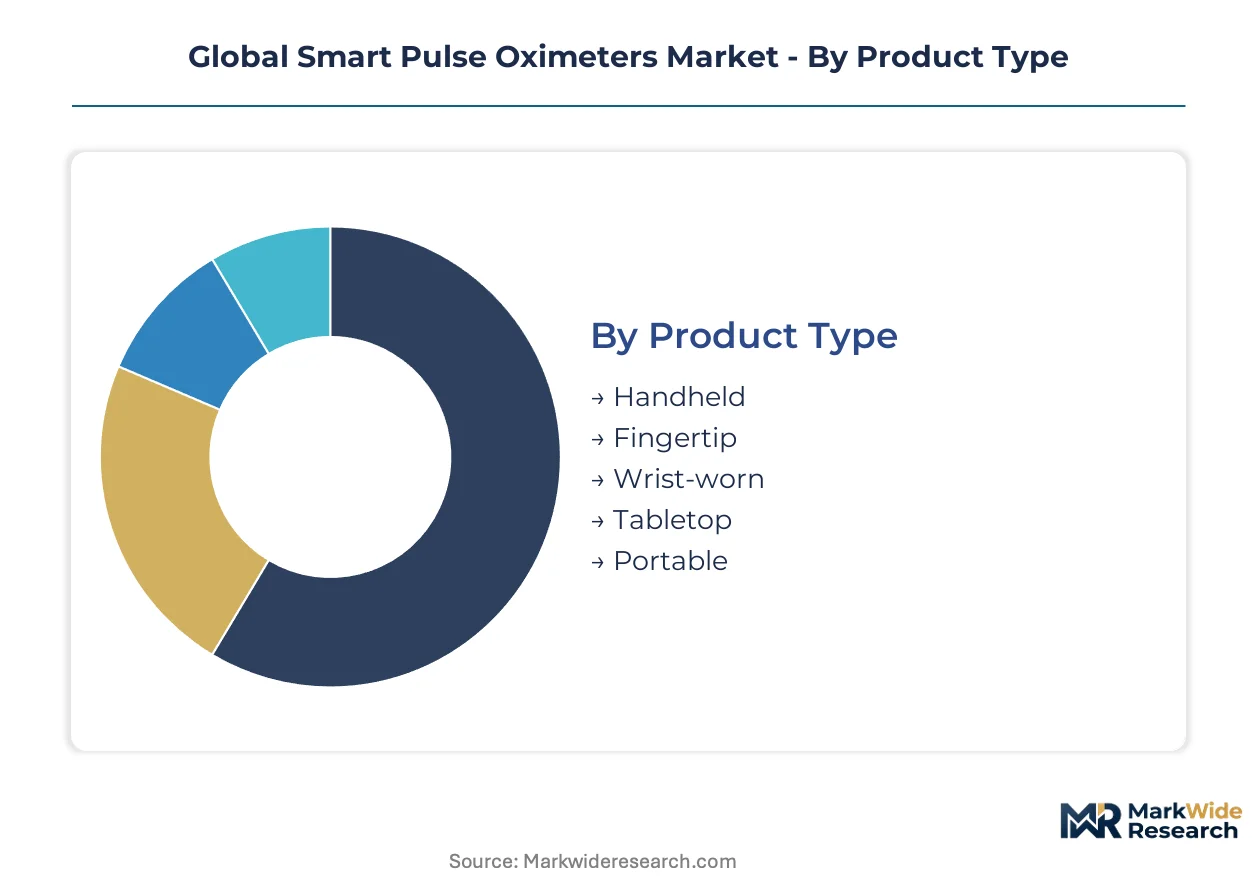
Segmentation in smart pulse oximeters reveals how hardware form factors, connectivity protocols, and clinical use cases map to distinct procurement channels and margin structures. Manufacturers must align product development with the specific reimbursement and integration requirements of each segment cluster.
Product Type:
Channel strategy diverges sharply between pharmacy retail, hospital procurement, and direct-to-consumer e-commerce, with each format optimized for specific point-of-care workflows.
- Fingertip:Clip-on photoplethysmography sensors weighing under 50 grams dominate pharmacy counter sales and home care kit bundling. United States hospital-at-home networks standardize on these units for distributed nursing staff due to minimal training requirements and disposable probe compatibility.
- Wrist-worn:Reflectance-mode sensors fused with accelerometry capture sleep apnea screening contracts from pulmonology networks in Germany. Multi-parameter biosensor integration commands premium pricing through recurring algorithm subscriptions rather than hardware margins alone.
- Handheld:Battery-operated units with detachable probes serve emergency medical services and pre-hospital triage in China.
- Tabletop:AC-powered devices with integrated printers anchor diagnostic laboratory workflows in India.
- Portable:Ruggedized variants with extended battery life target sports training facilities and military field medicine applications.
Fingertip devices dominate installed base. Wrist-worn formats are where expansion concentrates.
Technology:
Cost tier stratification separates premium connected platforms from economy standalone units, with connectivity module selection determining software revenue potential.
- Photoplethysmography:Dual-wavelength optical detection at 660 nm and 940 nm remains the foundational signal acquisition method across all form factors. FDA 510(k) predicate pathways favor established photoplethysmography algorithms, accelerating clearance timelines for iterative hardware improvements.
- Bluetooth:Low-energy protocols enable seamless pairing with smartphone applications and electronic health record middleware. Home care providers in the United States mandate Bluetooth connectivity for remote patient monitoring reimbursement eligibility under emerging CPT codes.
- Wi-Fi:Direct cloud transmission supports continuous monitoring in sleep labs and telehealth service platforms.
- Infrared:Near-infrared spectroscopy variants target cerebral oximetry niche applications in cardiac surgery.
- Optical Sensors:Advanced LED arrays with motion artifact rejection algorithms command premium positioning in wrist-worn fitness monitoring segments.
Photoplethysmography anchors every hardware architecture. Bluetooth connectivity is climbing the fastest as reimbursement codes mature.
Application:
Customer type segmentation separates acute clinical buyers from wellness consumers, with procurement authority residing in distinct organizational functions.
- Remote Patient Monitoring:Continuous SpO2 transmission with automated alert escalation supports hospital-at-home programs and chronic disease surveillance contracts. United States health systems unbundle hardware acquisition from predictive algorithm licensing, treating pulse oximeters as commoditized infrastructure.
- Sleep Apnea Detection:Overnight desaturation pattern analysis drives wrist-worn device adoption in cardiology outpatient clinics where finger probe compliance fails. Germany's statutory health insurers now reimburse connected diagnostic platforms for obstructive sleep apnea screening.
- Chronic Disease Management:COPD and heart failure patients require daily SpO2 logging integrated with care coordination platforms.
- Fitness Monitoring:Athletic performance optimization applications face substitution pressure from smartwatch SpO2 bundling at marginal hardware cost.
- Emergency Care:Rapid triage protocols in ambulatory centers demand instantaneous SpO2 readings with audible alarm thresholds.
Remote patient monitoring commands highest average revenue per user. Sleep apnea detection is gaining share fastest as screening guidelines expand.
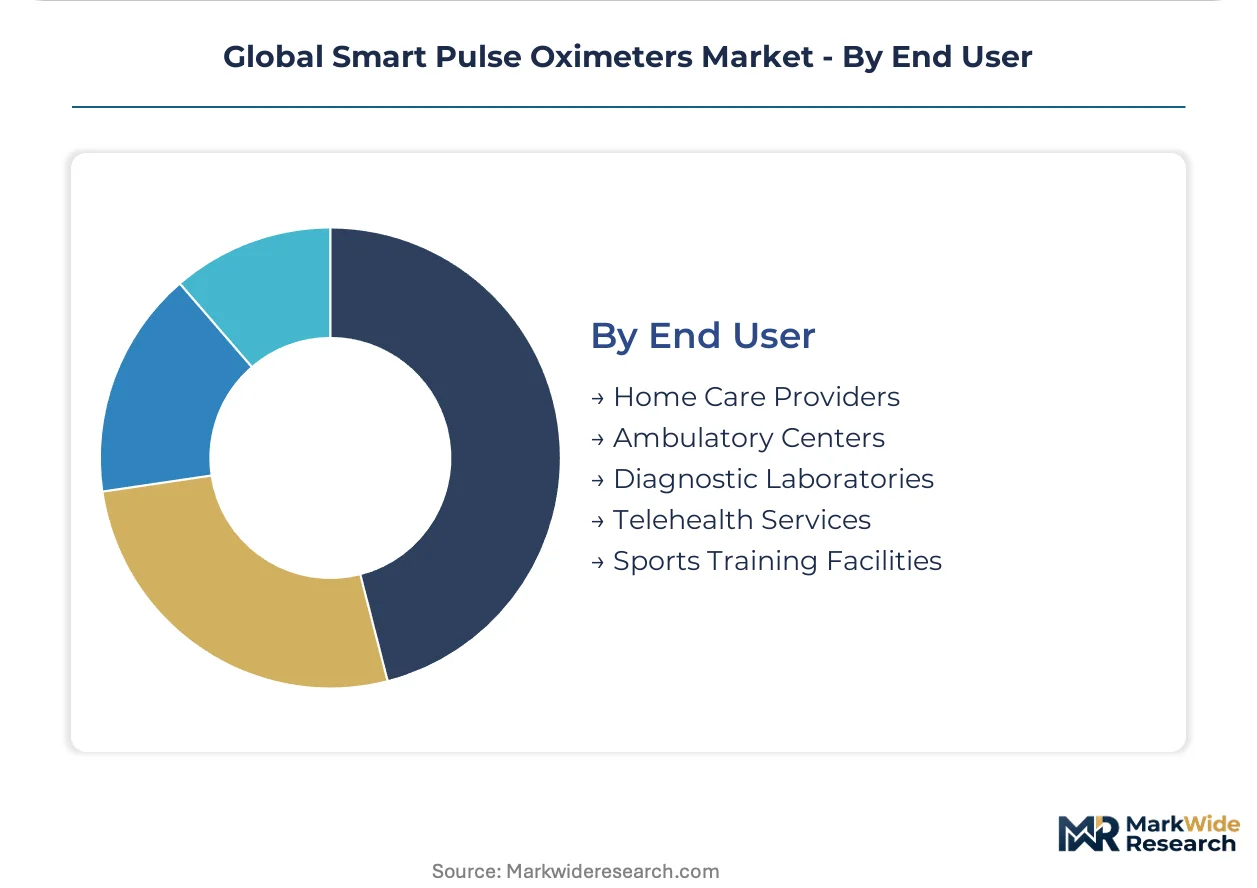
End User:
Supply concentration in sensor substrates and calibration expertise shapes which end user segments legacy manufacturers can serve profitably.
- Home Care Providers:Large nursing networks standardize on interoperable fleets to reduce training overhead across distributed staff. India's CDSCO data localization requirements for cross-border health transmission favor domestic platform partnerships.
- Telehealth Services:Virtual care platforms require HL7 FHIR connectivity for electronic health record integration, stretching thinly capitalized entrants with middleware development costs.
- Ambulatory Centers:High-throughput outpatient settings prioritize rapid measurement speed and disposable probe economics.
- Diagnostic Laboratories:ISO 80601-2-61 calibration documentation requirements concentrate procurement among legacy hospital device service organizations.
- Sports Training Facilities:Performance coaching applications tolerate lower accuracy tolerances in exchange for multi-parameter biosensor fusion.
Home care providers represent the deepest installed base. Telehealth services show the steepest expansion trajectory as virtual care reimbursement stabilizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States show low price elasticity for connected diagnostic platforms with predictive algorithms, while India's home care market remains acutely sensitive to hardware unit costs. China's regulatory data localization requirements create artificial cost premiums for foreign platform entrants.
United States
Hospital-at-home networks in Texas and Florida are standardizing interoperable pulse oximeter fleets to reduce nursing training overhead across distributed staff. FDA 510(k) clearance timelines for predicate photoplethysmography devices have compressed to under 90 days for iterative hardware improvements. The Boston medical device cluster hosts specialized calibration service organizations that maintain ISO 80601-2-61 phantom testing capabilities.
Germany
Statutory health insurers in Bavaria and North Rhine-Westphalia now reimburse connected diagnostic platforms for COPD surveillance under disease management contracts. EU MDR conformity assessment timelines for Class IIa devices have extended to 14 months, freezing product pipeline velocity for entrants lacking notified body relationships. The Munich pulmonology network concentration drives wrist-worn device procurement for sleep apnea screening workflows.
China
NMPA data localization mandates for cross-border health transmission favor domestic cloud infrastructure partnerships over direct foreign market entry. The Yangtze River Delta manufacturing belt concentrates indium gallium arsenide photodiode foundry capacity, exposing manufacturers to input cost volatility. Shanghai-based telehealth platforms are integrating pulse oximetry into chronic disease management contracts with municipal health bureaus.
India
CDSCO oversight of consumer-grade monitoring devices is tightening cross-border health data transmission requirements for home care kit distributors. Maharashtra's nursing network consolidation is driving demand for low-cost fingertip units with minimal training requirements. The Bangalore diagnostic laboratory cluster maintains ISO 80601-2-61 calibration documentation that concentrates procurement among legacy hospital device service organizations.
Japan
PMDA post-market surveillance requirements are mandating systematic collection of real-world performance data from deployed connected devices. The Kanto region's cardiology outpatient clinics are piloting reflectance-mode wrist sensors for 24-hour ambulatory monitoring where finger probe compliance fails. METI standards for multi-parameter biosensor fusion are accelerating algorithmic signal processing differentiation over optical hardware performance.
Global Smart Pulse Oximeters Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated platform providers commanding premium positioning while hardware-specialist manufacturers compete on unit economics. The market structure reflects a bifurcation between hospital-grade signal processing heritage and consumer electronics scale. Three archetypes dominate: clinical-grade platform vendors with cloud-connected fleets, consumer wellness brands with sleep and respiratory adjacencies, and contract manufacturers serving private-label pharmacy retail. Dominant competitive moves include backward integration into cardiac care ecosystems and strategic partnerships with domestic cloud infrastructure providers in regulated Asian markets.
Within the clinical-grade platform tier, Masimo Corporation and Medtronic plc exemplify divergent strategic positions. Masimo leverages its hospital-grade signal processing heritage to anchor clinical channel dominance. Medtronic occupies a position defined by backward integration into cardiac care ecosystems. Koninklijke Philips N.V. represents the consumer wellness convergence archetype, extending reach through sleep and respiratory product adjacencies that collapse the boundary between consumer and clinical-grade monitoring.
| Leading Market Players |
|---|
| Masimo Corporation |
| Medtronic plc |
| Koninklijke Philips N.V. |
| Nonin Medical, Inc. |
| Nihon Kohden Corporation |
| GE Healthcare |
| Contec Medical Systems Co., Ltd. |
| Smiths Medical |
| Omron Corporation |
| Others |
Supply & Pricing Matrix
Foundry-scale economies in indium gallium arsenide photodiode fabrication anchor cost floors across all device tiers, concentrating optical sensor production in East Asian manufacturing belts while pricing power accumulates with platform vendors who bundle predictive algorithms into recurring subscriptions.
Pricing Analysis
Algorithm licensing and cloud infrastructure subscriptions now drive lifetime value beyond hardware margins. Three-tier pricing structure across premium clinical-grade, standard connected, and economy standalone levels separates FDA-cleared platforms from consumer wellness devices. Pricing pressure stems from smartwatch SpO2 bundling at marginal hardware cost. Home care providers in India exhibit acute price sensitivity, while German statutory health insurers tolerate premium positioning for disease management contracts.
Supply Chain Analysis
Strait of Malacca transit underwrites photodiode substrate delivery schedules for manufacturers dependent on Taiwanese, South Korean, and Chinese foundry output. Optical-grade LED arrays and Bluetooth connectivity modules draw from Shenzhen and Seoul component ecosystems. Single-source vulnerability concentrates in near-infrared sensor substrate fabrication. Distribution runs through hospital procurement committees, pharmacy retail chains, and direct-to-consumer telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening as reimbursement code maturation splinters procurement authority between health system CIOs, pulmonology network administrators, and home care logistics managers.
For Market Incumbents: Shield clinical channel dominance by deepening backward integration into cardiac care ecosystems and accelerating ISO 80601-2-61 calibration service acquisitions. Smartwatch SpO2 substitution threatens standalone device volumes, demanding defensive algorithm bundling.
For New Entrants and Emerging Players: FDA 510(k) predicate pathway compression creates fast-track opportunity for photoplethysmography algorithm licensors. White-space concentrates in China's NMPA data localization compliance layer and India's CDSCO-registered home care kit distribution. Telehealth middleware partnerships offer lowest-friction go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform vendors with cloud-connected fleets and hospital system EHR integration. Five-to-ten year viability favors acquisition targets with established notified body relationships and algorithmic signal processing IP. Watch EU MDR post-market surveillance cost burdens as margin compression signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Pathway | Streamlined clearance accelerates iterative sensor improvements for established photoplethysmography algorithms. |
| CE Marking Pathway | EU MDR conformity assessment timelines extend procurement advantage to notified body incumbents. |
| Hospital System Partnership | Interoperable fleet standardization reduces training overhead across United States hospital-at-home networks. |
| Software Companion Development | HL7 FHIR middleware captures unbundled analytics licensing revenue from hardware commoditization. |
| Reimbursement Strategy | CPT code maturation for remote patient monitoring consolidates demand around connected diagnostic platforms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and telehealth platform operators; and secondary validation against FDA 510(k) filings, EU MDR notified body databases, CMS Medicare reimbursement schedules, and hospital procurement RFP archives. Bottom-up unit economics triangulated against top-down health system spending patterns.
Across the analysis window, forecasts modeled product type, connectivity protocol, clinical application, and end-user procurement channel dimensions. CAGRs derived from installed base replacement cycles and reimbursement code expansion trajectories. Photoplethysmography algorithm patent filings and NMPA data localization compliance costs fed industry-specific adjustments.
Underlying assumptions cover regulatory clearance timelines, reimbursement code stability, and sensor substrate supply continuity, with deviation risk concentrated in EU MDR post-market surveillance cost inflation and smartwatch SpO2 accuracy improvements. Practitioners should keep alternative scenarios live as FDA software-as-medical-device guidance and China's cross-border data rules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Bedside Monitors Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Respiration Monitor Belt Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
South America Respiratory Monitoring Market
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
Remote Home Monitoring Systems Market
Patient Monitoring
United States Cardiac Holter Monitor Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Patient Monitoring Devices Market
Patient Monitoring
Patient Monitoring Pods Market