
 Health Sensors Market | 2026-2036
Health Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Health Sensors Market Intelligence
South Korea's semiconductor foundry expansion is reshaping supply security for biosensor chipsets. Medtronic leverages its vertically integrated manufacturing footprint to control glucose sensor output. Abbott Laboratories anchors North American continuous monitoring through extensive ambulatory care partnerships. Siemens Healthineers competes on imaging-to-sensor workflow integration across integrated delivery networks.
Health sensors are electromechanical or biochemical transducers that convert physiological signals into quantifiable electrical or optical outputs, typically operating within precision ranges of microvolts to millivolts for bioelectronic variants or nanometer-scale optical path lengths for photonic devices, serving to enable real-time diagnostic feedback and longitudinal patient data collection. Wearable sensors dominate volume shipments due to consumer familiarity and retail channel penetration, while implantable sensors command premium positioning through extended functional lifetimes and direct tissue interfacing. Optical technology leads glucose and heart rate applications with non-invasive convenience, whereas bioelectronic platforms sustain higher average selling prices in critical care settings where signal fidelity determines clinical decision quality.
The FDA governs premarket submission pathways and software validation requirements for connected health sensors in the United States, while ISO 13485 and IEC 60601 shape international quality management and electrical safety baselines that manufacturers must satisfy for multi-jurisdiction market access. The EU MDR imposes stricter clinical evidence thresholds on invasive and implantable sensor classes, extending certification timelines and concentrating compliance investment among established players. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring as payer decisions will determine which sensor modalities achieve sustainable commercial scale.
Market Dynamics
The FDA's software-as-a-medical-device guidance is compressing clearance timelines for connected biosensors while South Korean foundry expansion redraws chipset supply geography. Hospital procurement consolidation across integrated delivery networks now favors vendors with captive manufacturing and multi-parameter platform portfolios.
Growth Catalysts
- Remote Therapeutic Monitoring Reimbursement:Medicare coverage expansion for continuous glucose and cardiac monitoring creates sustainable revenue streams for ambulatory sensor deployments. Physician practices accelerate platform adoption to capture new billing codes.
- Semiconductor Foundry Diversification:South Korea's biosensor-dedicated wafer capacity expansion reduces single-source dependency for MEMS and photonic chipsets. Foundry competition improves contract manufacturer bargaining power for mid-tier sensor developers.
- Optical Glucose Sensing Maturation:Non-invasive photonic platforms approach clinical-grade accuracy thresholds. Retail pharmacy chains prepare shelf space for consumer-grade continuous metabolic monitors.
Market Restraints
- EU MDR Clinical Evidence Burden:Stricter premarket documentation requirements for implantable sensor classes extend certification timelines by 18-24 months. Smaller manufacturers face capital constraints for expanded clinical trials.
- Precious Metal Input Volatility:Platinum and iridium electrode materials for bioelectronic sensors experience price swings tied to automotive catalyst demand. Formulation engineers seek conductive polymer substitutes.
- Single-Source Photodetector Concentration:High-sensitivity avalanche photodiodes for optical glucose sensing rely on three dominant Japanese suppliers. Geopolitical friction threatens just-in-time delivery for North American device assemblers.
Strategic Opportunities
- India Preventive Health Mandates:Ayushman Bharat digital health mission drives demand for low-cost wearable vitals monitors in tier-2 and tier-3 cities. Local manufacturing incentives under PLI schemes attract contract assembly investment.
- AI-Edge Sensor Fusion:On-device machine learning inference enables real-time arrhythmia detection without cloud latency. Cardiology clinics prioritize platforms with embedded neural processing units.
- Direct-to-Employer Contracts:Self-insured corporations bypass traditional distribution to procure continuous monitoring fleets for workforce wellness programs. Occupational health vendors build subscription revenue models.
Industry Challenges
- Multi-Jurisdiction Quality Management:Simultaneous FDA 21 CFR Part 820, EU MDR, and ISO 13485 compliance demands dedicated regulatory affairs teams exceeding 15 FTEs for mid-cap manufacturers.
- Legacy Hospital IT Integration:Epic and Cerner electronic health record interoperability requires proprietary API development. Sensor vendors absorb 6-9 month deployment delays for health system pilot programs.
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity and sensitization studies face 4-6 month queue times at accredited laboratories. Implantable sensor roadmaps stall awaiting final material qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health Sensors Market |
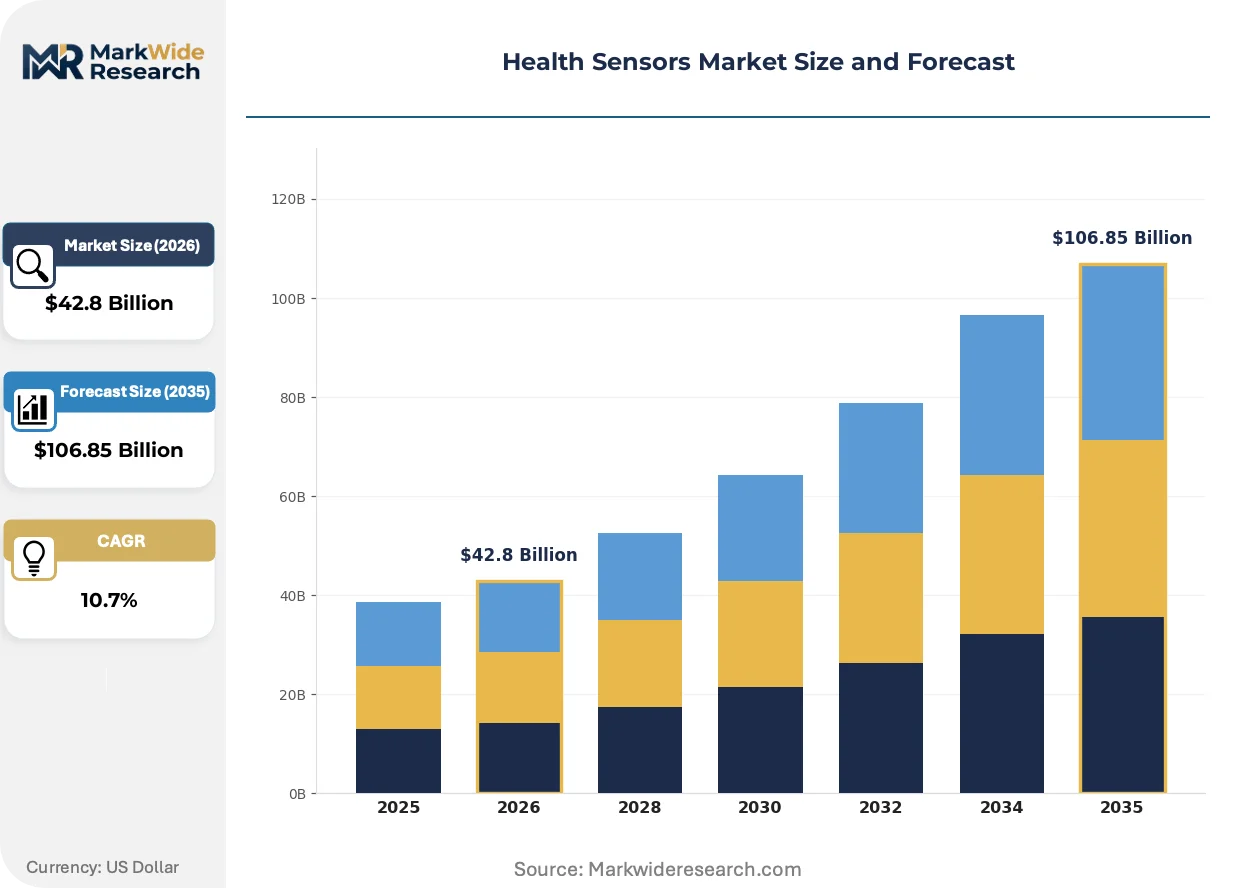
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $106.85 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Implantable Sensors, Invasive Sensors, Non-Invasive Sensors End User: Patients, Hospitals, Clinics, Research Institutions Technology: Bioelectronic, Optical, Ultrasound, Chemical Application: Heart Rate Monitoring, Glucose Monitoring, Blood Pressure Monitoring, Respiration Rate Monitoring |
| Companies Covered | Honeywell International, Philips Healthcare, Medtronic, Johnson & Johnson, Siemens Healthineers, Abbott Laboratories, TE Connectivity, Dexcom, GE Healthcare Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health Sensors Market Strategic Shifts & Innovations
Photonic sensing architectures and edge AI inference are converging to enable real-time physiological monitoring without cloud dependency. Regulatory frameworks are adapting to software-defined medical devices faster than hardware certification paradigms.
Silicon photonics is collapsing the cost structure for optical biosensors by integrating laser sources, waveguides, and detectors onto single CMOS dies. Medtronic and Abbott Laboratories are transitioning glucose monitoring prototypes from discrete optoelectronic assemblies to monolithic photonic chips. This integration is collapsing the price premium between consumer wellness trackers and clinical-grade continuous monitors.
The EU MDR's software classification guidance now explicitly addresses machine learning-enabled diagnostic sensors, requiring locked algorithm versions for each device submission. Manufacturers must freeze model weights and document training data provenance before CE marking. Class IIa and IIb sensor developers are responding by segmenting product lines into locked-algorithm clinical devices and continuously learning wellness peripherals sold outside medical device jurisdiction.
Hospital procurement committees now mandate interoperability certification with specific electronic health record platforms before vendor qualification. Integrated delivery networks in Texas and Florida are consolidating sensor purchasing through single-source agreements covering glucose, cardiac, and pulse oximetry modalities. This concentration is displacing independent device vendors who lack Epic or Cerner pre-certification, forcing mid-tier manufacturers into partnership or exit decisions.
Health Sensors Market Segmentation
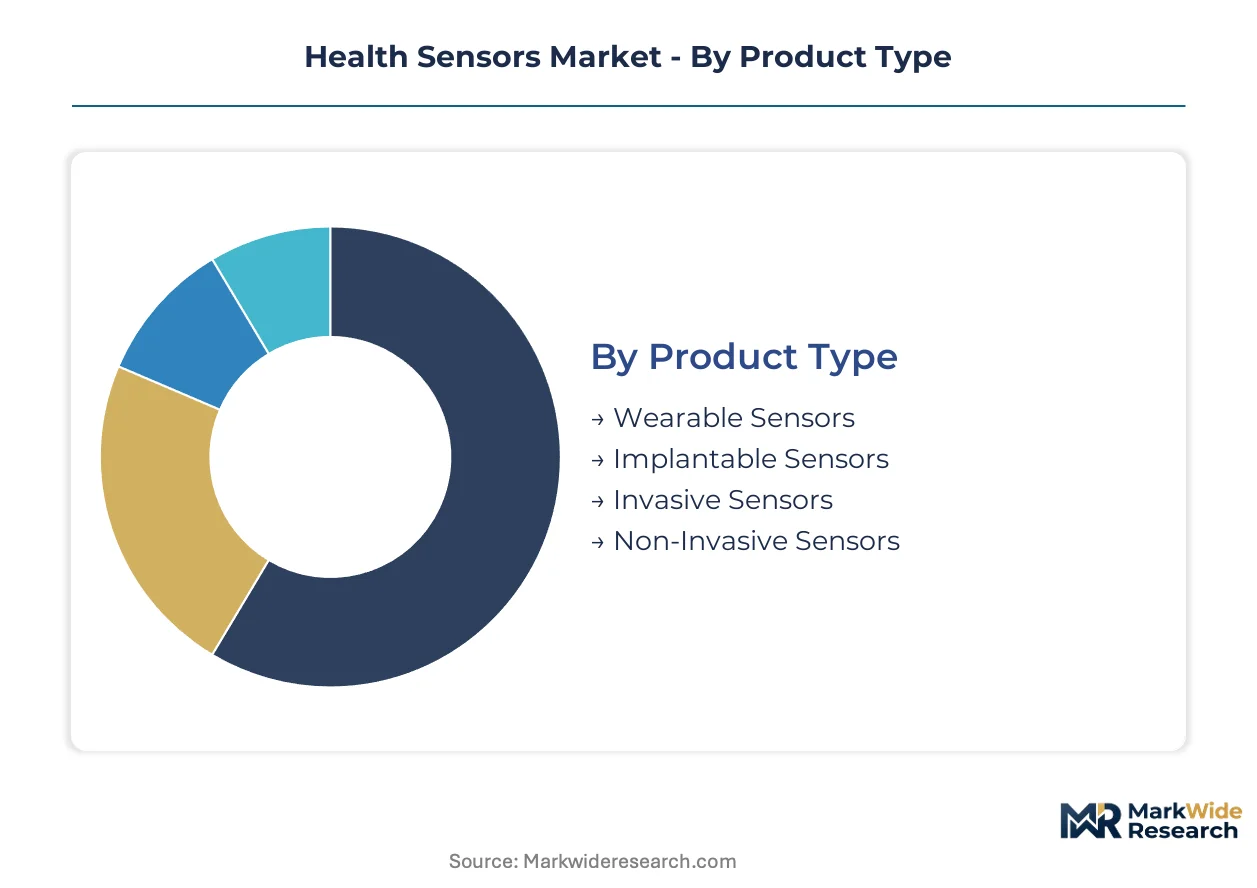
Health sensors fragment across four distinct category axes, each with unique service intensity requirements and margin structures. Product type determines calibration frequency and regulatory burden. Technology choice dictates semiconductor foundry relationships and optical component sourcing strategies.
Product Type:
After-sales service intensity varies dramatically across implantable versus wearable form factors, with calibration protocols and battery replacement cycles driving lifetime value calculations.
- Wearable Sensors:Electromechanical transducers packaged in wrist-worn or patch formats with 12-18 month functional lifespans. Demand concentrates in United States retail pharmacy chains where Medicare Advantage plans subsidize continuous glucose monitors for prediabetic populations.
- Implantable Sensors:Biocompatible devices requiring ISO 10993-5 cytotoxicity certification and hermetic sealing against bodily fluids. German cath labs and French cardiac surgery centers drive procurement for implantable loop recorders with 3-5 year battery endurance.
- Invasive Sensors:Catheter-mounted or needle-embedded transducers for acute care settings. Japanese university hospitals favor these for ICU hemodynamic monitoring where signal fidelity trumps patient discomfort.
- Non-Invasive Sensors:Photoplethysmography and impedance-based platforms leveraging consumer familiarity. Indian preventive health mandates under Ayushman Bharat accelerate low-cost pulse oximetry deployment in tier-2 cities.
Wearable sensors hold the largest share; momentum sits with implantable sensors.
End User:
Cost tier stratification separates enterprise procurement committees from individual purchase decisions, with hospitals commanding volume discounts unavailable to direct consumers.
- Patients:Direct purchasers through retail channels or pharmacy benefit managers. United States consumers drive subscription revenue for continuous glucose monitoring platforms with smartphone-integrated dashboards.
- Hospitals:Integrated delivery networks in Texas and Florida consolidate sensor purchasing through single-source agreements. Epic and Cerner interoperability certification gates vendor qualification.
- Clinics:Physician practices capturing remote therapeutic monitoring reimbursement codes. Medicare coverage expansion for cardiac and glucose monitoring accelerates platform adoption.
- Research Institutions:Academic medical centers and contract research organizations. South Korean semiconductor foundries prioritize these buyers for biosensor chipset prototyping volumes.
Hospitals hold the largest share; momentum sits with clinics.
Technology:
Application specificity determines whether bioelectronic precision or optical convenience wins procurement decisions, with critical care settings sustaining premium pricing for signal fidelity.
- Bioelectronic:Microvolt-precision transducers employing precious metal electrodes for electrophysiological signal capture. Platinum and iridium price volatility tied to automotive catalyst demand pressures formulation engineers toward conductive polymer substitutes.
- Optical:Photonic platforms integrating laser sources, waveguides, and detectors onto single CMOS dies. Silicon photonics collapses cost structures for non-invasive glucose and heart rate applications.
- Ultrasound:Piezoelectric transducers for deep tissue imaging and blood flow monitoring. German and Japanese imaging equipment manufacturers dominate transducer manufacturing.
- Chemical:Enzymatic and electrochemical sensors for metabolite detection. FDA software-as-a-medical-device guidance compresses clearance timelines for connected chemical biosensors.
Optical technology holds the largest share; bioelectronic platforms climb the fastest.
Application:
Customer type segmentation separates chronic disease management from acute episode monitoring, with reimbursement codes determining sustainable commercial scale per modality.
- Heart Rate Monitoring:Photoplethysmography and electrocardiographic methods spanning consumer wellness to clinical-grade arrhythmia detection. AI-edge sensor fusion enables real-time atrial fibrillation identification without cloud latency.
- Glucose Monitoring:Enzymatic amperometric and emerging photonic non-invasive approaches. Optical glucose sensing approaches clinical-grade accuracy thresholds as retail pharmacy chains prepare shelf space.
- Blood Pressure Monitoring:Oscillometric cuff-based and emerging cuffless photoplethysmography methods. Direct-to-employer contracts for workforce wellness programs bypass traditional distribution channels.
- Respiration Rate Monitoring:Impedance pneumography and accelerometer-derived methods. ICU settings in United States integrated delivery networks drive demand for continuous respiratory monitoring post-extubation.
Glucose monitoring holds the largest share; heart rate monitoring gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean foundry capacity expansion and United States hospital procurement consolidation are redrawing supply geography for biosensor chipsets. German precision engineering clusters and Japanese photodetector suppliers anchor component-tier output. Indian preventive health mandates and Chinese CMOS photonics scaling complete the regional map.
United States
Integrated delivery networks in Texas and Florida consolidate sensor purchasing through single-source agreements covering glucose, cardiac, and pulse oximetry modalities. FDA software-as-a-medical-device guidance compresses clearance timelines for connected biosensors. The Greater Boston cluster hosts academic medical centers driving AI-edge sensor fusion prototyping for arrhythmia detection.
Germany
Cath labs and cardiac surgery centers in Bavaria and Baden-Württemberg drive procurement for implantable loop recorders with extended battery endurance. EU MDR imposes stricter clinical evidence thresholds on invasive sensor classes, extending certification timelines. The Stuttgart precision engineering corridor supplies hermetic sealing technologies for implantable device manufacturers.
Japan
University hospitals in Tokyo and Osaka favor invasive catheter-mounted sensors for ICU hemodynamic monitoring where signal fidelity dominates procurement decisions. PMDA oversees premarket approval pathways for high-risk device classes. Three dominant suppliers in the Nagoya industrial corridor control high-sensitivity avalanche photodiode output for optical glucose sensing platforms.
South Korea
Biosensor-dedicated wafer capacity expansion in the Seoul Capital Area reduces single-source dependency for MEMS and photonic chipsets. MFDS regulates software-enabled medical devices under harmonized international standards. Samsung and SK Hynix foundry competition improves contract manufacturer bargaining power for mid-tier sensor developers seeking second-source security.
India
Ayushman Bharat digital health mission drives demand for low-cost wearable vitals monitors in tier-2 and tier-3 cities beyond metropolitan hospital networks. CDSCO oversees medical device registration under streamlined 2017 rules. Karnataka and Tamil Nadu manufacturing incentives under PLI schemes attract contract assembly investment for pulse oximetry and basic cardiac monitoring devices.
Health Sensors Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in MEMS, photonics, and electrode materials. The vendor base separates into three strategic archetypes: diversified health conglomerates with captive manufacturing, pure-play sensor developers dependent on foundry partnerships, and industrial sensor suppliers crossing over from aerospace or automotive applications. M&A activity concentrates on optical glucose sensing startups and AI-edge inference chip designers. Vertical integration into semiconductor foundry relationships represents the dominant defensive maneuver.
Within the diversified health technology tier, Medtronic and Abbott Laboratories exemplify platform integrators with vertically controlled supply chains. Dexcom occupies a position among pure-play continuous monitoring specialists dependent on external foundry capacity. Siemens Healthineers sits within the imaging-to-sensor workflow integration segment, bridging diagnostic equipment and point-of-care monitoring.
| Leading Market Players |
|---|
| Honeywell International |
| Philips Healthcare |
| Medtronic |
| Johnson & Johnson |
| Siemens Healthineers |
| Abbott Laboratories |
| TE Connectivity |
| Dexcom |
| GE Healthcare Technologies |
| Others |
Cost & Logistics Intelligence
The Incheon-Busan freight corridor's container cost dynamics compress margins for biosensor chipsets entering United States distribution channels, concentrating pricing power among foundries with captive wafer capacity while forcing downstream device assemblers into tiered certification-based price differentiation.
Pricing Analysis
FDA 21 CFR Part 820 quality system regulation dictates the pricing tier structure across implantable, wearable, and consumer wellness sensor categories. Three-tier pricing structure across premium clinical-grade, standard hospital-approved, and economy direct-to-consumer levels separates ISO 13485-certified devices from wellness peripherals. Pricing pressure stems from South Korean foundry competition improving contract manufacturer bargaining power for mid-tier developers. Hospital procurement committees exhibit lowest price sensitivity due to bundled reimbursement capture, while direct consumers face highest sensitivity driving subscription model adoption.
Supply Chain Analysis
Samsung and SK Hynix foundries in South Korea, alongside TSMC-contracted capacity in Taiwan and legacy MEMS production in Germany, anchor contract manufacturing concentration for photonic and bioelectronic chipsets. Platinum and iridium electrode materials for bioelectronic sensors, high-sensitivity avalanche photodiodes from Japanese suppliers, and biocompatible polymers for implantable housings constitute critical input dependencies. Single-source photodetector concentration in the Nagoya industrial corridor presents tariff-exposed vulnerability for North American optical glucose device assemblers. Distribution runs through integrated delivery network procurement committees, retail pharmacy chains, and direct-to-employer occupational health contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health sensors sit in early-cycle expansion as Medicare remote therapeutic monitoring reimbursement codes unlock sustainable ambulatory revenue streams for continuous glucose and cardiac monitoring platforms.
For Market Incumbents: Insulate platform positions by deepening backward integration into Seoul Capital Area foundry partnerships for MEMS and photonic chipset security, while accelerating FDA software-as-a-medical-device pre-certification to compress clearance timelines against emerging optical glucose entrants. Captive manufacturing and locked-algorithm clinical device segmentation represent critical defensive levers against pure-play sensor developers.
For New Entrants and Emerging Players: Build out AI-edge inference capabilities for real-time arrhythmia detection targeting cardiology clinics prioritizing on-device processing without cloud latency, while exploiting India Ayushman Bharat tier-2 city preventive health mandates through low-cost pulse oximetry contract assembly under PLI manufacturing incentives. Direct-to-employer workforce wellness subscription models offer the most penetrable go-to-market angle bypassing traditional hospital procurement gatekeeping.
For Investors and Strategic Acquirers: Optical glucose sensing startups with silicon photonics integration roadmaps present priority acquisition archetypes as retail pharmacy chains prepare shelf space for consumer-grade continuous metabolic monitors. Long-term viability hinges on reimbursement code expansion sustainability and optical accuracy threshold achievement. Watch FDA software classification guidance evolution for machine learning-enabled diagnostic sensors as the inflection signal determining locked-algorithm clinical device versus wellness peripheral market boundary shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Pre-Certification | Compresses clearance timelines for connected biosensors against EU MDR's extended certification pathways. |
| Seoul Capital Area Foundry Partnership | Secures second-source MEMS and photonic chipset capacity reducing single-source dependency risks. |
| Epic and Cerner Interoperability Certification | Gates vendor qualification for Texas and Florida integrated delivery network procurement consolidation. |
| Locked-Algorithm Clinical Device Segmentation | Navigates EU MDR software classification requirements while preserving wellness peripheral upgrade flexibility. |
| Direct-to-Employer Occupational Health Contract | Bypasses traditional distribution channels for workforce wellness continuous monitoring fleet deployment. |
Research Approach
The analysis maps wearable, implantable, invasive, and non-invasive sensor sub-sectors, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads at diversified health conglomerates. Primary interview insights triangulate against FDA 510(k) and PMA filings, CMS Medicare reimbursement code databases, hospital procurement contract repositories, and ISO 13485 certification registries. Bottom-up shipment modeling and top-down healthcare expenditure allocation converge through iterative stakeholder validation.
Assumptions hold reimbursement code expansion continuity, foundry capacity commissioning timelines, and optical glucose accuracy maturation trajectories within observed patterns across the analysis window. Segmentation dimensions span product type, technology platform, application, and end-user archetype with geographic regulatory cluster overlays. CAGRs derive from installed base growth, replacement cycle compression, and penetration rate trajectories calibrated against Medicare claims data and health system pilot program disclosures.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pure-play continuous monitoring specialists or silicon photonics startups would shift outcomes through accelerated price erosion or premature optical glucose platform launches. Quarterly review of FDA software guidance updates, South Korean foundry utilization rates, and Epic-Cerner interoperability certification backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
Global Non-Invasive Monitoring Device Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
Respiratory Monitoring Market
Patient Monitoring
IoT in Healthcare Market