
 Hospital Resource Management Market | 2026-2036
Hospital Resource Management Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Resource Management Market Foresight
Acute care networks is bifurcating demand away from standalone community hospitals as integrated delivery systems prioritize enterprise-wide resource visibility. Epic Systems Corporation leverages its dominance in electronic health records to extend into bed management and capacity planning workflows. Cerner Corporation anchors its position through cloud-based command center architectures that unify operational data across multi-site networks. GE Healthcare competes on real-time location system integration, pairing asset tracking with predictive maintenance analytics for high-value mobile equipment.
Hospital resource management encompasses the digital coordination of personnel, equipment, and facility capacity through software platforms that integrate real-time data streams from admission systems, electronic health records, and IoT-enabled devices to optimize throughput and reduce operational waste. Cloud-based solutions lead deployment preference as health systems migrate away from on-premise infrastructure to reduce capital expenditure and enable remote access for distributed clinical teams; IoT integration represents the fastest-expanding technology segment, with RFID and Bluetooth Low Energy tags now tracking infusion pumps, wheelchairs, and portable imaging equipment across enterprise footprints. Staffing solutions command concentrated margin pools due to persistent clinical labor shortages and the complexity of union scheduling rules, credential verification, and float-pool orchestration.
The FDA's interoperability mandates under the 21st Century Cures Act compel vendors to standardize APIs and data exchange protocols, reshaping product development roadmaps and creating compliance barriers for legacy systems. HIPAA security requirements govern cloud deployments, with business associate agreements now scrutinizing subprocessor networks and encryption standards for protected health information in operational analytics. Stakeholders must monitor how CMS value-based payment models reshape resource management priorities, as shared savings contracts tie reimbursement directly to length-of-stay reduction and emergency department throughput metrics.
Market Dynamics
Hospital consolidation into integrated delivery networks is compressing procurement cycles and demanding enterprise-grade visibility across bed capacity, staff scheduling, and mobile asset location.
Growth Catalysts
- Interoperability mandates:The FDA's 21st Century Cures Act forces API standardization, compelling legacy system upgrades and opening procurement for cloud-native platforms.
- Ambulatory Surgery Centers:These facilities are adopting resource optimization tools to manage same-day discharge workflows and equipment turnover.
- IoT sensor networks:RFID and Bluetooth Low Energy tags on infusion pumps and wheelchairs generate real-time location data that feeds predictive analytics engines.
Market Restraints
- Legacy infrastructure debt:On-premise EHR architectures in community hospitals resist cloud migration due to sunk capital and staff retraining costs.
- Clinical labor scarcity:Persistent shortages of nurses and specialized technicians inflate staffing solution prices and extend implementation timelines.
- HIPAA compliance friction:Business associate agreements scrutinize subprocessor networks and encryption standards, slowing vendor onboarding.
Strategic Opportunities
- Predictive maintenance convergence:Real-time location systems paired with equipment utilization analytics create bundled offerings for high-value mobile imaging.
- Value-based care alignment:CMS shared savings contracts tie reimbursement to length-of-stay reduction, creating budget authority for throughput optimization.
- Float-pool orchestration:Union scheduling rules and credential verification complexity create premium-margin niches for staffing optimization software.
Industry Challenges
- Integration complexity:Bed management platforms must reconcile admission data from disparate EHR instances across merged health systems.
- Credential verification bottlenecks:Multi-state licensing and privileging delays constrain staff deployment flexibility during demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Resource Management Market |
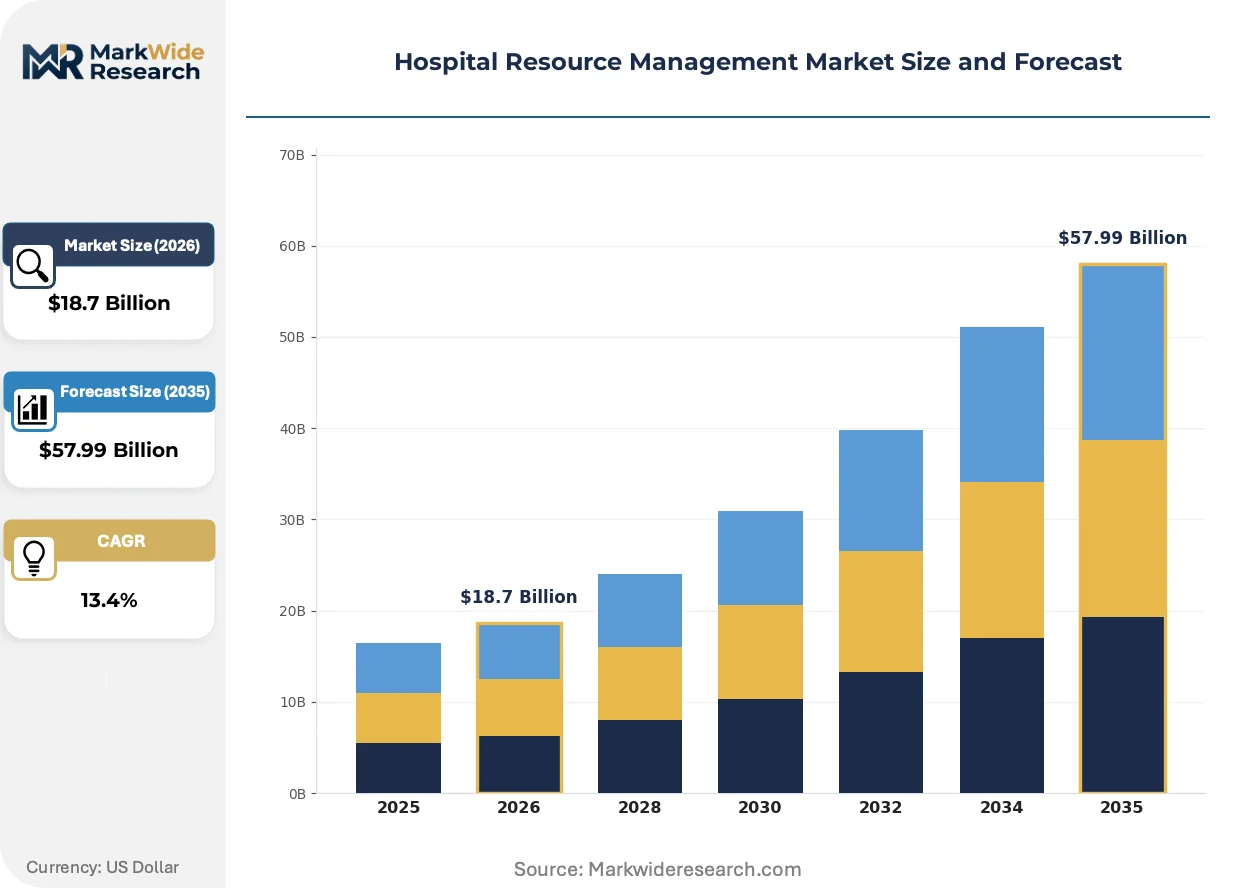
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inventory Management, Staffing Solutions, Scheduling Software, Asset Tracking End User: Healthcare Providers, Emergency Services, Rehabilitation Centers, Ambulatory Surgery Centers Technology: Cloud-Based Solutions, On-Premise Solutions, Mobile Applications, IoT Integration Application: Patient Flow Management, Resource Allocation, Staff Utilization, Emergency Preparedness |
| Companies Covered | Epic Systems Corporation, GE Healthcare, Cerner Corporation, Oracle Health, Philips Healthcare, Allscripts Healthcare Solutions, Siemens Healthineers, McKesson Corporation, TeleTracking Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Resource Management Market Shifts & Advancements
Digital infrastructure in hospital operations is pivoting from retrospective reporting to predictive orchestration, with real-time data streams now driving minute-by-minute resource allocation decisions.
Edge computing architectures are fragmenting centralized analytics into distributed processing nodes. These systems execute bed turnover predictions and staff reallocation algorithms locally, reducing latency for time-critical workflows. Acute care networks are deploying edge nodes at individual hospital sites within integrated delivery systems, compressing the competitive advantage of single-vendor cloud monoliths.
The FDA's interoperability mandates under the 21st Century Cures Act are reshaping vendor development roadmaps. Standardized APIs and data exchange protocols now govern product certification, creating compliance barriers for closed systems. Cloud-native platforms with pre-built FHIR connectors capture procurement preference from health systems facing 2024 enforcement deadlines.
Command center purchasing is consolidating previously siloed budgets for bed management, asset tracking, and staffing optimization into single enterprise contracts. Health system CIOs now evaluate unified operational platforms rather than point solutions, displacing standalone vendors. This pattern concentrates in the United States, where hospital consolidation has created multi-site networks with centralized capital allocation authority.
Hospital Resource Management Market Segmentation
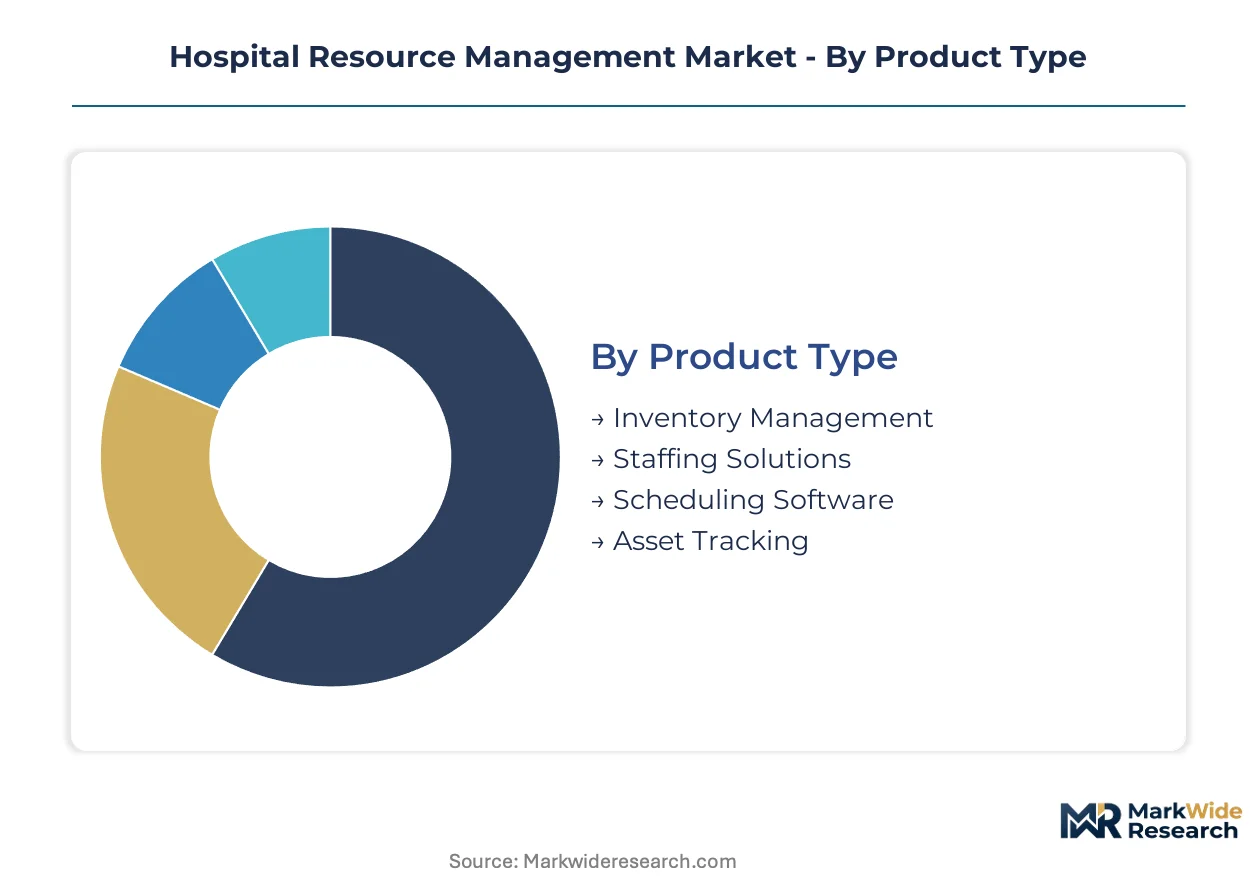
Hospital resource management platforms segment across operational workflows, enabling buyers to target specific inefficiencies rather than enterprise-wide replacement. Procurement patterns diverge sharply between systems prioritizing capital-intensive asset tracking and those addressing labor-intensive staffing optimization.
Product Type:
Inventory management and staffing solutions dominate domestic procurement in consolidated US health systems, while asset tracking commands premium pricing in export-led deployments across Middle Eastern and Asian hospital networks.
- Inventory Management:Automated replenishment systems integrate with supply chain ERPs to track consumable utilization against surgical schedules. Demand concentrates in multi-hospital IDNs seeking to reduce par-level waste across standardized formularies; FDA UDI compliance mandates accelerate barcode-enabled adoption.
- Staffing Solutions:Float-pool orchestration platforms reconcile union scheduling rules, credential verification, and acuity-based assignments. US acute care networks deploy these most aggressively where nurse vacancy rates exceed 15% and labor represents 55-60% of operating costs.
- Scheduling Software:OR block allocation modules optimize surgeon access while minimizing turnover delays.
- Asset Tracking:RTLS-enabled location services reduce equipment hoarding and rental dependency.
Staffing solutions hold the largest share; momentum sits with asset tracking as IoT sensor costs decline.
End User:
Healthcare providers absorb the majority of procurement volume through enterprise contracts, though ambulatory surgery centers represent the steepest expansion trajectory as same-day discharge protocols proliferate.
- Healthcare Providers:Integrated delivery networks deploy unified command centers spanning bed management, asset location, and staff deployment across 10+ hospital footprints. These buyers prioritize API standardization to reconcile Epic and Cerner instances following merger activity.
- Ambulatory Surgery Centers:Lean operational models drive adoption of turnkey scheduling and equipment turnover platforms. ASCs in Texas, Florida, and California lead procurement where case volume growth exceeds 8% annually and physical space constraints intensify.
- Emergency Services:Fire-based EMS agencies and hospital-affiliated ambulance fleets utilize dispatch optimization.
- Rehabilitation Centers:Skilled nursing facilities adopt therapy scheduling and durable medical equipment tracking.
Healthcare providers anchor procurement volume; ambulatory surgery centers are climbing the fastest.
Technology:
Deployment architecture determines capital structure and compliance burden, with cloud-native platforms capturing preference from buyers seeking to eliminate data center overhead.
- Cloud-Based Solutions:Multi-tenant SaaS architectures enable remote access for distributed clinical teams and accelerate vendor onboarding through pre-configured FHIR connectors. HIPAA business associate agreements now scrutinize subprocessor networks and encryption standards, creating compliance differentiation among vendors.
- IoT Integration:RFID and Bluetooth Low Energy tags on infusion pumps, wheelchairs, and portable imaging equipment generate real-time location feeds for predictive analytics engines. Sensor deployment concentrates in US academic medical centers with 500+ bed footprints and capital budgets for infrastructure overlay.
- On-Premise Solutions:Legacy architectures persist in community hospitals with sunk EHR infrastructure investments.
- Mobile Applications:Smartphone-based staff communication and bed status updates complement core platforms.
Cloud-based solutions hold the largest share; IoT integration is gaining share fastest.
Application:
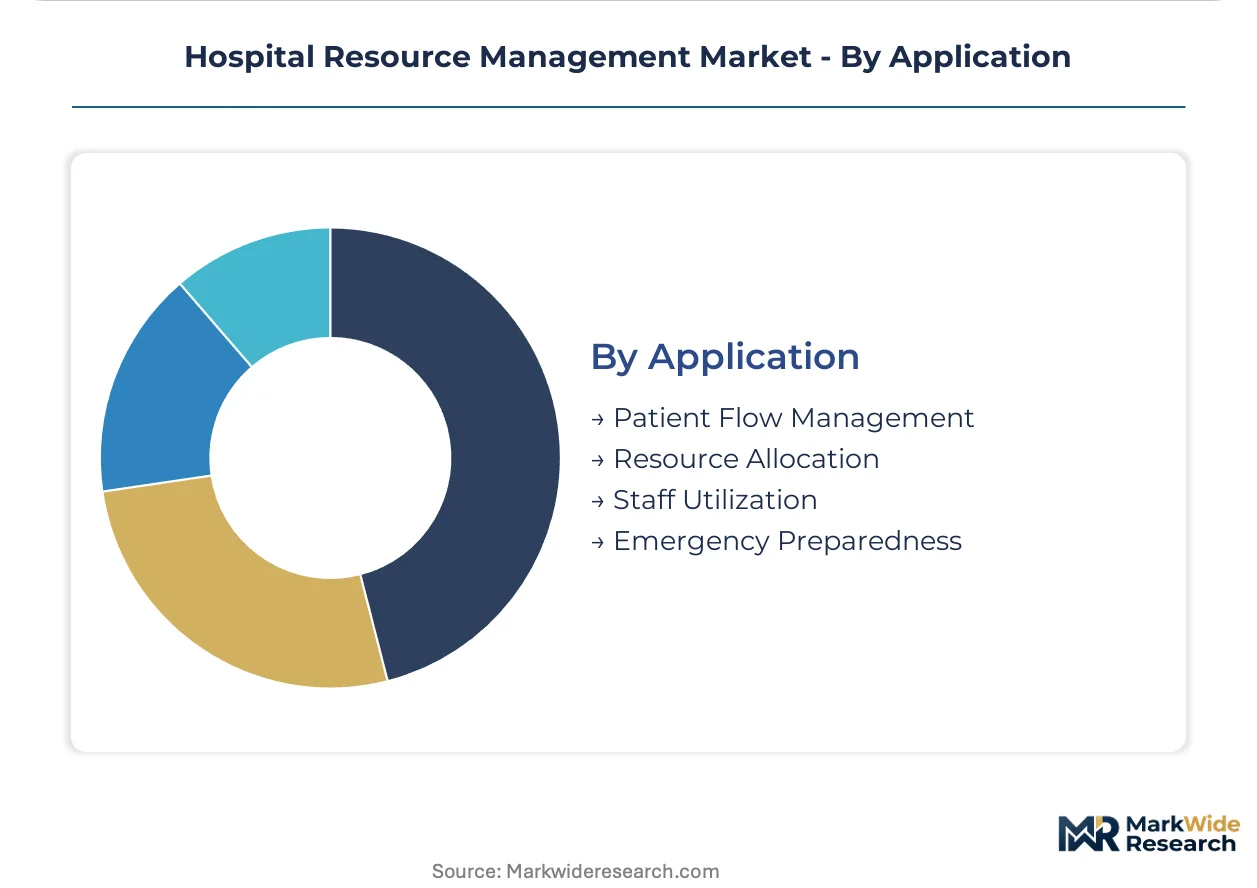
Functional priorities diverge by care setting, with throughput optimization dominating acute care while emergency preparedness commands dedicated budget lines in public hospital districts.
- Patient Flow Management:Bed turnover prediction algorithms integrate admission, discharge, and transfer data with environmental services capacity to compress length-of-stay. US health systems facing CMS shared savings contracts deploy these most intensively where reimbursement ties directly to throughput metrics.
- Resource Allocation:Dynamic distribution of equipment and personnel across units responds to real-time census and acuity shifts. Demand concentrates in California, New York, and Illinois where nurse staffing ratio mandates create rigid constraints requiring algorithmic optimization.
- Staff Utilization:Productivity analytics benchmark clinical labor deployment against case mix indices.
- Emergency Preparedness:Surge capacity planning and mass casualty response coordination tools serve public health mandates.
Patient flow management holds the largest share; resource allocation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains the dominant procurement position for hospital resource management platforms, underwritten by its dense network of integrated delivery networks and the CMS value-based payment infrastructure that ties reimbursement to operational metrics.
United States
Hospital consolidation into multi-site networks drives enterprise-scale deployments across bed management and staffing optimization. The FDA's 21st Century Cures Act interoperability mandates compel API standardization, reshaping vendor procurement criteria. Texas, Florida, and California concentrate ambulatory surgery center adoption where same-day discharge protocols proliferate.
Germany
Academic medical centers in Baden-Württemberg and Bavaria deploy real-time location systems for high-value mobile equipment tracking. The EU Medical Device Regulation (MDR) imposes conformity assessment requirements on connected health devices, filtering vendor eligibility. Berlin-Brandenburg clusters health IT procurement through university hospital networks.
United Kingdom
NHS England's operational performance targets accelerate patient flow management adoption across acute trusts. The UK Medicines and Healthcare products Regulatory Agency (MHRA) governs software as a medical device classifications, affecting platform certification pathways. London and the Southeast concentrate command center deployments within foundation trusts.
Japan
Metropolitan hospital networks in Tokyo and Osaka prioritize asset tracking for aging infrastructure and limited replacement capital. The Ministry of Economy, Trade and Industry (METI) promotes healthcare digitization through regulatory sandboxes for IoT integration. Kansai region academic centers pilot edge computing architectures for distributed analytics.
Australia
New South Wales and Victoria health districts consolidate operational technology budgets into unified command center contracts. The Therapeutic Goods Administration (TGA) regulates software-based medical devices, influencing vendor market access requirements. Melbourne's hospital networks lead staffing optimization procurement amid persistent nurse vacancy pressures.
Hospital Resource Management Market Competitive Landscape
Listed leaders compete with private specialists across platform architecture and deployment scale, with the market consolidating around three structural tiers. Tier-one vendors anchor enterprise contracts through electronic health record integration and cloud-native command centers. Tier-two specialists occupy niche workflows in asset tracking and staffing optimization. Tier-three regional providers serve community hospitals with limited capital budgets. Competitive dynamics center on strategic partnerships with health system consolidators and API certification for interoperability compliance.
Within the integrated platform tier, Epic Systems Corporation and Cerner Corporation exemplify EHR-anchored expansion into operational workflows. GE Healthcare occupies a position at the convergence of real-time location systems and predictive maintenance analytics. These three entities represent distinct strategic archetypes: clinical data platform extension, cloud-based operational unification, and industrial IoT healthcare application.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| GE Healthcare |
| Cerner Corporation |
| Oracle Health |
| Philips Healthcare |
| Allscripts Healthcare Solutions |
| Siemens Healthineers |
| McKesson Corporation |
| TeleTracking Technologies |
| Others |
Supply & Pricing Matrix
Cloud-native SaaS architectures replacing on-premise perpetual licenses simultaneously compress supply geography toward US-based hyperscaler infrastructure and reshape pricing economics toward subscription-based recurring revenue models. This substitution eliminates capital expenditure barriers for community hospitals while concentrating vendor margin pressure on legacy maintenance streams.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise, mid-market, and community hospital levels, with integrated delivery networks commanding 40-60% unit discounts against standalone facilities. Price differentiation rests on EHR integration depth and FDA 21st Century Cures Act API certification status. Pricing pressure stems from ambulatory surgery center procurement consolidating around turnkey bundles. Community hospitals exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize interoperability compliance over cost.
Supply Chain Analysis
Inbound logistics costs from Asian sensor manufacturing through Los Angeles and Long Beach port gateways influence RFID and Bluetooth Low Energy tag pricing for asset tracking deployments. Hardware components draw from China, Taiwan, and South Korea, while cloud infrastructure feeds from US-based hyperscaler regions. Single-source vulnerability concentrates in semiconductor-dependent IoT sensor modules. Distribution runs through health system GPO contracts and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where EHR-anchored switching costs protect incumbent positions against point-solution challengers. Regulatory entrenchment through FDA interoperability mandates creates certification barriers that compound customer lock-in.
For Market Incumbents: Consolidate command center architectures across bed management, asset tracking, and staffing optimization to displace standalone vendors. Deepen Epic and Cerner integration layers to raise substitution costs for health systems facing 21st Century Cures Act deadlines. Acquire IoT sensor specialists to capture predictive maintenance convergence opportunities.
For New Entrants and Emerging Players: FDA 21st Century Cures Act fast-track certification for cloud-native FHIR connectors opens procurement access to merged health systems reconciling disparate EHR instances. Ambulatory surgery centers in Texas and Florida present the most penetrable white space where lean operational models favor turnkey scheduling platforms. Pursue channel partnerships with GPOs to bypass direct enterprise sales barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed staffing optimization specialists holding union scheduling rule expertise and float-pool orchestration IP. Long-term viability hinges on value-based care alignment where CMS shared savings contracts create durable budget authority for throughput optimization. Monitor ambulatory surgery center case volume growth as inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Connector Certification | FDA 21st Century Cures Act compliance unlocks procurement from merged health systems. |
| Command Center Unification | Consolidated bed management and asset tracking displace standalone point solutions. |
| IoT Sensor Integration | Real-time location systems feed predictive analytics for high-value mobile equipment. |
| ASC Partnership Program | Same-day discharge workflow optimization captures fastest-expanding buyer segment. |
| Staffing Optimization Acquisition | Union scheduling expertise commands premium margins amid persistent nurse shortages. |
Research Methodology
Initial hypotheses were tested against primary input from hospital CIOs, health system procurement committees, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, CMS Medicare cost report data, hospital procurement databases, and SEC 10-K disclosures from listed vendors. Bottom-up modeling of vendor revenue segments triangulated against top-down health system IT spending benchmarks.
Variance decomposition across deployment model, health system scale, EHR integration complexity, regional regulatory cluster, and application priority shaped analytical framework construction throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated ambulatory surgery center case volume trajectories and CMS value-based payment model penetration assumptions.
Underlying assumptions cover interoperability mandate enforcement timelines and cloud migration adoption curves, with deviation risk concentrated in legacy infrastructure replacement delays and clinical labor shortage persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
IVD Contract Manufacturing Services Market
Healthcare Services
US Post-Acute Care (PAC) Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Private Healthcare Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Global Umbilical Cord Blood Banking Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
US Healthcare Third-Party Logistics Market
Healthcare Services
Global Hospice Care Market
Healthcare Services
Global Medical Affairs Outsourcing Market
Healthcare Services
Spa Services Market
Healthcare Services
In-Home Senior Care Franchises Market
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Professional Spa Services Market
Healthcare Services
India Senior Living Market