
 Global Wearable Skin Patch Market | 2026-2036
Global Wearable Skin Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wearable Skin Patch Market Foresight
Biomedical engineering talent pools in flexible electronics is collapsing across North America and Western Europe, constraining OEMs' ability to scale next-generation patch platforms. Abbott leverages its vertically integrated glucose biosensor manufacturing to sustain cost leadership in continuous monitoring applications. Dexcom competes through proprietary algorithm development that anchors its real-time predictive analytics layer.
Wearable skin patches are adhesive-mounted, miniaturized devices incorporating biocompatible substrates, conductive traces, and transducer elements that interface with epidermal tissue to extract physiological signals or deliver active compounds; typical specifications include sub-millimeter thickness, 3–14 day wear duration, and wireless transmission via Bluetooth Low Energy or near-field protocols. Monitoring sensor patches dominate current revenue flows due to established reimbursement for cardiac and metabolic indications, while microneedle-based drug delivery platforms represent the fastest-expanding technology segment as pharmaceutical sponsors seek alternatives to hypodermic injection. Bioimpedance modalities occupy a specialized niche in hydration and body composition tracking where optical methods face accuracy limitations.
FDA breakthrough device designations and EMA's medical device regulation framework are tightening clinical evidence requirements for algorithm-enabled patches, directly shaping R&D prioritization and market access timelines. Japan's PMDA has accelerated review pathways for wearable cardiovascular monitors, creating regulatory arbitrage opportunities for firms with multi-region submission capabilities. Stakeholders must monitor evolving cybersecurity standards for connected patch ecosystems as payers begin conditioning coverage on device resilience certifications.
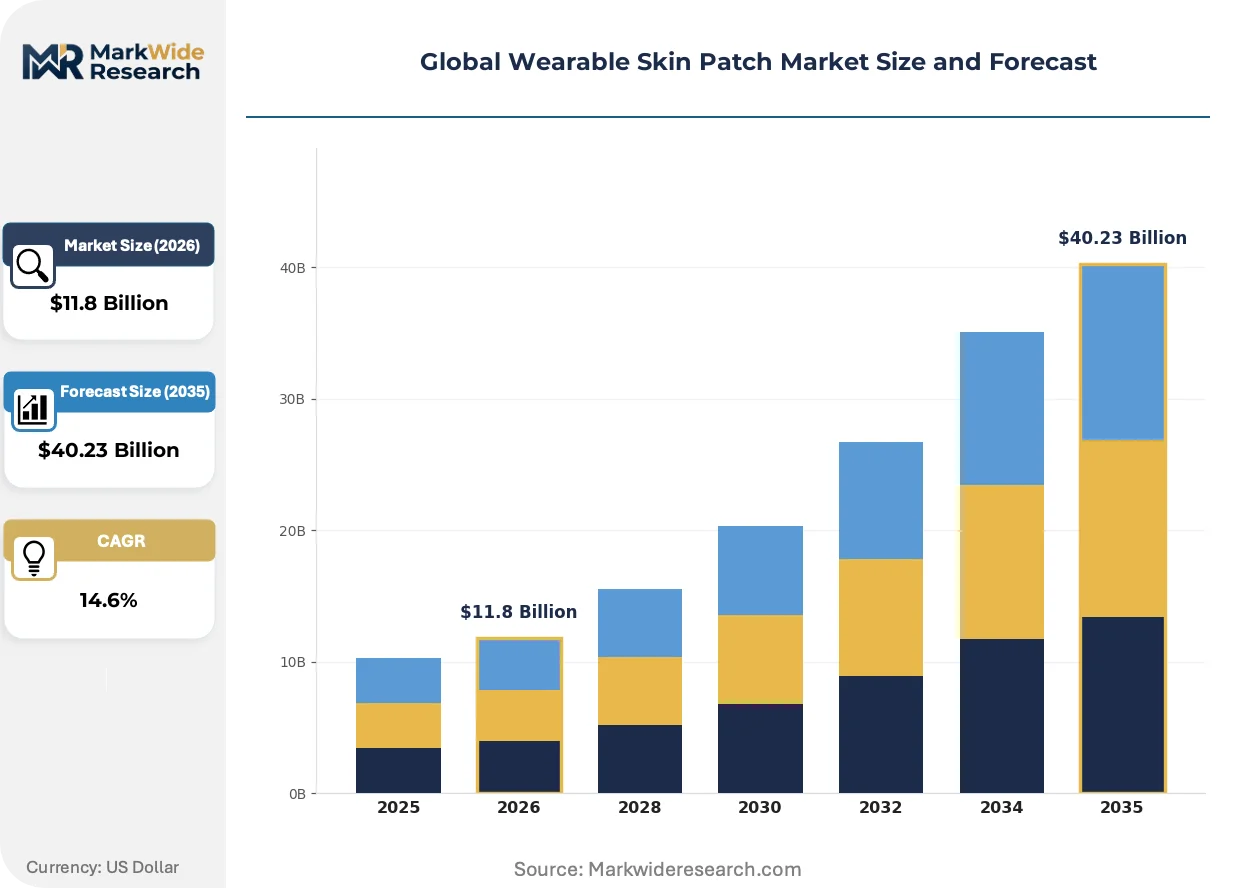
Market Dynamics
The FDA breakthrough device designation pathway is compressing commercialization timelines for algorithm-enabled patches while simultaneously tightening clinical evidence requirements, forcing OEMs to reallocate R&D budgets toward prospective validation studies rather than iterative hardware refinement.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:CMS expanded coverage codes for ambulatory cardiac monitoring in the United States, creating immediate revenue visibility for patch-based arrhythmia detection platforms.
- Microneedle Manufacturing Scale-Up:Roll-to-roll microfabrication lines in pharmaceutical contract manufacturing organizations are cutting unit costs for transdermal drug delivery patches below hypodermic injection parity.
- EMA Medical Device Regulation:The MDR framework's emphasis on clinical performance data is accelerating consolidation among patch developers with robust quality management systems, advantaging scaled players.
Market Restraints
- Silver Nanowire Supply Concentration:South Korean and Japanese conductive ink suppliers control critical flexible electrode material flows, exposing patch OEMs to input cost volatility and allocation risk.
- Adhesion Chemistry Limitations:Current silicone-acrylic hybrid formulations fail to maintain signal integrity beyond 14 days on mobile skin surfaces, capping wear duration for metabolic monitoring applications.
- FDA Cybersecurity Guidance:Pre-market submission requirements for connected patch ecosystems are extending regulatory review timelines by 6-12 months for first-time digital health entrants.
Strategic Opportunities
- Japan's PMDA Accelerated Pathway:Wearable cardiovascular monitors receive prioritized review, enabling regulatory arbitrage for firms with multi-region submission capabilities and Japan-specific clinical data packages.
- Home-Based Chronic Disease Management:Germany's DiGA fast-track for prescription digital therapeutics opens reimbursement channels for patch-integrated hypertension and heart failure management programs.
- Bioimpedance-AI Convergence:Machine learning models trained on multi-frequency impedance spectra are unlocking hydration and body composition metrics previously requiring laboratory-grade equipment.
Industry Challenges
- Flexible Electronics Talent Scarcity:Biomedical engineering programs in North America and Western Europe are producing insufficient graduates with thin-film processing and stretchable circuit design competencies.
- Legacy Health Record Integration:Hospital IT departments face 12-18 month implementation cycles to embed patch data streams into Epic and Cerner workflows, slowing enterprise adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wearable Skin Patch Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $40.23 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drug Delivery Patch, Monitoring Sensor Patch, Diagnostic Patch, Fitness Tracker Patch, Pain Relief Patch Technology: Electrochemical, Optical, Bioimpedance, Microfluidic, Microneedle, Wireless Communication Application: Diabetes Management, Cardiovascular Monitoring, Fitness & Wellness, Pain Management, Neurological Assessment End User: Pharmaceutical Companies, Research Institutions, Athletic Trainers, Home Care Providers, Telemedicine Services |
| Companies Covered | Abbott, Dexcom, Inc., Medtronic, Insulet Corporation, Boston Scientific Corporation, Koninklijke Philips N.V., VitalConnect, iRhythm Technologies, Inc., VivaLNK, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wearable Skin Patch Market Shifts & Advancements
Algorithmic inference at the edge is displacing cloud-dependent analytics architectures across the wearable patch value chain, while regulatory frameworks in major jurisdictions are hardening around cybersecurity resilience and clinical validation standards.
Printed graphene electrodes are displacing silver-silver chloride reference architectures in next-generation cardiac monitoring patches. Hospital systems in the United States and Germany are piloting these platforms for 30-day ambulatory arrhythmia detection. The shift is compressing bill-of-materials costs while extending functional wear duration beyond current adhesive chemistry limits.
EMA's Medical Device Regulation and FDA's pre-certification pilot for software-as-medical-device are converging on mandatory post-market surveillance databases. Patch developers must now fund 24-month follow-up registries for algorithm updates. Cardiovascular monitoring segments face the steepest compliance burden due to Class IIb/III risk classifications.
Self-insured employers are contracting directly with patch-enabled remote monitoring platforms, bypassing traditional payer channels. This disintermediation concentrates procurement decisions among benefits consultants and occupational health departments rather than hospital value analysis committees. The pattern is most advanced in the United States, where large employers face direct liability for catastrophic cardiac events in distributed workforces.
Global Wearable Skin Patch Market Segmentation
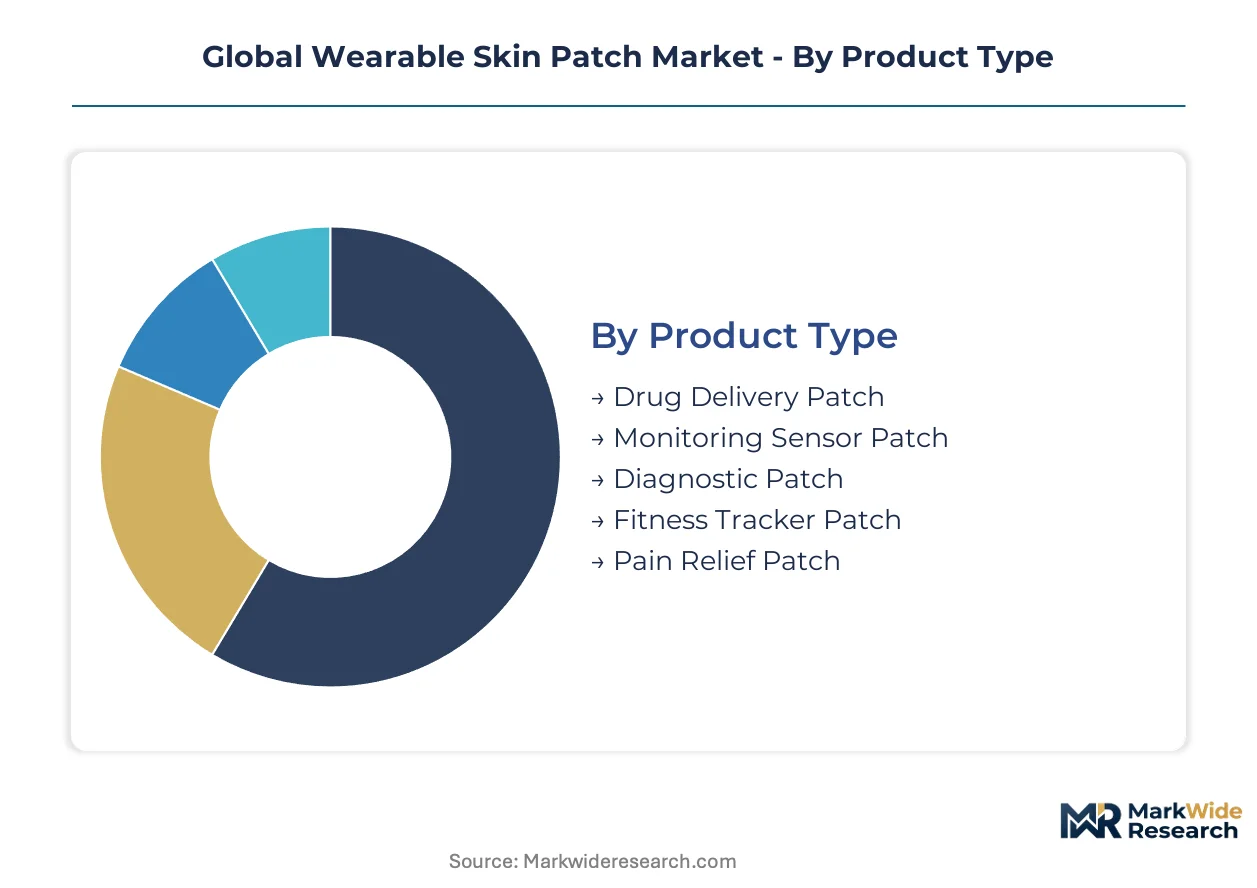
Segmentation in wearable skin patches reveals how regulatory pathways, reimbursement codes, and manufacturing capabilities concentrate value across distinct product configurations. Understanding these divisions exposes where FDA breakthrough designations, CMS coverage decisions, and EMA MDR compliance burdens reshape competitive positioning.
Product Type:
FDA Class II and III designations create divergent clinical evidence requirements across adhesive-mounted platforms, directly shaping commercialization timelines and capital deployment priorities.
- Drug Delivery Patch:Microneedle arrays and transdermal reservoirs deliver active compounds through stratum corneum penetration. Germany's DiGA fast-track for prescription digital therapeutics accelerates reimbursement for hormone and vaccine delivery platforms in home care settings.
- Monitoring Sensor Patch:Electrochemical and optical transducers extract continuous physiological signals for metabolic and cardiac surveillance. United States demand concentrates among Medicare Advantage plans covering ambulatory arrhythmia detection, though adhesive chemistry limitations cap wear duration at 14 days.
- Diagnostic Patch:Single-use biosensors detect biomarkers for infectious disease or acute cardiac events. Point-of-care deployment in Japanese clinics benefits from PMDA accelerated review pathways.
- Fitness Tracker Patch:Consumer-grade bioimpedance and accelerometer modules track hydration and movement metrics. Athletic trainers in United States collegiate programs drive procurement for load management applications.
- Pain Relief Patch:TENS-enabled conductive substrates deliver neuromuscular electrical stimulation. Retail pharmacy distribution in Germany and Japan faces pricing pressure from generic transdermal alternatives.
Monitoring sensor patches handle the majority of throughput; drug delivery patches are expanding most quickly on share.
Technology:
Unit economics and manufacturing yield rates stratify technology adoption, with roll-to-roll microfabrication investments favoring modalities that leverage existing pharmaceutical contract manufacturing infrastructure.
- Electrochemical:Enzyme-based and direct electron transfer architectures dominate glucose and lactate quantification. Abbott's vertically integrated biosensor manufacturing sustains cost leadership in continuous glucose monitoring applications.
- Optical:Photoplethysmography and spectroscopic methods enable heart rate and oxygen saturation tracking. Signal degradation on pigmented skin surfaces constrains clinical validation across diverse United States patient populations.
- Bioimpedance:Multi-frequency current injection measures tissue hydration and body composition. Machine learning models trained on impedance spectra are unlocking metrics previously requiring laboratory-grade equipment in German research institutions.
- Microfluidic:Capillary-driven sweat and interstitial fluid collection enables biomarker isolation. Research institutions in Japan pilot these platforms for cortisol and hydration monitoring in occupational health programs.
- Microneedle:Dissolvable and hydrogel-forming arrays create transdermal channels for macromolecule delivery. Pharmaceutical companies in the United States sponsor scale-up trials to achieve cost parity with hypodermic injection.
- Wireless Communication:Bluetooth Low Energy and NFC protocols transmit encrypted data to paired devices. FDA cybersecurity guidance extends regulatory review timelines for first-time digital health entrants deploying these modules.
Electrochemical platforms command the dominant installed base; microneedle systems are gaining share fastest.
Application:
Reimbursement code availability and clinical evidence requirements segment applications by payback period, with chronic disease management programs offering more predictable revenue streams than consumer wellness deployments.
- Diabetes Management:Continuous glucose monitoring patches integrate with insulin dosing algorithms. United States Medicare coverage expansion creates immediate revenue visibility for factory-calibrated systems eliminating fingerstick requirements.
- Cardiovascular Monitoring:Ambulatory ECG patches detect atrial fibrillation and ventricular arrhythmias. CMS expanded coverage codes in the United States drive enterprise adoption among accountable care organizations.
- Fitness & Wellness:Hydration, recovery, and load metrics target athletic and occupational populations. Self-insured employers in the United States contract directly with monitoring platforms, bypassing traditional payer channels.
- Pain Management:Neuromodulation and topical analgesic delivery address chronic and post-surgical indications. Home care providers in Germany integrate these into multimodal pain protocols.
- Neurological Assessment:EEG-enabled patches monitor seizure activity and sleep architecture. Research institutions in Japan pilot these for epilepsy management in pediatric populations.
Cardiovascular monitoring handles the majority of throughput; neurological assessment is climbing the fastest.
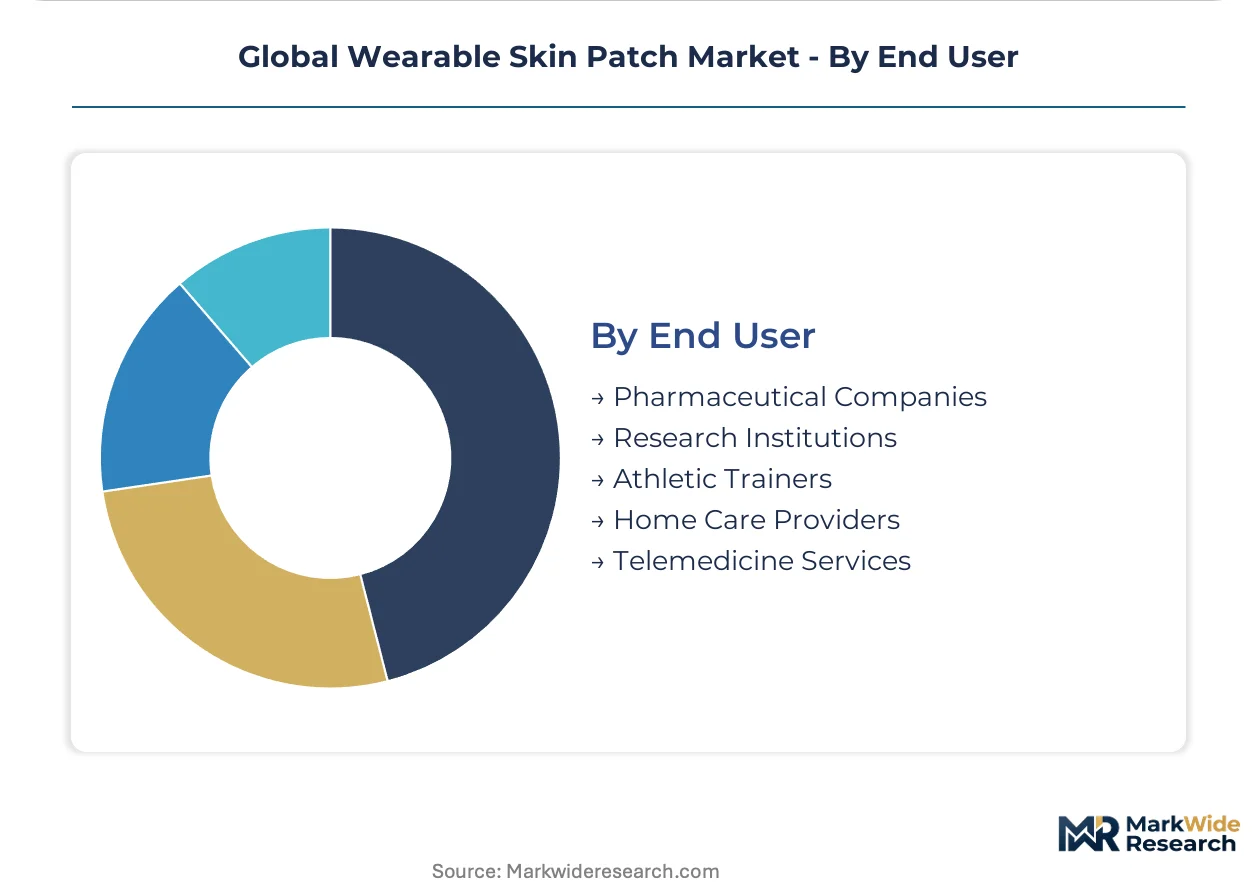
End User:
Procurement authority and technical integration requirements fragment the customer base, with pharmaceutical sponsors and telemedicine platforms offering contrasting volume and margin profiles.
- Pharmaceutical Companies:Sponsor microneedle and transdermal delivery platforms as alternatives to injection. Clinical trial supply agreements in the United States and Germany concentrate demand among top-20 sponsors.
- Research Institutions:Pioneer validation studies for novel biomarkers and wear durations. Japanese university hospitals lead PMDA-submission-ready clinical data generation.
- Athletic Trainers:Deploy load and recovery monitoring for injury prevention. United States collegiate and professional sports programs drive premium-tier procurement.
- Home Care Providers:Integrate chronic disease management patches into remote patient monitoring programs. German DiGA reimbursement channels accelerate adoption for hypertension and heart failure platforms.
- Telemedicine Services:Prescribe and remotely interpret patch-generated data. United States virtual-first primary care models embed cardiac and metabolic monitoring into subscription bundles.
Pharmaceutical companies handle the majority of throughput; telemedicine services are expanding most rapidly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds Germany by roughly 30% for ambulatory cardiac monitoring patches, while Japanese reimbursement rates for wearable cardiovascular devices trail both markets by a significant margin. This asymmetry reflects divergent regulatory pathways and payer structures across major demand centers.
United States
Medicare Advantage plans and self-insured employers drive procurement volume for continuous glucose and cardiac monitoring patches. FDA breakthrough device designations compress commercialization timelines for algorithm-enabled platforms. The Minneapolis medical device cluster anchors glucose biosensor manufacturing for continuous monitoring applications.
Germany
DiGA fast-track reimbursement for prescription digital therapeutics accelerates adoption of hypertension and heart failure management patches. EMA's Medical Device Regulation tightens clinical evidence requirements for algorithm updates, extending post-market surveillance obligations. The Munich-Stuttgart corridor concentrates telemedicine platform development integrating patch data streams.
Japan
PMDA accelerated review pathways for wearable cardiovascular monitors create regulatory arbitrage opportunities for firms with multi-region submission capabilities. Aging demographics expand home-based chronic disease management programs. Osaka-based university hospitals generate PMDA-submission-ready clinical data for novel biomarker validation.
United Kingdom
NHS Long Term Plan targets for remote patient monitoring drive patch procurement for ambulatory arrhythmia detection. MHRA convergence with EMA MDR frameworks elevates quality management system requirements. The Oxford-Cambridge-London arc hosts microfluidic research institutions piloting sweat-based biomarker platforms.
South Korea
MFDS streamlined approval pathways for software-as-medical-device accelerate market entry for connected patch ecosystems. National health insurance coverage expansion for diabetes management sustains demand for factory-calibrated glucose monitors. Seoul-based conductive ink suppliers control critical silver nanowire material flows for flexible electrode production.
Global Wearable Skin Patch Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the wearable skin patch value chain. The market structure concentrates around vertically integrated glucose monitoring specialists and algorithm-focused cardiac surveillance platforms, with contract manufacturing organizations filling capacity gaps for pharmaceutical-sponsored drug delivery programs. Three archetypes dominate: biosensor-integrated OEMs with captive manufacturing, predictive analytics specialists licensing software layers, and pharmaceutical contract manufacturers scaling microneedle production. Competitive moves center on backward integration into flexible electronics fabrication and strategic partnerships with telemedicine platforms for direct-to-patient distribution.
Among North American technology developers, Abbott and Dexcom occupy positions at opposite ends of the integration spectrum, with the former exemplifying cost leadership through captive biosensor production and the latter representing algorithm-centric competitive positioning. Medtronic anchors the diversified medical device tier, spanning multiple chronic disease indications beyond metabolic and cardiovascular surveillance. These three companies illustrate how scale, specialization, and vertical control generate divergent margin structures across otherwise overlapping market segments.
| Leading Market Players |
|---|
| Abbott |
| Dexcom, Inc. |
| Medtronic |
| Insulet Corporation |
| Boston Scientific Corporation |
| Koninklijke Philips N.V. |
| VitalConnect |
| iRhythm Technologies, Inc. |
| VivaLNK, Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements for silver nanowire conductive inks lock in both supply access and cost visibility for patch OEMs serving United States Medicare Advantage plans, while spot-market exposure for biocompatible adhesive polymers forces margin compression on shorter-duration wearables.
Pricing Analysis
The customization-premium spread between standard glucose monitoring platforms and algorithm-configured cardiac surveillance systems runs wide, with subscription-tiered SaaS models dominating predictive analytics layers while per-unit transactional pricing persists in factory-calibrated biosensor hardware. Price differentiation hinges on FDA breakthrough device certification tier and vertical integration depth in biosensor manufacturing. Cost compression in consumer-grade fitness tracker patches intensifies as generic transdermal alternatives flood retail pharmacy channels. Pharmaceutical sponsors exhibit lowest price sensitivity due to clinical trial supply guarantees, while home care providers face acute budget constraints under fixed DiGA reimbursement schedules.
Supply Chain Analysis
South Korean conductive ink suppliers control critical silver nanowire flows, creating single-source vulnerability for flexible electrode production across North American and Western European patch manufacturers. Raw material dependencies center on biocompatible silicone-acrylic hybrid adhesives, printed graphene precursor chemicals, and Bluetooth Low Energy module chipsets. Tariff exposure on Chinese-sourced microelectronic components threatens cost parity timelines for microneedle drug delivery platforms. Distribution runs through pharmaceutical contract manufacturing organizations for drug delivery patches and direct hospital system contracts for cardiac monitoring platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as home-based chronic disease management programs accelerate patch adoption beyond traditional clinical settings, with Germany's DiGA fast-track and United States CMS coverage expansions providing structural tailwinds.
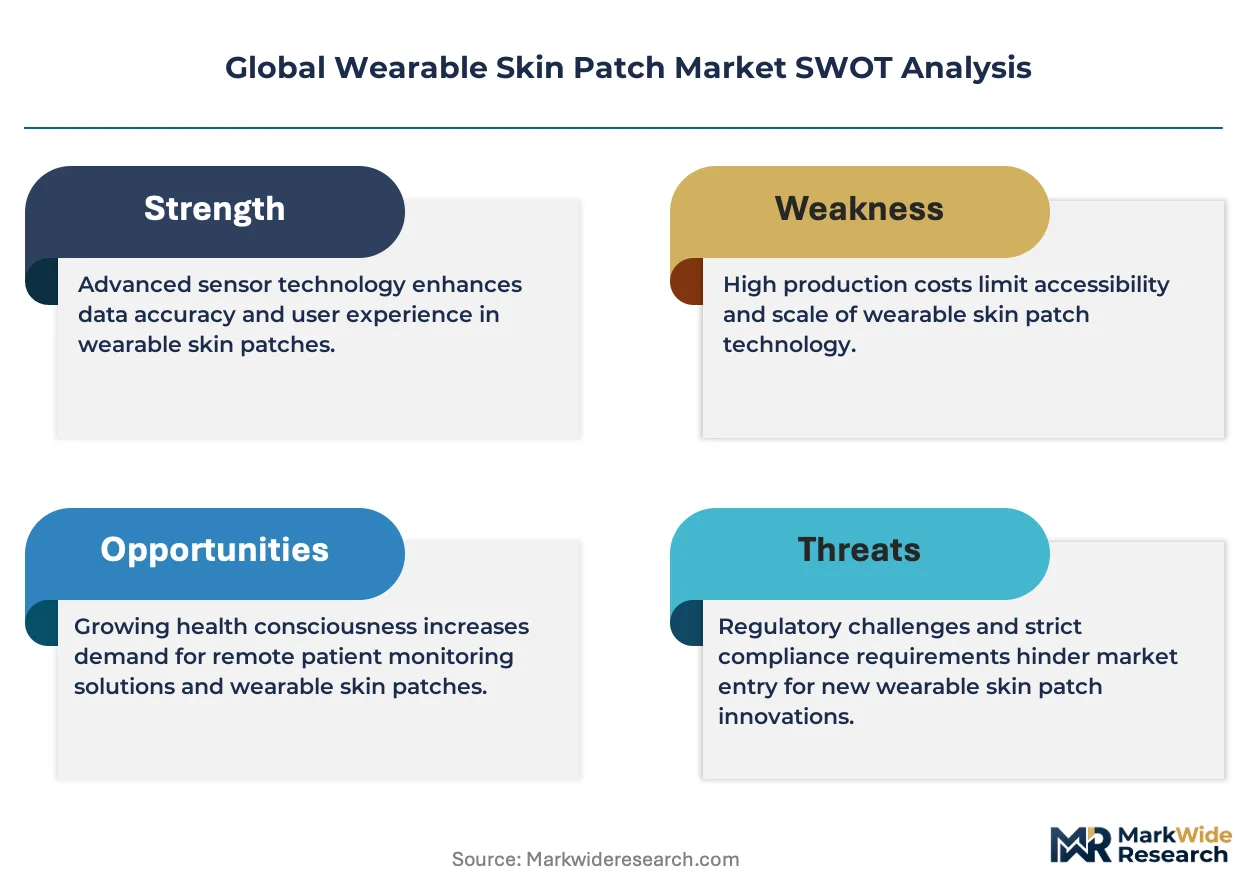
For Market Incumbents: Secure captive supply of silver nanowire conductive materials through backward integration into South Korean or Japanese material suppliers, and fortify algorithm validation registries to meet FDA cybersecurity guidance extensions threatening 6-12 month review delays. Defend against emerging contract manufacturing organizations scaling microneedle production by locking multi-year pharmaceutical sponsor agreements. For New Entrants and Emerging Players: Lead with bioimpedance-AI convergence platforms targeting hydration and body composition tracking, where optical methods face accuracy limitations and reimbursement pathways remain underdeveloped. Germany's DiGA fast-track for prescription digital therapeutics offers the most penetrable regulatory channel for hypertension and heart failure management patches. Pursue direct-to-patient distribution partnerships with telemedicine platforms bypassing traditional hospital value analysis committees. For Investors and Strategic Acquirers: Algorithm-focused cardiac surveillance specialists with proprietary predictive analytics layers and PMDA-submission-ready clinical data packages represent the highest-conviction acquisition archetype for multi-region regulatory arbitrage. Long-term viability rests on 5-10 year reimbursement durability as payers condition coverage on post-market surveillance database compliance. Watch for FDA breakthrough device designation announcements as inflection indicators for commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates commercialization timelines for algorithm-enabled patches meeting stringent clinical evidence requirements. |
| Backward Integration into Conductive Materials | Secures cost leadership in glucose biosensor manufacturing against silver nanowire supply concentration. |
| DiGA Reimbursement Strategy | Unlocks German prescription digital therapeutics channels for hypertension and heart failure management platforms. |
| Hospital System Partnership | Resolves 12-18 month Epic and Cerner workflow integration cycles slowing enterprise adoption. |
| Software Companion Development | Enables real-time predictive analytics layers that differentiate cardiac monitoring platforms from hardware-centric competitors. |
Research Methodology
Desk research of FDA 510(k) and De Novo filings, EMA MDR technical documentation, and CMS Medicare coverage determinations preceded structured interviews with biomedical engineering directors, hospital purchasing committee members, GPO contracts managers, and pharmaceutical clinical trial supply leads. Primary intelligence from patch OEMs and contract manufacturing organizations was cross-referenced against secondary validation from SEC 10-K disclosures, PMDA approval databases, and German DiGA directory listings. Bottom-up unit economics modeling and top-down reimbursement code analysis were triangulated to anchor market sizing.
Variance decomposition across product type, technology modality, application indication, and end-user procurement authority shaped the analytical framework over the projection horizon. CAGRs were derived from segmented adoption curves weighted by regulatory approval timelines and reimbursement code activation schedules. Forecast inputs incorporated silver nanowire material cost trajectories and microneedle manufacturing yield improvements from roll-to-roll microfabrication scale-up.
The analysis sits within stated boundaries; outcomes outside sustained CMS coverage expansion for ambulatory cardiac monitoring or PMDA accelerated pathway continuity would require recalibration. Forecasts reflect documented assumptions regarding adhesive chemistry wear duration limits and cybersecurity certification burden trajectories. Practitioners should keep alternative scenarios live as FDA software-as-medical-device pre-certification pilot evolution and EMA MDR post-market surveillance database mandates reshape compliance economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Germanium-68/Gallium-68 Generators Market
Medical Devices
Electroencephalography (EEG) Systems Market
Medical Devices
Global Aneurysm Clips Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Urine Collection Devices Market
Medical Devices
Global Mechanical Ventilators Market
Medical Devices
Global Pressure Relief Devices Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Medical Thermometer Market
Medical Devices
US Orthopedic Spine Navigation Systems Market
Medical Devices
Bone Cement Mixers Market