
 Non-Invasive Respiratory Monitoring Market | 2026-2036
Non-Invasive Respiratory Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Respiratory Monitoring Market Analytics
Aftermarket service revenue is tilting toward remote monitoring platforms and cloud-based analytics subscriptions. Koninklijke Philips N.V. leverages its HealthSuite digital infrastructure to capture recurring software revenue from hospital networks. ResMed Inc. anchors its competitive position through integrated sleep apnea management ecosystems that combine hardware with physician-facing dashboards. Masimo Corporation differentiates via advanced optical sensor algorithms that extend into homecare settings beyond traditional hospital contracts.
Non-invasive respiratory monitoring encompasses devices and systems that measure ventilation, gas exchange, and respiratory mechanics without breaking skin or mucosal barriers, typically employing optical spectroscopy, acoustic analysis, or electrical impedance techniques operating at sampling frequencies between 100 Hz and 500 Hz for clinical-grade resolution. These systems serve to enable continuous surveillance of at-risk patients while eliminating infection hazards and sedation requirements associated with arterial blood gas sampling or invasive catheterization. Portable monitors and wearable devices command expanding share as homecare reimbursement frameworks mature, while fixed systems retain dominance in intensive care units where multi-parameter integration remains essential. Capnography and optical sensor technologies lead installed base volumes, though impedance pneumography gains traction in ambulatory settings for its low power profile and textile integration potential.
FDA 510(k) clearance pathways and EU MDR conformity requirements shape product development timelines and clinical evidence standards for manufacturers seeking commercial access. HIPAA interoperability rules in the United States and GDPR data governance in Europe constrain how respiratory biomarker data flows between device makers, health systems, and payers. Stakeholders must weigh regulatory compliance investments against the pace of AI-enabled diagnostic claims that agencies are scrutinizing more intensively.
Market Dynamics
Hospital systems are consolidating vendor relationships around platforms that integrate respiratory data directly into electronic health records, compressing procurement cycles and elevating software interoperability above hardware specifications in purchasing decisions.
Growth Catalysts
- Medicare Hospital Readmissions Reduction Program:US health systems face financial penalties for excessive 30-day readmissions, driving investment in continuous remote monitoring for discharged patients with chronic respiratory conditions.
- Optical spectroscopy miniaturization:Advances in photoplethysmography and near-infrared sensors enable wearable form factors that maintain clinical-grade accuracy without arterial catheterization.
- Homecare reimbursement expansion:CMS and private payers in Germany and Japan are establishing dedicated billing codes for remote respiratory monitoring, shifting site-of-care economics toward ambulatory settings.
Market Restraints
- EU MDR clinical evidence requirements:Conformity assessment for Class IIa and IIb respiratory devices now demands expanded clinical data packages, extending time-to-market by 12-18 months for manufacturers without predicate device pathways.
- Indium gallium arsenide detector supply:High-performance optical sensors depend on specialized semiconductor materials concentrated in East Asian foundries, creating input cost volatility and single-source vulnerability.
- Acoustic monitoring substitution:Contactless radar and microphone-based respiratory rate detection offer lower hardware costs for sleep screening applications, pressuring optical sensor pricing in consumer-adjacent segments.
Strategic Opportunities
- Rural India primary care networks:Ayushman Bharat health infrastructure expansion creates first-mover potential for low-cost, solar-powered respiratory monitors in village-level clinics lacking trained pulmonologists.
- AI-enabled diagnostic claims under FDA breakthrough device pathway:Algorithm-based early warning systems for respiratory deterioration qualify for expedited review, enabling differentiated positioning in ICU early-warning platforms.
- Textile-integrated impedance pneumography:Convergence of conductive yarn manufacturing with garment production enables continuous monitoring in athletic and occupational safety applications beyond clinical settings.
Industry Challenges
- Firmware validation for AI/ML-enabled devices:FDA software as a medical device guidance requires locked algorithm versions with documented change control, complicating continuous learning deployments.
- Interoperability with legacy hospital IT:HL7 FHIR implementation varies across health systems, forcing device manufacturers to maintain multiple integration protocols and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Respiratory Monitoring Market |
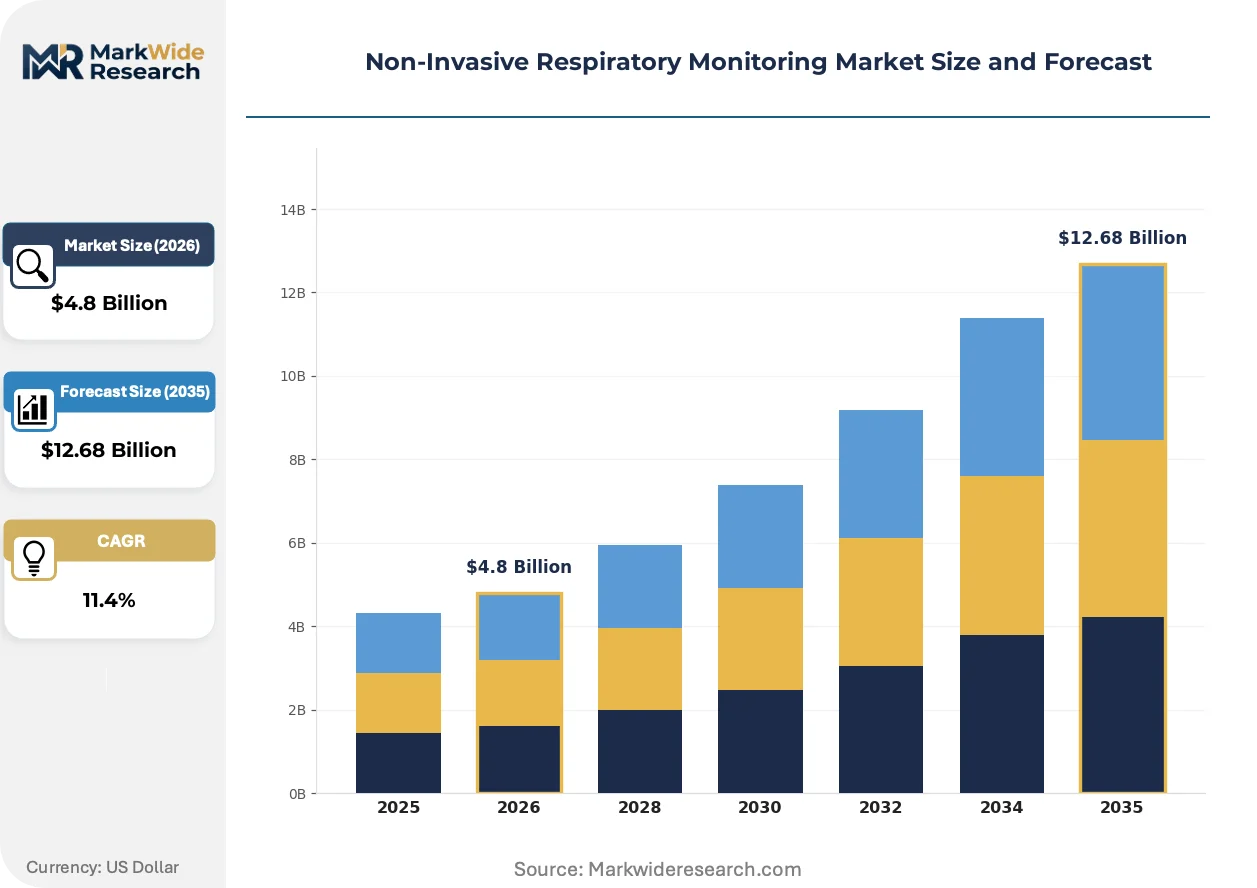
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
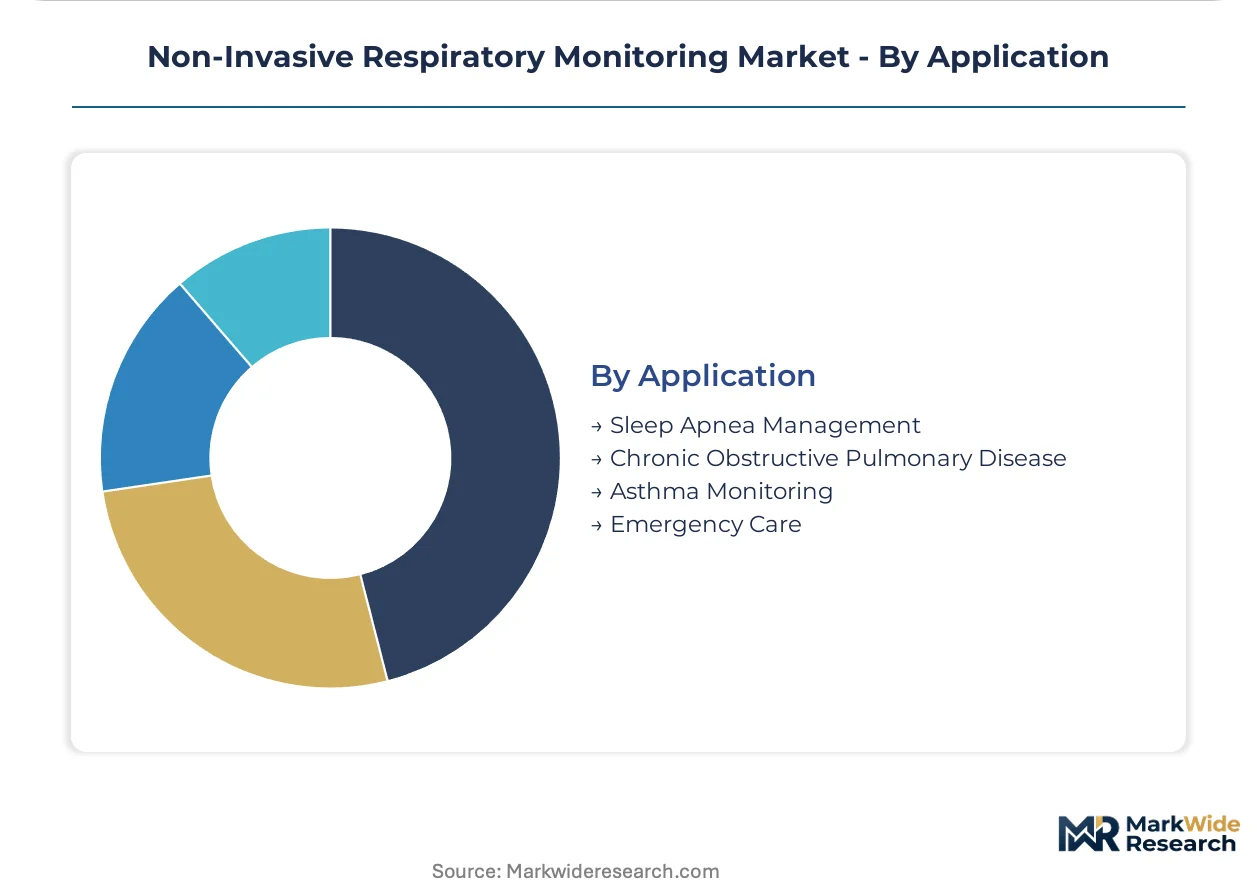
| Segmentation | Product Type: Portable Monitors, Wearable Devices, Fixed Systems, Software Solutions Technology: Capnometers, Impedance Pneumography, Ultrasound, Optical Sensors End User: Homecare Settings, Hospitals, Clinics, Research Laboratories Application: Sleep Apnea Management, Chronic Obstructive Pulmonary Disease, Asthma Monitoring, Emergency Care |
| Companies Covered | Koninklijke Philips N.V., ResMed Inc., Masimo Corporation, GE HealthCare Technologies Inc., Medtronic plc, Drägerwerk AG & Co. KGaA, Vyaire Medical, Smiths Medical, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Respiratory Monitoring Market Evolving Landscape
Sensor fusion architectures are collapsing the distinction between discrete respiratory parameters, enabling single-device platforms to replace multi-modality installations that previously required separate capital allocations.
Photoplethysmography is hybridizing with accelerometry and acoustic signal processing in next-generation wearables, combining blood oxygen saturation, respiratory rate, and sleep stage detection in unified form factors. Sleep medicine clinics and homecare providers are adopting these consolidated devices to reduce patient burden and equipment costs. The technology is hybridizing competitive dynamics by enabling consumer electronics manufacturers to enter clinical-adjacent monitoring segments previously protected by regulatory barriers.
The EU AI Act risk classification framework is imposing conformity obligations on respiratory diagnostic algorithms that influence patient triage decisions, requiring quality management systems and human oversight protocols. Manufacturers must now document training data provenance and algorithmic performance across demographic subgroups before CE marking. Respiratory early-warning systems deployed in French and German hospitals are responding by segregating AI-enabled features into standalone software modules that can be validated independently from hardware platforms.
Hospital procurement departments are consolidating respiratory monitoring contracts under enterprise-wide platform agreements, displacing the historical pattern of ICU-specific vendor relationships. Group purchasing organizations and integrated delivery networks are negotiating multi-year subscriptions that bundle hardware, software, and analytics. This concentration is most visible in the United States, where health systems exceeding 50 hospitals command pricing leverage that mid-tier device manufacturers struggle to match without channel partner restructuring.
Non-Invasive Respiratory Monitoring Market Segmentation
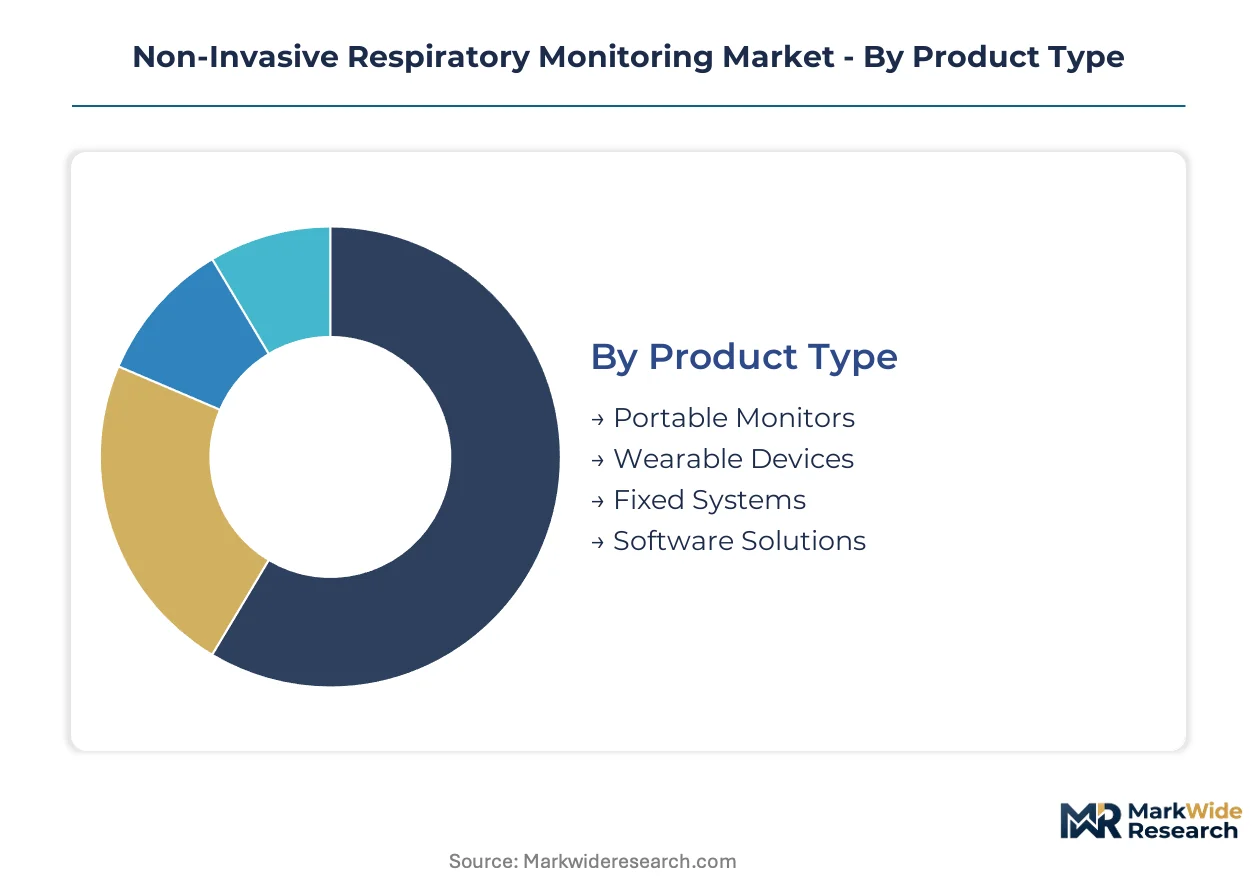
Segmentation in non-invasive respiratory monitoring reveals divergent replacement cycles and margin structures across hardware and software categories. Product refresh rates vary from 18 months for wearable firmware to 7-10 years for fixed ICU installations. Understanding these temporal patterns guides capital allocation and recurring revenue strategies for device manufacturers.
Product Type:
Replacement cycles stretch from rapid software iteration to decade-long capital equipment depreciation, creating divergent revenue recognition models across the portfolio.
- Portable Monitors:Battery-powered bedside units with wireless telemetry capability serve step-down units and emergency departments requiring mobility without sacrificing multi-parameter integration. Hospital procurement in the United States favors these units for Medicare-covered remote patient monitoring programs where 30-day readmission penalties drive continuous surveillance investment.
- Wearable Devices:Photoplethysmography-enabled patches and wrist-worn form factors integrate accelerometry for sleep stage classification. CMS reimbursement expansion for homecare respiratory monitoring accelerates patient discharge workflows and shifts site-of-care economics toward ambulatory settings in Germany and Japan.
- Fixed Systems:Rack-mounted ICU platforms with centralized nursing station displays dominate capital budgets in tertiary hospitals.
- Software Solutions:Cloud analytics subscriptions and AI-enabled early warning algorithms generate recurring revenue from health system networks.
Fixed systems anchor the volume base while software solutions gain share at the steepest rate.
Technology:
Cost tiers separate high-performance optical platforms from commodity acoustic alternatives, with reimbursement codes favoring clinical-grade accuracy over consumer-adjacent screening.
- Optical Sensors:Near-infrared spectroscopy and photoplethysmography modules measure SpO2 and respiratory rate through tissue perfusion analysis without arterial puncture. FDA 510(k) clearance for optical-based capnography extends Masimo Corporation's hospital contracts into homecare settings where indium gallium arsenide detector costs constrain pricing flexibility.
- Capnometers:Sidestream and mainstream CO2 analyzers provide quantitative ventilation assessment for intubated and non-intubated patients. Demand concentrates in United States operating rooms and post-anesthesia care units where End-Tidal CO2 monitoring is standard of care.
- Impedance Pneumography:Electrical impedance across thoracic electrodes enables textile integration for continuous ambulatory monitoring.
- Ultrasound:Point-of-care diaphragm imaging and lung ultrasound protocols gain adoption in emergency medicine.
Capnometers dominate current installed value while impedance pneumography expands most quickly through wearable form factors.
End User:
Customer type determines purchasing authority, with hospital IT departments overriding clinical preferences for interoperability-certified platforms.
- Hospitals:Integrated delivery networks and group purchasing organizations negotiate enterprise-wide contracts bundling hardware, software, and analytics subscriptions. HL7 FHIR implementation requirements in United States health systems exceeding 50 hospitals compress vendor selection to platforms with proven EHR integration.
- Homecare Settings:Durable medical equipment suppliers and sleep medicine clinics deploy patient-owned devices with remote physician oversight. Dedicated billing codes from CMS and private German payers shift chronic respiratory disease management from inpatient to domiciliary settings.
- Clinics:Primary care and pulmonology practices require lower-acuity monitoring for diagnostic screening.
- Research Laboratories:Academic medical centers and contract research organizations drive protocol development for novel biomarkers.
Hospitals command the revenue concentration while homecare settings climb the fastest as reimbursement frameworks mature.
Application:
Maturity curves separate established sleep apnea markets from emerging chronic disease management platforms requiring longitudinal evidence generation.
- Sleep Apnea Management:Home sleep testing devices with automated scoring algorithms replace in-laboratory polysomnography for diagnostic screening. ResMed Inc.'s integrated ecosystems combining positive airway pressure therapy with adherence monitoring capture recurring revenue from United States sleep medicine practices facing reimbursement compression.
- Chronic Obstructive Pulmonary Disease:Continuous remote monitoring for exacerbation prediction reduces hospitalization frequency in high-risk cohorts. Medicare Hospital Readmissions Reduction Program penalties drive United States health system investment in discharged patient surveillance.
- Asthma Monitoring:Pediatric and adolescent wearable solutions with parental notification features address adherence challenges.
- Emergency Care:Prehospital capnography and triage screening tools support emergency medical services workflows.
Sleep apnea management retains the largest patient volume while chronic obstructive pulmonary disease applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate lowest price elasticity due to reimbursement-backed procurement, while Indian village clinics and Southeast Asian distributors operate under severe budget constraints that prioritize hardware longevity over feature depth.
United States
Medicare Hospital Readmissions Reduction Program penalties compel integrated delivery networks to deploy continuous respiratory surveillance for discharged COPD patients. FDA 510(k) clearance pathways and HIPAA interoperability rules constrain vendor selection to platforms with proven EHR integration. The Boston-Cambridge corridor anchors algorithm development for AI-enabled early warning systems.
Germany
Statutory health insurance funds now reimburse remote respiratory monitoring under dedicated ambulatory care billing codes, shifting chronic disease management from inpatient wards to domiciliary settings. EU MDR conformity requirements and the EU AI Act risk classification framework impose documentation burdens on diagnostic algorithm deployments. The MedTech cluster around Tübingen and Freiburg drives textile-integrated impedance pneumography research.
Japan
Aging demographics and Ministry of Health, Labour and Welfare reimbursement expansion for home medical devices accelerate patient-owned monitor adoption. PMDA consultation procedures for software as a medical device extend development timelines for AI-enabled features. The Kansai region's electronics manufacturing base supplies photoplethysmography sensor modules to domestic and export markets.
India
Ayushman Bharat health infrastructure expansion creates procurement volume for low-cost, solar-powered respiratory monitors in rural primary health centers lacking pulmonologist coverage. CDSCO medical device rules and BIS certification requirements govern import and local manufacturing compliance. Hyderabad's medical device cluster assembles optical sensor platforms for price-sensitive South Asian and African markets.
China
National health system digitization mandates and NMPA regulatory streamlining for Class II devices attract domestic capital toward respiratory monitoring platform development. Dual carbon goals pressure manufacturers toward low-power wearable designs that reduce battery waste. The Yangtze River Delta concentration of MEMS foundries supplies miniaturized optical detectors for regional device assemblers.
Non-Invasive Respiratory Monitoring Market Competitive Landscape
Capability concentration sits with specialized optical sensor developers; scale advantage sits with diversified health technology conglomerates. The market structure bifurcates between premium-tier platforms commanding enterprise-wide hospital contracts and mid-tier vendors competing on modular hardware pricing. Three archetypes dominate: integrated sleep therapy ecosystem operators, hospital IT infrastructure incumbents, and component-level sensor specialists. Competitive moves center on AI algorithm validation for FDA breakthrough device designation and multi-year subscription bundling that locks out point-solution competitors.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and GE HealthCare Technologies Inc. occupy positions shaped by enterprise software integration capabilities rather than discrete device specifications. ResMed Inc. exemplifies the integrated ecosystem archetype through its sleep apnea management platforms. Masimo Corporation anchors the sensor specialization tier with optical algorithm expertise extending beyond traditional hospital settings. Drägerwerk AG & Co. KGaA represents German-engineered critical care infrastructure. Medtronic plc sits within the diversified medical device tier with respiratory monitoring as one vertical among multiple therapeutic categories.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| ResMed Inc. |
| Masimo Corporation |
| GE HealthCare Technologies Inc. |
| Medtronic plc |
| Drägerwerk AG & Co. KGaA |
| Vyaire Medical |
| Smiths Medical |
| Nihon Kohden Corporation |
| Others |
Value Network & Pricing Analysis
Indium gallium arsenide detector supply concentration in East Asian foundries determines both the premium-to-economy tier spread in optical sensor modules and the geographic shape of respiratory device manufacturing networks. Manufacturers must navigate single-source semiconductor vulnerability while calibrating pricing architectures across hospital procurement and homecare reimbursement environments.
Pricing Analysis
After-sales service contracts and cloud analytics subscriptions now drive lifetime value capture for respiratory monitoring platforms. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared ICU platforms from CE-marked ambulatory devices and consumer-adjacent screening tools. Pricing pressure stems from acoustic monitoring substitutes in sleep screening segments where radar and microphone-based detection undercuts optical sensor hardware costs. Hospital procurement committees demonstrate lowest price sensitivity due to Medicare penalty avoidance incentives, while Southeast Asian distributors operate under severe budget constraints prioritizing hardware longevity.
Supply Chain Analysis
Contract manufacturing capacity for photoplethysmography modules concentrates in Taiwan, South Korea, and Japan where MEMS foundries and EMS providers serve tier-one device assemblers. Optical sensor production draws from indium phosphide substrates, gallium arsenide wafers, and near-infrared LED emitters anchored in specialized semiconductor supply chains. Single-source vulnerability in InGaAs detector fabrication creates procurement risk for manufacturers dependent on East Asian foundry output. Distribution runs through hospital group purchasing organizations in the United States, statutory health insurance channels in Germany, and durable medical equipment suppliers in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-invasive respiratory monitoring incumbents face acute substitution pressure from acoustic and radar-based contactless detection technologies that commoditize basic respiratory rate measurement in screening applications.
For Market Incumbents: Insulate installed base relationships through multi-year subscription bundling that combines hardware, software, and AI-enabled early warning analytics. Deepen backward integration into optical sensor algorithm development to differentiate against lower-cost acoustic substitutes. Prioritize FDA breakthrough device pathway validation for respiratory deterioration prediction models that lock out point-solution competitors from ICU early-warning platforms. For New Entrants and Emerging Players: Pursue white-space positioning in rural Indian primary care networks where Ayushman Bharat infrastructure expansion creates first-mover opportunity for solar-powered, low-cost respiratory monitors. Target textile-integrated impedance pneumography for athletic and occupational safety applications beyond regulated clinical settings. Deploy direct-to-clinic go-to-market models that bypass consolidated hospital procurement channels. For Investors and Strategic Acquirers: EU AI Act risk classification reshapes the acquisition landscape by imposing conformity obligations on diagnostic algorithms that influence patient triage decisions. Long-term viability favors targets with validated quality management systems and documented training data provenance across demographic subgroups. Monitor FDA software as a medical device guidance enforcement patterns as the signal indicating whether continuous learning algorithm deployments face locked-version constraints that devalue AI-enabled acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway Submission | Expedited review for AI-enabled respiratory early-warning systems accelerates ICU platform differentiation. |
| Hospital System Partnership | Enterprise-wide EHR integration contracts with integrated delivery networks lock out modular competitors. |
| CE Marking Pathway under EU MDR | Class IIa and IIb conformity assessment demands clinical evidence packages extending time-to-market. |
| Software Companion Development | Cloud analytics subscriptions generate recurring revenue from health system networks beyond hardware sales. |
| Reimbursement Strategy | Dedicated CMS and German statutory insurance billing codes shift site-of-care economics toward homecare. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and sleep medicine clinicians converged on the working assumptions underlying this analysis. Primary interviews with respiratory device manufacturers and homecare durable medical equipment suppliers combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body documentation, and hospital procurement contract records. Bottom-up segmentation modeling and top-down macroeconomic factor adjustment ensured cross-verification of volume and value estimates.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation dimensions spanning product type, technology modality, end-user setting, and application area. CAGRs emerged from patient population growth trajectories, reimbursement code expansion patterns, and replacement cycle analysis across hardware and software categories. Forecast inputs incorporated optical sensor miniaturization curves, EU AI Act implementation timelines, and Medicare Hospital Readmissions Reduction Program penalty structures.
Sensitivities concentrate around EU MDR clinical evidence requirement stringency, InGaAs detector supply disruptions, and acoustic monitoring substitution rates in consumer-adjacent segments. Forecasts reflect documented assumptions regarding reimbursement framework maturation and regulatory pathway efficiency. Cross-checking against hospital capital expenditure surveys and medical device import customs data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Global Fetal and Neonatal Monitoring Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
Global Intrapartum Monitoring Devices Market
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
Remote Electrocardiogram Monitoring Market
Patient Monitoring
Pain Monitoring Devices Market
Patient Monitoring
Medical Telemetry Market
Patient Monitoring
Global Body Temperature Monitoring Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Health Sensors Market