
 Lung Monitoring Devices Market | 2026-2036
Lung Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Lung Monitoring Devices Market Analysis
The capital-intensity divergence between integrated sensor manufacturers and assembly-only device makers is unwinding competitive stability across the lung monitoring landscape. Medtronic PLC leverages captive semiconductor fabrication to control pulse-oximetry module costs. Koninklijke Philips N.V. anchors its bedside monitor franchise through hospital IT integration contracts that lock in multi-year replacement cycles.
Lung monitoring devices comprise electronic sensor arrays, acoustic transducers, and data-transmission modules that measure respiratory rate, oxygen saturation, lung volume, and airflow patterns in real time. These systems employ piezoelectric pressure sensors with sampling frequencies exceeding 100 Hz and wireless protocols such as Bluetooth Low Energy to stream biometric data to clinical decision-support platforms. Portable monitors and wearable devices are capturing margin pools as home-care reimbursement codes expand, while bedside monitors occupy a mature replacement cycle dominated by GE Healthcare and Nihon Kohden Corporation installed bases. AI analytics represents the fastest-growing technology segment, though acoustic monitoring retains cost advantages in resource-constrained clinic settings.
FDA 510(k) pathways and EU MDR conformity assessments shape product development timelines and market access thresholds for lung monitoring devices. Japan's PMDA enforces JIS T 0601-1 electrical safety standards that constrain design architectures for devices targeting that market. Stakeholders must track evolving home-care reimbursement policies and interoperability mandates from regulators to anticipate which product configurations will secure preferential placement.
Market Dynamics
Home-care reimbursement expansion is compressing hospital replacement cycles while forcing manufacturers to reconfigure sensor architectures for untethered operation. This demand rotation is redistributing margin pools from bedside systems toward portable and wearable form factors.
Growth Catalysts
- EU MDR compliance deadlines:Manufacturers accelerating conformity assessments ahead of 2024-2026 renewal waves, creating replacement demand for legacy devices lacking updated technical documentation.
- Japan's aging demographic concentration:PMDA electrical safety standards (JIS T 0601-1) are shaping design specifications for devices targeting the 65+ population segment with chronic respiratory conditions.
- Piezoelectric pressure sensors:Sampling frequencies exceeding 100 Hz now enable real-time airflow pattern detection in ambulatory settings previously limited to stationary monitoring.
Market Restraints
- Semiconductor supply concentration:Captive fabrication capacity at integrated manufacturers limits component access for assembly-only device makers, constraining production scale-up.
- EU MDR technical documentation burdens:Conformity assessment timelines extending 12-18 months beyond legacy CE marking processes delay product launches and tie up regulatory capital.
- Acoustic monitoring substitution:Lower-cost acoustic transducers retain cost advantages in resource-constrained clinic settings, compressing pricing for electronic sensor arrays.
Strategic Opportunities
- Germany's hospital IT integration mandates:Procurement specifications requiring HL7 FHIR interoperability create preference windows for vendors with established EHR connectivity.
- AI analytics convergence with Bluetooth Low Energy:Edge computing architectures enabling on-device pattern recognition without continuous cloud connectivity open rural and developing-market penetration.
- United States home-care reimbursement codes:CMS expansion of remote patient monitoring billing categories is redirecting capital toward wearable respiratory monitor development.
Industry Challenges
- FDA 510(k) predicate device navigation:Substantial equivalence determinations for novel sensor configurations require extensive clinical validation, extending time-to-revenue.
- Legacy bedside monitor installed bases:GE Healthcare and Nihon Kohden Corporation multi-year replacement contracts lock in hospital purchasing committees, raising customer acquisition costs for challengers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lung Monitoring Devices Market |
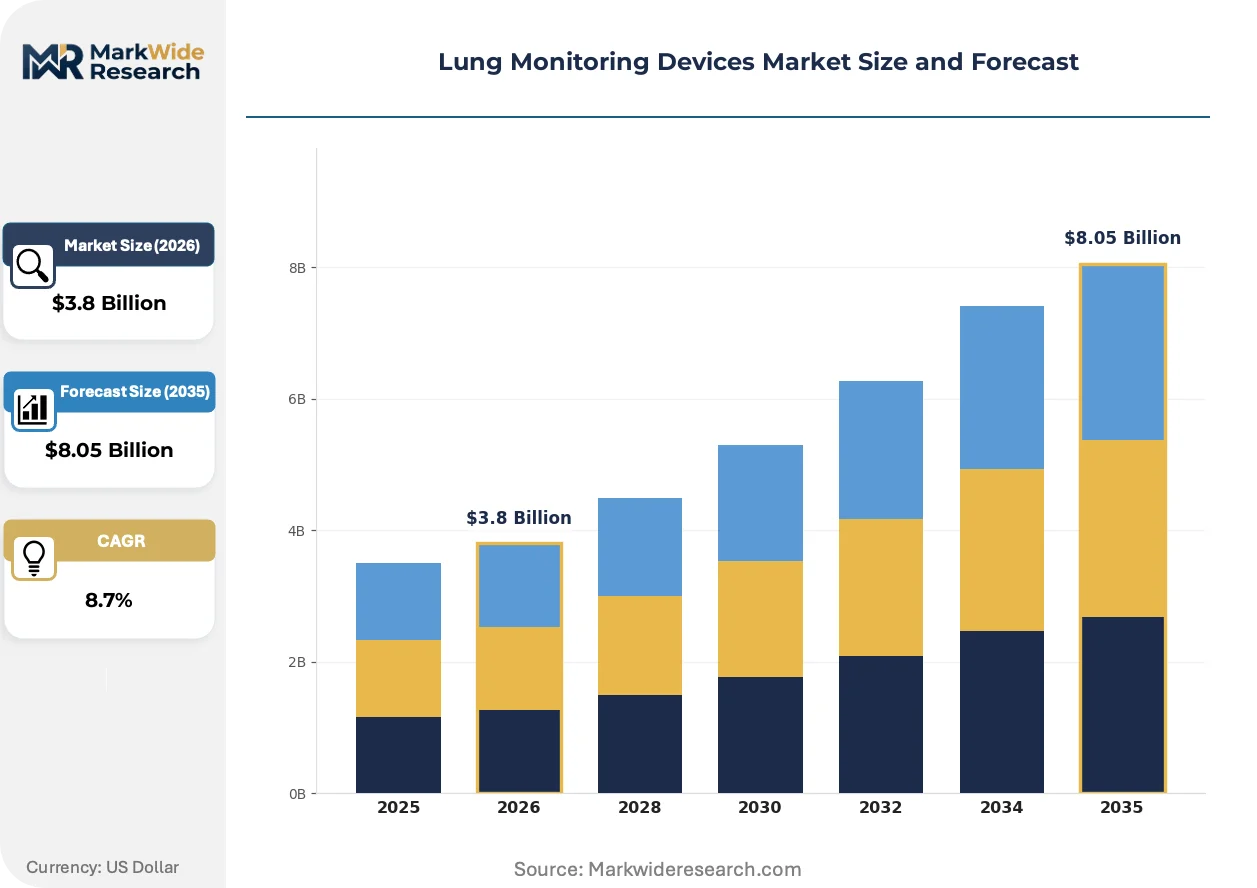
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Wearable Devices, Home Monitoring Systems, Bedside Monitors Technology: Electronic Sensors, Acoustic Monitoring, AI Analytics, Data Transmission End User: Hospitals, Home Care, Clinics, Research Laboratories Application: Chronic Disease Management, Postoperative Monitoring, Oxygen Therapy, Preventive Care |
| Companies Covered | Medtronic PLC, Koninklijke Philips N.V., ResMed Inc., Nihon Kohden Corporation, Masimo Corporation, GE Healthcare, Teleflex Inc., Becton Dickinson and Company, Vyaire Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lung Monitoring Devices Market Emerging Trajectories
Sensor fusion architectures and wireless protocol standardization are actively reconfiguring how respiratory data flows from patient to clinical decision-support platforms. These shifts are redistributing technical differentiation from hardware precision toward software analytics and interoperability.
Multi-modal sensor fusion combining pulse-oximetry, acoustic transducers, and impedance pneumography is bifurcating the market into premium integrated systems and single-parameter economy devices. Hospital systems in the United States are consolidating purchasing around platforms with native EHR integration, while home-care providers in Germany prioritize standalone wearables with patient-facing apps. This divergence is compressing mid-tier product生存空间 as buyers refuse to pay integrated-system prices for disconnected hardware.
EU MDR Article 10 post-market surveillance requirements now mandate systematic collection and analysis of device performance data across the entire product lifecycle. Manufacturers must establish quality management systems capable of detecting emerging safety signals and reporting to competent authorities within compressed timelines. Class IIa and IIb lung monitoring devices face the steepest compliance burdens, with notified body capacity constraints extending certification timelines and favoring larger players with dedicated regulatory affairs functions.
Hospital procurement committees are unbundling after-sales service contracts from hardware purchases, forcing device manufacturers to compete on transparent per-procedure or per-patient pricing models. This disintermediation of long-term service agreements is most visible in Japan, where METI hospital efficiency directives pressure capital expenditure committees to demonstrate total cost of ownership over five-year horizons. Vendors responding with modular service tiers and remote diagnostics capabilities are capturing preference in centralized purchasing frameworks.
Lung Monitoring Devices Market Segmentation
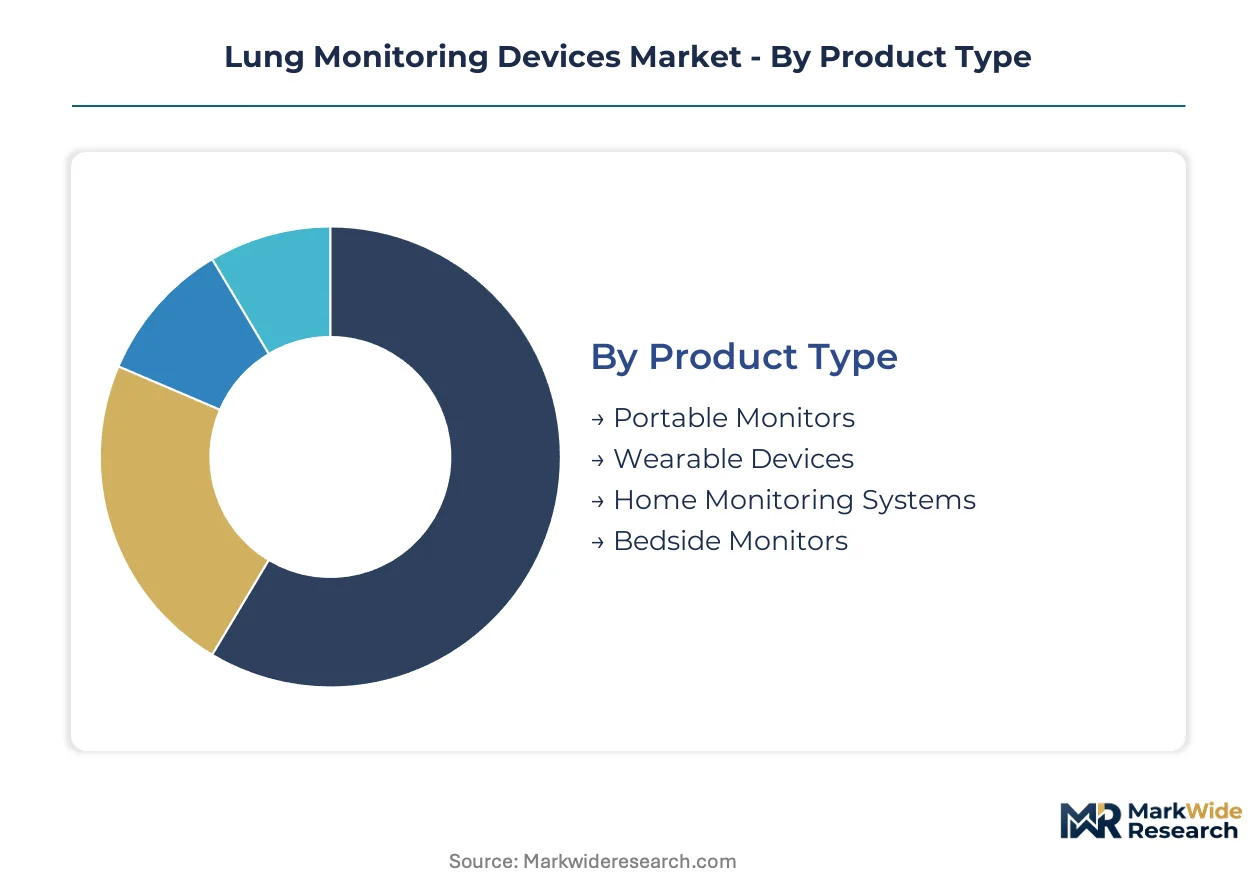
Lung monitoring devices fragment across four intersecting dimensions that determine regulatory pathways, reimbursement eligibility, and sensor architecture requirements. Product form factor and technology selection directly gate market access in Japan, Germany, and the United States where divergent standards shape competitive positioning.
Product Type:
FDA 510(k) predicates and EU MDR classification rules split hardware configurations into distinct conformity assessment tracks with material timeline implications.
- Portable Monitors:Battery-powered units with Bluetooth Low Energy streaming capabilities bridge acute and ambulatory settings. Hospital systems in Germany favor these for ward-based respiratory surveillance under HL7 FHIR procurement mandates.
- Wearable Devices:Chest-worn or finger-worn form factors integrate piezoelectric sensors with sub-50g enclosures. CMS remote patient monitoring billing code expansion in the United States redirects R&D capital toward continuous SpO2 and respiratory rate tracking for home-bound patients with COPD.
- Home Monitoring Systems:Hub-based architectures with cellular backhaul serve rural geographies lacking broadband infrastructure.
- Bedside Monitors:Multi-parameter consoles with 100+ Hz sampling occupy mature replacement cycles locked in by GE Healthcare and Nihon Kohden Corporation installed bases.
Bedside monitors handle the majority of throughput; wearable devices are the fastest mover on share.
Technology:
Component selection determines whether manufacturers capture premium integrated margins or compete as assembly-only device makers.
- Electronic Sensors:Piezoelectric pressure arrays with 100+ Hz sampling frequencies enable real-time airflow pattern detection. Captive semiconductor fabrication at Medtronic PLC and Philips constrains component access for second-tier assemblers.
- Acoustic Monitoring:Contact microphones and tracheal sound analysis deliver respiratory rate without skin-adhesive electrodes. Resource-constrained clinics in Japan retain preference for these lower-cost transducers over electronic arrays.
- AI Analytics:Edge computing architectures process biometric streams on-device without continuous cloud connectivity, opening penetration in bandwidth-limited developing markets.
- Data Transmission:Protocol standardization around Bluetooth Low Energy and proprietary 2.4 GHz links determines interoperability with hospital IT systems and patient-facing mobile applications.
Electronic sensors command the dominant revenue position; AI analytics is expanding most quickly as software differentiation displaces hardware precision.
End User:
Procurement authority concentration varies sharply across settings, with hospital committees demanding EHR integration and home-care providers prioritizing patient-facing usability.
- Hospitals:Centralized purchasing committees in the United States and Germany consolidate around platforms with native interoperability, compressing mid-tier vendors without established IT partnerships.
- Home Care:Reimbursement code expansion from CMS and parallel European mechanisms redirects capital toward untethered sensor architectures with patient-facing apps.
- Clinics:Capital constraints favor acoustic monitoring and single-parameter economy devices over integrated multi-sensor systems.
- Research Laboratories:Investigational use exemptions and non-clinical validation protocols permit pre-market sensor configurations unavailable in regulated care settings.
Hospitals absorb the largest capital allocation; home care is climbing the fastest as reimbursement boundaries shift.
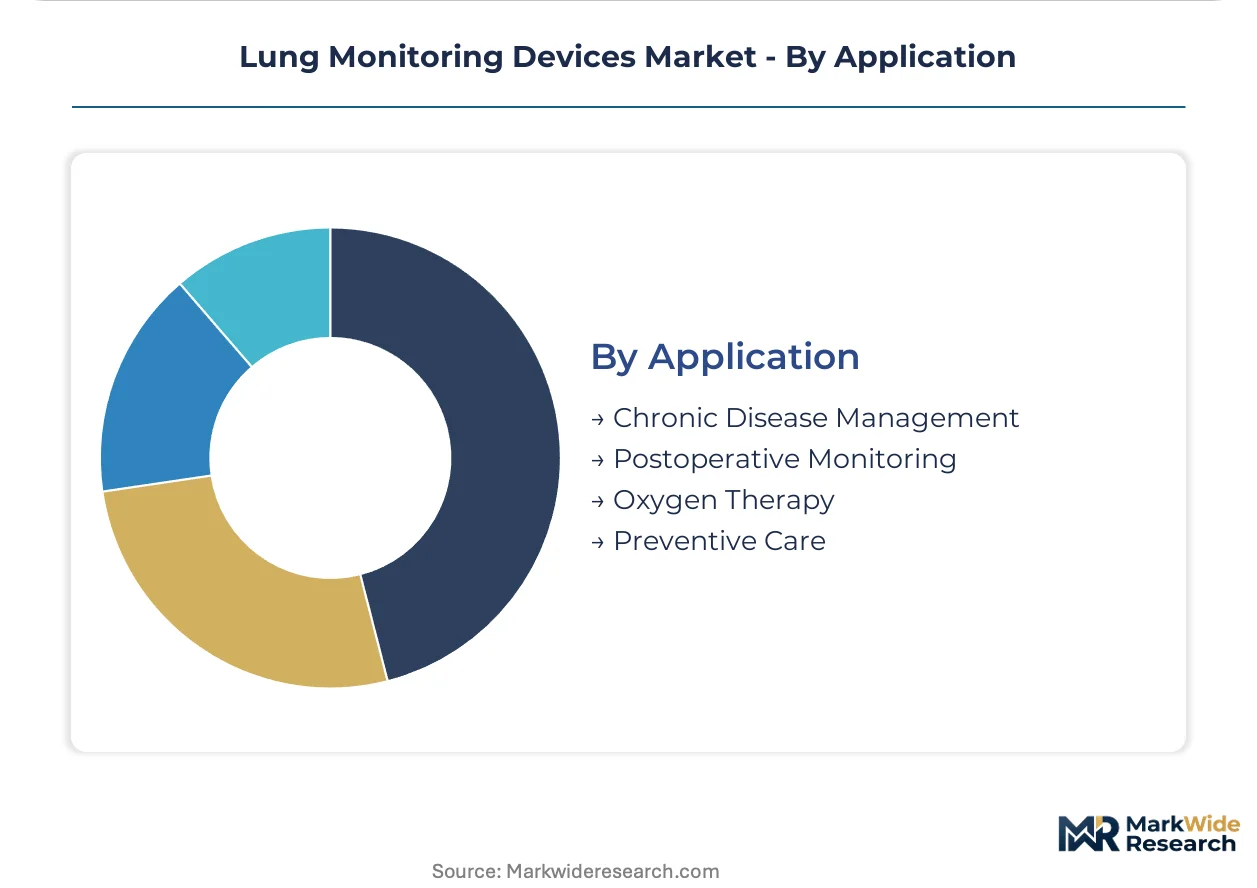
Application:
Clinical use case determines sampling frequency requirements, alarm threshold configurations, and regulatory predicate selection.
- Chronic Disease Management:Continuous multi-day monitoring of COPD and asthma patients drives demand for wearable form factors with 72+ hour battery endurance.
- Postoperative Monitoring:High-acuity respiratory surveillance in surgical wards requires 100+ Hz sampling and immediate alarm escalation, favoring bedside and portable configurations.
- Oxygen Therapy:SpO2-guided titration of supplemental oxygen integrates pulse-oximetry with delivery system feedback loops in home and hospital settings.
- Preventive Care:Population-scale screening programs for early respiratory dysfunction employ lower-cost acoustic or single-parameter electronic screening tools.
Chronic disease management captures the deepest installed base; preventive care is gaining share fastest as payer focus shifts upstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan and Germany demonstrate low price elasticity for integrated hospital systems, while clinics in India and resource-constrained settings prioritize acoustic monitoring substitutes. This demand divergence shapes regional investment patterns.
United States
CMS reimbursement code expansion for remote patient monitoring redirects capital toward wearable respiratory monitors for home-bound COPD patients. FDA 510(k) pathways enforce substantial equivalence requirements that extend validation timelines for novel sensor configurations. The Boston-Cambridge corridor concentrates AI analytics development for edge computing architectures.
Germany
Hospital procurement committees consolidate purchasing around HL7 FHIR-integrated platforms under federal IT interoperability mandates. EU MDR Article 10 post-market surveillance requirements compress certification timelines for Class IIa and IIb devices. The Baden-Württemberg medical technology cluster drives piezoelectric sensor manufacturing for ambulatory monitors.
Japan
PMDA electrical safety standards under JIS T 0601-1 constrain design architectures targeting the 65+ chronic respiratory population. METI hospital efficiency directives pressure capital committees to demonstrate five-year total cost of ownership. The Kansai region anchors Nihon Kohden Corporation's installed base maintenance and multi-year replacement contracting.
India
Capital constraints in tier-2 and tier-3 cities sustain demand for lower-cost acoustic transducers over electronic sensor arrays. CDSCO medical device rules alignment with international standards accelerates market entry for imported portable monitors. The Maharashtra-Gujarat pharmaceutical corridor expands contract manufacturing for export-oriented respiratory device assembly.
United Kingdom
NHS England procurement frameworks prioritize EHR-native platforms that compress mid-tier vendor margins without established IT partnerships. MHRA post-Brexit regulatory autonomy maintains CE marking recognition while introducing UKCA conformity assessment parallel tracks. The Oxford-Cambridge-London golden triangle concentrates AI-enabled pattern recognition development for preventive care screening.
Lung Monitoring Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive semiconductor fabrication distinguishing the former from assembly-only device makers. Medtronic PLC and Koninklijke Philips N.V. anchor the upper tier through backward integration into pulse-oximetry module production. Three archetypes populate the competitive landscape: integrated sensor manufacturers, hospital IT integrators, and portable/wearable specialists. Dominant competitive moves include strategic partnerships for EHR connectivity and geographic expansion through notified body certification stacking.
Within the integrated tier, Medtronic PLC and Koninklijke Philips N.V. represent the capital-intensive archetype that constrains component access for second-tier assemblers. ResMed Inc. exemplifies the portable and wearable specialist archetype benefiting from CMS reimbursement tailwinds. These three companies occupy positions that reflect the market's bifurcation between premium integrated systems and single-parameter economy devices.
| Leading Market Players |
|---|
| Medtronic PLC |
| Koninklijke Philips N.V. |
| ResMed Inc. |
| Nihon Kohden Corporation |
| Masimo Corporation |
| GE Healthcare |
| Teleflex Inc. |
| Becton Dickinson and Company |
| Vyaire Medical Inc. |
| Others |
Supply Flow & Price Mechanics
Twelve-to-eighteen-month EU MDR conformity assessment timelines compress inventory turnover for device manufacturers while amplifying pricing power for integrated sensor producers with captive semiconductor fabrication. This lead-time band concentrates procurement leverage among Medtronic PLC and Koninklijke Philips N.V., forcing assembly-only competitors to absorb margin compression or sacrifice market access.
Pricing Analysis
After-sales service revenue tiers—spanning replacement sensors, calibration contracts, and remote diagnostics subscriptions—drive lifetime value capture in installed-base bedside monitors. Three-tier pricing structure across premium integrated systems, mid-range portable units, and economy acoustic devices stratifies by EHR interoperability certification and sampling frequency performance. Cost compression in mid-range portable monitors intensifies as German hospital procurement committees unbundle service contracts and demand transparent per-patient pricing. Home-care providers exhibit highest price sensitivity, while Japanese hospital capital committees demonstrate lowest elasticity under METI efficiency directives emphasizing five-year total cost of ownership.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors fluctuate with container availability for piezoelectric sensor substrates sourced from Baden-Württemberg manufacturing clusters. Component supply concentrates in Germany for precision pressure transducers, Taiwan for Bluetooth Low Energy chipsets, and Japan for acoustic transducer membranes. Raw material dependencies span lithium niobate crystals, medical-grade silicon wafers, and platinum electrode coatings. Single-source vulnerability in EU MDR-notified body capacity extends certification queues and favors larger players with dedicated regulatory affairs functions. Distribution runs through hospital GPO contracts in the United States, centralized procurement frameworks in Germany, and regional medical device distributors in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lung monitoring devices market sits in cyclical recovery as EU MDR compliance deadlines force replacement waves for legacy devices lacking updated technical documentation. This regulatory-driven refresh cycle redirects capital toward conformant sensor architectures.
For Market Incumbents: Compound installed-base defensibility through backward integration into pulse-oximetry module production and multi-year hospital IT integration contracts that lock replacement cycles. Extend regulatory affairs capacity to capture notified body queue priority for Class IIa and IIb device certifications. Counter acoustic monitoring substitution in resource-constrained clinics by demonstrating total cost of ownership advantages from electronic sensor arrays.
For New Entrants and Emerging Players: Differentiate on edge computing architectures enabling on-device AI analytics without continuous cloud connectivity, opening rural and developing-market penetration where bandwidth constraints exclude cloud-dependent competitors. Target India's tier-2 and tier-3 cities with portable monitors under CDSCO alignment with international standards. Pursue hospital system partnerships in Germany under HL7 FHIR procurement mandates as the primary go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized medical device divisions lacking dedicated regulatory affairs functions or EHR connectivity capabilities. Five-to-ten-year viability hinges on reimbursement code expansion sustainability and AI analytics differentiation displacing hardware precision. Watch CMS remote patient monitoring billing category expansion velocity as the inflection indicator for wearable respiratory monitor capital allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Substantial equivalence pathways accelerate market entry for novel sensor configurations in the United States. |
| CE Marking Pathway | EU MDR Article 10 compliance enables post-market surveillance data capture across the entire product lifecycle. |
| Hospital System Partnership | HL7 FHIR interoperability mandates in Germany create preference windows for EHR-native platform vendors. |
| Software Companion Development | Patient-facing mobile applications differentiate home-care wearables under CMS reimbursement expansion. |
| Reimbursement Strategy | Remote patient monitoring billing code navigation determines capital allocation between bedside and portable form factors. |
Methodological Framework
A spread of perspectives from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR notified body certification databases, CMS Medicare reimbursement schedules, and hospital procurement contract records. Bottom-up demand modeling from installed-base replacement cycles and top-down market sizing from manufacturer revenue disclosures were triangulated to establish volume and value estimates.
Segmentation dimensions modeled span product form factor, sensor technology type, end-user setting, and clinical application across the projection horizon. CAGRs were derived from replacement cycle analysis, reimbursement code expansion trajectories, and regulatory compliance deadline clustering. Forecast inputs incorporated EU MDR notified body capacity constraints, semiconductor supply concentration patterns, and AI analytics adoption curves in bandwidth-limited geographies.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement expansion, EU MDR timeline adherence, and semiconductor supply stabilization would require recalibration. Forecasts reflect documented assumptions regarding home-care demand rotation and hospital procurement consolidation. Specific risk factors include acoustic monitoring substitution acceleration, single-source component supply disruption, and FDA predicate device navigation delays for novel sensor configurations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
North America Respiratory Monitoring Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
Italy Patient Monitoring Market
Patient Monitoring
Europe Hemodynamic Monitoring Market
Patient Monitoring
Heart Monitoring Devices Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Mobile Continuous Patient Monitors Market