
 North America Cardiac Arrhythmia Monitoring Devices Market | 2026-2036
North America Cardiac Arrhythmia Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cardiac Arrhythmia Monitoring Devices Market Outlook
Buyer concentration among hospital networks is restructuring procurement dynamics across the North America Cardiac Arrhythmia Monitoring Devices Market. Medtronic leverages its integrated device and service platform to anchor long-term telemetry contracts with major health systems. Abbott Laboratories competes through specialized catheter-based monitoring solutions that extend its electrophysiology footprint. iRhythm Technologies dominates the ambulatory patch segment with cloud-connected diagnostic workflows that reduce clinic administrative burden.
Cardiac arrhythmia monitoring devices encompass wearable, implantable, and stationary systems that detect, record, and transmit electrical activity anomalies from the myocardium, typically sampling at 250–1000 Hz with wireless transmission ranges of 10–30 meters to centralized monitoring stations. These systems serve the primary commercial purpose of enabling early intervention in atrial fibrillation, ventricular tachycardia, and bradyarrhythmia before thromboembolic or hemodynamic compromise occurs. Implantable loop recorders capture the fastest-growing margin pool as extended monitoring durations reduce diagnostic uncertainty in cryptogenic stroke cases. Holter monitors retain the largest installed base but face displacement by mobile cardiac outpatient telemetry where reimbursement aligns with episode-based care models. Wireless monitoring technology separates premium pricing tiers from standard ECG offerings through real-time alert capabilities that justify higher per-patient fees.
FDA premarket notification requirements under 21 CFR 870 shape device safety validation timelines, while CMS national coverage determinations directly influence reimbursement thresholds for remote cardiac monitoring services. The Cardiovascular Device Panel advisory committee reviews novel monitoring modalities before commercialization, creating a gatekeeping function that favors established players with regulatory affairs infrastructure. Stakeholders must monitor evolving CMS telehealth parity rules and state-level scope-of-practice expansions for nurse-led arrhythmia interpretation services.
Market Dynamics
Hospital network consolidation across the United States is compressing vendor relationships into multi-year telemetry service agreements that bundle device procurement with continuous monitoring support.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance for wearable ECG patches accelerates commercialization timelines for ambulatory monitoring innovators.
- Southeastern US cardiology expansion:Aging demographics in Florida, Georgia, and North Carolina drive deployment of implantable loop recorders in cryptogenic stroke protocols.
- Episode-based reimbursement alignment:CMS reimbursement structures favor mobile cardiac outpatient telemetry over traditional Holter monitoring for extended arrhythmia detection.
Market Restraints
- Semiconductor supply concentration:Dependence on Asian foundries for wireless transmission chipsets creates vulnerability in device manufacturing schedules.
- CMS national coverage determination lag:Delayed reimbursement decisions for novel monitoring modalities freeze hospital capital expenditure cycles.
- Signal artifact interference:Motion artifacts in wearable patches limit diagnostic yield during high-activity patient states.
Strategic Opportunities
- Nurse-led interpretation services:State-level scope-of-practice expansions enable remote arrhythmia triage without physician overhead.
- Cloud-connected diagnostic workflows:Integration of AI-enhanced ECG analysis with electronic health record systems reduces clinic administrative burden.
- Canadian market penetration:Health Canada's streamlined medical device licensing creates entry pathway for US-cleared monitoring technologies.
Industry Challenges
- Electrophysiologist workforce scarcity:Limited fellowship-trained specialists constrain interpretation capacity for high-volume telemetry services.
- Legacy system integration friction:Proprietary data formats from incumbent device manufacturers impede interoperability with third-party monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cardiac Arrhythmia Monitoring Devices Market |
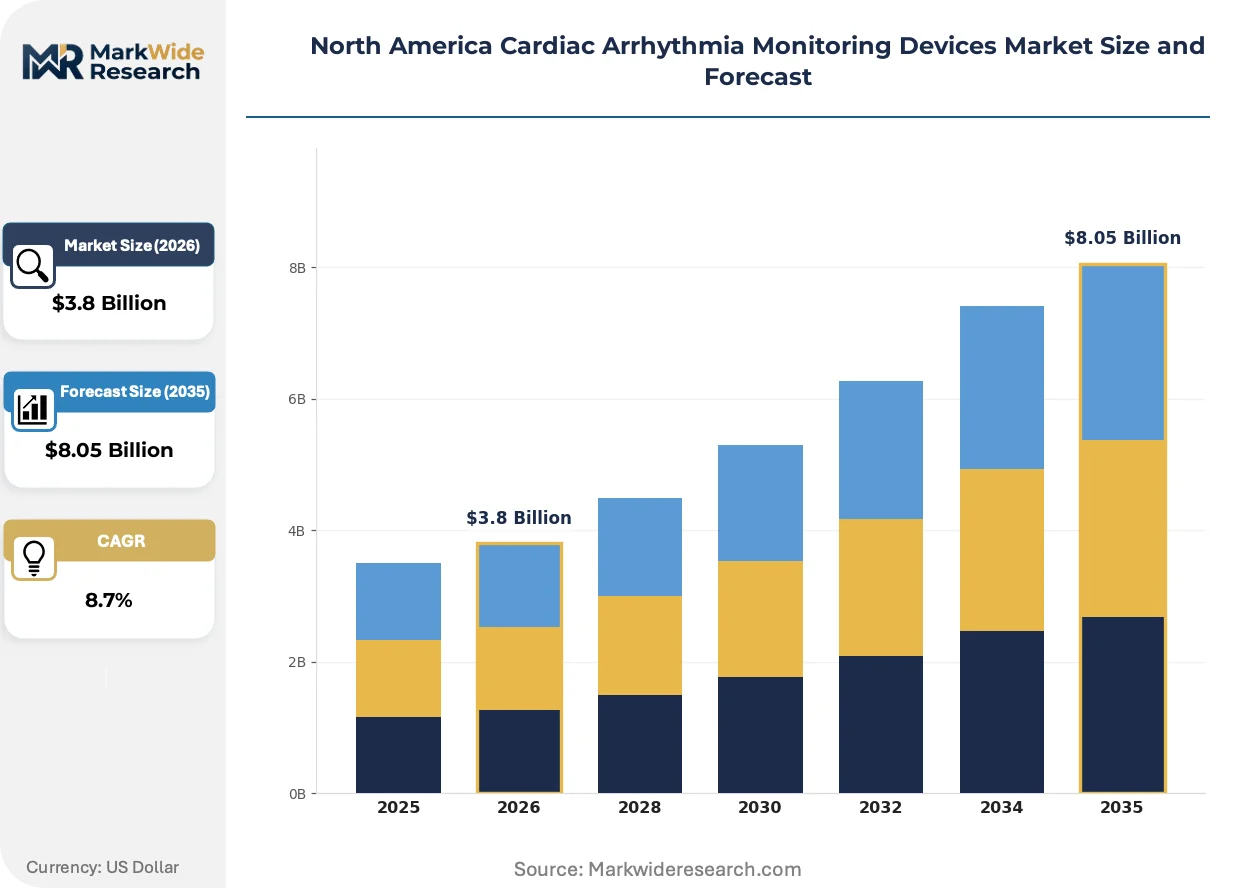
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitors, Event Monitors, Mobile Cardiac Outpatient Telemetry, Implantable Loop Recorders End User: Hospitals, Specialty Clinics, Cardiology Practices, Home Care Technology: Electrocardiogram, Wireless Monitoring, Cloud-based Solutions, Wearable Devices Application: Arrhythmia Detection, Postoperative Monitoring, Stroke Prevention, Heart Failure Management |
| Companies Covered | Medtronic, Abbott Laboratories, GE Healthcare, Koninklijke Philips NV, iRhythm Technologies, BioTelemetry, Boston Scientific, ACS Diagnostics, Cardiac Science Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cardiac Arrhythmia Monitoring Devices Market Strategic Shifts
Wearable ECG technology is redistributing diagnostic capability from hospital settings into patient homes, collapsing the traditional site-of-care boundary for arrhythmia detection.
Artificial intelligence-enhanced ECG interpretation is decentralizing diagnostic authority from centralized reading centers to edge-computing devices embedded in patient-worn monitors. Community health systems in Texas and Arizona are deploying these systems to reduce specialist consultation backlogs. The shift compresses time-to-diagnosis from days to hours while fragmenting revenue pools across technology vendors and clinical service providers.
CMS telehealth parity rule evolution is reshaping reimbursement geography for remote cardiac monitoring services. The policy extension enables synchronous physician-patient interaction during arrhythmia episodes, previously restricted to asynchronous data review. Ambulatory surgery centers in California and New York are restructuring service lines to capture these newly reimbursable encounters.
Hospital procurement committees are consolidating vendor relationships into enterprise-wide telemetry contracts that span implantable, wearable, and stationary monitoring modalities. Independent cardiology practices in the Midwest face exclusion from these purchasing coalitions and are migrating toward device-as-a-service arrangements with specialized monitoring companies. The behavioral shift concentrates purchasing power among integrated delivery networks while fragmenting the ambulatory provider vendor base.
North America Cardiac Arrhythmia Monitoring Devices Market Segmentation
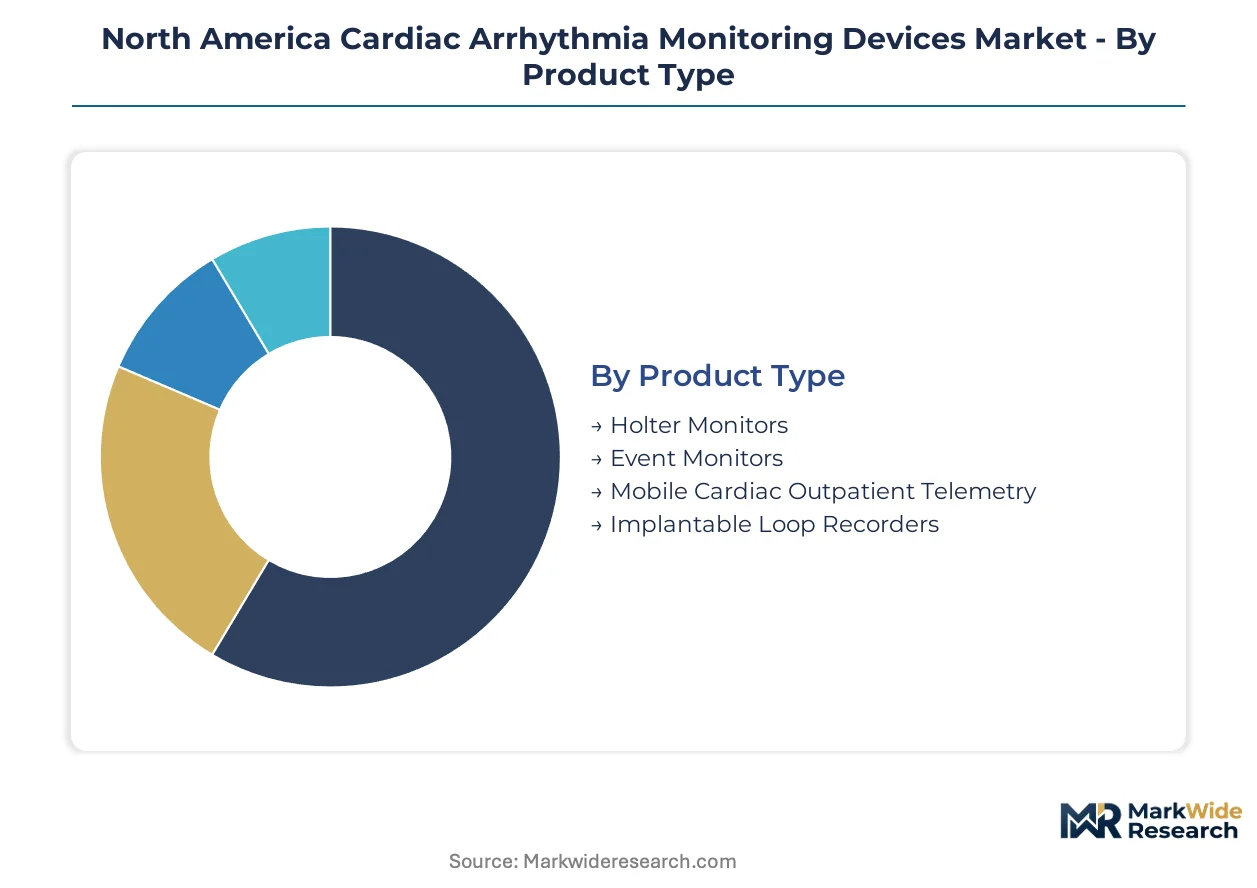
Segmentation in cardiac arrhythmia monitoring reveals divergent capital requirements and reimbursement pathways across device modalities. Hospital procurement committees weight upfront hardware costs against per-patient service revenue when allocating budgets across product categories.
Product Type:
Implantable loop recorders demand the heaviest upfront capital commitment, requiring sterile surgical infrastructure and electrophysiology suite access. Holter monitors operate at the opposite extreme, with minimal capital barriers enabling broad clinic deployment.
- Holter Monitors:Portable external devices record continuous ECG data over 24–48 hours through adhesive electrode arrays. Demand concentrates in community cardiology practices across the southeastern United States, where Medicare reimbursement simplicity drives preference for established diagnostic protocols.
- Implantable Loop Recorders:Subcutaneous devices provide extended monitoring up to three years via battery-powered sensing circuits. Hospital networks in Florida and Georgia are expanding cryptogenic stroke programs, where prolonged arrhythmia detection justifies surgical implantation costs.
- Event Monitors:Patient-activated or auto-triggered external recorders capture symptomatic episodes.
- Mobile Cardiac Outpatient Telemetry:Real-time cellular transmission systems enable immediate clinician notification during arrhythmic events.
Most installed capacity flows through Holter Monitors. Expansion is steepest in Implantable Loop Recorders.
End User:
Customer type determines purchasing authority complexity, with integrated delivery networks consolidating procurement across multiple sites while independent practices negotiate device-as-a-service arrangements.
- Hospitals:Acute care facilities deploy comprehensive telemetry infrastructure spanning emergency departments, step-down units, and catheterization laboratories. Multi-year service contracts with major health systems in Texas and California bundle device procurement with continuous monitoring support.
- Cardiology Practices:Outpatient electrophysiology groups generate recurring revenue through ambulatory monitoring interpretation. Independent practices in the Midwest face exclusion from hospital purchasing coalitions and rely on specialized monitoring company partnerships.
- Specialty Clinics:Focused cardiovascular centers concentrate high-volume diagnostic workflows.
- Home Care:Post-acute and hospice settings utilize simplified monitoring for remote patient surveillance.
Revenue concentration sits with Hospitals. Patient volume expansion is climbing fastest in Home Care.
Technology:
Technology segmentation separates legacy wired systems from wireless and cloud-native architectures, with differentiation increasingly driven by data integration capabilities rather than raw sensing performance.
- Wireless Monitoring:Radiofrequency and cellular transmission systems eliminate bedside tethering while enabling real-time alert generation. Ambulatory surgery centers in New York and California are restructuring service lines to capture newly reimbursable synchronous encounters under evolving CMS telehealth parity rules.
- Cloud-based Solutions:Centralized data repositories with AI-enhanced ECG analysis reduce clinic administrative burden through automated preliminary interpretation. Community health systems in Arizona deploy these systems to compress time-to-diagnosis from days to hours.
- Electrocardiogram:Conventional wired electrode systems retain dominance in perioperative settings.
- Wearable Devices:Consumer-form-factor patches and watches extend monitoring into patient daily routines.
Diagnostic throughput concentrates in Cloud-based Solutions. Capability investment is accelerating most rapidly in Wearable Devices.
Application:
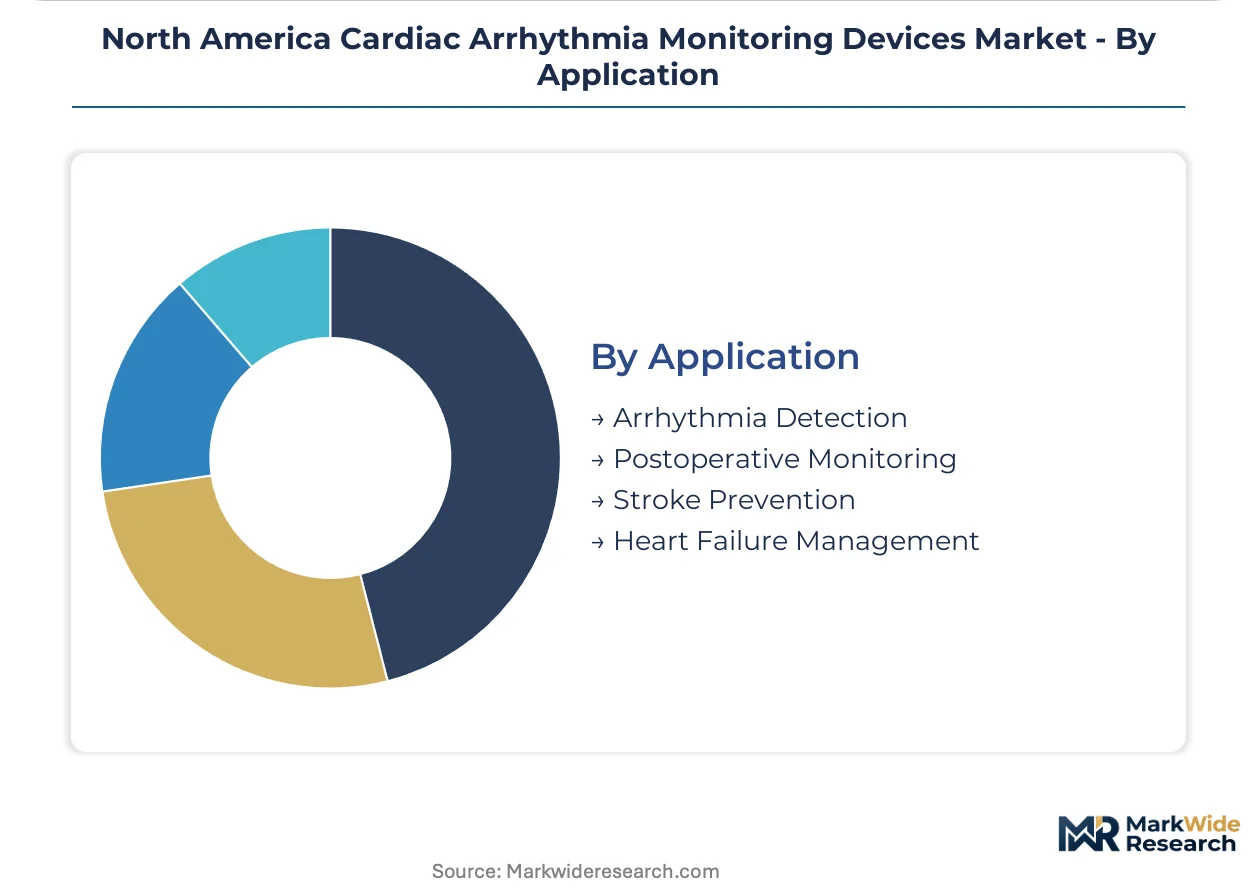
Clinical application determines monitoring duration requirements and reimbursement coding complexity, with stroke prevention protocols driving extended-duration implantable device adoption.
- Arrhythmia Detection:Primary diagnostic indication spans atrial fibrillation, ventricular tachycardia, and bradyarrhythmia identification through multi-day to multi-year monitoring protocols. Cardiology networks across North Carolina prioritize this application in aging patient populations with cryptogenic symptoms.
- Stroke Prevention:Extended monitoring in cryptogenic stroke patients seeks occult atrial fibrillation to guide anticoagulation decisions. Hospital systems in Florida embed implantable loop recorders into comprehensive stroke center protocols.
- Postoperative Monitoring:Surveillance following cardiac surgery or ablation procedures detects procedural complications.
- Heart Failure Management:Integration of arrhythmia data with hemodynamic monitoring guides medication titration.
Procedure volume concentrates in Arrhythmia Detection. Protocol adoption is broadening fastest in Stroke Prevention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophysiology fellowship programs concentrate in the northeastern United States, anchoring interpretation capacity for high-volume telemetry services across the continent.
United States
Hospital network consolidation in Texas and California compresses vendor relationships into multi-year telemetry service agreements. FDA 510(k) pathway streamlining accelerates wearable ECG patch commercialization for ambulatory monitoring innovators. The southeastern cluster spanning Florida, Georgia, and North Carolina drives implantable loop recorder deployment through aging demographics and expanding cryptogenic stroke protocols.
Canada
Health Canada's streamlined medical device licensing creates entry pathways for US-cleared monitoring technologies. Provincial health authorities in Ontario and Quebec negotiate centralized procurement for cardiac telemetry services across integrated delivery networks. The Toronto-Waterloo corridor hosts emerging digital health ventures developing cloud-connected diagnostic workflows.
Mexico
Private hospital chains in Mexico City and Monterrey import US-manufactured Holter monitors and event recorders for affluent patient segments. COFEPRIS regulatory alignment with FDA standards reduces time-to-market for wearable monitoring devices. Medical tourism corridors in Jalisco and Baja California deploy ambulatory cardiac monitoring for pre-operative cardiac clearance protocols.
North America Cardiac Arrhythmia Monitoring Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the North America Cardiac Arrhythmia Monitoring Devices Market. Medtronic, Abbott Laboratories, and GE Healthcare anchor the consolidated tier through integrated device-service platforms and electrophysiology ecosystem control. The vendor base separates into three strategic archetypes: full-stack health systems suppliers, ambulatory-focused diagnostic pure-plays, and component technology licensors. Competitive dynamics center on multi-year hospital telemetry contracts and cloud-native diagnostic workflow integration.
Among diversified medical technology conglomerates, Medtronic and Abbott Laboratories exemplify the integrated platform archetype spanning implantable, wearable, and stationary monitoring modalities. iRhythm Technologies occupies a distinct position within the ambulatory pure-play tier, representing cloud-connected patch-based diagnostic workflows. These three companies anchor the competitive structure through contrasting approaches to hospital procurement consolidation and clinic administrative burden reduction.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| GE Healthcare |
| Koninklijke Philips NV |
| iRhythm Technologies |
| BioTelemetry |
| Boston Scientific |
| ACS Diagnostics |
| Cardiac Science Corporation |
| Others |
Value Chain & Pricing Dynamics
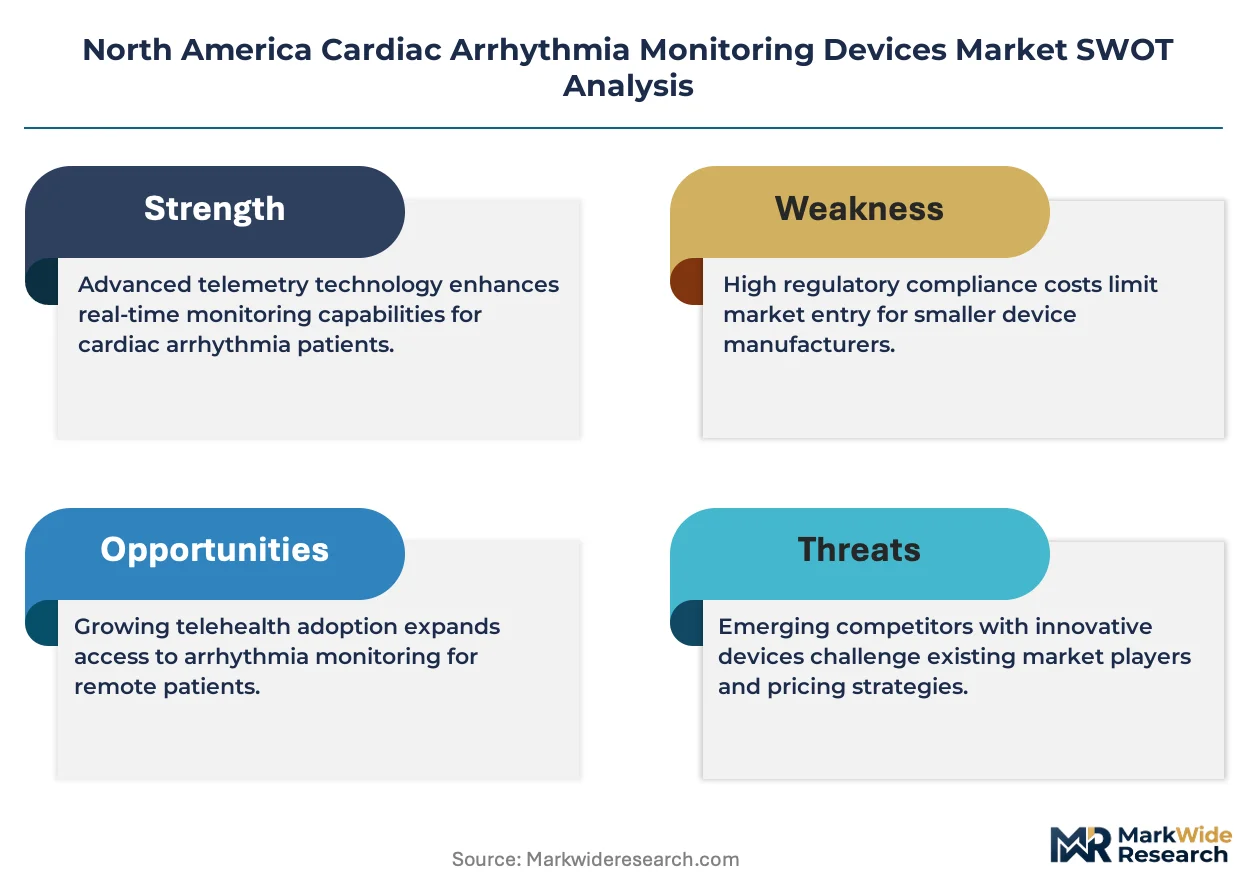
Captive semiconductor fabrication for wireless transmission chipsets anchors supply security for premium telemetry device manufacturers while insulating them from foundry pricing volatility. Hospital network consolidation across the southeastern United States concentrates procurement leverage, compressing margins for vendors without integrated service platforms.
Pricing Analysis
Capacity additions in Taiwanese foundries are reshaping price floors for wireless chipset components embedded in cardiac monitoring devices. Three-tier pricing structure across premium real-time telemetry, standard Holter monitoring, and economy event recorder tiers reflects FDA clearance tier and after-sales service bundling. Pricing pressure stems from GPO-negotiated multi-year hospital contracts that commoditize hardware margins. Independent cardiology practices in the Midwest exhibit highest price sensitivity, while integrated delivery networks in Texas prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Microcontroller and Bluetooth Low Energy module supply rests on Taiwanese, South Korean, and Chinese semiconductor fabricators. Lithium-polymer battery cells, medical-grade adhesives, and biocompatible polymers constitute critical input dependencies. Single-source vulnerability concentrates in advanced node wireless chipsets subject to export control restrictions. Distribution runs through specialized medical device distributors serving hospital IDNs and direct-to-clinic arrangements for ambulatory monitoring pure-plays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are tightening as stroke prevention protocols demand extended-duration implantable monitoring with diagnostic-grade signal fidelity. This shift favors vendors with vertically integrated manufacturing and regulatory affairs infrastructure.
For Market Incumbents: Lock in electrophysiologist training partnerships to secure interpretation capacity for high-volume telemetry services. Consolidate cloud-native diagnostic workflow acquisitions to neutralize AI-enhanced ECG pure-plays threatening service revenue pools. Backward integration into wireless chipset design reduces exposure to Asian foundry concentration.
For New Entrants and Emerging Players: Ambulatory surgery centers in California and New York represent the most penetrable channel partner type for synchronous telehealth-enabled monitoring services. Target cryptogenic stroke protocol expansion in Florida and Georgia hospital systems where implantable loop recorder adoption outpaces specialist interpretation capacity. Pursue FDA 510(k) clearance for wearable patches with automated preliminary interpretation to reduce clinic administrative burden.
For Investors and Strategic Acquirers: Roll-up economics work for ambulatory diagnostic pure-plays because hospital procurement consolidation fragments the independent cardiology practice vendor base. Five-to-ten year viability hinges on cloud-connected workflow integration and state-level scope-of-practice expansion for nurse-led interpretation. Watch CMS national coverage determination timelines for novel monitoring modalities as the inflection signal for capital expenditure cycle reactivation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Streamlining | Expedited wearable ECG patch clearance accelerates commercialization for ambulatory monitoring innovators targeting southeastern US cardiology networks. |
| Hospital System Partnership | Multi-year telemetry service agreements with Texas and California IDNs bundle device procurement with continuous monitoring support. |
| Software Companion Development | AI-enhanced ECG analysis integration with Epic and Cerner EHR systems reduces clinic administrative burden in Arizona community health systems. |
| Reimbursement Strategy | CMS telehealth parity rule alignment enables synchronous physician-patient encounters during arrhythmia episodes in New York ambulatory surgery centers. |
| CE Marking Pathway | Health Canada streamlined licensing creates entry pathway for US-cleared monitoring technologies into Ontario and Quebec provincial health networks. |
Study Parameters
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market. Electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided qualitative intelligence through structured interviews. Secondary validation drew from FDA 510(k) filings, CMS national coverage determinations, hospital procurement databases, and GPO contract disclosures. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation anchored market size estimation.
Rate-of-change decomposition across the projection horizon separates volume expansion from pricing dynamics and mix shifts. Segmentation modeling captured product type, end user, technology, and application dimensions alongside regional regulatory cluster variations. CAGRs derived from fitted growth curves applied to procedural volume forecasts and reimbursement trajectory assumptions. Cryptogenic stroke protocol adoption rates and electrophysiology fellowship graduation counts served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS reimbursement rule evolution and semiconductor supply chain reshoring progress. Assumptions reflect current regulatory and macroeconomic conditions. FDA advisory committee composition shifts, foundry capacity allocation decisions, and state-level scope-of-practice legislation represent triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Remote Patient Monitoring Software Market
Patient Monitoring
Telemonitoring Systems Market
Patient Monitoring
Fetal and Neonatal Heart Monitor Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Global IOT Sensors in Healthcare Market
Patient Monitoring
South America Respiratory Monitoring Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
Mobile Heart Monitoring Market
Patient Monitoring
Dehydration Monitoring Systems Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
South Africa Patient Monitoring Market