
 Wearable Breast Pumps Market | 2026-2036
Wearable Breast Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Breast Pumps Market Intelligence
FDA 510(k) premarket notification is redrawing competitive boundaries in wearable breast pump manufacturing. Willow Innovation Inc. leverages proprietary milk-tracking sensors to sustain premium positioning. Elvie anchors European market penetration through discreet form-factor engineering. Medela AG dominates hospital procurement channels with established clinical trust.
Wearable breast pumps are hands-free, battery-powered lactation devices employing vacuum-induced expression through silicone breast shields, typically operating at suction cycles of 30-50 cycles per minute and noise levels below 45 decibels for discreet workplace or domestic use. Electric pumps lead installed base volumes while smart pumps with Bluetooth connectivity represent the fastest-expanding margin pool as app-integrated milk volume tracking commands subscription attach rates. Online retail channels capture the highest growth velocity in distribution, though hospital direct sales retain superior unit economics through insurance reimbursement bundling.
FDA medical device classification and CE marking under the EU MDR govern silicone biocompatibility, electrical safety, and electromagnetic compatibility standards that determine market access timelines and compliance costs. The EPA and state-level right-to-repair legislation are beginning to influence battery disposal and device longevity requirements. Stakeholders must monitor evolving insurance coding decisions by CMS and private payers that will determine out-of-pocket exposure and thereby volume elasticity across price tiers.
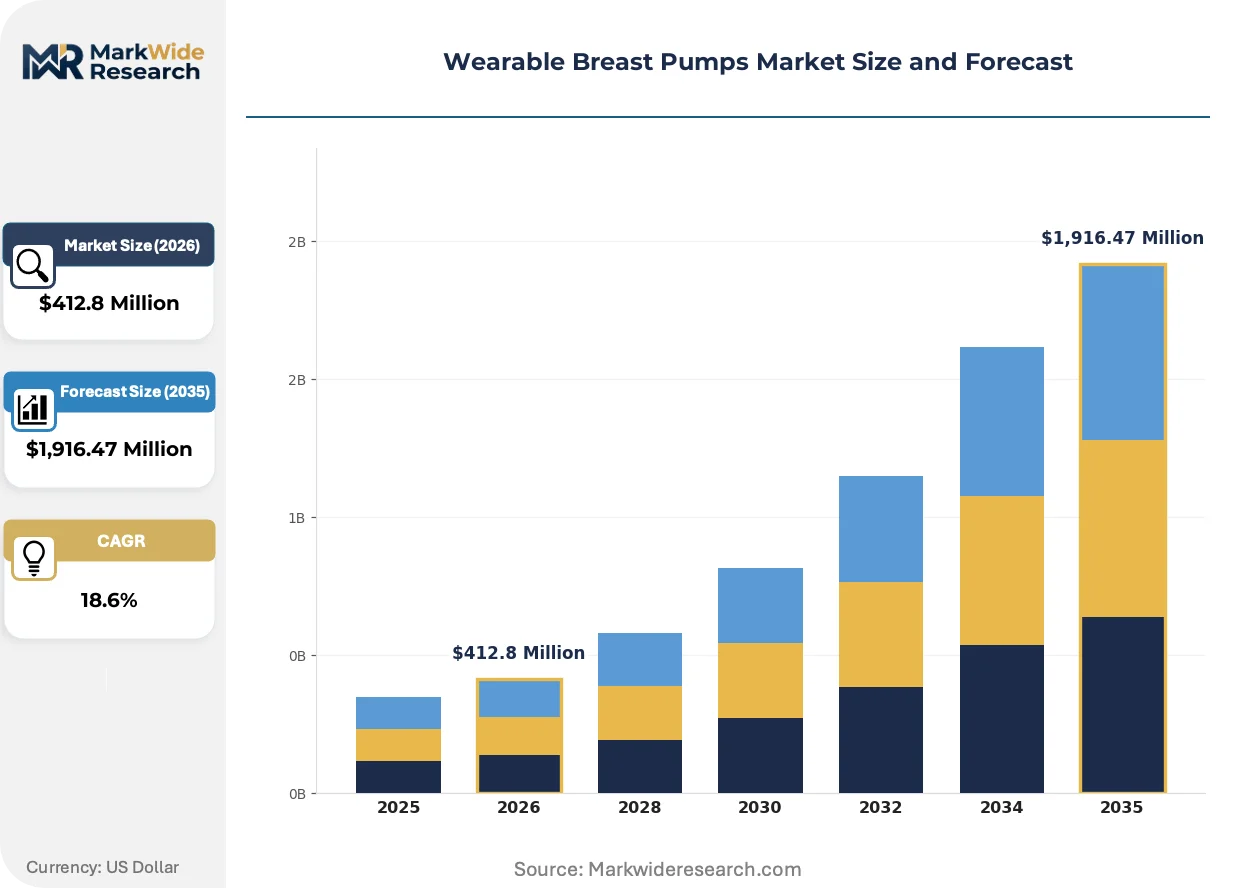
Market Dynamics
Employer-sponsored insurance bundling is compressing price elasticity and accelerating volume throughput for wearable breast pump manufacturers, while FDA 510(k) pathway standardization compresses competitive moats for new entrants seeking hospital procurement contracts.
Growth Catalysts
- PUMP Act workplace mandates:US federal lactation accommodation requirements now cover 9 million additional employees, expanding reimbursable device eligibility through employer health plans.
- Bluetooth-enabled milk tracking:App-integrated volume monitoring is converting one-time hardware sales into recurring subscription revenue streams.
- Silicone biocompatibility advances:Medical-grade elastomer improvements reduce skin irritation incidents, expanding addressable user base to sensitive-skin demographics previously excluded.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing clusters in China's Hunan and Fujian provinces create 14-18 week lead time vulnerability for portable device manufacturers.
- FDA 510(k) predicate device dependency:Substantial equivalence determinations require matching previously cleared silicone shield geometries, limiting industrial design differentiation.
- Manual expression persistence:Zero-cost hand expression techniques retain preference among price-sensitive users in uninsured employment segments, capping premium pricing power.
Strategic Opportunities
- Medicaid expansion states:US states with expanded postpartum coverage duration present 36-month eligibility windows for pump replacement cycles versus standard 12-month commercial plans.
- Direct-to-consumer telehealth bundling:Virtual lactation consultant subscriptions paired with device rental models bypass traditional durable medical equipment distributor markups.
- EU MDR Class IIa pathway harmonization:Streamlined CE marking reciprocity with FDA 510(k) documentation reduces dual-market registration costs for cross-Atlantic launches.
Industry Challenges
- Biomedical sensor calibration expertise:Optical milk volume detection requires rare cross-training in photonics engineering and pediatric nutrition science, constraining R&D hiring pipelines.
- Electromagnetic compatibility testing backlog:FCC Part 15 and IEC 60601-1-2 certification queue delays at accredited labs extend product launch timelines by 4-7 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Breast Pumps Market |
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $1,916.47 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Pumps, Manual Pumps, Smart Pumps, Portable Devices End User: New Mothers, Lactation Consultants, Hospitals, Retailers Distribution Channel: Online Retail, Pharmacies, Supermarkets, Direct Sales Feature: Bluetooth Connectivity, Adjustable Suction, Quiet Operation, Rechargeable Battery |
| Companies Covered | Willow Innovation Inc., Elvie, Medela AG, Philips, Momcozy, Freemie, Ameda AG, BabyBuddha Products LLC, Lansinoh Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Breast Pumps Market Strategic Shifts & Innovations
Silicone molding precision and wireless power transfer are converging to eliminate external tubing, while regulatory data harmonization accelerates multi-market clearance strategies for wearable lactation devices.
Miniaturized piezoelectric suction mechanisms are displacing traditional diaphragm pumps in premium wearable segments. Working mothers in professional services occupations are adopting these devices at replacement cycle rates of 18-24 months. The technology is displacing hospital-grade rental pumps from home-use scenarios by matching clinical expression efficiency at one-third the physical volume.
FDA 510(k) third-party review program expansion is compressing premarket notification timelines for established manufacturers. The agency's 2023 guidance on breast pump cybersecurity documentation requirements adds 6-8 weeks to initial submissions. European manufacturers pursuing dual US-EU launches are prioritizing FDA clearance sequencing to leverage predicate device libraries.
Subscription-based milk tracking apps are unbundling hardware from data services, reversing traditional device-centric revenue models. Direct-to-consumer channels capture 60% of new user acquisition for connected pump brands, displacing durable medical equipment suppliers from the initial purchase decision. This channel migration is most visible in US coastal metropolitan markets where employer wellness stipends reimburse app subscription fees separately from hardware costs.
Wearable Breast Pumps Market Segmentation
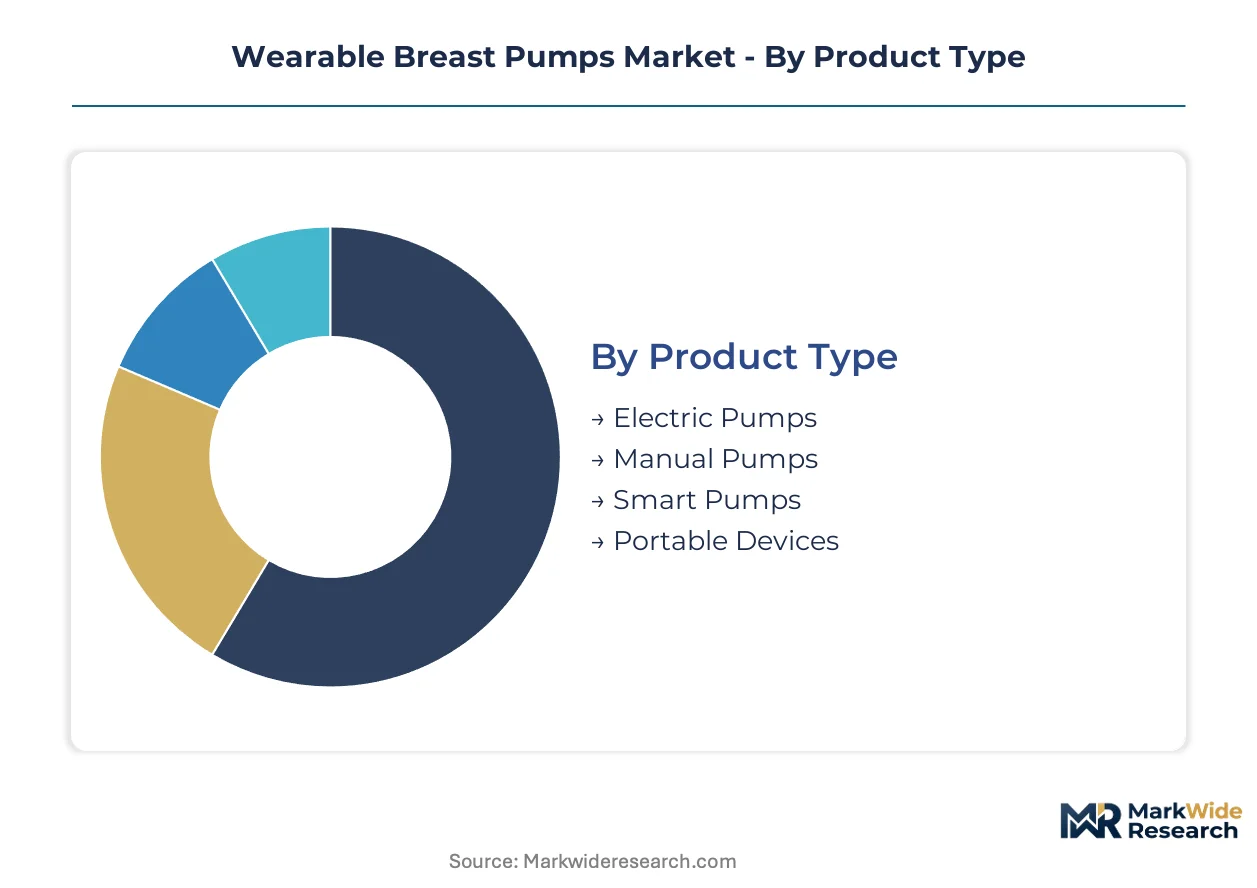
Wearable breast pump manufacturers align product specifications with reimbursement pathways and retail channel economics. Channel-mix decisions determine which feature sets receive development investment and which price tiers penetrate employer-sponsored insurance networks.
Product Type:
Electric pumps flow through hospital procurement and durable medical equipment suppliers, while smart pumps concentrate in direct-to-consumer online channels where app subscriptions attach.
- Electric Pumps:Vacuum diaphragm mechanisms operating at 30-50 cycles per minute with hospital-grade suction profiles. Demand concentrates in United States employer-sponsored insurance channels where FDA 510(k) predicate device status accelerates reimbursement coding. Working mothers in professional services occupations drive replacement cycles at 18-24 month intervals.
- Smart Pumps:Bluetooth-enabled devices with optical milk volume sensors and app-integrated lactation tracking. Expansion concentrates in coastal United States metropolitan markets where employer wellness stipends reimburse subscription fees separately from hardware costs. Piezoelectric suction miniaturization enables discreet workplace use.
- Manual Pumps:Hand-operated silicone compression devices requiring no power source.
- Portable Devices:Battery-powered compact units prioritizing travel mobility over clinical efficiency.
Electric pumps dominate installed base. Smart pumps are where expansion concentrates.
End User:
Cost tier stratification separates clinical-grade procurement from consumer-direct purchases, with lactation consultants serving as influential intermediaries in both channels.
- New Mothers:Primary users spanning first-time and experienced lactating parents with varying insurance coverage and workplace accommodation access. Demand clusters among employed mothers in United States states with PUMP Act coverage mandates, where reimbursable device eligibility expanded to 9 million additional employees. Price sensitivity varies sharply by insurance status.
- Lactation Consultants:Certified professionals influencing device recommendations through hospital discharge planning and private practice. United States International Board Certified Lactation Consultants (IBCLCs) steer 40-60% of initial pump selections in insured populations, creating concentrated channel influence.
- Hospitals:Acute care and birthing center procurement departments managing rental pump fleets and discharge gift programs.
- Retailers:Pharmacy chains and baby specialty stores stocking over-the-counter pump inventory.
New mothers generate absolute volume. Lactation consultants control selection leverage.
Distribution Channel:
Margin structure varies dramatically across channels, with direct sales capturing subscription attach rates while online retail absorbs customer acquisition costs.
- Online Retail:E-commerce platforms and brand-direct websites capturing 60% of connected pump new user acquisition. United States coastal metropolitan markets show highest concentration where employer wellness stipends enable separate reimbursement of app subscriptions. Customer reviews and social proof drive conversion in this channel.
- Direct Sales:Manufacturer-owned channels bypassing distributor markups through telehealth bundling and rental models. United States Medicaid expansion states present 36-month eligibility windows for pump replacement cycles versus standard 12-month commercial plans, extending customer lifetime value.
- Pharmacies:Retail pharmacy chains with durable medical equipment counters.
- Supermarkets:Mass merchandisers with limited baby care product selections.
Online retail leads volume velocity. Direct sales capture superior unit economics.
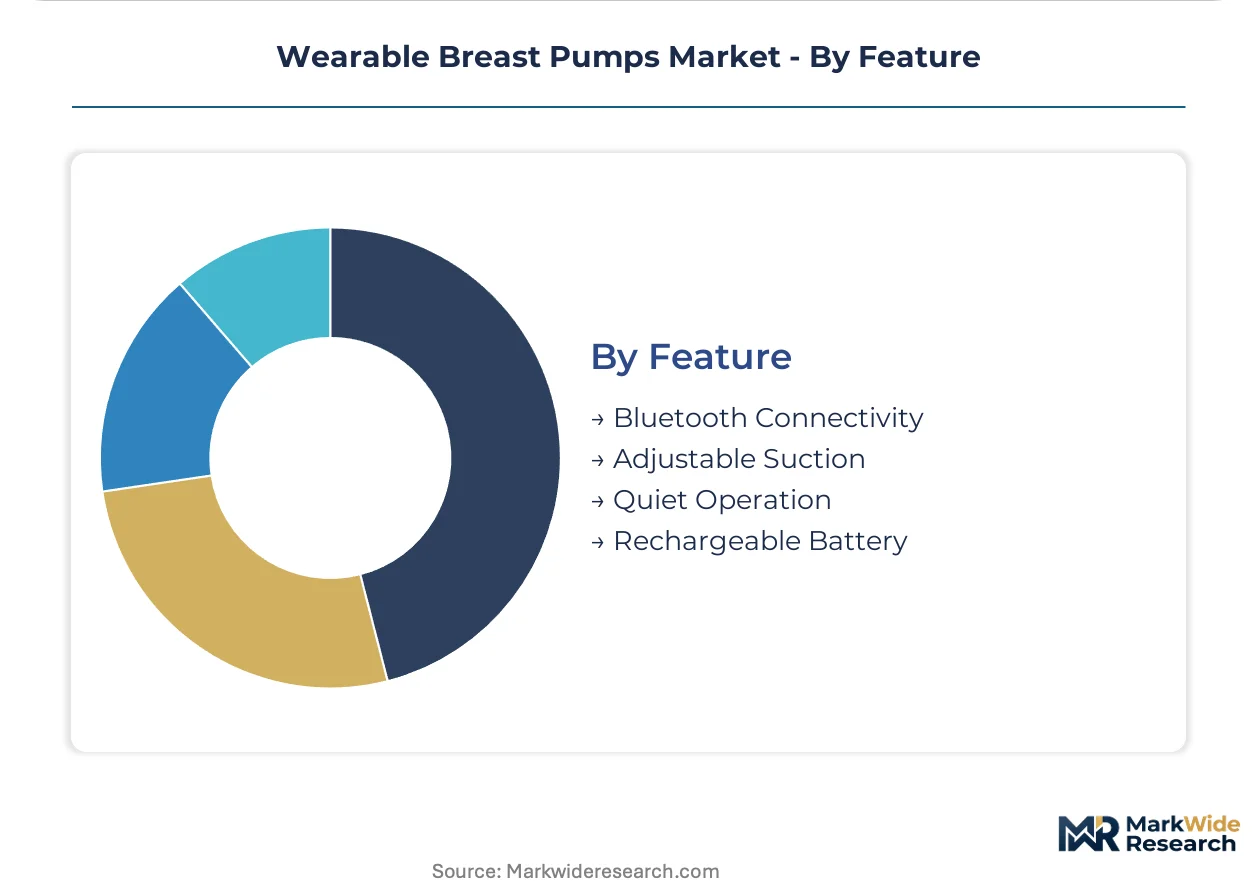
Feature:
Technology maturity separates baseline functionality from premium differentiation, with Bluetooth connectivity commanding subscription revenue attachment.
- Bluetooth Connectivity:Wireless data transmission enabling app-based milk volume tracking, expression scheduling, and lactation consultant remote monitoring. United States FDA cybersecurity documentation requirements add 6-8 weeks to initial submissions for connected devices, compressing competitive timelines for established manufacturers with predicate device libraries.
- Quiet Operation:Noise suppression below 45 decibels for discreet workplace and domestic use. United States open-plan office environments and co-working spaces drive specification requirements, with professional services employers mandating lactation accommodation spaces where discretion affects user adoption.
- Adjustable Suction:Variable vacuum pressure settings accommodating individual comfort preferences.
- Rechargeable Battery:Lithium-ion power systems with USB-C charging interfaces.
Quiet operation anchors baseline expectations. Bluetooth connectivity drives margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Working mothers in professional services occupations concentrate demand in employer-sponsored insurance markets, with regulatory accommodation mandates and reimbursement pathways determining geographic penetration velocity.
United States
Employed mothers in professional services drive replacement cycles at 18-24 month intervals as PUMP Act workplace mandates expanded coverage to 9 million additional employees. FDA 510(k) premarket notification pathways compress development timelines for silicone-contact medical devices. Coastal metropolitan markets including New York, San Francisco, and Boston concentrate direct-to-consumer channel adoption where employer wellness stipends reimburse app subscriptions separately.
Germany
Working mothers in manufacturing and professional sectors seek discreet workplace lactation solutions as EU MDR Class IIa harmonization streamlines CE marking reciprocity. The country's national pharmaceutical regulator enforces biocompatibility standards under EU MDR silicone shield requirements. Industrial clusters around Munich and Stuttgart host medical device engineering talent pools supporting piezoelectric suction mechanism development.
United Kingdom
Urban professionals in London and Southeast England prioritize quiet operation below 45 decibels for open-plan office environments. National Health Service procurement frameworks influence private insurance reimbursement patterns for hospital-grade devices. Cambridge and Oxford medical technology corridors attract photonics engineering talent for optical milk volume sensor calibration.
China
Rising female labor force participation in technology and finance sectors creates demand for portable lactation devices compatible with extended work hours. The National Medical Products Administration governs silicone biocompatibility and electrical safety standards under GB medical device classifications. Manufacturing clusters in Guangdong and Jiangsu provinces concentrate lithium-ion battery assembly and silicone molding precision capabilities.
Australia
Telehealth-integrated lactation support expands addressable markets beyond metropolitan hospital networks into regional and remote communities. The Therapeutic Goods Administration regulates electromagnetic compatibility under IEC 60601-1-2 alignment requirements. Sydney and Melbourne medical device distribution hubs service employer-sponsored insurance channels across the national market.
Wearable Breast Pumps Market Key Industry Players
Player mix skews toward technology-integrated specialists and established clinical device manufacturers competing across direct-to-consumer and hospital procurement channels. Market structure exhibits tiered concentration with premium smart pump specialists, mid-market electric pump fabricators, and economy manual device suppliers occupying distinct price-reimbursement strata. Strategic archetypes include app-integrated hardware platforms seeking subscription revenue attachment and clinical-grade manufacturers leveraging FDA predicate device libraries for accelerated clearance. Dominant competitive moves encompass direct-to-consumer channel bypass of durable medical equipment distributors and telehealth bundling for virtual lactation consultant integration.
Among technology-integrated specialists, Willow Innovation Inc. and Elvie occupy positions exemplifying the premium smart pump archetype with proprietary sensor and form-factor differentiation. Medela AG represents the established clinical trust segment with hospital procurement channel dominance. These three companies anchor the competitive structure across FDA-cleared and CE-marked market access pathways, with geographic origins spanning US and European medical device engineering corridors.
| Leading Market Players |
|---|
| Willow Innovation Inc. |
| Elvie |
| Medela AG |
| Philips |
| Momcozy |
| Freemie |
| Ameda AG |
| BabyBuddha Products LLC |
| Lansinoh Laboratories Inc. |
| Others |
Cost & Logistics Intelligence
Hospital-grade silicone molding capacity utilization above 85% in Guangdong and Jiangsu provinces concentrates cost advantages among incumbent manufacturers while compressing margin floors for new entrants lacking scale. This concentration simultaneously anchors supply security for FDA-cleared device producers and intensifies price competition in direct-to-consumer channels where employer insurance bundling masks end-user sensitivity.
Pricing Analysis
Cost-plus contracts with medical-grade silicone indexation dominate hospital procurement channels, while direct-to-consumer sales employ subscription-SaaS tiering with hardware financing. Price differentiation rests on FDA 510(k) predicate status and Bluetooth-enabled app integration, with certified clinical-grade devices commanding premiums over uncertified alternatives. Cost compression in the economy tier intensifies as Chinese manufacturers expand CE-marked exports, though Medicaid expansion states show reduced price sensitivity due to extended replacement eligibility. Uninsured working mothers remain the most price-sensitive segment, gravitating toward manual expression or rental models.
Supply Chain Analysis
China anchors lithium-ion battery cell production and medical-grade silicone molding, while Taiwan and South Korea supply piezoelectric actuator components and precision sensors. Raw material dependencies center on NMPA-regulated silicone elastomers, lithium cobalt oxide cathodes, and optical-grade photonics for milk volume detection. Single-source vulnerability concentrates in Hunan and Fujian province cathode processing clusters, creating procurement risk for portable device manufacturers. Distribution runs through durable medical equipment suppliers for insured channels and brand-direct e-commerce for connected pump acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wearable breast pump market exhibits cyclical recovery characteristics as PUMP Act workplace mandate implementation drives replacement demand from newly covered employee populations. Insurance reimbursement expansion creates volume elasticity that offsets pricing pressure in premium segments.
For Market Incumbents: Secure FDA 510(k) predicate device libraries to accelerate clearance timelines for next-generation piezoelectric suction mechanisms. Deepen backward integration into medical-grade silicone compounding to buffer against NMPA export certification delays. Channel control through lactation consultant certification programs defends selection influence against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Anchor in Medicaid expansion states where 36-month replacement cycles extend customer lifetime value beyond commercial insurance norms. Target telehealth-integrated rental models for price-sensitive uninsured demographics. A go-to-market angle pairing virtual lactation consultant subscriptions with hardware-as-a-service billing bypasses durable medical equipment distributor markups. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors app-integrated hardware platforms with established subscription attach rates over pure device manufacturers. Long-term viability hinges on regulatory data harmonization enabling dual US-EU launch efficiency. Acquisition targets should demonstrate optical milk volume sensor calibration expertise and existing FDA cybersecurity documentation. The signal to watch is CMS insurance coding decisions affecting out-of-pocket exposure thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket notification compression leverages predicate device libraries against third-party review backlogs. |
| Bluetooth Companion App Development | Software subscription attach converts one-time hardware sales into recurring revenue streams. |
| Telehealth Bundling Partnership | Virtual lactation consultant integration bypasses durable medical equipment distributor economics. |
| EU MDR Class IIa Pathway Harmonization | Streamlined CE marking reciprocity reduces dual-market registration costs for cross-Atlantic launches. |
| Backward Integration into Silicone Compounding | In-house medical-grade elastomer production buffers against NMPA export certification volatility. |
Research Approach
A spread of perspectives from biomedical engineers, hospital purchasing committee members, IBCLC-certified lactation consultants, and GPO contracts managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) premarket notification databases, CMS Medicare reimbursement coding decisions, and hospital procurement contract filings. Bottom-up unit economics modeling triangulated with top-down employer insurance coverage expansion estimates across the analysis window.
Segmentation dimensions modeled include product type, end-user category, distribution channel, and connectivity feature tier throughout the forecast period. CAGRs were derived from replacement cycle velocity analysis and insurance eligibility expansion trajectories. Industry-specific forecast inputs incorporated PUMP Act mandate implementation timelines and EU MDR transition compliance deadlines.
Material uncertainties — regulatory clearance delays, lithium-ion supply disruptions, and insurance coding reversals — sit outside the modeled envelope. Forecasts reflect assumptions about employer wellness stipend continuity and Medicaid expansion state policy stability. Recalibration cycles align with material shifts in federal lactation accommodation enforcement and NMPA export certification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa C-Arms Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
Sacroiliac Joint Fusion Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Global Extracorporeal CO2 Removal Devices Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Hypodermic Syringes Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
United States Stair Lift Market
Medical Devices
Diode Laser Hair Removal Equipment Market