
 United States Stair Lift Market | 2026-2036
United States Stair Lift Market Size, Share, and Industry Trends Forecast 2026-2036
United States Stair Lift Market Analytics
ASME A18.1 safety standards for platform lifts and stairway chairlifts is redrawing competitive boundaries in the United States stair lift industry. Bruno Independent Living Aids leverages extensive dealer networks across the Southeast and Midwest to sustain installation capacity. Handicare Group anchors its position through vertical integration from manufacturing to direct service operations. Stannah Lifts Holdings differentiates via custom curved rail fabrication capabilities that competitors struggle to replicate.
A stair lift is a motorized seating platform mounted on a rail system that transports individuals with mobility limitations between floor levels, typically operating on DC battery power with rack-and-pinion or cable drive mechanisms rated for inclines up to 52 degrees. Straight stair lifts dominate volume sales due to standardized rail extrusions and rapid installation timelines, while curved stair lifts command premium positioning because each rail requires site-specific engineering and CNC bending. Residential users generate the largest addressable base, though healthcare facilities represent a faster-expanding channel as hospitals discharge patients earlier to reduce readmission penalties.
FDA oversight of stair lifts as medical devices, combined with state-level Medicaid waiver programs and local building code enforcement, creates a multi-layered compliance environment that elevates barriers for new entrants. OSHA workplace safety standards also influence commercial installation protocols and technician certification requirements. Stakeholders must monitor evolving Medicare Advantage supplemental benefit structures, as these plans increasingly cover home modification equipment that traditional fee-for-service Medicare excludes.
Market Dynamics
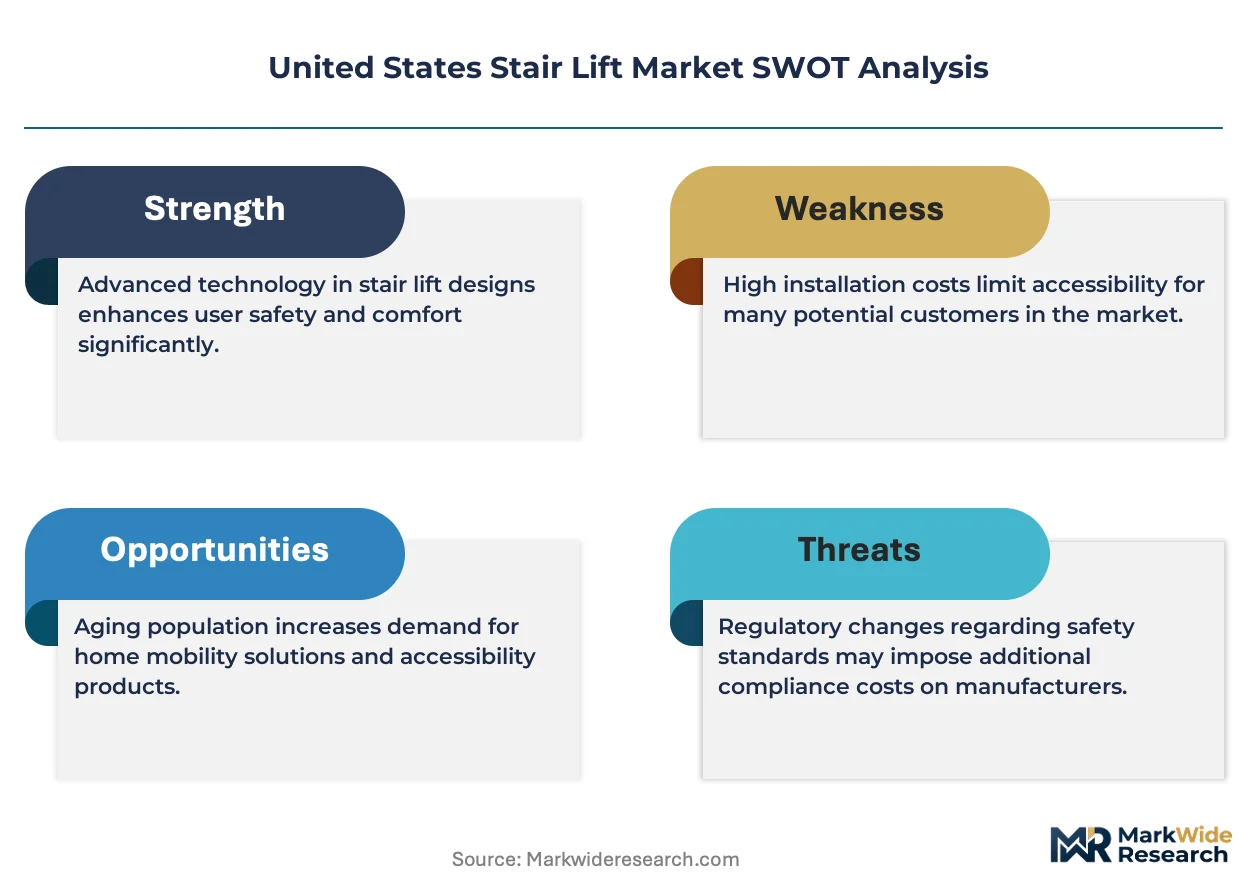
The United States stair lift market is being fundamentally restructured by the collision of Medicare Advantage supplemental benefit expansion with state Medicaid waiver program fragmentation, creating divergent reimbursement pathways that favor vertically integrated service providers over pure equipment vendors.
Growth Catalysts
- Medicaid HCBS Waivers:State-level Home and Community-Based Services waivers in Florida, Arizona, and California now explicitly cover stair lift installations for aging-in-place beneficiaries, expanding addressable demand beyond traditional out-of-pocket purchasers.
- DC Battery Systems:Lithium-ion battery packs with smart charge management are eliminating the power-outage vulnerability that historically stalled residential adoption in hurricane-prone coastal markets.
- ASME A18.1 Compliance Mandates:Updated safety standards for platform lifts and stairway chairlifts are forcing facility retrofits in commercial buildings, particularly in multi-story healthcare clinics and assisted living properties.
Market Restraints
- Aluminum Extrusion Cost Volatility:Rail system manufacturers face margin compression from fluctuating primary aluminum prices and limited domestic smelter capacity, with Midwest fabricators particularly exposed to Midwest power grid pricing spikes.
- Curved Rail Engineering Bottleneck:CNC bending capacity for custom curved stair lift rails concentrates among a handful of specialized metalworking shops in the Great Lakes region, creating 6-10 week order backlogs during peak remodeling seasons.
- FDA Medical Device Classification:Stair lifts regulated as Class I medical devices require 510(k) clearance pathways and quality system documentation that elevates compliance costs for new market entrants without grandfathered predicate devices.
Strategic Opportunities
- Medicare Advantage Supplemental Benefits:MA plans covering home modification equipment that traditional fee-for-service Medicare excludes are opening reimbursement channels in Texas, Pennsylvania, and Ohio where MA penetration exceeds 50% of eligible beneficiaries.
- Smart Home Integration:IoT-enabled stair lifts with voice control and predictive maintenance algorithms are converging with Amazon Alexa and Google Home ecosystems, appealing to tech-forward adult children purchasing for aging parents.
- Home Healthcare Agency Channel:Hospital-at-home discharge programs are creating bundled equipment procurement relationships where agencies specify stair lifts as part of comprehensive fall-risk reduction protocols.
Industry Challenges
- Certified Technician Shortage:OSHA-compliant installation requires technicians holding ASME A17.1/A18.1 certifications that fewer than 2,000 professionals hold nationwide, constraining peak-season deployment capacity in Sun Belt retirement corridors.
- Legacy Electrical Infrastructure:Pre-1980s residences with knob-and-tube wiring or 60-amp service panels require costly electrical upgrades before stair lift installation, extending sales-to-revenue cycles and increasing customer acquisition costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Stair Lift Market |
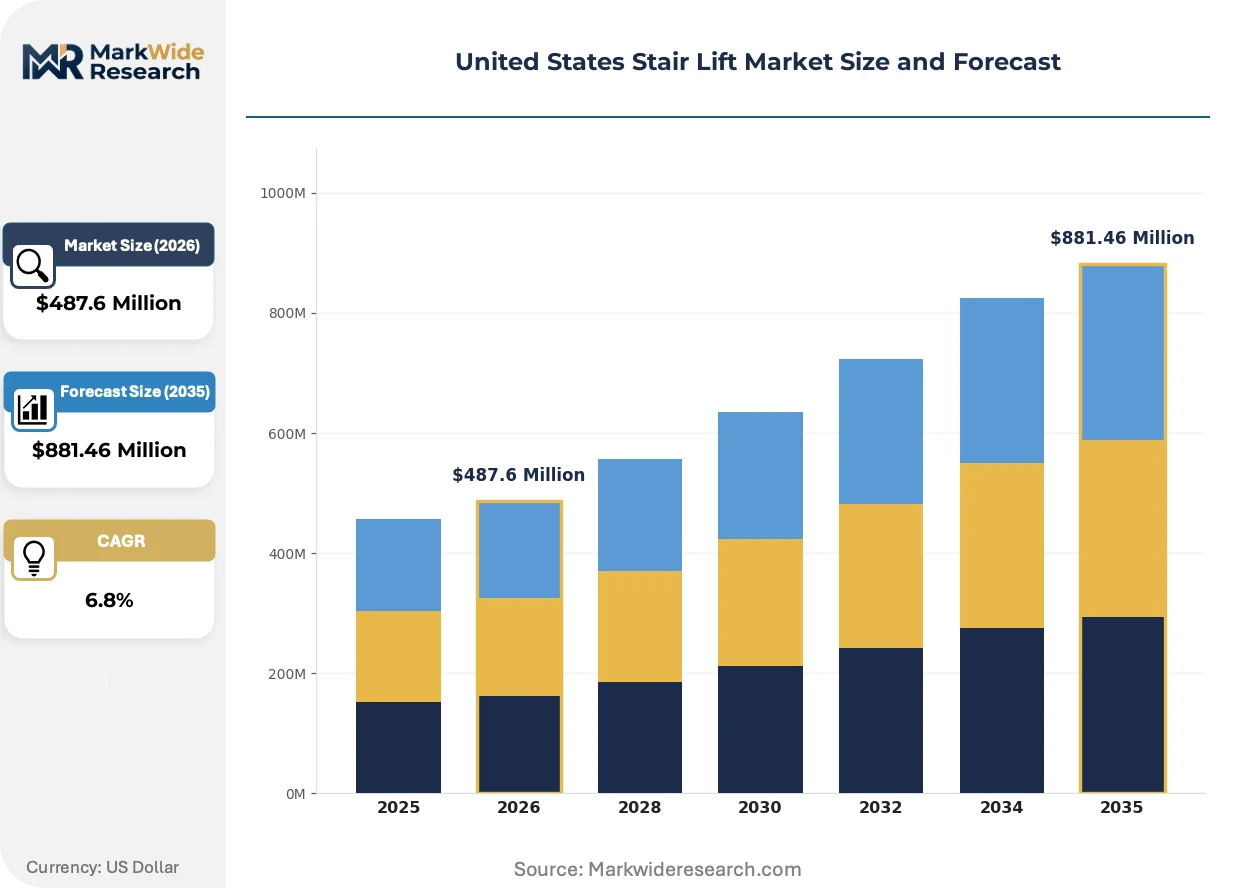
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Curved Stair Lifts, Straight Stair Lifts, Outdoor Stair Lifts, Portable Stair Lifts End User: Residential Users, Commercial Properties, Healthcare Facilities, Aging Population Weight Capacity: 250 lbs, 350 lbs, 400 lbs, 500 lbs Power Source: Electric, Battery-operated, Hydraulic, Manual |
| Companies Covered | Handicare Group, Stannah Lifts Holdings, Bruno Independent Living Aids, Lifeway Mobility, AmeriGlide Distributing, Savaria Corporation, Acorn Stairlifts, MobilityWorks, TK Elevator, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Stair Lift Market Evolving Landscape
Rack-and-pinion drive mechanisms are losing ground to alternative propulsion architectures as manufacturers pursue quieter operation and reduced maintenance intervals. Three convergent developments are redefining product roadmaps and competitive differentiation.
Modular rail extrusion systems are decomposing the traditional single-piece rail manufacturing model. These aluminum components with snap-fit joint technology allow same-day installation for straight stair configurations. Regional home medical equipment dealers in Florida and Arizona are adopting these systems aggressively. The technology is compressing installation labor costs and enabling inventory-light distribution models that challenge established dealer networks.
OSHA workplace safety standards for powered platform lifts are tightening technician certification requirements and documentation protocols. Commercial installation contracts now mandate proof of continuing education credits and liability insurance riders specific to stairway chairlift work. Hospital and skilled nursing facility procurement departments are screening vendor compliance more rigorously, disqualifying smaller independent installers from large-scale retrofit projects.
Adult children are displacing end-users as primary purchase decision-makers, shifting marketing emphasis from clinical functionality to remote monitoring capabilities and aesthetic customization. Manufacturers now offer rail color matching, upholstery upgrades, and fold-away seat designs that prioritize household visual integration over pure utility. This behavioral pivot is most pronounced in California and Pacific Northwest markets where home resale value considerations dominate renovation spending.
United States Stair Lift Market Segmentation
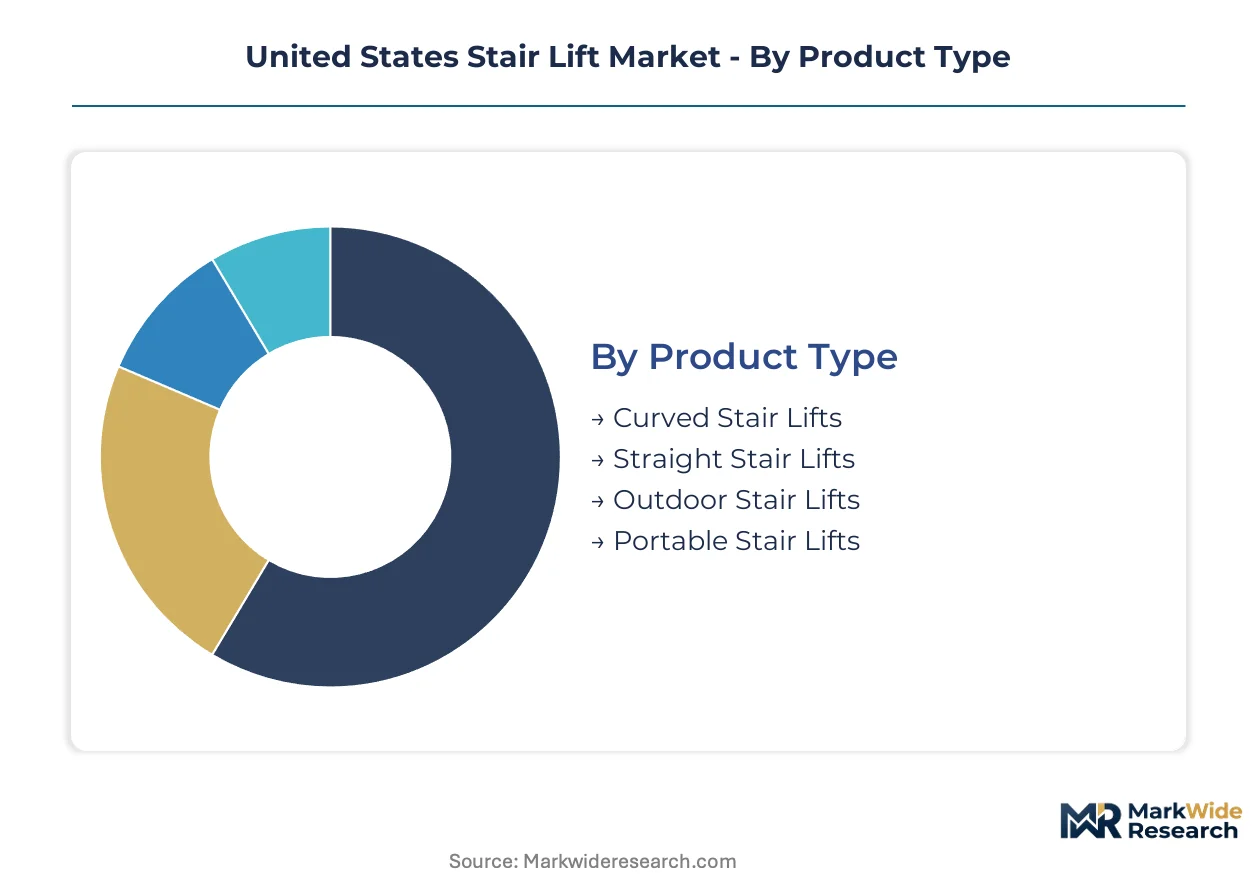
Stair lift manufacturers configure product portfolios around installation complexity, reimbursement pathways, and structural constraints of American housing stock. Segment-specific margin profiles diverge sharply between standardized straight rail systems and engineered curved configurations.
Product Type:
Margins concentrate in custom-engineered solutions where CNC fabrication and site-specific rail bending create pricing power unavailable in commoditized straight rail segments.
- Straight Stair Lifts:Aluminum rail extrusions with rack-and-pinion drive mechanisms mount directly to stair treads without bending or custom fabrication. Demand clusters in Florida and Arizona retirement communities where ranch-style homes with single straight staircases dominate, driven by Medicaid HCBS waiver coverage expansion.
- Curved Stair Lifts:Site-measured rails undergo CNC bending to match spiral, L-shaped, or fanned staircase geometries. Premium positioning reflects 6-10 week engineering lead times and concentrated fabrication capacity in Great Lakes metalworking shops, with strongest uptake in Northeast urban markets with older multi-story housing.
- Outdoor Stair Lifts:Weather-sealed DC battery systems with marine-grade coatings withstand temperature cycling and precipitation exposure.
- Portable Stair Lifts:Temporary rental configurations deploy for post-surgical recovery periods without permanent structural modification.
The dominant share belongs to Straight Stair Lifts, while Curved Stair Lifts is closing the gap fastest.
End User:
Procurement authority is shifting from individual consumers to institutional buyers with bundled equipment mandates and volume contracting leverage.
- Residential Users:Individual homeowners or family members purchase through out-of-pocket expenditure or supplemental insurance benefits. California and Pacific Northwest markets show adult children driving selection toward IoT-enabled units with remote monitoring capabilities.
- Healthcare Facilities:Hospitals and skilled nursing facilities specify stair lifts for ADA-compliant patient transfer routes and early discharge protocols. ASME A18.1 compliance mandates are accelerating retrofit timelines in multi-story clinics.
- Commercial Properties:Office buildings and retail locations install platform lifts to satisfy OSHA workplace accessibility requirements.
- Aging Population:Direct beneficiary segment encompasses individuals aged 65+ with mobility limitations qualifying for Medicare Advantage supplemental home modification benefits.
Residential Users retain the largest volume position, though Healthcare Facilities is expanding most quickly.
Weight Capacity:
Product line differentiation tracks bariatric care requirements and liability exposure thresholds in institutional settings.
- 350 lbs:Reinforced drive mechanisms and wider seat platforms address the bariatric patient population. Healthcare facilities in Texas and Ohio specify this tier for hospital-at-home discharge programs managing higher-acuity patients.
- 250 lbs:Standard-duty configurations serve typical adult mobility needs with compact rail footprints suited to narrow residential staircases.
- 400 lbs:Heavy-duty structural reinforcement with dual-motor drive systems for commercial installation codes.
- 500 lbs:Maximum-capacity platforms with reinforced wall anchoring for specialized bariatric care environments.
The 350 lbs specification commands premium positioning in institutional procurement, while 250 lbs maintains broadest residential penetration.
Power Source:
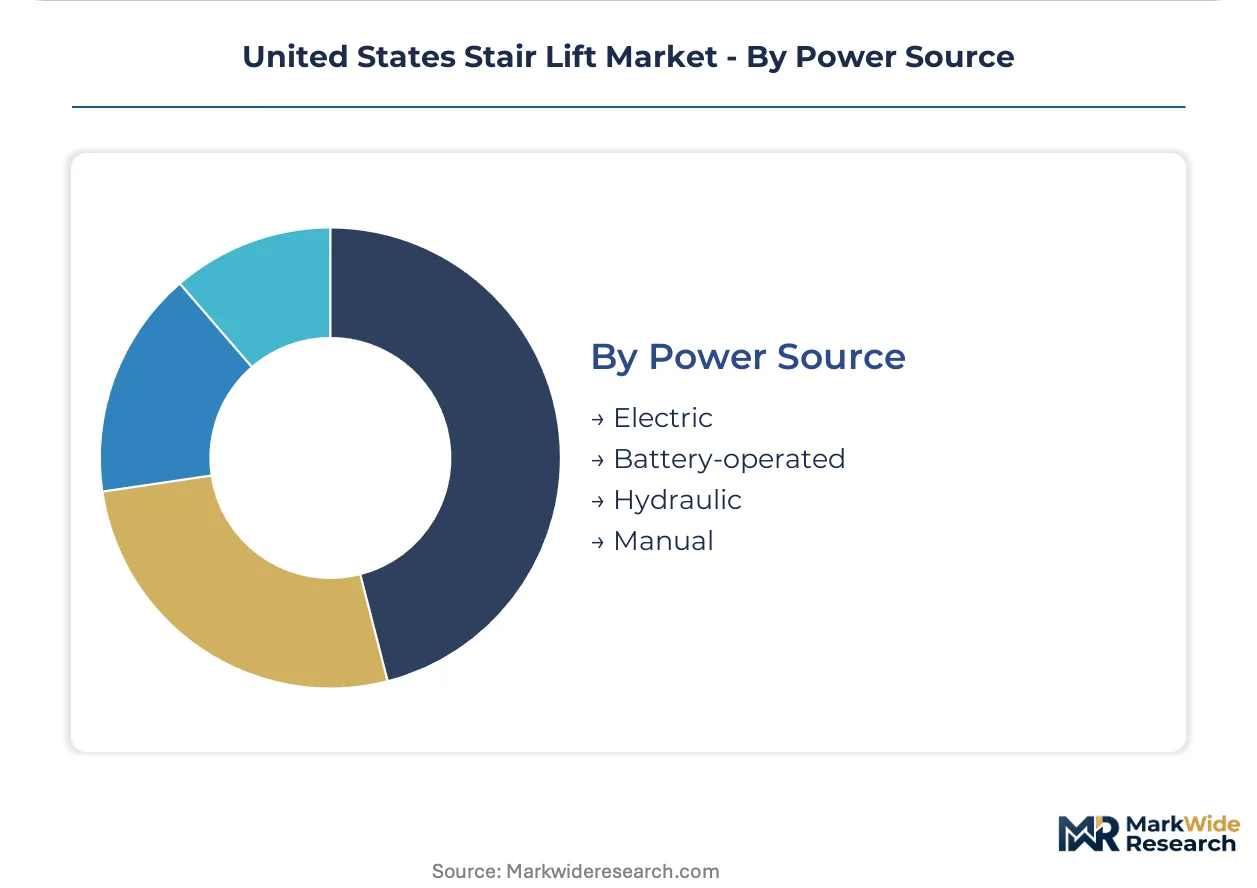
Electrical infrastructure compatibility and outage resilience shape technology selection across hurricane-exposed coastal markets versus stable-grid inland regions.
- Battery-operated:Lithium-ion packs with smart charge management eliminate power-outage vulnerability and simplify installation in pre-1980s residences with legacy electrical panels. Florida dealers report this configuration as default specification for coastal counties.
- Electric:Hardwired AC systems with continuous charging docks offer lowest operating cost where electrical service is modern and reliable.
- Hydraulic:Fluid-pressure drive systems for vertical platform lifts in commercial accessibility applications.
- Manual:Human-powered emergency evacuation chairs for backup use during system maintenance or power failure.
Battery-operated systems are displacing hardwired alternatives fastest in residential channels, while Electric retains cost advantage in new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicaid HCBS waiver expansion and Medicare Advantage supplemental benefit growth are redistributing stair lift demand across state-level markets, with reimbursement policy variations creating distinct regional adoption corridors.
Florida
Retiree population concentration in Tampa Bay and Southwest Florida corridors sustains the nation's highest per-capita stair lift installation rate. State Medicaid HCBS waivers explicitly cover home modifications for aging-in-place beneficiaries, expanding addressable demand beyond traditional out-of-pocket purchasers. Miami-Dade and Palm Beach counties host dense networks of home medical equipment dealers leveraging modular rail systems for same-day installation capacity.
California
Tech-forward adult children in Silicon Valley and Los Angeles Basin markets prioritize IoT-enabled units with remote monitoring capabilities over basic functionality. Local building code enforcement of ADA accessibility standards accelerates retrofit timelines in multi-story assisted living properties. San Diego and Orange County clusters concentrate curved rail engineering demand for custom staircase configurations in older coastal housing stock.
Arizona
Sun Belt retirement migration into Phoenix-Mesa-Scottsdale and Tucson metro areas generates straight stair lift volume for ranch-style homes with single staircases. Lithium-ion battery configurations dominate specifications due to power-outage resilience requirements in monsoon-exposed desert regions. Medicaid waiver coverage expansion in Maricopa and Pima counties shifts procurement toward institutional reimbursement channels.
Texas
Medicare Advantage penetration exceeding fifty percent of eligible beneficiaries in Houston and Dallas-Fort Worth metros opens reimbursement channels for home modification equipment that traditional fee-for-service Medicare excludes. Hospital-at-home discharge programs in Texas Medical Center cluster create bundled equipment procurement relationships specifying stair lifts for fall-risk reduction. San Antonio and Austin markets show adult children driving aesthetic customization preferences.
Ohio
Legacy manufacturing infrastructure in Cleveland-Akron and Cincinnati-Dayton corridors supports concentrated CNC bending capacity for custom curved rail fabrication. Medicare Advantage supplemental benefit structures in these markets increasingly cover stair lift installations for aging-in-place protocols. Cold-climate battery performance requirements differentiate product specifications from Sun Belt markets.
United States Stair Lift Market Competitive Landscape
Player mix skews toward vertically integrated service providers with captive installation networks rather than pure equipment vendors. The competitive structure concentrates around three strategic archetypes: manufacturers with dealer network control, direct-to-consumer specialists with in-house service operations, and diversified accessibility equipment conglomerates with portfolio breadth. Consolidation pressure intensifies as reimbursement complexity favors integrated service capabilities over standalone product distribution. Capacity expansion in certified technician training programs and strategic partnerships with home healthcare agencies represent the dominant competitive moves reshaping market position.
Among the established manufacturer-service integrators, Handicare Group, Stannah Lifts Holdings, and Bruno Independent Living Aids exemplify distinct strategic positioning within the competitive spectrum. Handicare Group represents the vertically integrated archetype with direct service operations spanning manufacturing through installation. Stannah Lifts Holdings occupies a position emphasizing custom engineering capabilities for non-standard staircase configurations. Bruno Independent Living Aids anchors the dealer-network model with extensive geographic coverage across the Southeast and Midwest. These three entities collectively illustrate the strategic divergence between captive service control and distributed installation partnerships that defines competitive dynamics in this market.
| Leading Market Players |
|---|
| Handicare Group |
| Stannah Lifts Holdings |
| Bruno Independent Living Aids |
| Lifeway Mobility |
| AmeriGlide Distributing |
| Savaria Corporation |
| Acorn Stairlifts |
| MobilityWorks |
| TK Elevator |
| Others |
Value Network & Pricing Analysis
Aluminum extrusion scale economies at Midwest fabricators establish price floors for straight rail systems while concentrating bargaining power among a handful of primary smelter relationships. This concentration amplifies margin volatility when power grid pricing spikes hit Ohio and Michigan production clusters, forcing stair lift manufacturers to absorb cost swings or pass through to Medicaid-constrained end users.
Pricing Analysis
Certification level creates the primary spread between market tiers, with ASME A18.1-compliant units commanding substantial premiums over uncertified imports. Three-tier pricing structure separates FDA-registered medical devices from state-level waiver-eligible equipment and cash-pay economy configurations. Pricing pressure stems from aluminum cost volatility and certified technician scarcity extending installation timelines. Healthcare facilities show lowest price sensitivity due to bundled procurement mandates, while individual residential buyers in Florida and Arizona remain most cost-conscious.
Supply Chain Analysis
Inbound logistics costs from Great Lakes ports through Chicago rail hubs concentrate CNC bending capacity within a 300-mile radius of Cleveland. Primary aluminum draws from domestic smelters in Kentucky and Missouri, with secondary sourcing from Canadian producers subject to tariff exposure. Lithium-ion battery packs hinge on South Korean cell manufacturers and Chinese BMS suppliers, creating single-source vulnerability for DC system configurations. Distribution runs through regional home medical equipment dealers with ASME-certified installation crews, though modular rail systems are compressing traditional dealer margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The certified technician gap constrains revenue conversion across Sun Belt retirement corridors, with fewer than two thousand ASME A17.1/A18.1 holders available for peak-season deployment. This scarcity elevates installation capacity as the decisive competitive moat.
For Market Incumbents: Shield dealer network relationships by embedding proprietary technician training academies in Florida and Arizona markets. Acquire CNC bending capacity in Ohio to reduce rail fabrication lead times below six weeks. Consolidate position against modular rail entrants by bundling IoT-enabled remote monitoring with installation contracts.
For New Entrants and Emerging Players: Lead with Medicare Advantage supplemental benefit navigation as a differentiated service layer in Texas and Pennsylvania markets where MA penetration exceeds half of eligible beneficiaries. Target hospital-at-home discharge programs with bundled fall-risk reduction protocols. White-space exists in curved rail rental models for post-surgical recovery periods.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated service providers with captive installation networks over pure equipment vendors. Long-term viability rests on reimbursement complexity favoring integrated capabilities. Acquisition targets should demonstrate ASME-certified technician density and Medicaid waiver program relationships. Watch Medicare Advantage supplemental benefit expansion rates as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Academy Expansion | ASME A17.1/A18.1 training capacity alleviates peak-season installation bottlenecks in Sun Belt corridors. |
| CNC Bending Capacity Acquisition | Captive rail fabrication compresses curved stair lift lead times below competitor benchmarks. |
| Medicare Advantage Navigation Platform | Supplemental benefit expertise unlocks reimbursement channels in Texas and Ohio markets. |
| IoT Remote Monitoring Integration | Predictive maintenance algorithms appeal to adult children purchasing for aging parents. |
| Hospital-at-Home Partnership Program | Bundled procurement relationships with discharge programs secure institutional volume. |
Research Methodology
A standing panel of home medical equipment dealers, ASME-certified installation technicians, Medicaid waiver program administrators, and hospital discharge planners provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, state HCBS waiver coverage documents, and CMS Medicare Advantage plan benefit filings. Bottom-up demand modeling triangulated against top-down aluminum consumption data and regional building permit flows.
Consistency checks validated volume and value outputs against external benchmarks including hospital procurement database trends and GPO contract award patterns. The analytical framework segmented across product type, end user, weight capacity, and power source dimensions throughout the projection horizon. CAGRs derived from installed base growth rates and replacement cycle assumptions, with Medicare Advantage penetration curves and Medicaid waiver expansion timelines as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement policy support or aluminum price stability would require recalibration. Forecasts reflect documented assumptions regarding technician training pipeline expansion and modular rail adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Global Advanced Bipolar Direct Energy Device Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
China Electrocardiograph (ECG) Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
Global Lenses for Myopia Control Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Cyberknife Technology Market
Medical Devices
North America Medical Devices Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Struts Implants Market
Medical Devices
Ultrasound Biometry Devices Market
Medical Devices
Global Implantable Drug Delivery Market