
 Eastern Europe Online Pharmacy Market | 2026-2036
Eastern Europe Online Pharmacy Market Size, Share, and Industry Trends Forecast 2026-2036
Eastern Europe Online Pharmacy Market Intelligence
Multi-sourced platform procurement is expanding across the Eastern Europe online pharmacy sector as regional operators diversify beyond single-country supply bases. Dr.Max Group leverages its Czech and Slovak brick-and-mortar network to anchor last-mile fulfillment density. Zur Rose Group AG competes through Swiss-backed technology infrastructure that sustains cross-border prescription routing. Pelion SA dominates Polish wholesale-to-digital channels, while Apotheka SIA operates Baltic-centric logistics that control inventory freshness for temperature-sensitive shipments.
An online pharmacy constitutes a digitally intermediated pharmaceutical retail channel where licensed dispensaries process orders through encrypted web or mobile interfaces, verify prescriptions via national e-health databases, and distribute medicines through cold-chain or ambient logistics networks. Its primary commercial purpose is to extend pharmacy access beyond physical catchment areas while maintaining regulatory compliance with prescription validity, patient data protection, and medicine traceability standards. Prescription drugs command the deepest margin pools due to reimbursement complexity and recurring refill patterns, whereas OTC medications attract price-sensitive traffic that feeds subscription services and loyalty programs. Home delivery remains the default fulfillment mode, though same-day delivery in Warsaw and Prague is gaining traction among urban healthcare providers seeking immediate patient supply.
Poland's Pharmaceutical Inspectorate, the Czech State Institute for Drug Control, and the EU's EMA framework collectively enforce serialization, data localization, and cross-border dispensing rules that shape market access conditions. REACH-aligned packaging standards and national e-prescription systems determine which platforms qualify for reimbursement partnerships and insurance integration. Stakeholders must monitor how emerging EU AI Act provisions classify automated prescription-checking algorithms and whether Baltic regulators harmonize their digital pharmacy licensing with broader EU mutual recognition principles.
Market Dynamics
The EU's Falsified Medicines Directive and national e-prescription mandates are compressing compliance timelines while concentrating procurement authority within pharmacy chains that can absorb serialization infrastructure costs.
Growth Catalysts
- E-prescription integration:Poland's national e-recepta system and Czech ePrescription platforms are eliminating paper-based verification delays, accelerating refill velocity for chronic disease patients.
- Cold-chain logistics maturation:Temperature-controlled last-mile networks now cover Warsaw, Prague, and Bratislava with same-day biologics delivery, expanding the addressable patient base for insulin and vaccine categories.
- REACH-aligned packaging standards:Harmonized serialization requirements across EU member states are reducing cross-border fulfillment friction for multi-country pharmacy operators.
Market Restraints
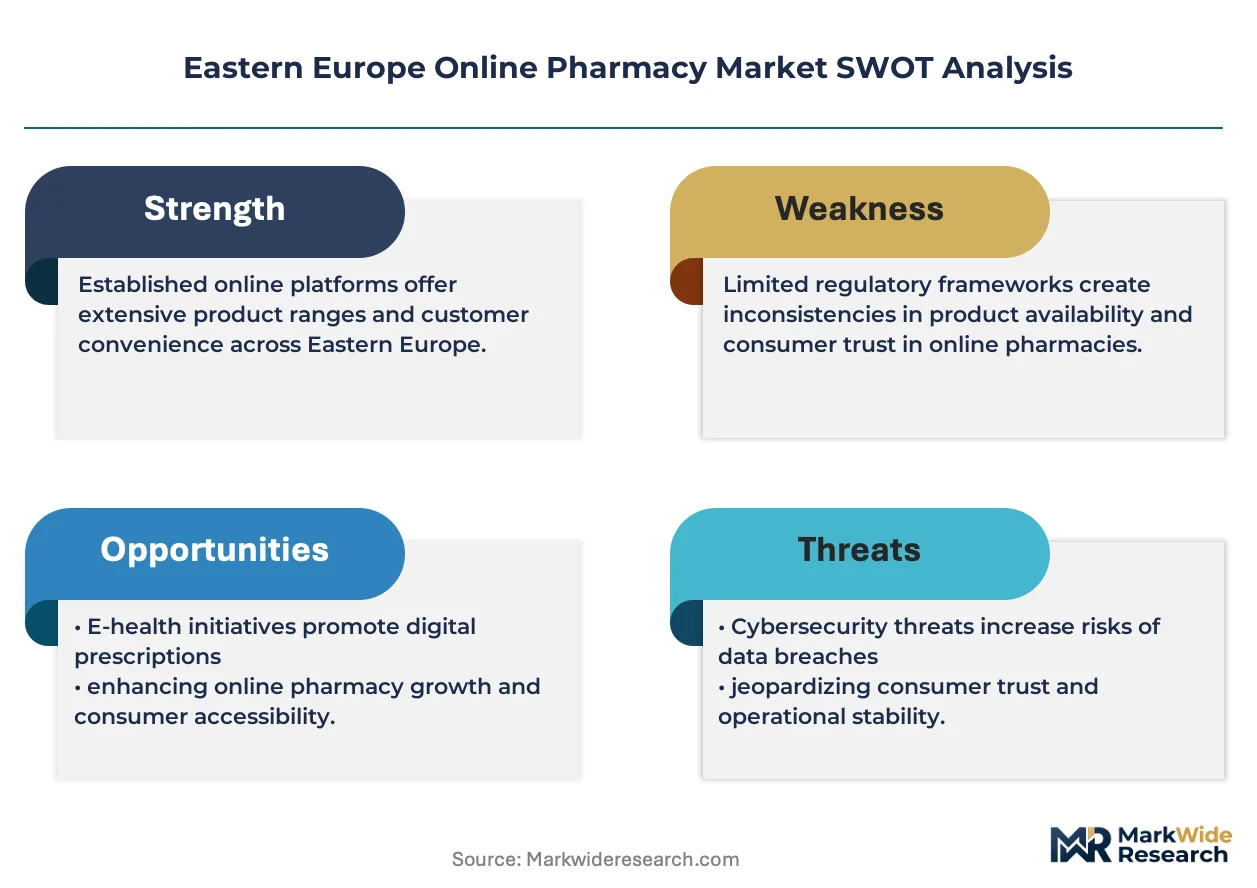
- Data localization mandates:Poland's Pharmaceutical Inspectorate and Czech State Institute for Drug Control require patient records and transaction data to reside on domestic servers, fragmenting cloud infrastructure economies.
- Reimbursement complexity:National health funds in Hungary and Romania maintain divergent formularies and copay structures, forcing platforms to maintain parallel pricing engines.
- Brick-and-mortar pharmacy lobbies:Physical dispensary associations in Slovakia and Bulgaria have secured regulatory caps on online prescription volumes, constraining digital channel expansion.
Strategic Opportunities
- Rural underpenetration:Eastern Poland and northern Romania contain pharmacy deserts where telehealth-integrated delivery platforms can capture chronic disease patients currently traveling 50+ kilometers for refills.
- Subscription model expansion:Auto-refill programs for hypertension and diabetes medications are penetrating urban markets, with loyalty mechanics reducing patient switching.
- EU AI Act alignment:Automated prescription-checking algorithms that achieve regulatory certification under emerging AI governance frameworks will secure preferential reimbursement partnerships with national insurers.
Industry Challenges
- Qualified pharmacist scarcity:Remote verification roles require licensed professionals fluent in national drug interaction databases, creating recruitment bottlenecks in Baltic markets.
- Legacy system integration:Wholesale distributors operating on 1990s-era ERP platforms face API compatibility gaps when connecting to modern patient-facing mobile applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eastern Europe Online Pharmacy Market |
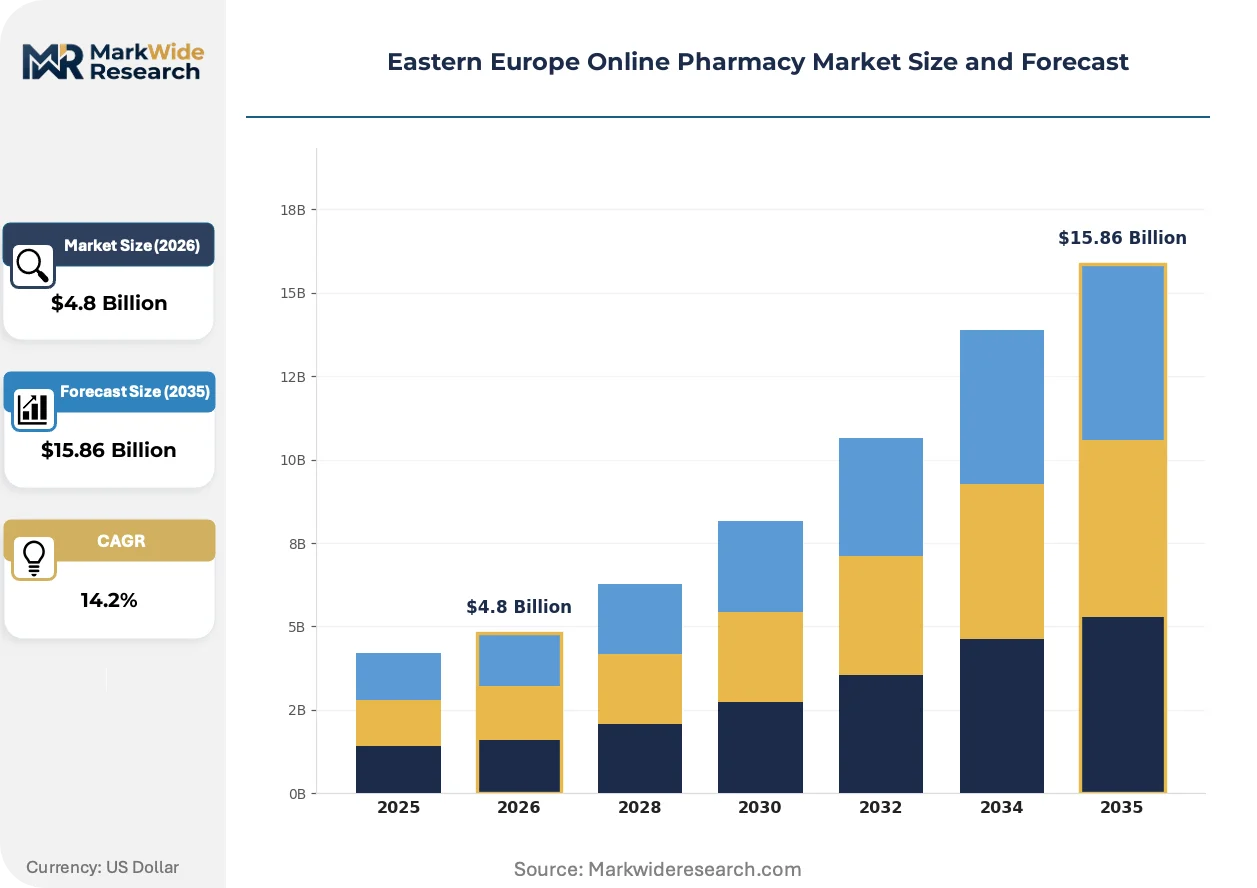
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, OTC Medications, Personal Care Products, Health Supplements Customer Type: Individuals, Healthcare Providers, Pharmacies, Insurance Companies Delivery Mode: Home Delivery, In-Store Pickup, Same-Day Delivery, Scheduled Delivery Service Type: Online Consultations, Subscription Services, Price Comparison, Loyalty Programs |
| Companies Covered | AZETA Sia, Webaptieka, Dr.Max Group, Lékárna WPK sro, EXTRAPHARMA online pharmacy, Apotheka SIA, Medikaments.lv, Zur Rose Group AG, Pelion SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eastern Europe Online Pharmacy Market Strategic Shifts & Innovations
Telehealth-pharmacy convergence is dissolving the traditional separation between diagnosis and fulfillment, with prescription routing now occurring within single-session digital encounters.
Blockchain-based medicine traceability is unifying serialization data across Czech, Polish, and Slovak supply chains. Dr.Max Group and Pelion SA are piloting shared ledger infrastructure that compresses verification time from hours to minutes. This unifying architecture is enabling real-time counterfeit detection while reducing insurance fraud exposure for reimbursement partners.
EMA's evolving guidance on algorithmic clinical decision support is tightening validation requirements for automated drug interaction screening. Platforms must now document training data provenance and bias auditing before national regulators approve reimbursement eligibility. Polish and Czech operators with existing AI governance frameworks are adapting verification workflows ahead of formal enforcement.
Chronic disease patients are consolidating refill activity onto platforms offering integrated teleconsultation and medication management. Urban healthcare providers in Warsaw and Prague are steering patients toward affiliated digital pharmacies, displacing standalone dispensary relationships. This behavioral shift concentrates prescription volume within vertically integrated health systems.
Eastern Europe Online Pharmacy Market Segmentation
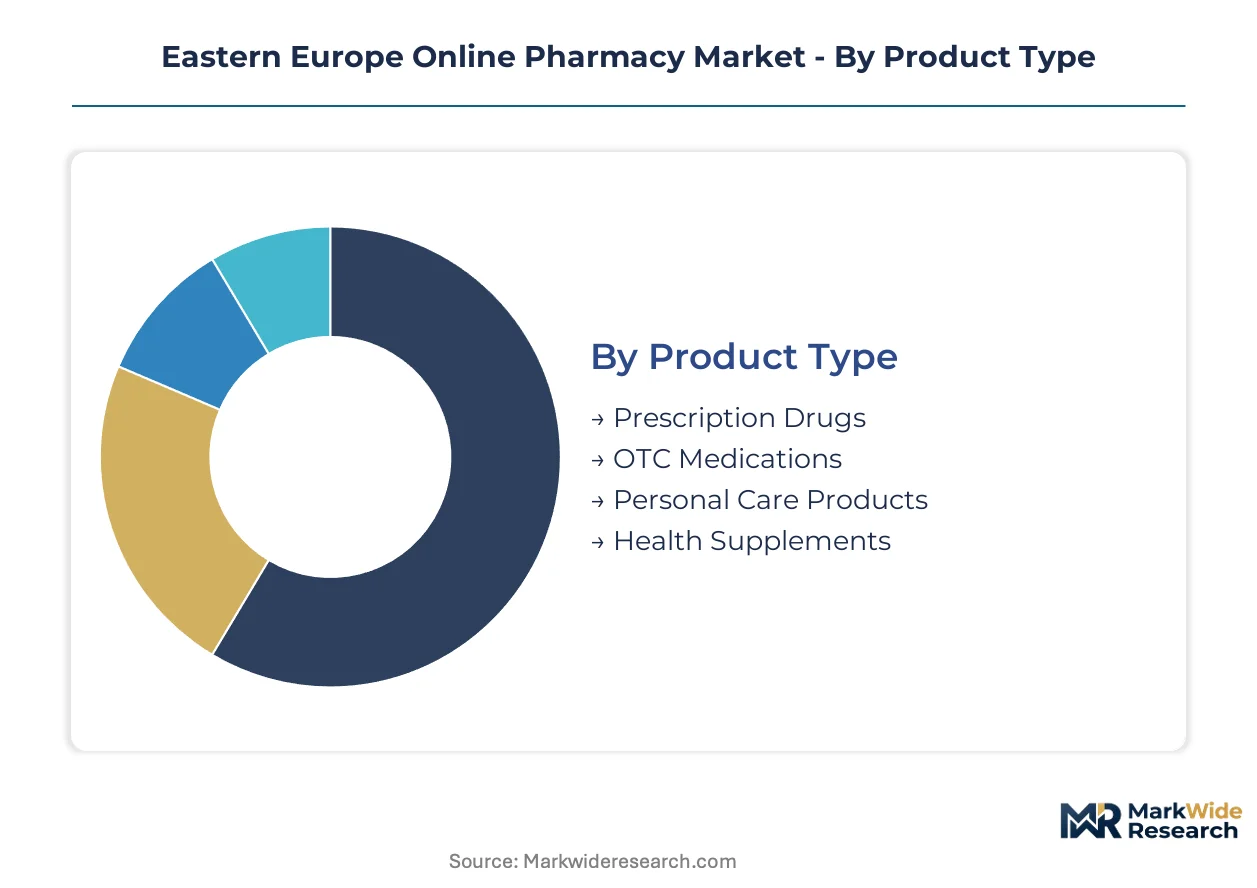
Eastern Europe's online pharmacy market segments along four operational dimensions that determine platform architecture and margin capture. Product type dictates cold-chain investment intensity, while customer type shapes prescription verification workflows and reimbursement integration depth.
Product Type:
Replacement cycles for chronic disease medications drive recurring revenue predictability, whereas acute-condition prescriptions exhibit sporadic demand patterns with lower lifetime value per patient.
- Prescription Drugs:Temperature-sensitive biologics and controlled substances requiring pharmacist verification against national e-health databases. Demand concentrates in Warsaw and Prague corridors where telehealth-integrated platforms secure insurance reimbursement partnerships for diabetes and cardiovascular therapies.
- OTC Medications:Self-care products spanning analgesics, antihistamines, and digestive remedies with minimal regulatory friction. Price-sensitive traffic in Polish urban markets feeds subscription bundling and cross-selling into higher-margin categories.
- Personal Care Products:Dermatological and hygiene SKUs with ambient storage requirements. Baltic operators leverage these for basket-building alongside pharmaceutical purchases.
- Health Supplements:Vitamins and nutraceuticals facing lighter serialization mandates under REACH-aligned standards. Romanian pharmacy deserts show rising penetration as rural patients consolidate wellness spending onto single platforms.
Volume placements concentrate in Prescription Drugs; the faster expansion belongs to Health Supplements.
Customer Type:
Cost tier differentiation separates high-touch institutional relationships from automated individual transactions, with reimbursement complexity escalating across the spectrum.
- Individuals:Chronic disease patients managing hypertension, diabetes, and respiratory conditions through recurring refill patterns. Polish e-recepta integration enables seamless prescription routing without physical pharmacy visits.
- Healthcare Providers:Clinics and hospitals sourcing acute-care supplies through contracted procurement portals. Czech hospital networks are consolidating purchasing onto platforms with EMA-compliant traceability.
- Pharmacies:Independent dispensaries accessing wholesale-to-digital channels for inventory replenishment. Pelion SA's B2B infrastructure dominates Polish inter-pharmacy distribution.
- Insurance Companies:Payers integrating pharmacy benefits management with utilization review algorithms. Hungarian national health funds maintain divergent formularies that fragment platform pricing engines.
Margin capture peaks with Insurance Companies; patient volume dominance rests with Individuals.
Delivery Mode:
Application urgency determines logistics infrastructure investment, with temperature-controlled networks commanding premium positioning in urban corridors.
- Home Delivery:Standard fulfillment mode covering ambient and cold-chain requirements across Eastern Poland and northern Romania pharmacy deserts. Last-mile density in Warsaw and Prague compresses delivery windows for chronic disease patients.
- Same-Day Delivery:Biologics and acute-condition medications requiring refrigerated vehicle fleets. Bratislava corridors are piloting this capability for insulin and vaccine categories.
- In-Store Pickup:Click-and-collect integration with Dr.Max Group's Czech and Slovak brick-and-mortar network. This hybrid model reduces last-mile costs while preserving patient-pharmacist interaction.
- Scheduled Delivery:Auto-refill synchronization with prescription renewal cycles for hypertension and diabetes therapies. Subscription mechanics reduce switching behavior among chronic disease cohorts.
Addressable reach is widest through Home Delivery; infrastructure investment is concentrating on Same-Day Delivery.
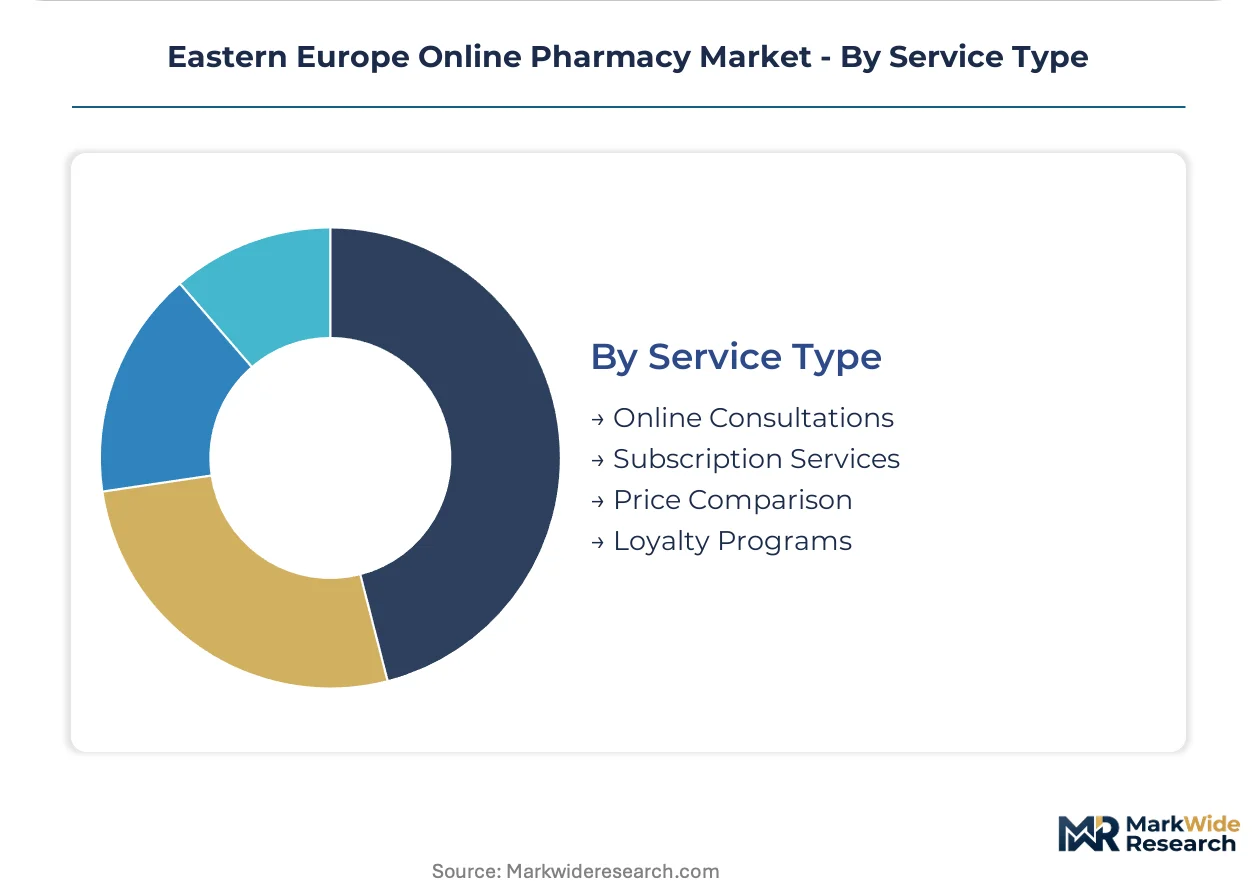
Service Type:
Customer maturity and digital literacy shape adoption curves, with integrated health services capturing stickiest patient relationships.
- Online Consultations:Telehealth-pharmacy convergence enabling single-session diagnosis-to-fulfillment workflows. Polish platforms with existing AI governance frameworks are adapting verification ahead of EU AI Act enforcement.
- Subscription Services:Auto-refill programs with loyalty mechanics reducing patient churn. Urban healthcare providers in Warsaw steer chronic disease patients toward affiliated digital pharmacies.
- Price Comparison:Transparent OTC pricing engines attracting cost-sensitive traffic. Romanian markets show highest engagement as patients navigate fragmented reimbursement structures.
- Loyalty Programs:Points-based retention systems bundling pharmaceutical and wellness purchases. Baltic operators use these to offset higher customer acquisition costs in smaller markets.
Patient retention depends most on Subscription Services; acquisition efficiency is climbing fastest through Online Consultations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical wholesale infrastructure anchored in Warsaw and Prague shapes procurement density across the region. Cold-chain logistics networks radiating from these hubs determine last-mile reach for temperature-sensitive medicines.
Poland
Chronic disease patients in pharmacy deserts drive demand for telehealth-integrated delivery platforms. The Pharmaceutical Inspectorate enforces data localization mandates requiring domestic server hosting for patient records. Warsaw anchors same-day biologics delivery networks that now extend into eastern regions previously underserved by physical dispensaries.
Czech Republic
Hospital networks are consolidating acute-care procurement onto platforms with EMA-compliant traceability systems. The State Institute for Drug Control mandates serialization verification against national e-prescription databases. Prague's logistics corridors enable cold-chain coverage that supports insulin and vaccine distribution to Bratislava-adjacent markets.
Slovakia
Brick-and-mortar pharmacy lobbies have secured regulatory caps on online prescription volumes, constraining digital channel expansion. Physical dispensary associations influence reimbursement negotiations with national health funds. Bratislava corridors pilot same-day delivery capabilities for temperature-sensitive categories, leveraging proximity to Czech distribution infrastructure.
Hungary
Divergent formularies and copay structures force platforms to maintain parallel pricing engines for reimbursement complexity. The national health fund maintains distinct procurement protocols that fragment cross-border fulfillment standardization. Budapest's healthcare provider networks are consolidating purchasing authority onto contracted platforms with utilization review algorithms.
Romania
Pharmacy deserts in northern regions contain chronic disease patients traveling 50+ kilometers for medication refills. Rural underpenetration creates addressable markets for subscription-based auto-refill programs. Cluj-Napoca and Bucharest clusters concentrate digital pharmacy infrastructure while outlying areas remain dependent on intermittent physical dispensary access.
Eastern Europe Online Pharmacy Market Key Industry Players
Consolidation through pharmacy chain acquisition dominates the current landscape, compressing vendor diversity into vertically integrated health systems. The market structure concentrates procurement authority within entities that can absorb serialization infrastructure costs and maintain reimbursement partnerships with national insurers. Two strategic archetypes predominate: wholesale-backed platforms leveraging existing distribution networks, and telehealth-integrated operators capturing patient relationships through diagnosis-to-fulfillment workflows. M&A activity and cold-chain capacity expansion constitute the primary competitive moves, with operators acquiring brick-and-mortar density to anchor last-mile economics.
Among Swiss-backed technology operators, Zur Rose Group AG occupies a position exemplifying cross-border prescription routing infrastructure. Dr.Max Group and Pelion SA represent contrasting archetypes within the regional tier—Czech-Slovak brick-and-mortar network density versus Polish wholesale-to-digital channel dominance. These three entities collectively illustrate how geographic origin and underlying corporate structure shape competitive positioning without requiring specific product or technology claims.
| Leading Market Players |
|---|
| AZETA Sia |
| Webaptieka |
| Dr.Max Group |
| Lékárna WPK sro |
| EXTRAPHARMA online pharmacy |
| Apotheka SIA |
| Medikaments.lv |
| Zur Rose Group AG |
| Pelion SA |
| Others |
Cost & Logistics Intelligence
REACH-aligned packaging standards gate qualified supply access and premium-tier pricing power for Eastern European online pharmacy operators, with serialization-compliant cold-chain infrastructure separating reimbursable prescription platforms from OTC-only competitors. National health funds direct procurement volume toward platforms bearing EMA-compliant traceability certifications, compressing margins for uncertified entrants while rewarding verified operators with preferred formulary status.
Pricing Analysis
Cold-chain warranty bundling distinguishes premium-tier pharmacy platforms from economy competitors, with temperature-controlled delivery guarantees and pharmacist consultation access included in subscription pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and geographic delivery density, with Warsaw and Prague corridors commanding premium positioning. Cost compression in standard tiers is intensifying because brick-and-mortar pharmacy lobbies have secured volume caps that fragment digital scale economies. Individual chronic disease patients exhibit highest price sensitivity, whereas insurance company procurement contracts demonstrate lowest elasticity due to utilization review integration.
Supply Chain Analysis
Qualified pharmacist workforce scarcity in Baltic manufacturing geographies constrains remote verification capacity expansion, forcing Polish and Czech operators to absorb recruitment premiums. API sourcing draws from India, China, and Switzerland, with biologics cold-chain inputs resting on German and Dutch logistics infrastructure. Single-source vulnerability concentrates in temperature-controlled vehicle fleets serving insulin and vaccine categories. Distribution runs through wholesale-to-digital channels anchored by Pelion SA's Polish infrastructure and Dr.Max Group's Czech-Slovak network density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where qualified pharmacist scarcity props pricing power for certified platforms. Serialization infrastructure requirements and cold-chain capacity bottlenecks prevent rapid competitive entry, sustaining incumbent margin structures.
For Market Incumbents: Hedge against telehealth-integrated entrants by acquiring brick-and-mortar density in Warsaw and Prague corridors, securing last-mile economics that pure-play digital competitors cannot replicate. Deepen vertical integration into biologics cold-chain fleets before EMA AI Act certification requirements harden compliance timelines. Channel control through Dr.Max Group's Czech-Slovak network exemplifies defensible positioning against wholesale-backed challengers.
For New Entrants and Emerging Players: Telehealth platform partnerships offer the most penetrable entry vector, enabling prescription routing integration without standalone serialization infrastructure investment. Rural pharmacy deserts in eastern Poland and northern Romania present addressable white space where subscription auto-refill models can capture chronic disease patients traveling excessive distances for refills. Go-to-market execution should prioritize reimbursement partnership negotiations with Hungarian national health funds before geographic expansion.
For Investors and Strategic Acquirers: EMA AI Act certification announcements from Polish and Czech regulators are the leading indicator that algorithmic prescription-checking platforms will secure preferential insurance partnerships, shifting competitive dynamics toward technology-enabled operators. Long-term viability across the projection horizon favors wholesale-backed platforms with existing cold-chain infrastructure over pure digital entrants lacking physical anchor points. Acquisition targets should demonstrate EMA-compliant traceability systems and active national e-prescription database integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Capacity Expansion | Same-day biologics delivery in Warsaw and Prague corridors captures insulin-dependent diabetes patient volume from brick-and-mortar competitors. |
| E-Prescription Platform Integration | Polish e-recepta and Czech ePrescription database connectivity secures reimbursement eligibility for chronic disease medication refills. |
| AI Governance Framework Certification | EMA-aligned algorithmic prescription-checking validation positions platforms for preferential national insurer partnerships under emerging EU AI Act provisions. |
| Telehealth-Pharmacy Convergence | Single-session diagnosis-to-fulfillment workflows displace standalone dispensary relationships in urban healthcare provider networks. |
| Subscription Auto-Refill Programs | Loyalty mechanics for hypertension and diabetes therapies reduce patient switching behavior and stabilize recurring revenue predictability. |
Research Approach
Document review covered EMA regulatory filings, national e-prescription system documentation, and pharmaceutical wholesale trade data, complemented by interviews with pharmacy chain procurement directors, telehealth platform executives, cold-chain logistics operators, and national health fund formulary managers. Secondary validation drew from EU Falsified Medicines Directive implementation reports, REACH-aligned packaging standard updates, and serialization infrastructure investment disclosures. Bottom-up patient volume modeling and top-down market sizing triangulation across the analysis window ensured cross-verification of segment-level estimates.
Cross-reference between historical reimbursement pattern analysis and expert panel input shaped the projection framework across product type, customer type, delivery mode, and service type dimensions, with regional regulatory cluster differentiation as an additional modeled variable. CAGRs were derived from patient cohort growth trajectories and telehealth penetration curves rather than simple trend extrapolation. Forecast inputs incorporated e-prescription system adoption rates and cold-chain logistics network expansion timelines specific to Polish and Czech corridor development.
Caveats apply where EMA AI Act enforcement timing or national pharmacy lobby regulatory capture could materially shift the outlook for algorithmic prescription-checking platform reimbursement eligibility. Material deviation in serialization infrastructure cost trajectories or qualified pharmacist workforce availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Transitional Care Management Services Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Canada Senior Living Market
Healthcare Services
Vaccine Logistics Market
Healthcare Services
Patient Transportation Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Medical Social Working Services Market
Healthcare Services
IVD Contract Manufacturing Services Market
Healthcare Services
Acute Care Market
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
Direct-To-Patient Healthcare Logistics Market
Healthcare Services
Tissue Banking Market
Healthcare Services
US Acute Hospital Care Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Healthcare Transportation Services Market