
 Europe Breast Pumps Market | 2026-2036
Europe Breast Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Breast Pumps Market Intelligence
Modular pump kits that separate motor units from collection containers and tubing sets is restructuring how European mothers evaluate total cost of ownership against single-unit alternatives. Medela AG leverages its Swiss manufacturing base to sustain premium positioning across hospital and retail channels. Koninklijke Philips N.V. competes through Avent-branded closed-system designs that dominate pharmacy distribution in the Netherlands and Belgium. Ardo Medical Ltd. specializes in hospital-grade rentals that anchor its presence within German midwife networks and neonatal wards.
A breast pump is a mechanical or electrical suction device designed to extract milk from the lactating human breast, typically operating at cycle frequencies between 30 and 60 expressions per minute and vacuum pressures ranging from 100 to 250 mmHg for safe, effective milk ejection without tissue trauma. Electric pumps with closed-system technology lead European value pools due to backflow prevention requirements under EU MDR biocompatibility standards, while wearable pump configurations represent the fastest-growing segment as Dutch and Swedish direct-to-consumer brands redesign motors for garment integration. Hospital supply channels capture the highest per-unit margins, though online retailers are displacing pharmacy foot traffic for replacement flange and tubing purchases.
EMA oversight through the Medical Device Regulation (EU MDR 2017/745) mandates clinical evidence and post-market surveillance for breast pumps classified as Class I or IIa devices, directly shaping R&D budgets and registration timelines for manufacturers seeking CE marking. REACH compliance on silicone and BPA-free plastics further constrains material sourcing options for pump bodies and tubing assemblies. Stakeholders must monitor how national health technology assessment bodies in France, Germany, and Italy reconcile reimbursement eligibility between rental-grade hospital pumps and direct-purchase consumer units.
Market Dynamics
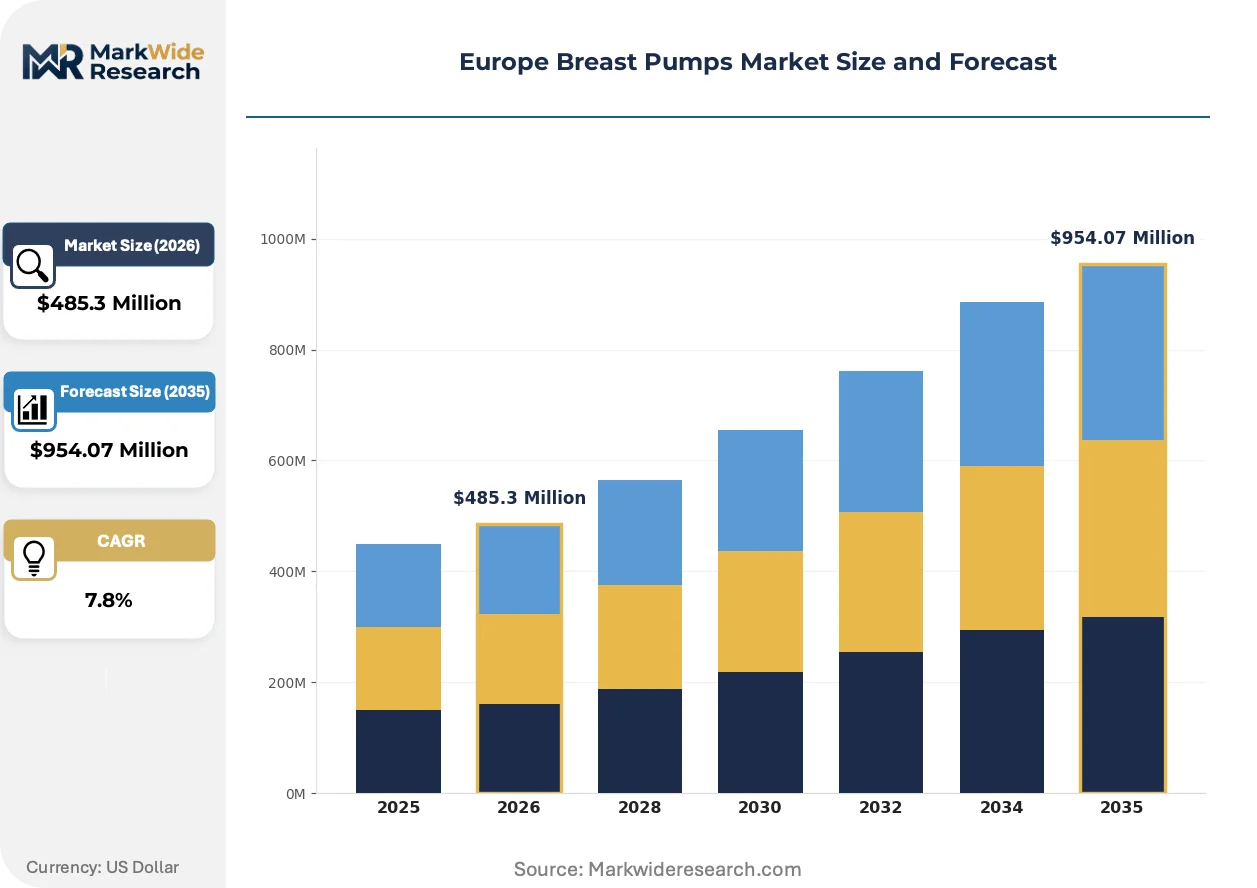
The European breast pumps market is undergoing structural reconfiguration as the EU MDR 2017/745 framework forces manufacturers to redesign closed-system architectures and rebuild clinical evidence portfolios for CE marking renewal.
Growth Catalysts
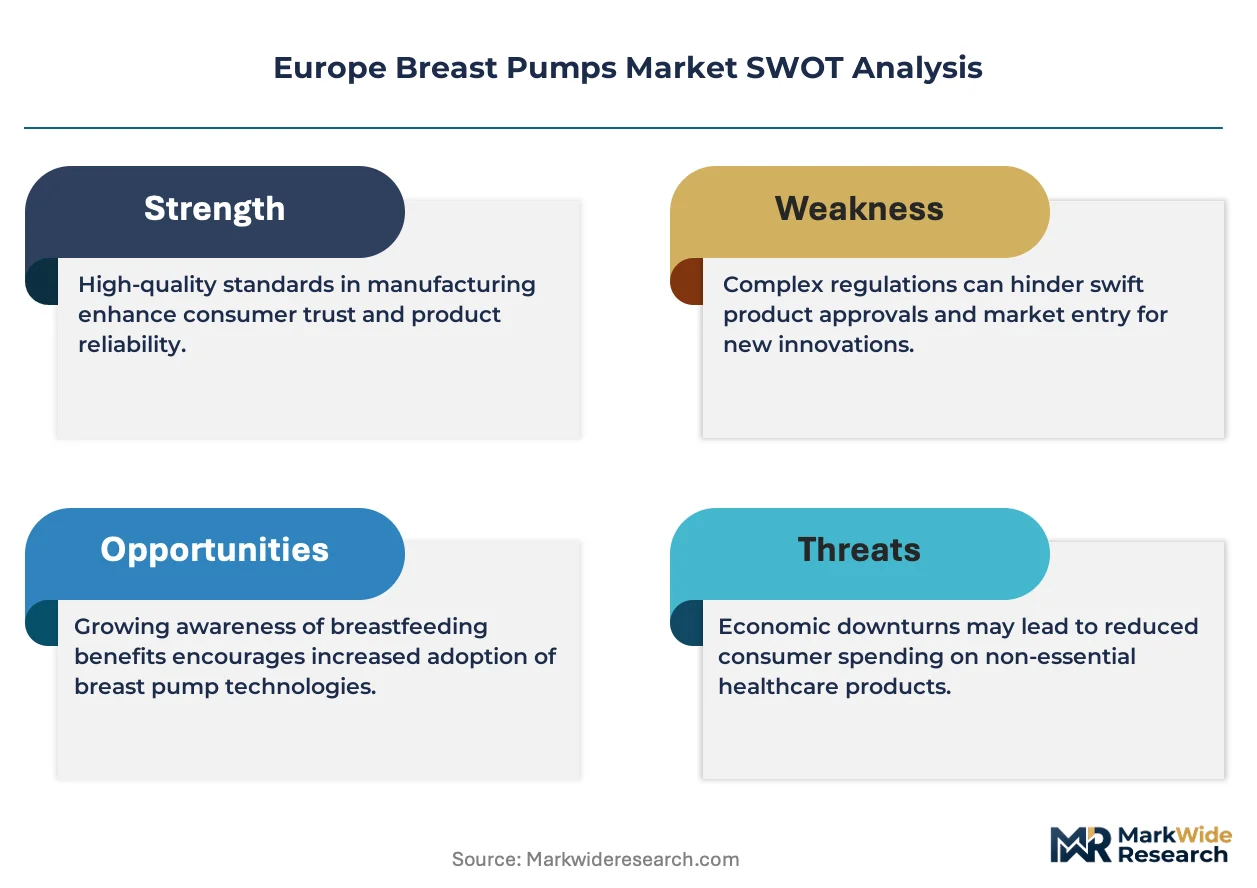
- German statutory reimbursement:Health insurance coverage for electric breast pump rentals creates predictable demand pools that stabilize manufacturer revenue forecasting across hospital procurement cycles.
- Closed-system technology:Backflow prevention mechanisms mandated under EU MDR biocompatibility standards are accelerating hospital-grade specification upgrades in neonatal wards.
- Wearable motor miniaturization:Dutch and Swedish engineering clusters are developing garment-integrated pump motors that eliminate tethered tubing constraints for ambulatory mothers.
Market Restraints
- Silicone supply concentration:REACH-compliant medical-grade silicone sourcing concentrates among three European chemical suppliers, exposing pump manufacturers to input cost volatility.
- MDR transition friction:The Medical Device Regulation's tightened clinical evidence requirements extend registration timelines by 18-24 months for Class IIa pump submissions.
- Manual pump substitution:Price-sensitive consumers in Southern European markets retain preference for manual suction devices that bypass electrical certification costs.
Strategic Opportunities
- Polish retail expansion:Pharmacy channel penetration remains underdeveloped in Warsaw and Kraków metropolitan zones relative to Western European coverage density.
- Subscription rental models:Direct-to-consumer platforms in Scandinavia are piloting monthly hardware-as-a-service arrangements that decouple upfront purchase barriers.
- CSRD sustainability reporting:The Corporate Sustainability Reporting Directive creates procurement preference for manufacturers documenting circular material flows in pump housing production.
Industry Challenges
- Biocompatibility testing capacity:EU-notified body bottlenecks for cytotoxicity and sensitization studies delay product launch schedules.
- Midwife network integration:German hospital-grade pump rentals require certification alignment with regional midwife association protocols that vary across Länder boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Breast Pumps Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $954.07 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Pumps, Electric Pumps, Battery-Operated Pumps, Hospital-Grade Pumps End User: Mothers, Hospitals, Clinics, Lactation Consultants Distribution Channel: Pharmacies, Online Retailers, Hospital Supply, Specialty Stores Technology: Closed System, Open System, Smart Technology, Wearable Pumps |
| Companies Covered | Spectra Baby USA, Ameda, Medela AG, Lansinoh, Mayborn Group Limited, Koninklijke Philips N.V., Ardo Medical Ltd., Artsana S.p.A., Pigeon Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Breast Pumps Market Strategic Shifts & Innovations
Wearable form factors and connected health architectures are redefining how European mothers interact with lactation technology, compressing the boundary between clinical-grade efficacy and consumer convenience.
Motor miniaturization through brushless DC architectures is electrifying the wearable breast pump segment. German component suppliers are shipping sub-40-gram drive units to Dutch OEMs at volumes that now match traditional hospital-grade motor orders. This power density breakthrough is compressing the price-performance gap between prescription and over-the-counter purchase tiers.
EU MDR post-market surveillance requirements are mandating systematic adverse event reporting for vacuum pressure deviations exceeding 250 mmHg thresholds. Manufacturers must now maintain electronic data capture systems that feed directly into EUDAMED, the European database on medical devices. French and Italian health technology assessment bodies are incorporating this surveillance data into reimbursement eligibility reviews for rental-grade equipment.
Hospital supply agreements are fragmenting as procurement departments unbundle motor unit purchases from disposable flange and tubing contracts. German university hospitals now source collection kits through separate tenders that emphasize single-patient-use sterilization guarantees. This purchasing pattern shift is most visible in Bavaria and Baden-Württemberg, where centralized procurement consortia have dissolved into specialty-specific buying groups.
Europe Breast Pumps Market Segmentation
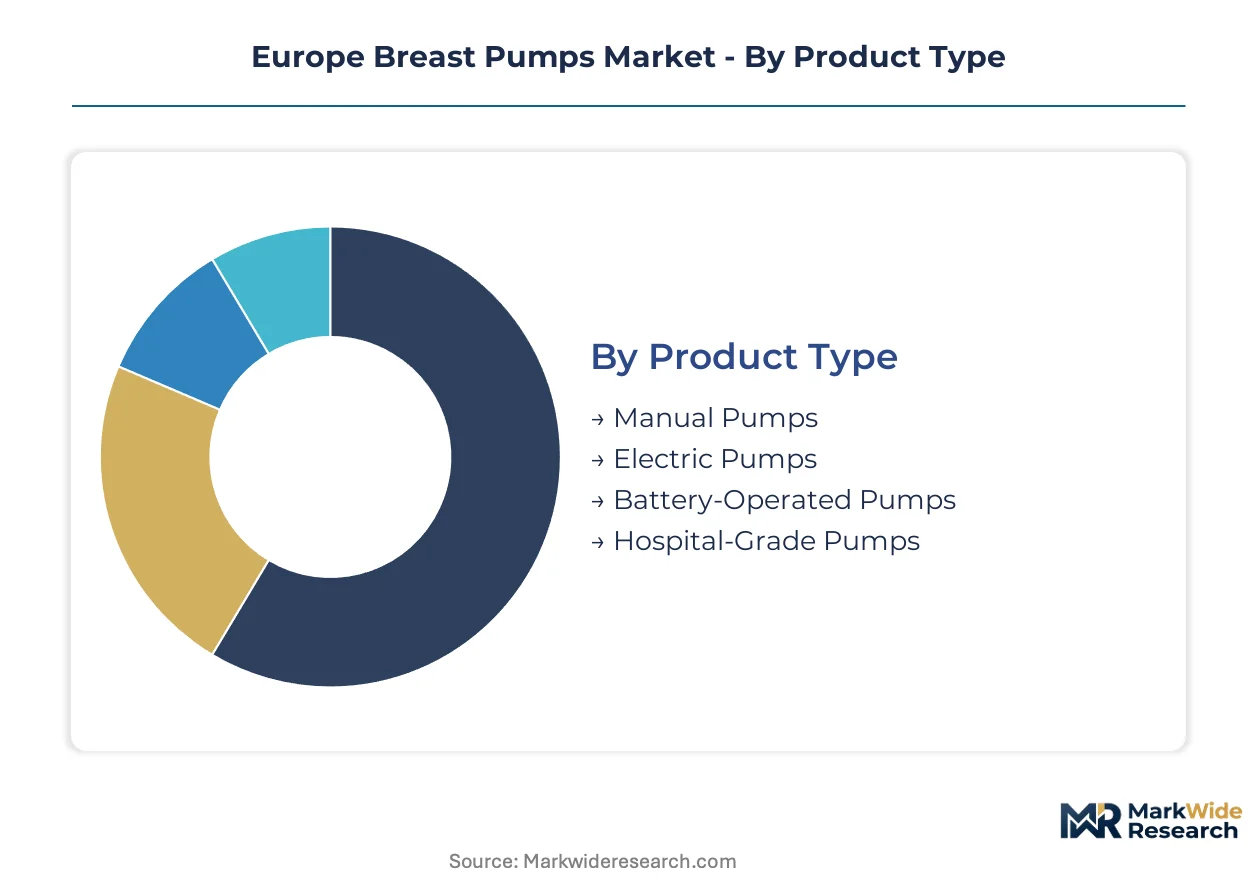
European breast pump purchasing decisions fragment across reimbursement eligibility, clinical setting requirements, and consumer convenience preferences. Manufacturers must align product architectures with distinct regulatory pathways and channel margin structures that vary sharply between hospital procurement and direct-to-consumer retail.
Product Type:
Buyers in this category differentiate primarily by power source dependency and suction control precision rather than price alone.
- Manual Pumps:Hand-operated suction devices using piston or lever mechanisms generate vacuum through mechanical force without electrical components. Demand concentrates in Southern European pharmacy channels where price-sensitive consumers in Spain and Italy bypass reimbursement paperwork for immediate purchase.
- Electric Pumps:Mains-powered motor units deliver programmable cycle frequencies and adjustable vacuum pressures between 100-250 mmHg. German statutory health insurance reimbursement for rental-grade electric units anchors volume concentration in hospital procurement cycles across Bavaria and North Rhine-Westphalia.
- Battery-Operated Pumps:Rechargeable lithium-ion powered units enable portable expression without tethering to wall outlets. French and Belgian mothers favor these for workplace lactation rooms where electrical access varies.
- Hospital-Grade Pumps:Multi-user rental devices with closed-system barriers and industrial motor durability withstand continuous clinical use. Neonatal wards in British National Health Service trusts specify these for premature infant feeding support.
Volume sits with Electric Pumps; growth tilts toward Hospital-Grade Pumps.
End User:
Specification requirements diverge sharply between clinical professionals seeking sterilization guarantees and individual consumers prioritizing portability.
- Mothers:Individual lactating women purchasing for home use evaluate noise levels, flange sizing options, and garment compatibility. Dutch direct-to-consumer brands target Amsterdam and Rotterdam metropolitan mothers with wearable subscription models.
- Hospitals:Procurement departments mandate closed-system architectures, biocompatibility certifications under EU MDR, and multi-year service contracts. German university hospitals in Berlin and Munich unbundle motor purchases from disposable collection kit tenders.
- Clinics:Private maternity facilities and pediatric practices require mid-grade electric units with patient education support materials. Polish clinic networks in Warsaw remain underpenetrated relative to Western European density.
- Lactation Consultants:Independent breastfeeding specialists recommend specific flange geometries and suction patterns to clients, functioning as de facto channel influencers in Swedish midwife networks.
Procurement volume concentrates with Hospitals; consultant-mediated recommendations are expanding most quickly.
Distribution Channel:
Channel selection determines margin capture, with hospital supply agreements yielding highest per-unit returns and online retail displacing replacement part foot traffic.
- Pharmacies:Licensed retail dispensaries provide immediate product access and insurance claim processing assistance. Belgian and Dutch pharmacy chains dominate Avent-branded closed-system distribution through trained staff consultation.
- Online Retailers:E-commerce platforms capture replacement flange, tubing, and accessory purchases that mothers previously sourced through physical pharmacy visits. Scandinavian direct-to-consumer brands pilot hardware-as-a-service monthly subscriptions.
- Hospital Supply:Specialized medical device distributors serve institutional procurement with sterilization documentation and batch traceability. German centralized purchasing consortia in Baden-Württemberg fragment into specialty-specific buying groups.
- Specialty Stores:Maternity and baby product retailers offer hands-on demonstration and fitting services. Premium positioning in Swiss urban centers sustains higher price realization.
Transaction volume flows through Online Retailers; margin protection remains strongest in Hospital Supply.
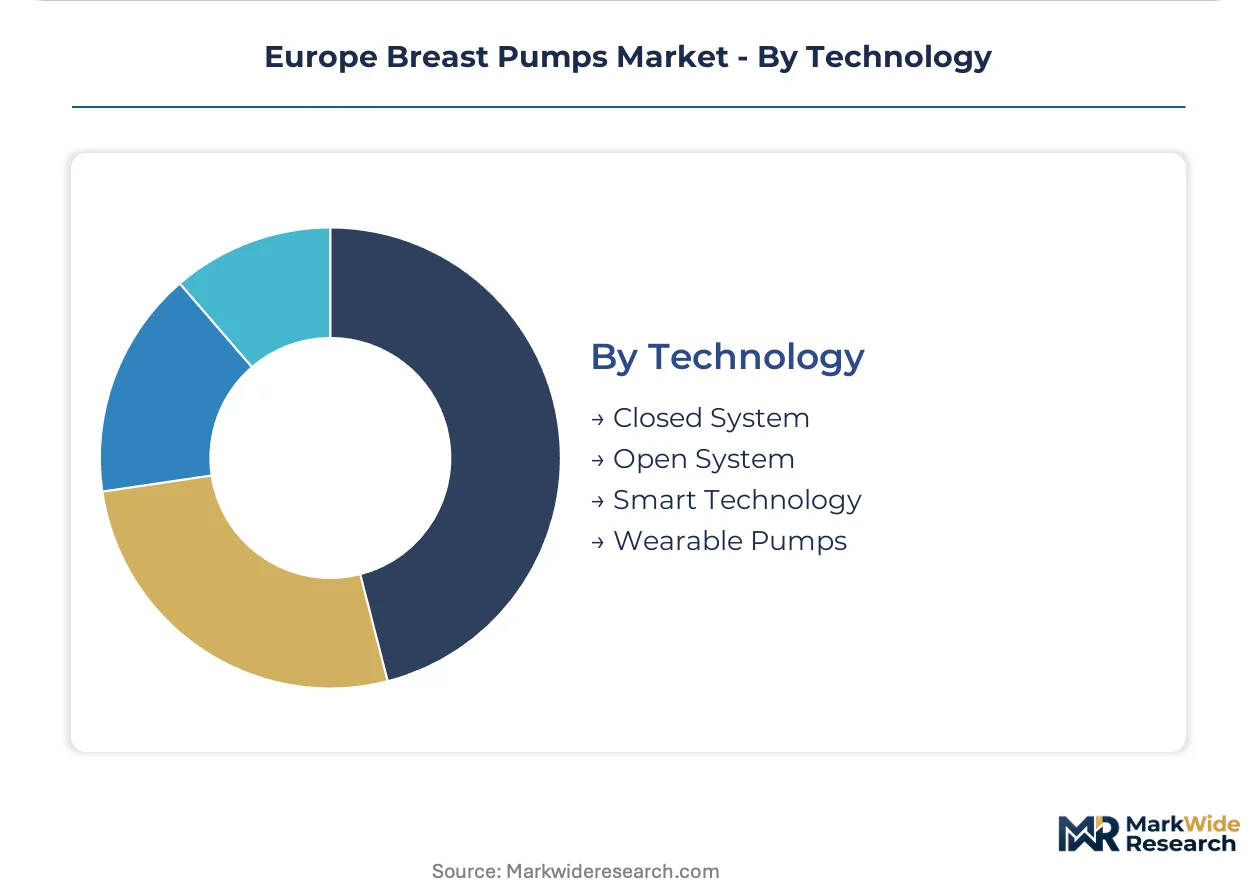
Technology:
Regulatory classification under EU MDR 2017/745 and biocompatibility testing requirements separate compliant architectures from legacy open-system designs facing market withdrawal.
- Closed System:Backflow prevention barriers isolate milk pathways from pump motors and tubing, eliminating contamination risk between users. EMA biocompatibility standards mandate this architecture for all hospital-grade CE marking renewals.
- Open System:Direct milk-to-motor contact designs without barrier protection persist in economy manual pump segments. REACH-compliant silicone sourcing constraints accelerate phase-out in favor of closed alternatives.
- Smart Technology:Bluetooth-connected pumps with mobile app integration track expression volumes, cycle patterns, and lactation schedules. French health technology assessment bodies incorporate this surveillance data into reimbursement reviews.
- Wearable Pumps:Garment-integrated motor units eliminate external tubing through brushless DC miniaturization. Dutch and Swedish engineering clusters drive steepest expansion trajectory as sub-40-gram drive units reach volume parity with traditional hospital-grade motors.
Installed base remains concentrated in Closed System; Wearable Pumps are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Swiss and German precision engineering clusters, while consumption patterns diverge sharply across national reimbursement frameworks. Southern European markets favor manual pump purchases, whereas Northern European health systems institutionalize electric pump rentals through statutory coverage.
Germany
Statutory health insurance funds reimburse electric breast pump rentals for new mothers, creating predictable demand pools across hospital procurement cycles. The EU MDR 2017/745 framework mandates closed-system architectures for CE marking renewal, tightening biocompatibility documentation requirements. Bavarian university hospitals in Munich and Erlangen unbundle motor purchases from disposable collection kit tenders, fragmenting supply agreements.
United Kingdom
British National Health Service trusts specify hospital-grade pumps for premature infant feeding support in neonatal wards, anchoring institutional volume. MHRA post-Brexit regulatory alignment with EU MDR maintains backflow prevention standards for closed-system devices. London procurement consortia and Midlands hospital networks drive specification upgrades through centralized purchasing frameworks.
France
French health technology assessment bodies incorporate EUDAMED surveillance data into reimbursement eligibility reviews for rental-grade equipment. ANSM oversight enforces cytotoxicity testing protocols for silicone components under REACH compliance. The Île-de-France region and Lyon metropolitan clusters concentrate pharmacy distribution for Avent-branded closed-system designs.
Netherlands
Dutch direct-to-consumer brands pilot hardware-as-a-service monthly subscriptions that decouple upfront purchase barriers for Amsterdam and Rotterdam mothers. EMA medical device regulations govern CE marking pathways for wearable pump configurations with garment-integrated motors. Eindhoven engineering clusters supply sub-40-gram brushless DC drive units to regional OEMs at volumes matching traditional hospital-grade orders.
Sweden
Swedish midwife networks function as de facto channel influencers, mediating pump recommendations through independent breastfeeding specialists. REACH-compliant medical-grade silicone sourcing constraints expose manufacturers to input cost volatility from limited European chemical suppliers. Stockholm and Gothenburg metropolitan zones drive steepest wearable pump adoption as engineering clusters redesign motors for garment integration.
Europe Breast Pumps Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across distinct channel and technology vectors. The market structure tilts toward consolidation in hospital supply agreements, while direct-to-consumer retail fragments across subscription models and pharmacy distribution. Three archetypes dominate: Swiss-German precision manufacturers with hospital-grade positioning, Dutch-Swedish wearable innovators leveraging motor miniaturization, and diversified health technology conglomerates with pharmacy channel control. Competitive moves center on unbundling procurement contracts and geographic expansion into underpenetrated Central European markets.
Within the precision manufacturing tier, Medela AG and Ardo Medical Ltd. exemplify focused specialists anchoring hospital-grade rental networks through German midwife associations and neonatal ward specifications. Koninklijke Philips N.V. occupies a diversified conglomerate position, leveraging Avent-branded distribution through Belgian and Dutch pharmacy chains. These three entities represent distinct strategic postures: captive manufacturing depth, clinical channel integration, and consumer health portfolio breadth.
| Leading Market Players |
|---|
| Spectra Baby USA |
| Ameda |
| Medela AG |
| Lansinoh |
| Mayborn Group Limited |
| Koninklijke Philips N.V. |
| Ardo Medical Ltd. |
| Artsana S.p.A. |
| Pigeon Corporation |
| Others |
Cost & Logistics Intelligence
German statutory health insurance procurement pools anchor pricing power for hospital-grade electric breast pump rentals, compressing margin structures for manufacturers competing on CE marking compliance rather than brand premium. This buyer concentration forces three-tier pricing stratification across premium Swiss-manufactured closed-system units, mid-grade Dutch pharmacy brands, and economy manual alternatives in Southern European markets.
Pricing Analysis
Margin tightening in the wearable pump segment traces to brushless DC motor commoditization as Eindhoven engineering clusters ship sub-40-gram drive units at volumes matching traditional hospital-grade orders. Pricing stratifies across premium closed-system rentals, standard battery-operated portable units, and economy manual devices based on EU MDR certification tier and sterilization documentation depth. Cost-down pressure on manual pump manufacturers accelerates because REACH-compliant silicone sourcing concentrates among three European chemical suppliers. Price sensitivity concentrates most heavily among Spanish and Italian pharmacy consumers bypassing reimbursement paperwork, while German hospital procurement committees prioritize biocompatibility guarantees over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle component demand from Dutch and Swedish wearable pump developers, while specialized medical device distributors serve fragmented German hospital procurement consortia. Manufacturing concentrates in Swiss precision engineering clusters for hospital-grade motor units, German component suppliers for brushless DC architectures, and Dutch assembly operations for garment-integrated wearable configurations. Raw material dependencies center on REACH-compliant medical-grade silicone for tubing and flange assemblies, lithium-ion cells for portable battery systems, and BPA-free thermoplastics for pump housings. Single-source vulnerability in medical-grade silicone exposes manufacturers to input cost volatility from limited European chemical suppliers. Distribution runs through hospital supply agreements capturing highest per-unit margins, online retailers displacing pharmacy foot traffic for replacement parts, and pharmacy chains dominating Belgian and Dutch closed-system sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe breast pumps market is becoming a vertical-integration race as manufacturers pursue captive control over REACH-compliant silicone supply to defend margin structures against raw material volatility.
For Market Incumbents: Extend service contract bundling beyond motor units into disposable collection kit tenders, capturing recurring revenue streams as German university hospitals fragment procurement agreements. Deepen backward integration into medical-grade silicone compounding to offset supply concentration risk from European chemical suppliers. Prioritize EUDAMED surveillance data infrastructure investment to accelerate CE marking renewals under EU MDR post-market requirements and outpace notified body bottlenecks. For New Entrants and Emerging Players: EU MDR 2017/745 in Germany opens a window for subscription rental models that decouple upfront purchase barriers for Amsterdam and Rotterdam metropolitan mothers. Target Polish pharmacy channel penetration in Warsaw and Kraków metropolitan zones where closed-system distribution remains underdeveloped relative to Western European density. Pursue hardware-as-a-service go-to-market positioning that aligns with Scandinavian direct-to-consumer pilot programs and captures recurring revenue without competing on upfront device cost. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with captive manufacturing depth in brushless DC motor miniaturization and established German midwife network relationships. Long-term viability hinges on reimbursement policy stability across French, German, and Italian health technology assessment frameworks rather than pure retail volume capture. Watch EUDAMED adverse event reporting thresholds for vacuum pressure deviations as the signal indicating regulatory enforcement intensity and product liability exposure escalation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR biocompatibility documentation accelerates registration timelines for Class IIa pump submissions. |
| Hospital System Partnership | German university hospital unbundling creates entry points for collection kit tender specialization. |
| Backward Integration into Silicone | Captive supply of REACH-compliant medical-grade material defends against European chemical supplier concentration. |
| Software Companion Development | Bluetooth-connected pumps with EUDAMED-integrated data capture satisfy French HTA reimbursement review requirements. |
| Reimbursement Strategy Alignment | German statutory health insurance rental coverage stabilizes revenue forecasting across procurement cycles. |
Research Approach
Independent corroboration across hospital procurement databases, GPO contracts, and EUDAMED surveillance records underwrites the qualitative findings on closed-system technology adoption. Primary interviews with hospital purchasing committee members, biomedical engineers, midwife association representatives, and regulatory affairs specialists at notified bodies combined with secondary validation from EMA MDR guidance documents, REACH compliance filings, and national health technology assessment publications. Bottom-up triangulation across product-type segmentation and top-down reconciliation against statutory reimbursement expenditure data ensure internal consistency.
Rate-of-change decomposition across the projection horizon isolates volume drivers from price-mix effects in electric, battery-operated, and wearable pump configurations. Segmentation dimensions modeled include power source dependency, end-user setting, distribution channel margin structure, and technology architecture classification under EU MDR 2017/745. CAGRs derive from installed base replacement cycles, reimbursement policy stability assumptions, and motor miniaturization adoption curves. Industry-specific forecast inputs incorporate EUDAMED adverse event reporting thresholds and German statutory health insurance rental coverage expansion trajectories.
Caveats apply where notified body bottlenecks for cytotoxicity testing, REACH silicone supply disruptions, or midwife network certification protocol fragmentation across German Länder boundaries could materially shift the outlook. Forecasts reflect documented assumptions on regulatory enforcement intensity and reimbursement eligibility stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Medical Cyclotron Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Neonatal Hearing Screening Devices Market
Medical Devices
Infant Oxygen Hoods Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Implant Handpiece Market
Medical Devices
Global Chemotherapy Devices Market
Medical Devices
Global Disability Devices Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Endoscope Flushing Pumps Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Global Aneurysm Clips Market
Medical Devices
Global Soft Tissue Allografts Market