
 Integrated Cardiology Devices Market | 2026-2036
Integrated Cardiology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Cardiology Devices Market Outlook
China is fragmenting its integrated cardiology device supply base as domestic manufacturers scale catheter and stent production for regional export. Medtronic leverages extensive R&D pipelines across pacemaker and defibrillator platforms to sustain technology leadership. Edwards Lifesciences Corporation anchors premium transcatheter valve segments with specialized structural heart expertise. Abbott Laboratories differentiates through biometric sensor integration and wireless monitoring system architectures.
Integrated cardiology devices combine implantable and external cardiovascular therapeutic and diagnostic hardware with embedded software, biometric sensors, and wireless telemetry operating at 2.4 GHz ISM band frequencies for real-time hemodynamic monitoring and automated therapy delivery. These systems serve to unify acute intervention, chronic disease management, and preventive cardiac care within connected clinical workflows. Pacemakers and defibrillators capture the deepest margin pools due to long implant lifecycles and proprietary battery chemistry dependencies, while wireless monitoring and smart software represent the fastest-expanding technology layer as health systems prioritize remote patient surveillance. Catheters and imaging systems occupy mature, volume-driven positions where price transparency pressures concentrate among high-throughput hospital purchasers.
FDA premarket approval requirements for Class III cardiovascular devices enforce extensive clinical evidence standards that extend development timelines and elevate capital barriers for new entrants. The EU Medical Device Regulation and CE marking frameworks impose post-market surveillance obligations and unique device identification mandates that reshape quality management systems for manufacturers serving European hospitals. Stakeholders must monitor evolving cybersecurity guidance from FDA and IEC for connected cardiac devices, as network-enabled implants introduce liability and patient safety considerations distinct from traditional hardware-only platforms.
Market Dynamics
Wireless telemetry integration at 2.4 GHz ISM frequencies is compressing the traditional boundary between acute intervention hardware and chronic disease management platforms, forcing manufacturers to rearchitect product portfolios around continuous data streams rather than episodic device deployment.
Growth Catalysts
- FDA Class III PMA Pathways:Premarket approval requirements for implantable cardioverter-defibrillators enforce clinical evidence standards that filter out undercapitalized competitors, concentrating margin pools among established manufacturers with trial infrastructure.
- Hospital Cath Lab Modernization:Integrated catheterization laboratory upgrades in the United States drive replacement cycles for imaging systems and hemodynamic monitoring consoles as health systems consolidate cardiovascular service lines.
- Biometric Sensor Miniaturization:Advances in MEMS pressure transducers and accelerometers enable leadless pacemaker architectures and injectable cardiac monitors, expanding the addressable patient population for ambulatory arrhythmia surveillance.
Market Restraints
- Lithium-Iodine Battery Chemistry Concentration:Proprietary cell designs for implantable devices create single-source dependencies on specialized battery suppliers, exposing manufacturers to input cost volatility and qualification timeline risk.
- EU MDR Transition Friction:The Medical Device Regulation's post-market surveillance obligations and unique device identification mandates force substantial quality management system rewrites, extending recertification timelines for legacy product lines.
- Substitute Monitoring Modalities:Wearable consumer electrocardiography devices from Apple and Withings capture low-acuity arrhythmia detection, pressuring reimbursement for prescription-grade ambulatory monitors in primary care settings.
Strategic Opportunities
- Remote Patient Monitoring Infrastructure:Medicare reimbursement codes for continuous cardiac telemetry create financial tailwinds for wireless monitoring system deployments in post-acute care settings and skilled nursing facilities.
- Structural Heart Convergence:Integration of transcatheter valve delivery systems with real-time intracardiac echocardiography guidance enables single-procedure workflows that reduce cath lab utilization time and anesthetic exposure.
- India Medical Device Manufacturing:Production-linked incentive schemes and dedicated medical device parks in Andhra Pradesh and Tamil Nadu attract catheter and stent assembly operations targeting Middle East and Southeast Asian export markets.
Industry Challenges
- Cybersecurity Engineering Talent Scarcity:Network-enabled implants require specialized firmware security expertise that traditional cardiovascular hardware engineering teams lack, forcing reliance on external consultants or acquisition of digital health startups.
- Legacy Electronic Health Record Integration:Proprietary data formats from implantable device interrogators create interoperability friction with hospital information systems, requiring expensive custom interface development for each health system deployment.
- Clinical Evidence Generation Burden:Longitudinal outcome studies for novel pacing algorithms or automated therapy delivery systems demand multi-year follow-up periods that delay product launches and consume substantial R&D capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Cardiology Devices Market |
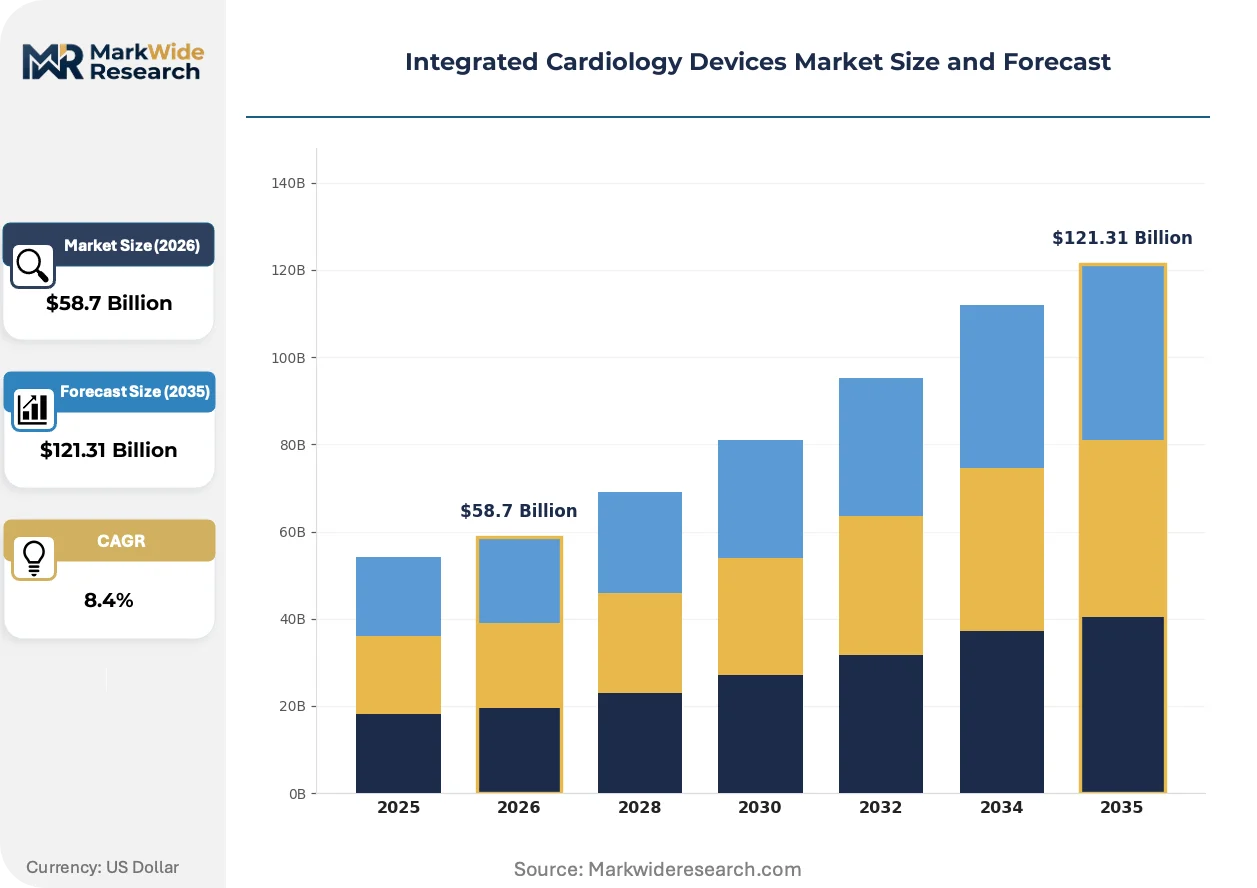
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pacemakers, Stents, Catheters, Defibrillators Technology: Wireless Monitoring, Biometric Sensors, Imaging Systems, Smart Software End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Application: Heart Failure, Arrhythmia Management, Coronary Artery Disease, Diagnostics |
| Companies Covered | Johnson & Johnson, Edwards Lifesciences Corporation, Medtronic, Lepu Medical Technology, Getinge AB, Boston Scientific Corporation, Koninklijke Philips N.V., Terumo Corporation, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Cardiology Devices Market Strategic Shifts
Cardiovascular device architectures are converging around software-defined functionality, with embedded algorithms displacing fixed hardware logic and enabling post-implant therapy parameter adjustments without surgical revision.
Leadless pacing technology is collapsing the traditional transvenous lead infrastructure that has defined cardiac rhythm management for four decades. Medtronic's Micra and Abbott's Aveir platforms eliminate lead fracture and extraction risks that drive long-term complications. Hospital systems in Germany and the Netherlands are prioritizing leadless devices for elderly patients with vascular access limitations, compressing the market for conventional dual-chamber systems in this demographic.
The EU Medical Device Regulation's enhanced clinical evidence requirements for Class III implants are forcing manufacturers to maintain parallel technical documentation systems for European and United States submissions. Notified body capacity constraints in Germany and the Netherlands extend review timelines, delaying product launches by 12-18 months compared to FDA clearance pathways. High-risk structural heart devices face the most severe documentation burden, with some manufacturers deprioritizing European market entry.
Health system procurement committees are consolidating vendor relationships for integrated cardiology suites, bundling imaging systems, hemodynamic monitors, and electrophysiology recording platforms under multi-year enterprise agreements. This concentration displaces the traditional best-of-breed purchasing model where cardiologists selected individual devices. The shift is most visible in United States integrated delivery networks, where standardized platforms reduce training costs and service contract complexity across multiple hospital sites.
Integrated Cardiology Devices Market Segmentation
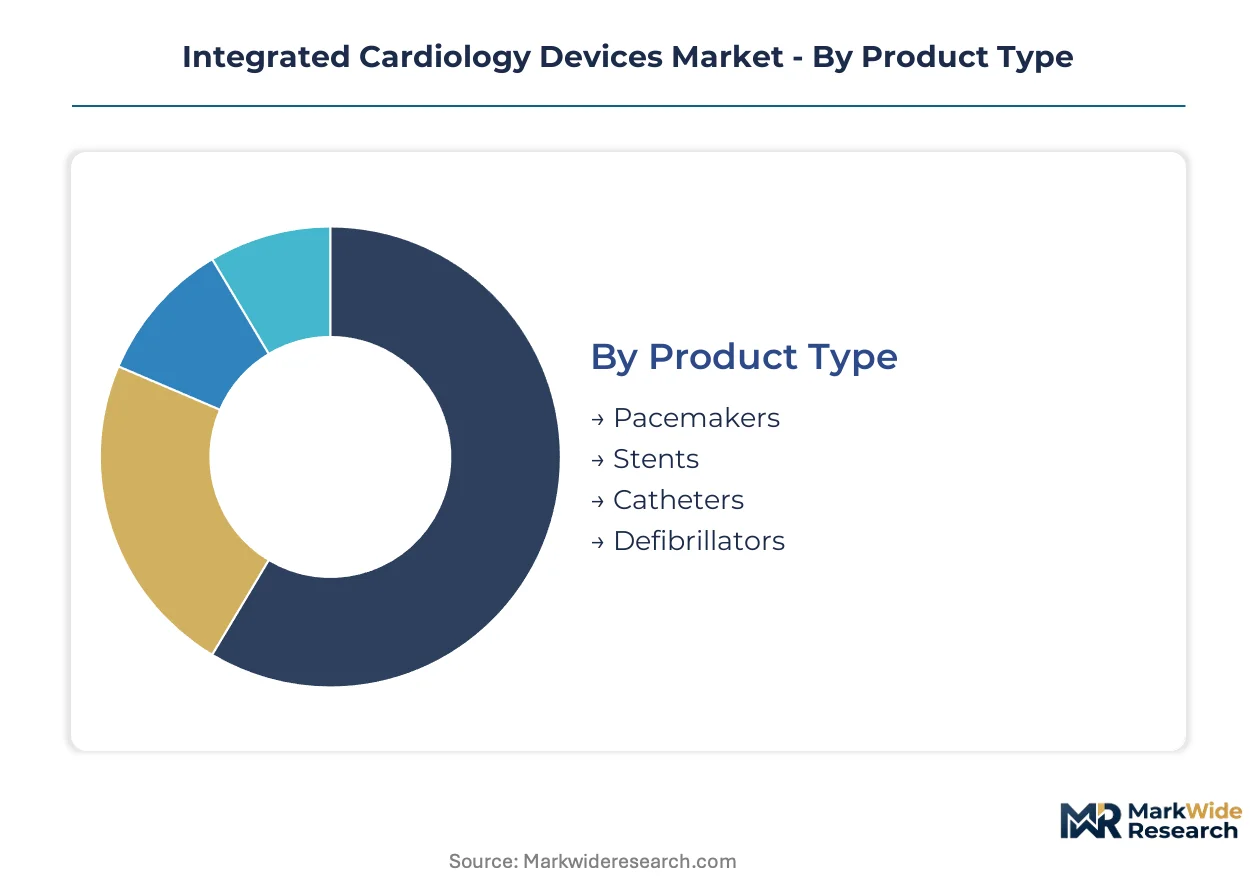
Segmentation in integrated cardiology devices reveals how therapeutic hardware, diagnostic platforms, and care settings interlock. Manufacturers configure product portfolios around procedure volume, reimbursement pathways, and integration complexity rather than single-device sales.
Product Type:
Use-case spectrum spans acute intervention hardware through chronic implantable systems, with each category carrying distinct margin profiles and replacement cycles.
- Pacemakers:Battery-powered implantable pulse generators with lithium-iodine cells delivering electrical stimuli to regulate bradycardia. Demand concentrates in United States hospital systems adopting leadless architectures for elderly patients with vascular access limitations, driven by Medicare reimbursement for minimally invasive procedures.
- Defibrillators:Implantable cardioverter-defibrillators and external automated units delivering high-energy shocks to terminate ventricular fibrillation. United States integrated delivery networks drive replacement cycles as cath lab modernization programs bundle device upgrades with enterprise service agreements.
- Stents:Expandable mesh scaffolds restoring coronary lumen patency following percutaneous intervention.
- Catheters:Flexible intravascular delivery platforms for diagnostic angiography and therapeutic intervention.
The dominant share belongs to Pacemakers, while Defibrillators is closing the gap fastest.
Technology:
Cost tier separation distinguishes premium integrated platforms from component-level hardware, with software and telemetry commanding expanding margin pools.
- Wireless Monitoring:2.4 GHz ISM band telemetry systems transmitting real-time hemodynamic data from implantable sensors to external receivers. United States skilled nursing facilities and post-acute care settings deploy these systems under Medicare reimbursement codes for continuous cardiac surveillance.
- Smart Software:Embedded algorithms enabling post-implant therapy parameter adjustments and predictive arrhythmia detection without surgical revision. United States health systems prioritize these platforms to reduce readmission penalties and extend device lifecycle value.
- Biometric Sensors:MEMS pressure transducers and accelerometers capturing physiological signals for automated therapy modulation.
- Imaging Systems:Fluoroscopy and intracardiac echocardiography platforms guiding structural heart procedures.
Wireless Monitoring holds the dominant share, while Smart Software is expanding most quickly.
End User:
Customer type fragmentation reflects care setting economics, with inpatient facilities capturing high-acuity procedures and outpatient sites absorbing monitoring-intensive workflows.
- Hospitals:Acute care facilities with integrated catheterization laboratories performing implantation, intervention, and complex electrophysiology procedures. United States integrated delivery networks consolidate vendor relationships across multiple sites, bundling imaging systems and hemodynamic monitors under multi-year enterprise agreements.
- Home Care:Residential settings where patients manage chronic cardiac conditions through remote monitoring infrastructure and wearable telemetry devices. United States reimbursement codes for continuous cardiac telemetry accelerate deployment of wireless systems in skilled nursing and home-based recovery.
- Clinics:Outpatient facilities conducting diagnostic workup and device follow-up interrogation.
- Rehabilitation Centers:Post-acute facilities integrating cardiac telemetry into recovery protocols.
Hospitals command the dominant share, while Home Care is gaining share fastest.
Application:
Volume concentration tracks disease prevalence and procedure reimbursement, with chronic condition management outpacing episodic intervention in platform economics.
- Arrhythmia Management:Detection and treatment of atrial fibrillation, ventricular tachycardia, and conduction disorders through pacing, defibrillation, and ablation. United States electrophysiology service lines expand as health systems prioritize remote patient surveillance to reduce emergency department utilization.
- Heart Failure:Monitoring and therapeutic modulation for reduced ejection fraction and preserved ejection fraction patients. United States hospital systems deploy hemodynamic monitoring platforms to manage decompensation risk and avoid costly admissions.
- Coronary Artery Disease:Revascularization and medical management of atherosclerotic obstruction.
- Diagnostics:Non-invasive and invasive assessment of cardiac structure and function.
Arrhythmia Management holds the dominant share, while Heart Failure is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways for Class III cardiovascular devices establish the regulatory baseline that shapes integrated cardiology device development timelines across major markets. Hospital systems in the United States drive replacement cycles for wireless monitoring systems and cath lab infrastructure. China fragments its supply base as domestic manufacturers scale production for regional export.
United States
Integrated delivery networks consolidate vendor relationships across multiple hospital sites, bundling imaging systems and hemodynamic monitors under multi-year enterprise agreements. Medicare reimbursement codes for continuous cardiac telemetry accelerate deployment of wireless monitoring systems in skilled nursing facilities and post-acute care settings. The Minneapolis medical technology corridor anchors pacemaker and defibrillator R&D operations for manufacturers serving North American electrophysiology service lines.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia prioritize leadless pacing devices for elderly patients with vascular access limitations, compressing demand for conventional dual-chamber systems. EU Medical Device Regulation post-market surveillance obligations and unique device identification mandates force substantial quality management system rewrites for manufacturers serving European hospitals. The Frankfurt-Rhine-Main medical device cluster faces notified body capacity constraints that extend review timelines for Class III implant certifications.
China
Domestic manufacturers scale catheter and stent production for export to Middle East and Southeast Asian markets as NMPA regulatory frameworks mature for high-risk cardiovascular devices. Production-linked incentive schemes and dedicated medical device parks in Andhra Pradesh and Tamil Nadu attract assembly operations targeting regional export markets. The Suzhou medical technology industrial park concentrates transcatheter valve delivery system manufacturing for Asia-Pacific distribution.
India
Production-linked incentive schemes and dedicated medical device parks in Andhra Pradesh and Tamil Nadu attract catheter and stent assembly operations targeting Middle East and Southeast Asian export markets. CDSCO regulatory harmonization with international standards accelerates market entry timelines for multinational manufacturers establishing local manufacturing. The Hyderabad medical device cluster specializes in cost-optimized structural heart device components for emerging market price points.
Japan
PMDA regulatory frameworks for software-enabled cardiac devices impose cybersecurity documentation requirements that extend premarket submission timelines for network-enabled implants. METI industrial policy supports domestic manufacturing of high-value cardiovascular components to reduce import dependency for critical medical devices. The Tokyo-Osaka medical technology corridor concentrates hemodynamic monitoring console assembly for Asia-Pacific hospital system procurement.
Integrated Cardiology Devices Market Competitive Environment
Integrated device manufacturers and component specialists split the market along technology integration depth. The vendor base concentrates among established players with FDA trial infrastructure and proprietary battery chemistry capabilities. Three archetypes dominate: full-stack platform vendors, structural heart specialists, and wireless telemetry innovators. Competitive dynamics center on cath lab modernization bundling and leadless pacing technology transitions.
Within the full-stack platform tier, Medtronic and Abbott Laboratories exemplify integrated portfolio breadth spanning implantable hardware through remote monitoring software. Edwards Lifesciences Corporation occupies a specialized position in transcatheter valve segments. Boston Scientific Corporation represents the diversified cardiovascular intervention archetype with cross-platform electrophysiology capabilities. These anchors reflect the market's stratification between premium integrated suites and targeted component solutions.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Edwards Lifesciences Corporation |
| Medtronic |
| Lepu Medical Technology |
| Getinge AB |
| Boston Scientific Corporation |
| Koninklijke Philips N.V. |
| Terumo Corporation |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in lithium-iodine battery cell production concentrates pricing power among three qualified suppliers serving implantable device manufacturers. This tightness forces cardiovascular OEMs into long-term offtake commitments that lock in component costs and compress margin flexibility for new entrants.
Pricing Analysis
Geographic price spreads between United States hospital systems and Indian private clinics exceed three-to-one for equivalent pacemaker platforms. Pricing stratifies across premium, standard, and economy tiers based on FDA PMA status and wireless telemetry capability. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are scaling stent and catheter exports to Southeast Asia. Price sensitivity peaks among outpatient clinics in emerging markets, while United States integrated delivery networks prioritize enterprise service bundling over unit economics.
Supply Chain Analysis
Upstream feedstock concentration in specialized battery chemistry centers on three countries: United States, Switzerland, and Japan. Lithium-iodine cells, platinum-iridium electrodes, and medical-grade silicone elastomers constitute critical input dependencies. Single-source vulnerability in proprietary battery formulations exposes manufacturers to qualification timeline risk if primary suppliers face regulatory inspection. Distribution runs through authorized distributor networks serving hospital purchasing committees and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where FDA Class III PMA pathways create regulatory entrenchment that filters out undercapitalized competitors and locks in incumbent pricing power.
For Market Incumbents: Entrench proprietary battery chemistry dependencies through exclusive supply agreements with qualified cell manufacturers. Expand wireless monitoring software attach rates to hospital systems undergoing cath lab modernization. This counters margin pressure from leadless pacing technology transitions that compress conventional device lifecycle value. For New Entrants and Emerging Players: Establish a beachhead in India's export-oriented catheter and stent assembly segment. Target cost-optimized structural heart components for Middle East and Southeast Asian price points. Pursue CDSCO manufacturing registrations as a pathway to supply multinational OEMs seeking geographic diversification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform vendors with integrated remote monitoring software and multi-year hospital enterprise agreements. Five-to-ten year viability favors acquirers of wireless telemetry specialists with FDA cybersecurity documentation already filed. Watch for EU MDR notified body capacity expansion as an inflection signal for European market re-entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Class III cardiovascular submissions enforce clinical evidence standards that concentrate margin pools among trial-capable manufacturers. |
| CE Marking Transition Strategy | EU MDR technical documentation rewrites extend recertification timelines and force parallel submission systems for European access. |
| Hospital System Partnership | Integrated delivery network bundling of imaging systems and hemodynamic monitors displaces best-of-breed purchasing models. |
| Software Companion Development | Embedded algorithms enabling post-implant therapy adjustments extend device lifecycle value and reduce surgical revision rates. |
| Reimbursement Strategy | Medicare telemetry codes for skilled nursing facilities accelerate wireless monitoring deployment in post-acute care settings. |
Study Parameters
Initial hypotheses were tested against primary input from electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers and refined through secondary validation. Sources included FDA PMA filings, CMS Medicare reimbursement databases, hospital procurement records, and SEC 10-K device segment disclosures. Bottom-up demand modeling across product categories triangulated with top-down market sizing from trade flow data.
Demand-supply balance dynamics anchored the analytical framework across the analysis window. Segmentation dimensions modeled encompassed product type, technology layer, end-user setting, and application area. CAGRs derived from procedure volume trajectories, replacement cycle timing, and reimbursement pathway expansion. Industry-specific inputs included cath lab modernization spend patterns and leadless pacing adoption curves.
Sensitivities concentrate around FDA cybersecurity guidance evolution, EU notified body capacity constraints, and lithium-iodine cell supply disruptions. Forecasts reflect assumptions regarding hospital consolidation trajectories and remote monitoring reimbursement stability. Cross-checking against CMS Medicare claims data and hospital capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Pulmonary Artery Catheter Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Cardiovascular Ultrasound Imaging Systems Market
Cardiovascular Devices
Chile Cardiovascular Devices Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Ventricular Drainage Sets Market
Cardiovascular Devices
Global Intracranial Stents Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Abdominal Stent Graft System Market