
 Sacroiliac Joint Fusion Market | 2026-2036
Sacroiliac Joint Fusion Market Size, Share, and Industry Trends Forecast 2026-2036
Sacroiliac Joint Fusion Market Intelligence
Modular implant systems paired with disposable instrument kits is broadening the addressable market for ambulatory surgery centers. SI-BONE Inc. anchors the minimally invasive segment with its iFuse implant system and dedicated surgeon training infrastructure. Medtronic plc leverages its broader spine portfolio to cross-sell sacroiliac solutions through established orthopedic channels. Globus Medical Inc. competes on integrated navigation and imaging compatibility across its fusion platforms.
Sacroiliac joint fusion is a surgical intervention that stabilizes the articulation between the sacrum and ilium using titanium or PEEK implants, bone graft material, and fixation hardware to eliminate pathologic motion and relieve chronic pain. The procedure typically requires fluoroscopic guidance and achieves fusion through osteointegration over a twelve-to-twenty-four-month biological window. Minimally invasive surgery dominates procedural volume due to reduced blood loss and shorter recovery trajectories, while robotic-assisted surgery represents the fastest-growing technology segment as capital equipment costs decline and surgical precision demands intensify. Implant products capture the largest margin pool, though bone graft substitutes are gaining share as synthetic and allograft formulations reduce donor-site morbidity.
The FDA's 510(k) premarket notification process governs implant clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for CE marking across European markets. ISO 13485 quality management standards and ASTM F2077 mechanical testing protocols shape manufacturing compliance and product liability exposure for device manufacturers. Stakeholders must monitor reimbursement coding evolution, particularly Category III CPT code transitions that determine commercial payer coverage and hospital capital allocation for sacroiliac programs.
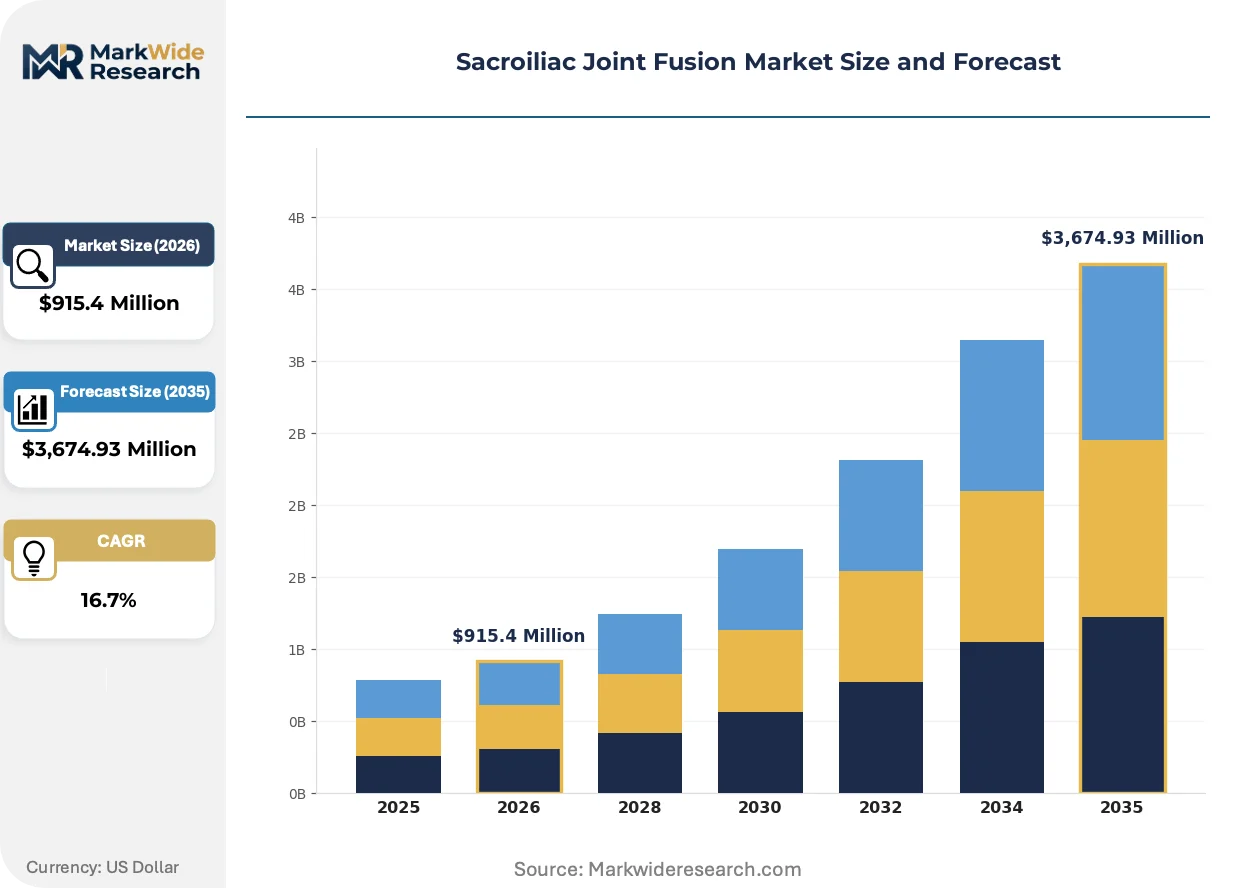
Market Dynamics
The transition of sacroiliac joint fusion from inpatient hospital settings to ambulatory surgery centers is compressing procedural economics and forcing implant manufacturers to redesign product form factors for streamlined outpatient workflows.
Growth Catalysts
- Category III CPT Code Migration:The American Medical Association's establishment of permanent Category I CPT codes for minimally invasive sacroiliac fusion procedures is securing commercial payer reimbursement and accelerating hospital capital allocation toward dedicated spine programs.
- Titanium Plasma-Sprayed PEEK Implants:Advanced surface engineering combining polyetheretherketone substrates with osteoconductive coatings is improving fusion rates and reducing revision surgery incidence in high-demand patient populations.
- Ambulatory Surgery Center Expansion:United States-based ASC networks are adding sacroiliac procedures to orthopedic service lines, driven by compressed recovery protocols and favorable site-of-service payment differentials under Medicare's Hospital Outpatient Prospective Payment System.
Market Restraints
- Allograft Supply Volatility:Donor tissue availability constraints and processing facility capacity limitations in the United States are creating intermittent shortages of demineralized bone matrix products essential for biologic fusion enhancement.
- Fluoroscopy Duration Exposure:Procedural radiation dose accumulation for surgical staff remains a technical limitation, with cumulative exposure thresholds constraining case volume per operating room team and elevating occupational health compliance costs.
- EU MDR Clinical Evidence Burden:The European Union Medical Device Regulation's expanded clinical investigation requirements for CE marking are extending approval timelines and elevating regulatory expenditure for implant manufacturers seeking European market access.
Strategic Opportunities
- Robotic Navigation Convergence:Integration of optical tracking systems with preoperative planning software is enabling sub-millimeter screw placement accuracy, opening premium pricing tiers for technology-enabled procedural bundles in academic medical centers.
- Synthetic Bone Graft Formulations:Ceramic-collagen composite substitutes are displacing autograft harvest in outpatient settings, eliminating iliac crest donor site morbidity and expanding addressable patient populations with osteoporosis or metabolic bone disease.
- Japan's Aging Surgical Population:METI's healthcare infrastructure investments targeting degenerative sacroiliitis in elderly patients present expansion pathways for manufacturers with PMDA-approval-ready minimally invasive systems.
Industry Challenges
- Fluoroscopic Navigation Expertise Gap:Surgeon training programs for C-arm spatial orientation and multiplanar trajectory planning remain underdeveloped, constraining safe case volume expansion and elevating malpractice exposure for early-adopter facilities.
- ISO 13485 Audit Compression:Notified body capacity constraints under the EU MDR transition are extending quality management system recertification timelines and freezing new product introductions for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sacroiliac Joint Fusion Market |
| Market Size in 2026 | $915.4 Million |
| Market Size in 2035 | $3,674.93 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Hardware, Bone Grafts, Fusion Devices End User: Orthopedic Clinics, Hospitals, Rehabilitation Centers, Pain Management Centers Technology: Minimally Invasive Surgery, Traditional Surgery, Robotic-Assisted Surgery, Imaging Techniques Application: Chronic Pain Management, Post-Trauma Reconstruction, Degenerative Conditions, Rheumatoid Arthritis |
| Companies Covered | SI-BONE Inc., Medtronic plc, Globus Medical Inc., Orthofix Medical Inc., Zimmer Biomet Holdings Inc., Life Spine Inc., PainTEQ LLC, SIGNUS Medizintechnik GmbH, NuVasive Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sacroiliac Joint Fusion Market Strategic Shifts & Innovations
Three intersecting developments are restructuring competitive advantage in sacroiliac fusion: implant surface engineering breakthroughs, regulatory pathway fragmentation between major markets, and the operational redesign of care delivery around outpatient economic models.
3D-printed titanium lattice implants with architected porosity are overtaking solid screw designs in high-volume centers. These patient-specific constructs match elastic modulus to native bone, reducing stress-shielding complications. Academic medical centers in Germany and the United States are adopting these systems for complex deformity cases. The technology is overtaking conventional machined implants in premium procedural segments where fusion assurance justifies extended operative time.
The FDA's 510(k) substantial equivalence pathway maintains streamlined clearance for predicate-based implant iterations, while the EU MDR demands prospective clinical data for medium-risk devices. This divergence is forcing manufacturers to maintain parallel regulatory strategies with divergent evidence packages. European orthopedic networks are delaying product evaluations until manufacturers complete MDR technical documentation, creating temporary supply concentration in United States markets.
Hospital procurement committees are consolidating vendor relationships through single-source contracts for implant-instrument-biologic bundles. Independent ASCs are responding by forming purchasing cooperatives to match hospital pricing tiers. This channel fragmentation is most visible in Texas and Florida, where freestanding surgery centers now account for over one-third of elective sacroiliac fusion volume and are negotiating direct manufacturer agreements bypassing traditional distributor markups.
Sacroiliac Joint Fusion Market Segmentation
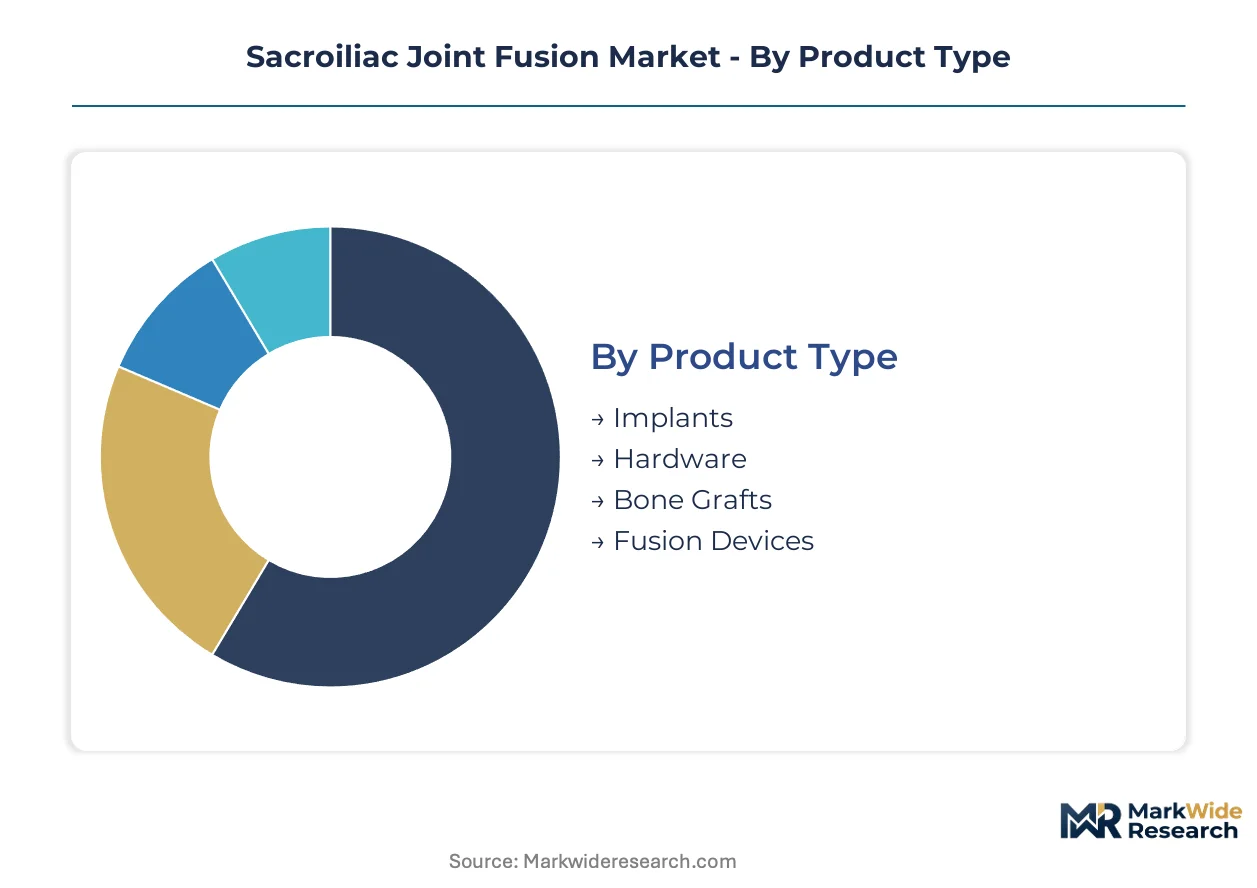
Segmentation in sacroiliac joint fusion reveals distinct margin structures across product tiers and divergent adoption velocities between inpatient and outpatient channels. Manufacturers configure portfolio breadth around these boundaries to optimize capital allocation and reimbursement positioning.
Product Type:
Standalone implant systems generate premium pricing through proprietary surface engineering, while bundled hardware-graft configurations dominate high-volume hospital contracts seeking procurement consolidation.
- Implants:Titanium and PEEK constructs with plasma-sprayed surfaces anchor the revenue pool, with demand concentrating in academic medical centers pursuing osteointegration reliability for complex deformity cases. The FDA's 510(k) pathway shapes development timelines for predicate-based iterations.
- Bone Grafts:Synthetic ceramic-collagen composites and demineralized bone matrix formulations are displacing autograft harvest in ambulatory settings, driven by elimination of donor-site morbidity and compressed procedural economics. Supply volatility in allograft processing constrains intermittent availability.
- Hardware:Instrumentation kits designed for fluoroscopic navigation include specialized drills, guides, and fixation screws calibrated to implant geometry.
- Fusion Devices:Integrated implant-delivery systems streamline operative workflow for outpatient conversion.
Implants lead volumes today; bone grafts are gaining share fastest as synthetic formulations mature.
End User:
Cost tier stratification separates capital-intensive hospital programs from lean ambulatory operators, with reimbursement differentials determining site-of-service migration speed.
- Hospitals:Inpatient facilities with dedicated spine centers capture complex revision cases and trauma reconstruction, leveraging integrated imaging suites and robotic navigation capital. Medicare's Hospital Outpatient Prospective Payment System constrains margin expansion for routine procedures.
- Orthopedic Clinics:Specialized ambulatory networks in Texas and Florida are aggregating elective volume through direct manufacturer purchasing agreements, bypassing traditional distributor markups. Compressed recovery protocols support same-day discharge economics.
- Pain Management Centers:Interventional practices with fluoroscopy capabilities are adding fusion procedures to chronic pain service lines.
- Rehabilitation Centers:Post-acute facilities coordinate recovery protocols and fusion monitoring through the twelve-to-twenty-four-month biological window.
Hospitals retain the largest procedure share; orthopedic clinics are expanding most quickly as ASC networks proliferate.
Technology:
Application context determines technology selection, with trauma and deformity cases demanding precision navigation while straightforward degenerative conditions tolerate conventional approaches.
- Minimally Invasive Surgery:Percutaneous implant placement through small incisions dominates procedural volume due to reduced blood loss and accelerated recovery trajectories. Fluoroscopic guidance requirements create training bottlenecks constraining safe expansion.
- Robotic-Assisted Surgery:Optical tracking integration with preoperative planning software enables sub-millimeter screw placement accuracy, opening premium pricing tiers in academic centers as capital equipment costs decline.
- Traditional Surgery:Open approaches persist for complex deformity correction requiring direct visualization.
- Imaging Techniques:Intraoperative C-arm fluoroscopy and navigation systems support trajectory planning across all surgical modalities.
Minimally invasive surgery leads volumes today; robotic-assisted surgery is climbing the fastest as precision demands intensify.
Application:
Patient population characteristics and reimbursement coding maturity create divergent commercial attractiveness across clinical indications.
- Chronic Pain Management:Degenerative sacroiliitis in aging populations drives the largest addressable patient pool, with Category I CPT code establishment securing commercial payer coverage for minimally invasive fusion. Diagnostic specificity requirements filter appropriate candidates.
- Degenerative Conditions:Spondyloarthropathy and age-related joint instability concentrate demand in Medicare-eligible demographics across Germany and the United States. 3D-printed titanium lattice implants with architected porosity are overtaking solid designs for complex cases.
- Post-Trauma Reconstruction:Pelvic fracture sequelae requiring stabilization represent acute intervention opportunities.
- Rheumatoid Arthritis:Inflammatory joint destruction in seropositive patients creates specialized surgical planning requirements.
Chronic pain management leads volumes today; degenerative conditions are expanding most quickly as aging demographics proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minimally invasive sacroiliac fusion techniques originated in United States academic medical centers during the early 2000s, with procedural standardization and commercial implant development following shortly thereafter. The technology diffused through German and Japanese spine surgery networks before establishing presence in broader European and Asia-Pacific markets.
United States
Specialized orthopedic networks in Texas and Florida drive procedural volume through ambulatory surgery center expansion. The FDA's 510(k) clearance pathway accelerates predicate-based implant iterations for domestic manufacturers. Greater Boston and the Pacific Northwest host concentrated training infrastructure for fluoroscopic navigation techniques.
Germany
Aging demographics with degenerative sacroiliitis create sustained demand for complex deformity reconstruction. The EU Medical Device Regulation imposes stricter clinical evidence requirements for CE marking than predecessor directives. Academic medical centers in Bavaria and Baden-Württemberg lead adoption of 3D-printed titanium lattice implants.
Japan
METI healthcare infrastructure investments target surgical intervention for elderly patients with degenerative joint conditions. The PMDA approval process shapes market entry timelines for minimally invasive systems. The Kanto region around Tokyo concentrates spine surgery volume and robotic navigation capital deployment.
United Kingdom
NHS procurement frameworks influence implant pricing and vendor selection for hospital spine programs. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR implementation timelines. London and the Southeast cluster private orthopedic networks pursuing same-day discharge protocols.
Australia
TGA regulatory requirements govern market access for implantable devices with biologic components. Private health insurance reimbursement structures determine procedural economics for elective fusion surgery. New South Wales and Victoria host the majority of specialized spine surgery capacity.
Sacroiliac Joint Fusion Market Key Industry Players
Premium-margin players sit above commodity-margin players across surface engineering sophistication and surgeon training infrastructure. The market structures around three tiers: dedicated sacroiliac specialists with integrated training ecosystems, diversified spine portfolio vendors leveraging cross-selling channels, and regional manufacturers competing on price-accessible implant configurations. Consolidation pressure intensifies as hospital procurement committees demand single-source bundles and ambulatory surgery centers negotiate direct purchasing agreements.
Within the dedicated specialist tier, SI-BONE Inc. exemplifies focused market development through proprietary implant systems and dedicated surgeon education infrastructure. Medtronic plc occupies a position as diversified spine portfolio anchor, while Globus Medical Inc. represents navigation-integrated platform competition. SIGNUS Medizintechnik GmbH anchors German-engineered precision manufacturing archetypes for European market access.
| Leading Market Players |
|---|
| SI-BONE Inc. |
| Medtronic plc |
| Globus Medical Inc. |
| Orthofix Medical Inc. |
| Zimmer Biomet Holdings Inc. |
| Life Spine Inc. |
| PainTEQ LLC |
| SIGNUS Medizintechnik GmbH |
| NuVasive Inc. |
| Others |
Cost & Logistics Intelligence
3D-printed titanium lattice implants with architected porosity are compressing manufacturing cost curves while concentrating production capability among German and United States precision metalworking clusters. This dual shift simultaneously elevates premium-tier pricing power for surface-engineered constructs and squeezes mid-tier margins as standardized PEEK screws commoditize.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies around surface engineering sophistication and surgeon training bundling. Premium tiers command substantial markups for plasma-sprayed titanium-PEEK constructs with ISO 13485 certification and dedicated fluoroscopic navigation support. Cost compression in standard-tier machined screws is intensifying because ambulatory surgery centers are consolidating purchasing cooperatives to bypass distributor markups. Orthopedic clinics in Texas and Florida exhibit highest price sensitivity; academic medical centers with robotic navigation capital show least.
Supply Chain Analysis
Freight cost volatility for temperature-controlled biologic shipments is reshaping bone graft substitute sourcing patterns across United States, German, and Japanese distribution networks. Raw material dependencies center on medical-grade titanium sponge from Japanese smelters, PEEK resin from Belgian polymer specialists, and demineralized bone matrix from United States tissue processing facilities. Single-source vulnerability in allograft processing creates intermittent supply constraints when donor tissue availability fluctuates. Distribution runs through specialized orthopedic distributor networks serving hospital procurement committees and direct manufacturer agreements with ambulatory surgery center cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory milestones, with the FDA's Category I CPT code establishment for minimally invasive sacroiliac fusion securing commercial payer reimbursement and accelerating hospital capital allocation toward dedicated spine programs.
For Market Incumbents: Extend surgeon training infrastructure to defend against robotic navigation convergence threatening fluoroscopic-guided implant placement. Deepen backward integration into titanium powder metallurgy to secure supply of architected porosity feedstock for 3D-printed lattice constructs. Fortify GPO contracts with hospital systems before ambulatory surgery center purchasing cooperatives achieve scale. For New Entrants and Emerging Players: Ambulatory surgery center networks in Florida and Texas represent the most penetrable channel for price-disruptive implant configurations. Target synthetic bone graft formulations displacing autograft harvest in outpatient settings, where elimination of donor-site morbidity creates immediate value capture. Pursue direct purchasing agreements bypassing traditional distributor markups as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers with FDA 510(k) clearance but incomplete EU MDR technical documentation. Long-term viability hinges on navigating divergent regulatory evidence requirements across United States and European markets. Watch for Category III CPT code transitions determining commercial payer coverage as the signal for inflection in hospital capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates predicate-based implant iterations for domestic manufacturers seeking rapid market entry. |
| EU MDR Technical Documentation | Extends approval timelines and elevates regulatory expenditure for CE marking across European markets. |
| Hospital System Partnership | Secures single-source contracts for implant-instrument-biologic bundles through procurement consolidation. |
| Software Companion Development | Enables optical tracking integration with preoperative planning for sub-millimeter screw placement accuracy. |
| Reimbursement Strategy | Positions products for Medicare's Hospital Outpatient Prospective Payment System site-of-service differentials. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up implant shipment modeling and top-down procedural volume estimates were triangulated to anchor market sizing.
Comparable historical periods anchored the forecast window to established growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, end-user channel, surgical technology, and clinical application, with regional regulatory cluster effects incorporated. CAGRs were derived from slope analysis of adoption curves, incorporating fluoroscopic navigation training pipeline constraints, ambulatory surgery center expansion rates, and synthetic bone graft formulation maturation as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR implementation delays, allograft supply disruptions, and robotic navigation capital cost trajectories. Forecasts reflect documented assumptions about reimbursement coding evolution and surgeon training capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
ADA Substitute Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Netherlands Respiratory Devices Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
Peripheral Interventions Market
Medical Devices
Netherlands Aesthetic Devices Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
Water Bath Vaporizer Market
Medical Devices
Single-Use Centrifuge System Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
South America C-Arms Market
Medical Devices
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
Microcurrent Facial Market