
 Implantable Pump Catheter Market | 2026-2036
Implantable Pump Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Implantable Pump Catheter Market Analytics
A shortage of interventional pain specialists trained in intrathecal drug delivery is redrawing competitive dynamics across the implantable pump catheter landscape. Medtronic plc leverages its decades-long installed base of SynchroMed systems to sustain recurring catheter replacement revenue. Flowonix Medical differentiates through programmable valve technology that anchors its position in targeted drug delivery niches. Abbott Laboratories competes via its neuromodulation division, which controls broad hospital contracting relationships that extend catheter pull-through.
An implantable pump catheter is a biocompatible silicone or polyurethane tube surgically placed in the intrathecal space or targeted anatomical region, connected to a subcutaneously implanted reservoir or pump for programmed drug infusion. The device typically features multi-lumen construction, radiopaque stripe markers, and anti-kink reinforcement to maintain flow integrity under cyclic bending. Infusion catheters dominate product-type revenue due to replacement-driven aftermarket economics, while automated systems with remote monitoring capability represent the fastest-growing technology segment as providers seek to reduce refill-related complications. Hospitals remain the primary end-user channel, though home care settings are gaining traction where reimbursement permits nursing-supported ambulatory infusion.
FDA 510(k) clearance pathways and EMA MDR conformity requirements shape product development timelines and clinical evidence burdens for manufacturers seeking multi-regional market access. ISO 80369 small-bore connector standards and USP Class VI biocompatibility testing protocols further constrain material selection and supplier qualification processes. Stakeholders must monitor evolving CMS national coverage determinations for intrathecal therapy, as reimbursement thresholds directly influence physician adoption rates and hospital capital commitment to implant programs.
Market Dynamics
Reimbursement pathway consolidation for intrathecal therapy is restructuring hospital procurement priorities and compressing vendor selection cycles across the implantable pump catheter landscape.
Growth Catalysts
- CMS National Coverage Determinations:Expanded reimbursement for targeted drug delivery in chronic pain is accelerating catheter placement volumes in US hospital systems.
- Biocompatible Polyurethane Formulations:Advanced material chemistry is extending device longevity and reducing replacement frequency in long-term implantation protocols.
- Japan's Super-Aged Society:Demographic concentration of patients over 75 years is driving demand for implantable pain management infrastructure in tertiary medical centers.
Market Restraints
- Silicone Raw Material Concentration:Medical-grade silicone supply clusters in Northeast Asia, creating single-source vulnerability for catheter manufacturers.
- EMA MDR Clinical Evidence Burden:Expanded post-market surveillance requirements are extending product recertification timelines and elevating compliance costs.
- External Drug Delivery Systems:Non-implantable infusion pumps and transdermal patches offer lower-risk alternatives for moderate chronic pain cases.
Strategic Opportunities
- Home Care Nursing Networks:Reimbursement-permitted ambulatory refill services are opening catheter utilization outside traditional hospital settings.
- ISO 80369-7 Small-Bore Connectors:Mandated connector standardization is creating first-mover advantage for manufacturers with compliant integrated systems.
- Germany's Ambulatory Surgery Centers:Underpenetrated outpatient implantation capacity offers expansion corridor for streamlined catheter placement protocols.
Industry Challenges
- Interventional Pain Specialist Training Pipeline:Fellowship program capacity constraints are limiting qualified implanter availability for device placement.
- FDA 510(k) Predicate Device Pathways:Evolving substantial equivalence standards are complicating clearance strategies for next-generation catheter designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implantable Pump Catheter Market |
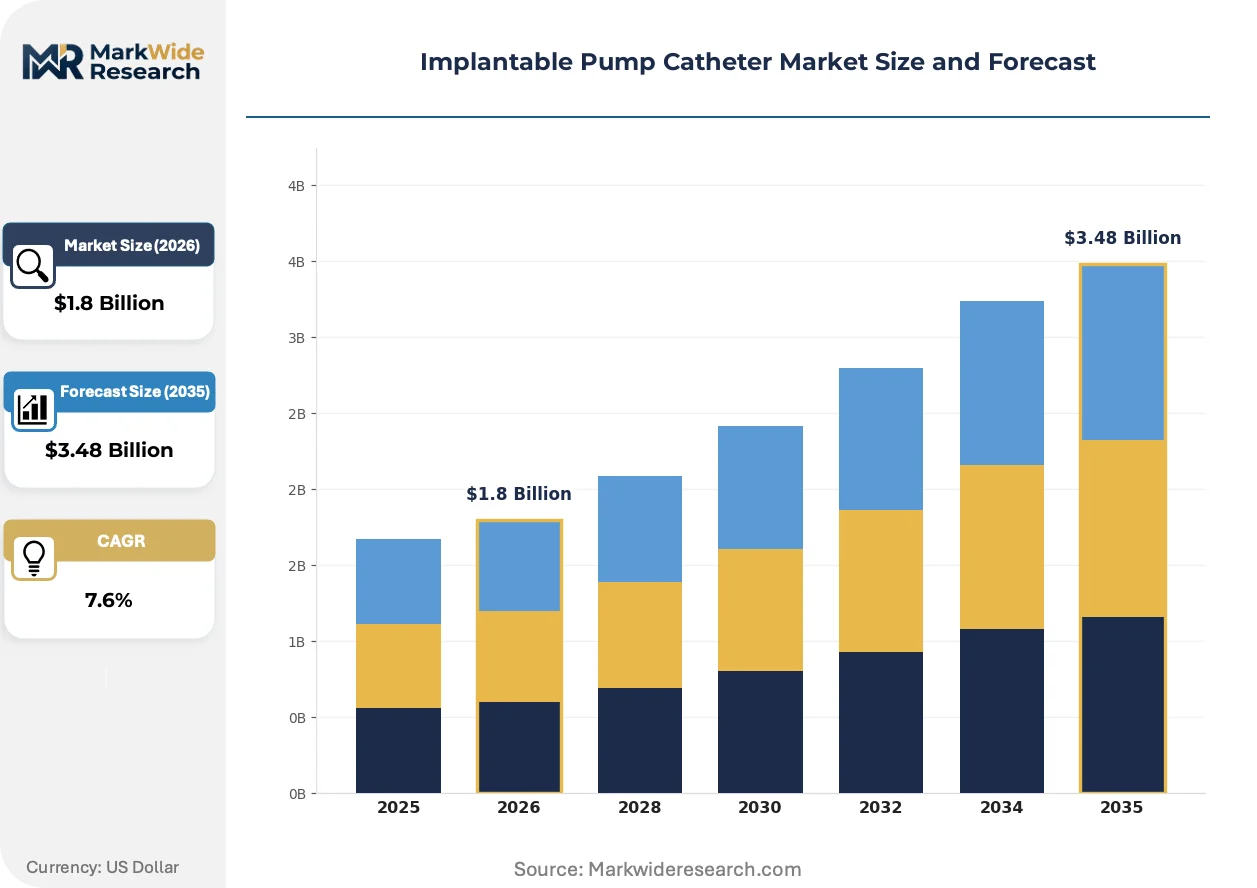
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Catheters, Administration Pumps, Reservoirs, Cannulas Application: Chronic Pain Management, Hormonal Therapy, Chemotherapy, Neurological Disorders Technology: Automated Systems, Manual Systems, Remote Monitoring, Biocompatible Materials End User: Hospitals, Home Care Settings, Specialty Clinics, Rehabilitation Centers |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, Flowonix Medical, Cognos Therapeutics, Intera Oncology, Smith's Medical, Epic Medical, Tricumed Medizintechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implantable Pump Catheter Market Evolving Landscape
Remote monitoring integration is redefining the service model for implantable drug delivery, shifting value capture from hardware sales toward subscription-based clinical support ecosystems.
Closed-loop sensing catheters with biomarker-responsive flow adjustment are displacing fixed-rate programmable systems in academic medical centers. Pain management departments at Cleveland Clinic and Mayo Clinic are piloting these devices for opioid-sparing protocols. The technology is displacing conventional refill-schedule dependency with real-time therapeutic optimization, compressing emergency intervention rates.
EMA MDR Article 10 clinical evaluation requirements are forcing manufacturers to generate new post-market clinical follow-up data for legacy catheter portfolios. European notified bodies are rejecting grandfathered technical documentation, compelling device firms to sponsor prospective registries. Infusion catheter lines with pre-2021 CE marks face the steepest compliance cliff.
Hospital value analysis committees are consolidating vendor contracts for implantable pump systems and consumables into single-source agreements. Integrated delivery networks in Texas and Florida are eliminating multi-vendor catheter purchasing, awarding sole-source contracts to neuromodulation suppliers with comprehensive service infrastructure. This concentration is most visible in US for-profit hospital chains with centralized procurement authority.
Implantable Pump Catheter Market Segmentation
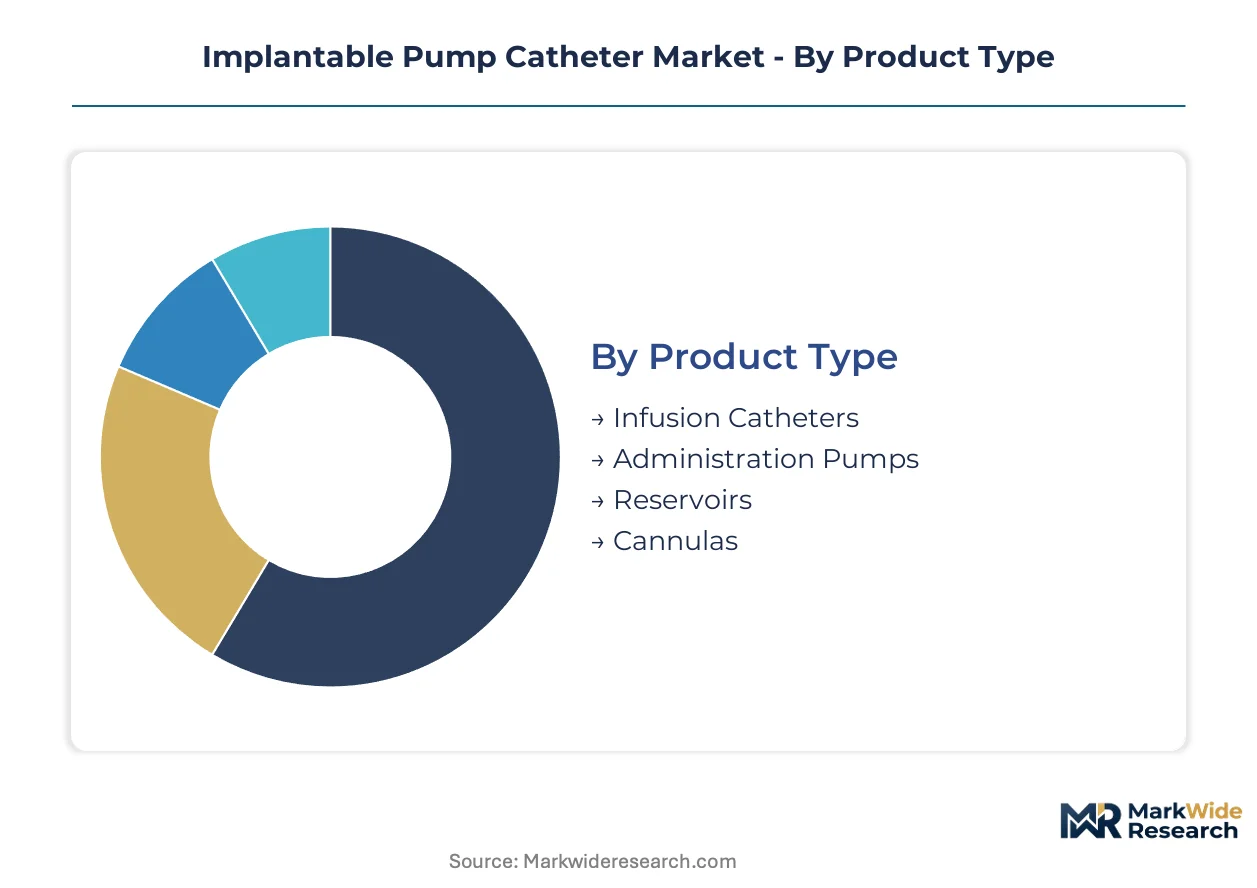
Segmentation in implantable pump catheters reveals distinct substitution pressures across product architectures and care settings. Each dimension exposes vulnerability to external drug delivery alternatives or internal technology displacement.
Product Type:
Infusion catheters face the most acute substitution threat from percutaneous port systems and external infusion pumps in moderate pain cases.
- Infusion Catheters:Multi-lumen silicone or polyurethane constructs with radiopaque markers and anti-kink reinforcement maintain flow integrity under cyclic bending. Demand concentrates in US hospital systems expanding chronic pain management programs, driven by replacement economics and catheter longevity improvements.
- Administration Pumps:Programmable subcutaneous reservoirs with precision flow control mechanisms enable titrated drug delivery. Germany and Japan show strongest demand concentration where aging populations and established reimbursement pathways support device adoption.
- Reservoirs:Biocompatible polymer chambers designed for periodic percutaneous refilling.
- Cannulas:Single-lumen access devices for targeted anatomical placement.
Infusion catheters retain volume leadership; administration pumps hold the steepest expansion curve.
Application:
Cost tier stratification separates high-complexity neurological applications from commoditized pain management protocols.
- Chronic Pain Management:Intrathecal opioid and local anesthetic delivery for failed back surgery syndrome and complex regional pain syndrome. US Medicare coverage determinations and Japan's super-aged society demographics drive placement volume concentration.
- Neurological Disorders:Baclofen delivery for severe spasticity in multiple sclerosis and spinal cord injury. Academic medical centers at Cleveland Clinic and Mayo Clinic pilot closed-loop sensing variants for real-time therapeutic optimization.
- Hormonal Therapy:Gonadotropin-releasing hormone agonist delivery for prostate and breast cancer.
- Chemotherapy:Regional cytotoxic agent infusion for hepatic metastases and peritoneal carcinomatosis.
Chronic pain management retains volume leadership; neurological disorders hold the steepest expansion curve.
Technology:
Customer type segmentation separates institutional purchasers seeking integrated systems from ambulatory providers prioritizing portability.
- Automated Systems:Electronically programmable pumps with dose error reduction software and bolus patient-controlled analgesia capability. Remote monitoring integration is gaining traction where reimbursement permits nursing-supported ambulatory infusion.
- Remote Monitoring:Cloud-connected devices transmitting reservoir levels, alarm events, and patient-reported outcomes to clinical dashboards. US integrated delivery networks in Texas and Florida consolidate vendor contracts around comprehensive service infrastructure.
- Manual Systems:Mechanical constant-flow pumps without electronic components.
- Biocompatible Materials:Advanced polyurethane formulations and surface-modified silicones extending device longevity.
Automated systems retain volume leadership; remote monitoring holds the steepest expansion curve.
End User:
Supply concentration in catheter manufacturing clusters shapes procurement leverage across care settings.
- Hospitals:Tertiary medical centers with interventional pain specialists and neurosurgical implantation capacity. Value analysis committees consolidate pump system and consumable contracts into single-source agreements, eliminating multi-vendor purchasing.
- Home Care Settings:Nursing-supported ambulatory refill services expanding catheter utilization outside traditional hospital infrastructure. Reimbursement-permitted models in Germany's underpenetrated outpatient sector offer expansion corridor.
- Specialty Clinics:Pain management and neuromodulation focused facilities.
- Rehabilitation Centers:Post-acute spasticity management and dose titration facilities.
Hospitals retain volume leadership; home care settings hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA reimbursement pathways for intrathecal drug delivery anchor demand concentration in the United States, while EMA MDR compliance timelines and Japan's super-aged demographics reshape procurement priorities across developed markets. Hospital system consolidation and interventional pain specialist shortages are redrawing competitive access corridors in each geography.
United States
Medicare national coverage determinations for targeted drug delivery are accelerating catheter placement volumes in tertiary medical centers. CMS reimbursement thresholds directly influence physician adoption rates and hospital capital commitment to implant programs. Texas and Florida integrated delivery networks are consolidating vendor contracts into single-source agreements, eliminating multi-vendor purchasing.
Germany
Ambulatory surgery centers represent underpenetrated outpatient implantation capacity for streamlined catheter placement protocols. EMA MDR Article 10 clinical evaluation requirements are forcing manufacturers to generate new post-market clinical follow-up data for legacy portfolios. Bavaria's tertiary medical centers concentrate interventional pain specialist capacity and neuromodulation infrastructure.
Japan
Demographic concentration of patients over 75 years is driving demand for implantable pain management infrastructure. PMDA biocompatibility standards are tightening material specifications for long-term implantation. Tokyo and Osaka metropolitan areas anchor tertiary medical center density and interventional pain specialist training programs.
United Kingdom
NHS value analysis committees are consolidating procurement for implantable pump systems and consumables into framework agreements. MHRA post-Brexit regulatory alignment with EMA MDR is extending product recertification timelines. London and Southeast England concentrate academic medical center pilot programs for closed-loop sensing catheter technology.
Switzerland
Swissmedic conformity assessment requirements for Class III implantable devices maintain stringent clinical evidence burdens. Premium reimbursement tiers for neuromodulation therapies support adoption of advanced programmable systems. Basel and Zurich medical technology clusters host catheter manufacturing and precision polymer formulation capabilities.
Implantable Pump Catheter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling hospital contracting relationships and comprehensive service infrastructure. The middle tier fragments across programmable valve technology and targeted drug delivery niches. Two strategic archetypes dominate: diversified neuromodulation conglomerates with broad installed bases, and focused catheter specialists with differentiated flow control mechanisms. Competitive moves concentrate on backward integration into biocompatible material supply and strategic partnerships for remote monitoring platform development.
Within the integrated leader tier, Medtronic plc and Abbott Laboratories occupy positions sustained by decades-long installed bases and recurring replacement revenue economics. Flowonix Medical exemplifies the specialist archetype, anchoring programmable valve differentiation in targeted drug delivery segments. Boston Scientific Corporation sits within the diversified medical technology tier, representing hospital contracting breadth that extends catheter pull-through across neuromodulation portfolios.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Flowonix Medical |
| Cognos Therapeutics |
| Intera Oncology |
| Smith's Medical |
| Epic Medical |
| Tricumed Medizintechnik |
| Others |
Value Network & Pricing Analysis
Long-term catheter replacement contracts with integrated delivery networks lock in both medical-grade silicone supply access and predictable per-unit pricing visibility for manufacturers serving US hospital systems. These arrangements insulate vendors from spot market volatility in raw materials while committing buyers to volume thresholds that sustain manufacturing scale.
Pricing Analysis
Catheter pricing spreads widest between US tertiary medical centers and Germany's ambulatory surgery centers, where reimbursement differentials and procurement consolidation create divergent cost structures. Three-tier pricing structure across premium programmable systems, standard fixed-rate pumps, and economy mechanical reservoirs dominates product architecture. Price differentiation hinges on FDA 510(k) clearance tier and remote monitoring integration level. Cost compression in standard-tier devices is intensifying because hospital value analysis committees are consolidating vendor contracts. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with bundled payment contracts show lowest.
Supply Chain Analysis
Japan and Germany anchor precision polymer formulation capabilities for medical-grade catheter manufacturing, while the United States concentrates programmable pump assembly and software integration. Medical-grade silicone, radiopaque marker compounds, and anti-kink reinforcement polymers constitute critical input dependencies. Single-source vulnerability in Northeast Asian silicone supply clusters threatens production continuity. Distribution runs through hospital value analysis committees and group purchasing organizations that gate access to integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in US integrated delivery networks that are eliminating multi-vendor purchasing, compressing supplier margins and favoring comprehensive service providers over component specialists.
For Market Incumbents: Secure backward integration into biocompatible polyurethane supply to reduce raw material cost exposure and defend against emerging catheter specialists with differentiated flow control mechanisms. Deepen hospital system partnerships in Texas and Florida where sole-source contracting is accelerating, prioritizing remote monitoring platform development to lock in recurring revenue streams. For New Entrants and Emerging Players: Differentiate on closed-loop sensing catheter technology for neurological disorder applications where academic medical centers pilot opioid-sparing protocols. Target Germany's underpenetrated ambulatory surgery center segment with streamlined implantation protocols. Pursue ISO 80369-7 connector compliance as a first-mover regulatory wedge. For Investors and Strategic Acquirers: Programmable valve technology specialists with established CE marking and PMDA approvals represent the most defensible acquisition archetype in a market shifting toward integrated systems. Long-term viability rests on regulatory clearance breadth and hospital contracting relationships rather than hardware margins alone. Watch CMS national coverage determination expansions for intrathecal therapy as the signal for accelerated catheter placement volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for next-generation catheter designs with biomarker-responsive capabilities. |
| CE Marking Pathway | Enables European commercialization under EMA MDR Article 10 clinical evaluation requirements. |
| Hospital System Partnership | Secures sole-source contracting position within Texas and Florida integrated delivery networks. |
| Software Companion Development | Supports remote monitoring integration shifting value capture toward subscription-based clinical support. |
| Reimbursement Strategy | Aligns catheter placement protocols with CMS national coverage determinations for intrathecal therapy. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with interventional pain specialists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EMA MDR submission databases, CMS Medicare coverage determinations, and hospital procurement contract records. Bottom-up catheter placement volume estimates triangulated with top-down market sizing from neuromodulation system manufacturers.
Across the analysis window, forecasts incorporated product type segmentation by infusion catheter versus administration pump architecture, technology tier by automation level, application stratification between chronic pain and neurological disorders, and end-user channel dynamics between hospitals and home care settings. CAGRs derived from replacement-driven aftermarket economics and demographic-driven placement expansion in super-aged societies. Industry-specific inputs included interventional pain specialist training pipeline capacity and biocompatibility standard evolution timelines.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement support, EMA MDR compliance cost trajectories, or medical-grade silicone supply stability would require recalibration. Forecasts reflect assumptions about hospital consolidation velocity and ambulatory care expansion permissiveness. Recalibration cycles align with material shifts in national coverage determinations and notified body conformity assessment practices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Heart Valve Devices Market
Medical Devices
Smart Lenses Market
Medical Devices
Global Skin Grafting Device Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Refurbished Medical Devices Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Global Urinary Incontinence Treatment Devices Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Cystic Fibrosis Devices Market
Medical Devices
Bronchial Thermoplasty Catheter Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
Temporary Pacing Leads Market
Medical Devices
Robotic Hair Transplant System Market